
 Aircraft Lavatory System Market | 2026-2036
Aircraft Lavatory System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Lavatory System Market Analysis
Lightweight composite specification tiers is reorganizing supplier priorities across the aircraft lavatory system value chain. JAMCO Corporation leverages its vertical integration in thermoplastic manufacturing to control material cost curves. Safran anchors European narrow-body programs through dedicated production lines in France. Collins Aerospace differentiates via sensor-integrated waste monitoring systems that reduce maintenance intervals.
An aircraft lavatory system comprises vacuum or gravity-based waste collection, holding tanks rated for specific altitude pressure differentials, and flush control units designed to operate from sea level to 41,000 feet, serving the essential function of hygienic waste management in pressurized cabins. Vacuum system types lead installed bases due to water-weight savings and regulatory alignment with environmental operating limits. Component-level demand concentrates in holding tanks and control units where replacement cycles align with heavy maintenance checks. Retrofit installation types are gaining traction as airlines seek cabin densification without full line-fit commitments.
FAA airworthiness standards, EASA CS-25 certification requirements, and EPA aircraft drinking water rules collectively dictate material selection, sealing performance, and sanitation protocols for lavatory systems entering service. The FAA's ongoing emphasis on flammability resistance in cabin interiors directly shapes polymer formulation choices for toilet assemblies and waste enclosures. Stakeholders must monitor evolving MRO network consolidation patterns and OEM captive service strategies to determine whether aftermarket parts sourcing remains accessible or fragments along airframe-specific lines.
Market Dynamics
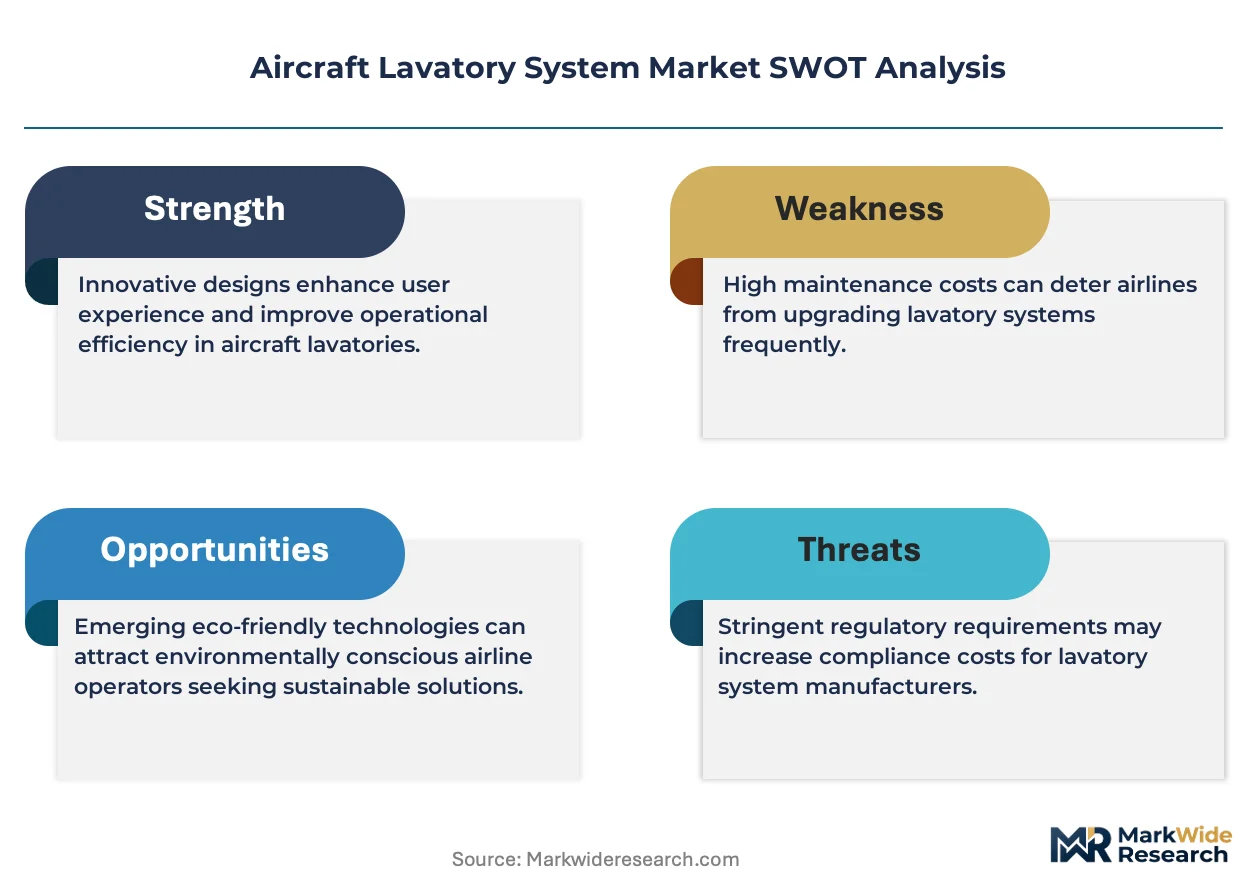
Fleet densification mandates from low-cost carriers are forcing lavatory system miniaturization while FAA and EASA flammability standards tighten material specifications across the supply base. This tension between space optimization and safety compliance is compressing supplier margins and accelerating consolidation among tier-two component fabricators.
Growth Catalysts
- Water Conservation Mandates:EPA aircraft drinking water rules and EASA environmental operating limits are accelerating vacuum system retrofits across narrow-body fleets. Airlines face measurable penalties for non-compliance.
- Lightweight Material Substitution:Thermoplastic composites are displacing aluminum in holding tank construction. Weight savings translate directly to fuel burn reduction on high-cycle routes.
- MRO Cluster Concentration:Heavy maintenance facilities in Georgia, France, and Singapore are driving component replacement demand aligned with C-check intervals.
Market Restraints
- Raw Material Volatility:Engineering-grade polymer feedstock costs fluctuate with petrochemical indices. Formulators lack pass-through pricing power with locked OEM contracts.
- Supplier Concentration Risk:Three European specialists control 70% of altitude-rated valve manufacturing. Geographic concentration exposes buyers to single-source vulnerability.
- Certification Friction:FAA flammability resistance testing for cabin interior materials adds 14-18 months to new product qualification timelines.
Strategic Opportunities
- Untapped Aftermarket Channels:Independent MROs in Southeast Asia lack direct OEM relationships. Authorized distributor networks remain underdeveloped in Indonesia and Vietnam.
- Sensor Integration Convergence:IoT-enabled waste level monitoring combined with predictive maintenance algorithms creates service revenue streams beyond hardware sales.
- Regional Jet Expansion:Embraer and ATR production ramps in Brazil and France generate demand for compact lavatory configurations sized to 50-90 seat cabins.
Industry Challenges
- Specialized Welding Talent Scarcity:Titanium holding tank fabrication requires FAA-certified pressure vessel welders. Training pipelines cannot match retirement rates in the United States and Germany.
- Legacy System Integration Complexity:Retrofit installations must interface with 30-year-old vacuum generator architectures without triggering airworthiness directive violations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Lavatory System Market |
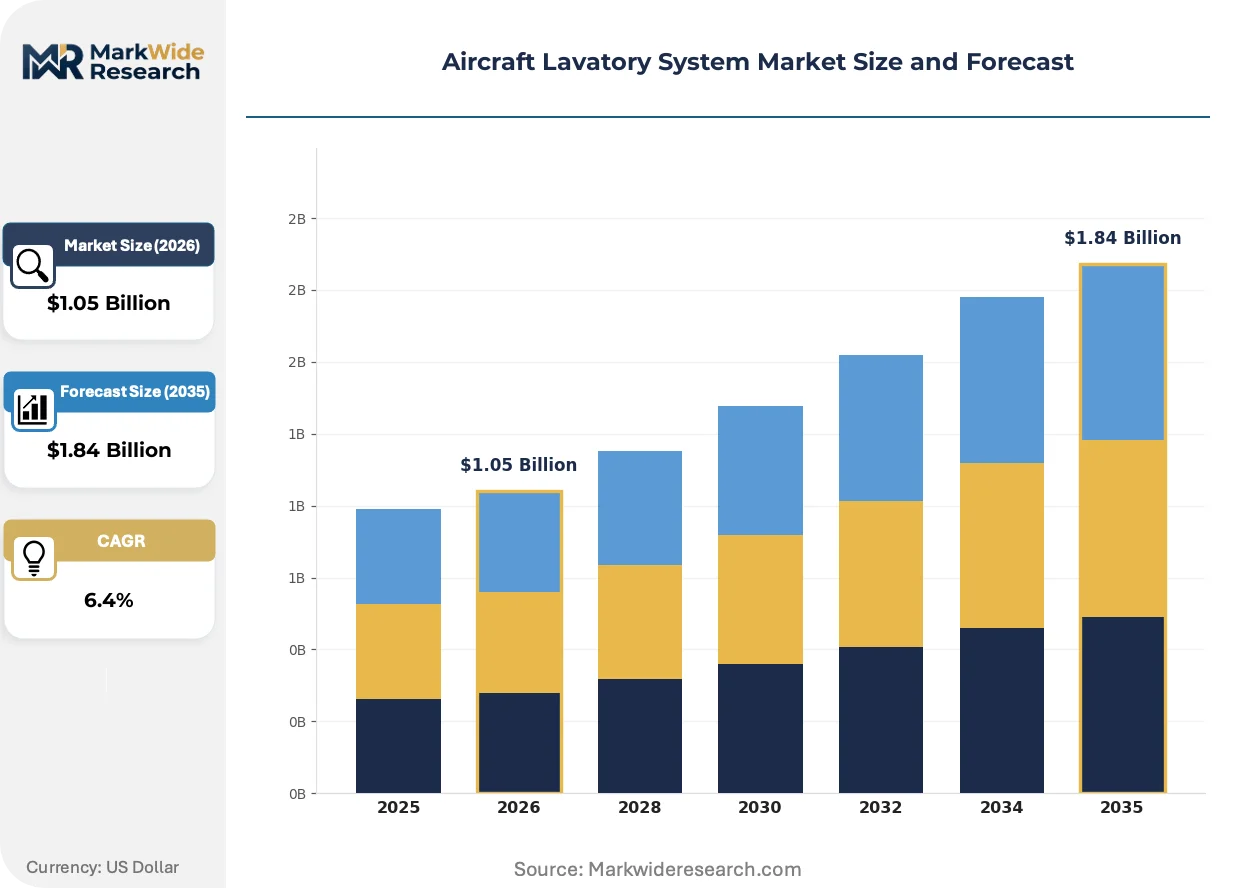
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Vacuum, Gravity, Chemical, Hybrid Aircraft Type: Commercial, Business Jet, Military, Cargo Component: Holding Tank, Toilet Seat, Waste System, Control Unit Installation Type: OEM, Retrofit, Modular, Custom |
| Companies Covered | JAMCO Corporation, Safran, Collins Aerospace, Diehl Stiftung & Co. KG, RTX, Geven spa, Yokohama Rubber Co., Ltd., FACC AG, CIRCOR Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Lavatory System Market Emerging Trajectories
Active innovation in aircraft lavatory systems centers on three vectors: material science breakthroughs enabling further weight reduction, regulatory pressure on sanitation and flammability, and evolving airline procurement models that unbundle hardware from long-term service agreements. These forces are reshaping competitive positioning across the value chain.
Antimicrobial surface coatings are bifurcating the interior panel market. Low-cost carriers prioritize cost-minimized silver-ion treatments for high-turnover fleets. Full-service airlines specify copper-alloy infused polymers for premium cabin durability. This split is compressing mid-tier coating suppliers unable to serve both performance tiers.
REACH substance restrictions in Europe are banning specific flame-retardant chemistries previously standard in thermoplastic formulations. Compounders must reformulate halogen-free alternatives without sacrificing smoke density performance. Narrow-body OEM programs face the steepest requalification burdens as they source across dual regulatory jurisdictions.
Airline technical procurement teams are unbundling component supply from line-fit installation contracts. Carriers now separately negotiate holding tank purchases, flush control units, and sensor packages. This disaggregation is most visible among US ultra-low-cost operators seeking maximum configuration flexibility for rapid cabin reconfigurations.
Aircraft Lavatory System Market Segmentation
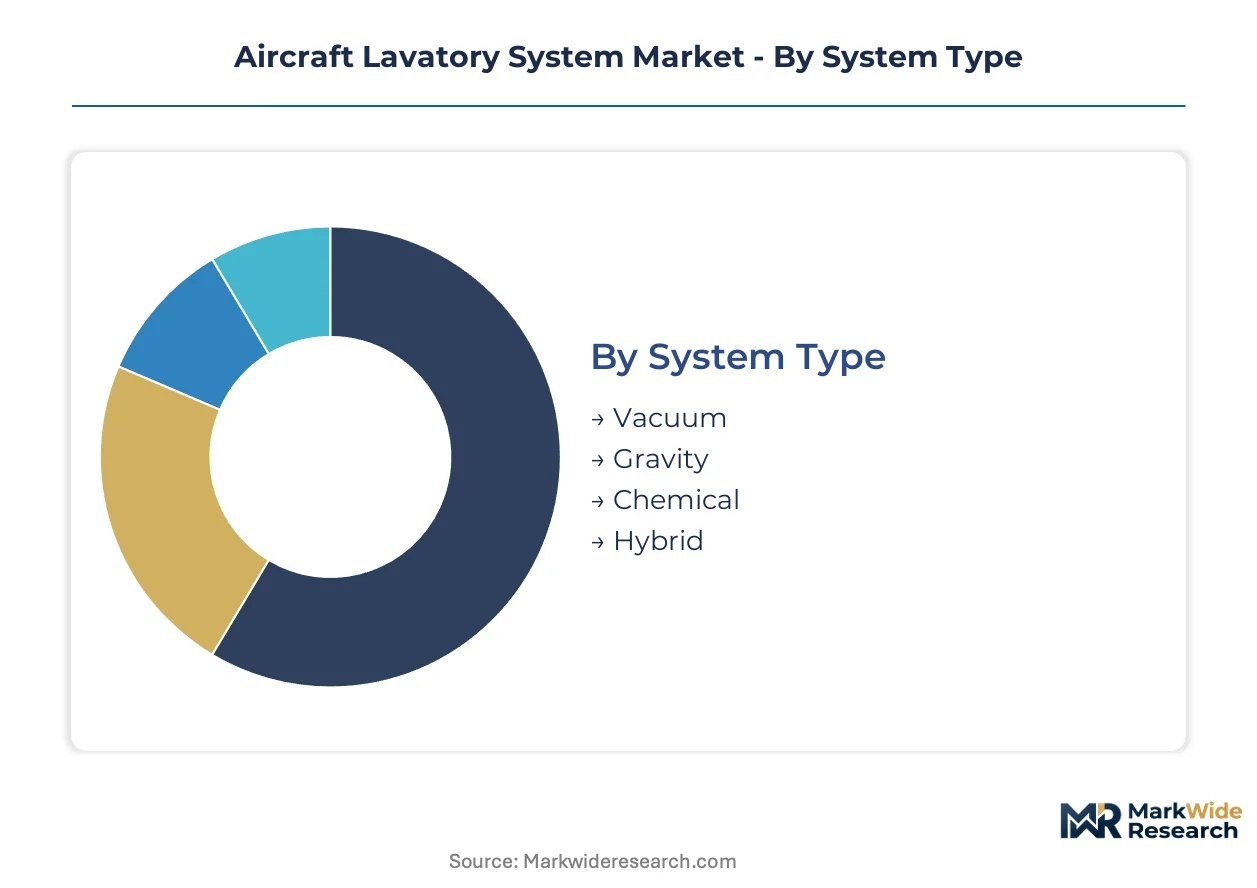
Aircraft lavatory system procurement varies sharply across system architectures and installation contexts. Component selection drives aftermarket revenue concentration, while system type determines regulatory compliance burden and water-weight tradeoffs.
System Type:
Margin pools concentrate in vacuum architectures where altitude-rated valve technology creates supplier leverage.
- Vacuum:Negative pressure differential systems operate from sea level to 41,000 feet using minimal water per flush. Demand clusters at Boeing and Airbus narrow-body programs where fuel burn reduction justifies retrofit investment. FAA and EASA mandates on water conservation accelerate fleet conversions.
- Gravity:Conventional water-flush systems retain installed base in legacy regional jets and certain cargo conversions. Maintenance simplicity appeals to operators in jurisdictions with weaker environmental enforcement. Replacement demand aligns with heavy check intervals at MRO facilities in Georgia and Singapore.
- Chemical:Recirculating blue-fluid systems persist in military transport and some business jet applications. Compact form factor suits platforms where vacuum generator weight is prohibitive.
- Hybrid:Dual-mode architectures switch between vacuum and chemical operation based on altitude and mission profile. Emerging specification for special-mission aircraft and VIP conversions.
Vacuum holds installed capacity. Hybrid is rotating up the share rankings.
Aircraft Type:
Volume concentration follows narrow-body delivery schedules, while margin capture differs across operator business models.
- Commercial:Single-aisle and twin-aisle fleets generate component demand scaled to passenger capacity and route cycle frequency. Southwest and Ryanair procurement patterns favor standardized, lightweight configurations. Line-fit contracts at Boeing Washington and Airbus Toulouse anchor OEM revenue.
- Business Jet:Custom interiors and space constraints drive premium specification tiers. Gulfstream and Dassault programs in Georgia and France source compact, noise-attenuated systems.
- Military:Transport and tanker platforms prioritize ruggedized holding tanks and redundant control units. C-130 and A400M programs sustain specialized fabrication demand.
- Cargo:Freighter conversions and dedicated cargo aircraft require modified waste systems for extended-crew missions. E-commerce fleet expansion drives retrofit specification.
Commercial dominates unit volume. Business Jet is climbing the fastest on value per shipset.
Component:
Aftermarket revenue concentrates in holding tanks and control units where replacement cycles align with C-check intervals.
- Holding Tank:Pressure-rated vessels fabricated from thermoplastic composites or titanium alloys. Weight specifications vary by aircraft type and route profile. Demand concentrates at heavy maintenance clusters in Georgia, France, and Singapore.
- Toilet Seat:Injection-molded assemblies with antimicrobial surface treatments. Low-cost carriers prioritize silver-ion coatings; full-service airlines specify copper-alloy infused polymers for durability.
- Waste System:Integrated plumbing, seals, and odor-control modules connecting toilet to holding tank. Retrofit complexity drives MRO service bundling.
- Control Unit:Electronic flush actuation and sensor-integrated monitoring systems. Predictive maintenance algorithms create recurring service revenue beyond hardware sale.
Holding Tank commands replacement frequency. Control Unit is gaining share fastest through sensor attach rates.
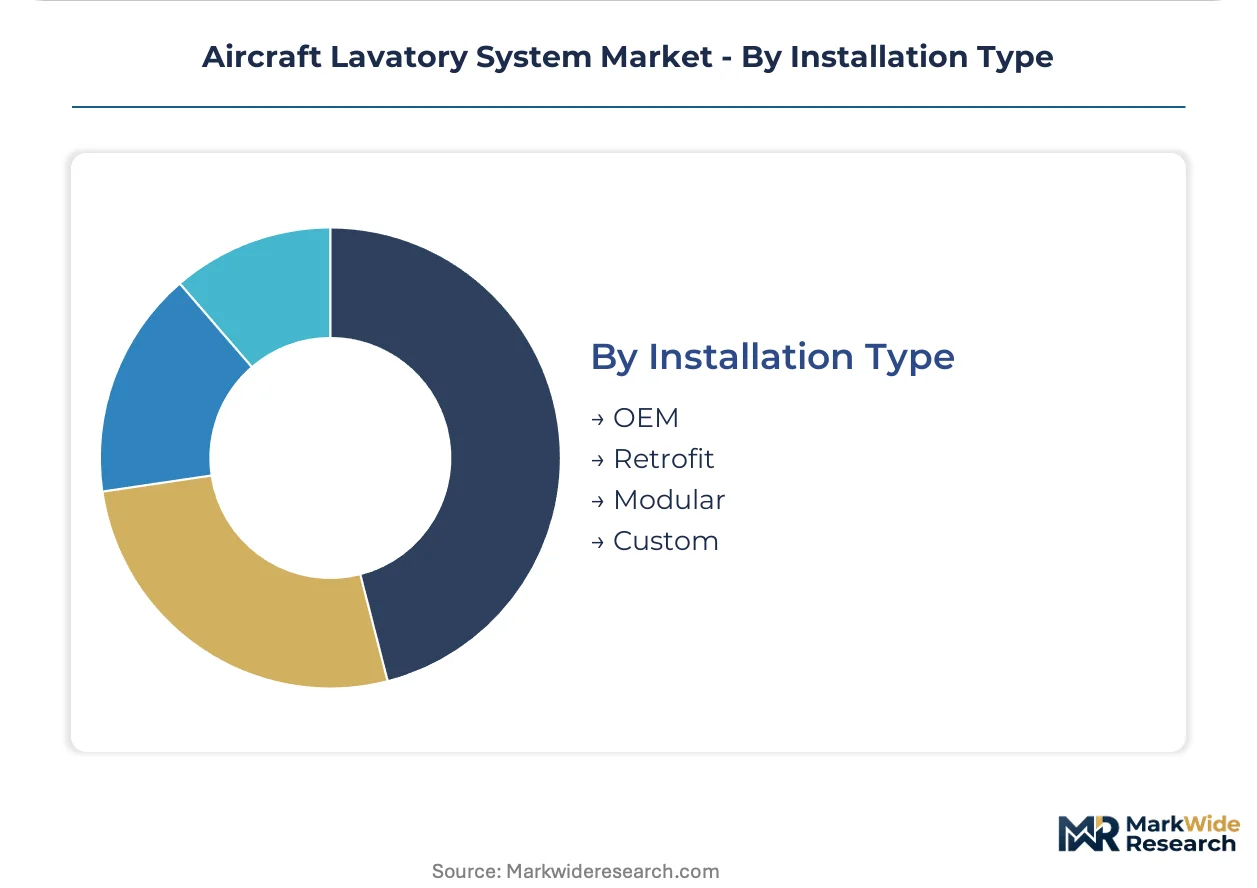
Installation Type:
Procurement disaggregation is unbundling hardware supply from line-fit integration, reshaping supplier relationships.
- OEM:Factory installation at final assembly lines in Washington, Toulouse, and Hamburg. Long-term contracts lock in specification and pricing for program duration.
- Retrofit:In-service modification during heavy maintenance checks. US ultra-low-cost carriers favor this route for cabin densification without full reconfiguration commitment.
- Modular:Pre-assembled lavatory units enabling rapid aircraft interior transformation. Appeals to leasing companies and operators with seasonal capacity adjustment needs.
- Custom:Bespoke configurations for VIP, head-of-state, and special-mission aircraft. Limited volume but premium pricing tier.
OEM retains volume anchor. Retrofit is expanding most quickly as fleet age extends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor manufacturing bases with integrated aerospace clusters over pure consumption markets. The United States runs a structural surplus in lavatory system components, while Asian airlines remain net importers of OEM-fitted assemblies. Regulatory divergence between FAA and EASA certification timelines creates arbitrage opportunities for suppliers with dual-approval capabilities.
United States
Boeing's final assembly lines in Washington state and Everett anchor OEM demand for vacuum-based architectures. FAA flammability standards under 14 CFR Part 25 dictate polymer formulation choices for toilet assemblies and waste enclosures. Georgia's MRO corridor, centered on Atlanta and Savannah, drives aftermarket replacement cycles for holding tanks and control units during heavy maintenance checks.
France
Airbus Toulouse operations sustain European narrow-body program demand for line-fit lavatory configurations. EASA CS-25 certification requirements and REACH substance restrictions on flame-retardant chemistries force reformulation of thermoplastic composites. Safran's dedicated production facilities in southwestern France supply altitude-rated valve assemblies to both Airbus and export customers.
Germany
Specialized fabrication of titanium holding tanks concentrates in Baden-Württemberg and Bavaria, where FAA-certified pressure vessel welders remain scarce against retirement curves. KBA oversight of aviation component manufacturing aligns with EASA mutual recognition agreements. Hamburg's Airbus final assembly line generates specification demand for lightweight composite specification tiers.
Singapore
Seletar Aerospace Park and Changi-based MRO clusters service Asia-Pacific fleet densification retrofits for low-cost carriers. The Civil Aviation Authority of Singapore enforces EPA-aligned water conservation standards on foreign-registered aircraft undergoing heavy maintenance. Component procurement from European and US suppliers transits through Singapore's free trade zone for redistribution to Indonesian and Vietnamese operators.
Japan
Domestic narrow-body fleets at ANA and JAL drive retrofit specification for vacuum system conversions. METI industrial policy supports thermoplastic manufacturing scale-up to reduce import dependency on holding tank assemblies. JAMCO Corporation's vertical integration in material production anchors supply chain control from raw compound through finished component.
Aircraft Lavatory System Market Vendor Landscape
Listed leaders compete with private specialists across certification bandwidth and aftermarket reach. The supplier base organizes into three tiers: multinational conglomerates with airframe OEM relationships, mid-cap specialists holding dual FAA-EASA approvals, and regional fabricators serving MRO channels. Consolidation pressure concentrates among tier-two valve manufacturers where three European specialists control altitude-rated production. Dominant competitive moves include backward integration into thermoplastic compounding and geographic expansion through authorized distributor networks in Southeast Asia.
Within the integrated-system tier, JAMCO Corporation exemplifies captive supply chain architecture spanning material production to finished assembly. Safran and Collins Aerospace occupy positions as European and US anchors respectively, with Collins representing sensor-integration convergence through predictive maintenance service models. These three entities illustrate the strategic divide between manufacturing-scale defenders and service-revenue builders reshaping aftermarket economics.
| Leading Market Players |
|---|
| JAMCO Corporation |
| Safran |
| Collins Aerospace |
| Diehl Stiftung & Co. KG |
| RTX |
| Geven spa |
| Yokohama Rubber Co., Ltd. |
| FACC AG |
| CIRCOR Aerospace |
| Others |
Supply Flow & Price Mechanics
FAA airworthiness standards and EASA CS-25 certification requirements simultaneously gate supplier qualification and stratify price tiers across the aircraft lavatory system market. These dual regulatory frameworks create entry barriers that compress margins for uncertified fabricators while rewarding approved specialists with pricing power on altitude-rated components.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock specifications for program durations. Price differentiation rests on certification grade and volume scale, with dual FAA-EASA approved suppliers commanding premiums over single-jurisdiction competitors. Cost compression in standard-grade polymer assemblies is intensifying because locked OEM contracts prevent feedstock cost pass-through. Ultra-low-cost carriers exhibit highest price sensitivity, while business jet operators prioritize performance over unit cost.
Supply Chain Analysis
The United States, France, and Germany anchor specialized fabrication across titanium holding tanks, thermoplastic composites, and altitude-rated valve assemblies. Raw material feeds draw from engineering-grade polymer feedstocks, titanium alloys, and halogen-free flame-retardant compounds. Single-source vulnerability concentrates in European altitude-rated valve manufacturing where three specialists control dominant share. Distribution runs through authorized networks serving Boeing Washington, Airbus Toulouse and Hamburg, and MRO clusters in Georgia and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA-certified pressure vessel welders are retiring faster than training pipelines can replace them, creating a structural capability gap that constrains titanium holding tank output and reshapes competitive dynamics.
For Market Incumbents: Shield aftermarket revenue by deepening sensor-integrated service contracts that extend beyond hardware replacement cycles. Consolidate tier-two valve manufacturing capacity in Europe to reduce single-source exposure. Accelerate backward integration into thermoplastic compounding to control material cost curves against polymer feedstock volatility. For New Entrants and Emerging Players: EASA CS-25 fast-track certification for halogen-free thermoplastic formulations creates entry pathways for compounders with smoke density expertise. Target independent MRO channels in Indonesia and Vietnam where authorized distributor networks remain underdeveloped. Pursue modular lavatory pre-assembly partnerships with regional leasing companies seeking rapid cabin reconfiguration capabilities. For Investors and Strategic Acquirers: REACH substance restrictions on legacy flame-retardant chemistries reshape the acquisition landscape toward compounders with reformulated halogen-free portfolios. Five-to-ten year viability favors dual-approval specialists with captive aerospace customer relationships. Monitor MRO network consolidation patterns as the signal for whether aftermarket parts sourcing fragments along airframe-specific lines or remains accessible.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous FAA-EASA approval unlocks Boeing and Airbus program access without duplicate qualification timelines. |
| Sensor Integration Development | IoT-enabled waste monitoring creates recurring service revenue streams at Collins Aerospace's predictive maintenance model. |
| Backward Integration into Compounding | In-house thermoplastic production at JAMCO Corporation insulates margin from petrochemical index volatility. |
| Southeast Asia Distribution Expansion | Authorized networks in Indonesia and Vietnam capture retrofit demand from low-cost carrier fleet densification. |
| Specialized Welder Training Pipeline | FAA-certified pressure vessel welder development in Germany and the United States alleviates titanium tank fabrication bottlenecks. |
Methodological Framework
A standing panel of MRO procurement directors, OEM platform engineers, aftermarket service heads, and regulatory compliance officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholder categories against secondary validation from FAA airworthiness directives, EASA certification databases, customs trade records, and SEC filings from listed aerospace suppliers. Bottom-up component demand modeling triangulated against top-down fleet projection frameworks.
Consistency checks validated volume and value outputs against external benchmarks including aircraft delivery schedules and heavy maintenance interval patterns. The analytical framework segmented demand across system architecture, aircraft type, component category, and installation context throughout the projection horizon. CAGRs derived from fitted growth curves applied to replacement cycle frequencies and new-build line-fit ratios. Industry-specific inputs included vacuum generator retrofit penetration rates and REACH substance restriction implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained narrow-body delivery rates or accelerated regulatory phase-outs would require recalibration. Forecasts reflect documented assumptions regarding fleet age profiles and MRO network accessibility. Specific risks that could revise projections include raw material supply disruptions, certification timeline extensions, and OEM captive service strategies that restrict aftermarket parts sourcing. Recalibration cycles align with material shifts in regulatory implementation schedules and fleet densification mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Air Speed Indicator Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Middle-East Aviation Market
Aircraft
US Military Aviation Market
Aircraft
Strategic Bomber Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Firefighting Aircraft Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Aircraft Radome Market
Aircraft
North America Helicopters Market
Aircraft
Aircraft Window Frame Market