
 Asteroid Mining Market | 2026-2036
Asteroid Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Asteroid Mining Market Intelligence
The maturation of autonomous robotic extraction systems is narrowing the economic gap between terrestrial and space-based resource acquisition. This technological shift creates new commercial possibilities for specialized firms. AstroForge specializes in the refinement of platinum-group metals from near-Earth objects. TransAstra leverages its expertise in orbital logistics and propellant depots to support future mining missions.
Asteroid mining involves the exploitation of raw materials from asteroids and other minor planets. The process targets specific asteroid types, such as M-type for platinum-group metals or C-type for water ice, using robotic spacecraft. Its primary purpose is to secure resources for use in space, like construction and propellant, or for return to Earth. Within resource types, water ice for spacecraft fuel production currently holds the most immediate commercial viability, while the extraction of platinum group metals represents a longer-term, high-value objective for Earth resource supply.
The international legal framework is governed by the Outer Space Treaty, which presents ambiguities regarding private resource ownership. National legislation, such as the US Space Act of 2015 and Luxembourg's space resources law, provides a legal basis for companies to own and sell materials extracted in space. Future investment hinges on the development of a more unified international consensus on celestial property rights.
Market Dynamics
The economic viability of asteroid mining is currently shaped by the tension between near-term demand for in-space consumables and long-term ambitions for Earth-bound resource delivery. This dynamic prioritizes the extraction of water ice for propellant over more complex platinum-group metal retrieval.
Growth Catalysts
- In-Situ Resource Utilization (ISRU):Advances in ISRU technologies, particularly in water ice extraction and electrolysis, enable the production of rocket propellant directly in space, meeting immediate demand from satellite operators and national space agencies.
- National Legal Frameworks:The US Space Act of 2015 and Luxembourg's space resources law provide critical legal clarity, granting private entities ownership rights over extracted materials and thereby encouraging venture capital investment.
- Aerospace Sector Demand:Growing plans for lunar bases and Mars missions from agencies like NASA create a foundational customer base for water, oxygen, and construction materials sourced from near-Earth asteroids.
Market Restraints
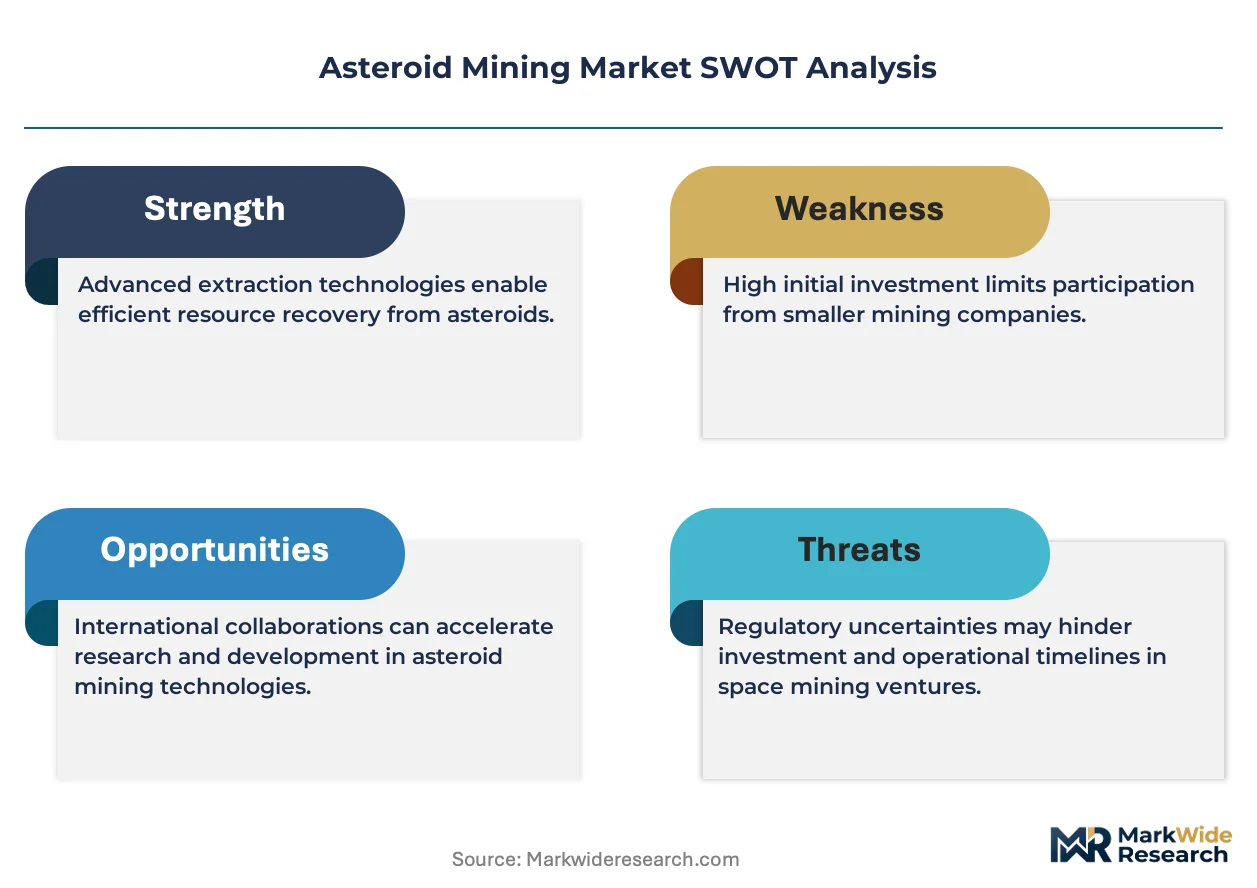
- Prohibitive Capital Costs:The initial investment required for prospecting, launching, and operating a single mining mission remains exceptionally high, creating a significant barrier to entry for all but the most well-funded ventures.
- International Law Ambiguity:The Outer Space Treaty prohibits national appropriation of celestial bodies but is silent on private resource extraction, creating legal uncertainty that deters conservative institutional investors.
- Extreme Operating Environments:Spacecraft must endure radiation, micrometeoroid impacts, and extreme temperature fluctuations, which increases mission complexity and the risk of catastrophic failure before any resources are recovered.
Strategic Opportunities
- Propellant Depot Networks:Developing a network of orbital refueling stations supplied by asteroid-derived water ice presents a first-mover advantage to service commercial satellites and deep space missions.
- Standardized Mining Hardware:Creating modular, off-the-shelf prospecting probes, extraction robots, and processing units could drastically reduce mission costs and development timelines for the entire industry.
- Expansion of Legal Regimes:Encouraging other nations with space capabilities, such as Japan or the United Arab Emirates, to adopt domestic space resource laws would broaden the global base for investment and collaboration.
Industry Challenges
- Specialized Talent Scarcity:A limited pool of professionals with combined expertise in fields like robotics, astrodynamics, and geology presents a significant operational bottleneck for scaling company operations.
- Mission Insurance Underwriting:The high risk and lack of historical data make it difficult and expensive to secure insurance for multi-billion-dollar mining missions, shifting significant financial risk onto the operating companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asteroid Mining Market |
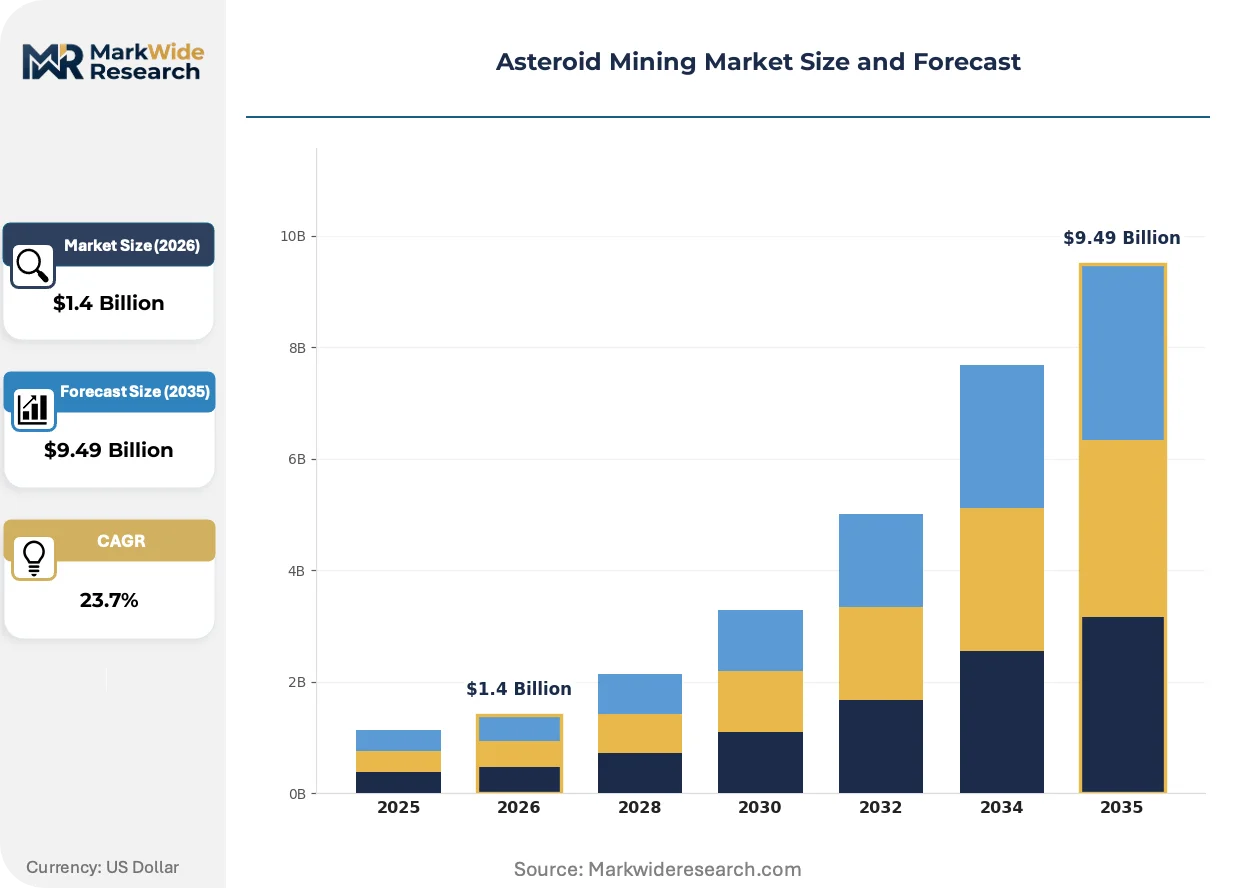
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $9.49 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resource Type: Platinum Group Metals, Rare Earth Elements, Water Ice, Nickel, Cobalt Mining Technology: Robotic Extraction, Automated Drilling, Tele-operated Systems, Sample Return Missions, In-Situ Processing Application: Spacecraft Fuel Production, Satellite Refueling, Space Infrastructure, Deep Space Exploration, Earth Resource Supply End User: Space Agencies, Aerospace Manufacturers, Space Mining Ventures, Scientific Research Institutions |
| Companies Covered | TransAstra, Pixxel, ispace, Lunasonde, Interlune, AstroForge, Karman Plus, Asteroid Mining Corporation, Fleet Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asteroid Mining Market Strategic Shifts & Innovations
The convergence of advanced robotics and artificial intelligence is actively reshaping the asteroid mining sector. This technological fusion is accelerating the transition from theoretical models to practical, small-scale demonstration missions, proving out core extraction and processing concepts in space.
Autonomous robotic systems are fundamental to the asteroid mining process. These systems use advanced AI for prospecting, navigation, and the mechanical extraction of materials from an asteroid's surface or subsurface. Commercial ventures are deploying them in early-stage proof-of-concept missions. The rapid maturation of this onboard intelligence is collapsing the economic gap between launching resources from Earth and producing them in-situ.
National legislation continues to provide the primary legal architecture for the industry. The US Commercial Space Launch Competitiveness Act of 2015 established a foundational precedent by granting American firms rights to resources they extract. This has spurred investment and forced an international dialogue, with other nations like Luxembourg and the UAE following with their own supportive laws, putting pressure on the United Nations to develop a global consensus.
A distinct shift in business strategy prioritizes securing in-space customers over speculative Earth-return models. This disrupts the previous focus on high-value platinum group metals, elevating the immediate commercial importance of water ice for propellant and life support. This trend is most visible in partnerships between mining startups and companies developing orbital logistics platforms and lunar surface infrastructure.
Asteroid Mining Market Segmentation
The asteroid mining market segmentation provides a granular view of the industry's evolving landscape, highlighting the distinct resource types, technological approaches, application areas, and end-user groups that define its commercial viability. Understanding these segments is crucial for strategic investment and technological development within this nascent space economy.
Resource Type:
The use-case spectrum for asteroid resources defines distinct extraction priorities and technological requirements.
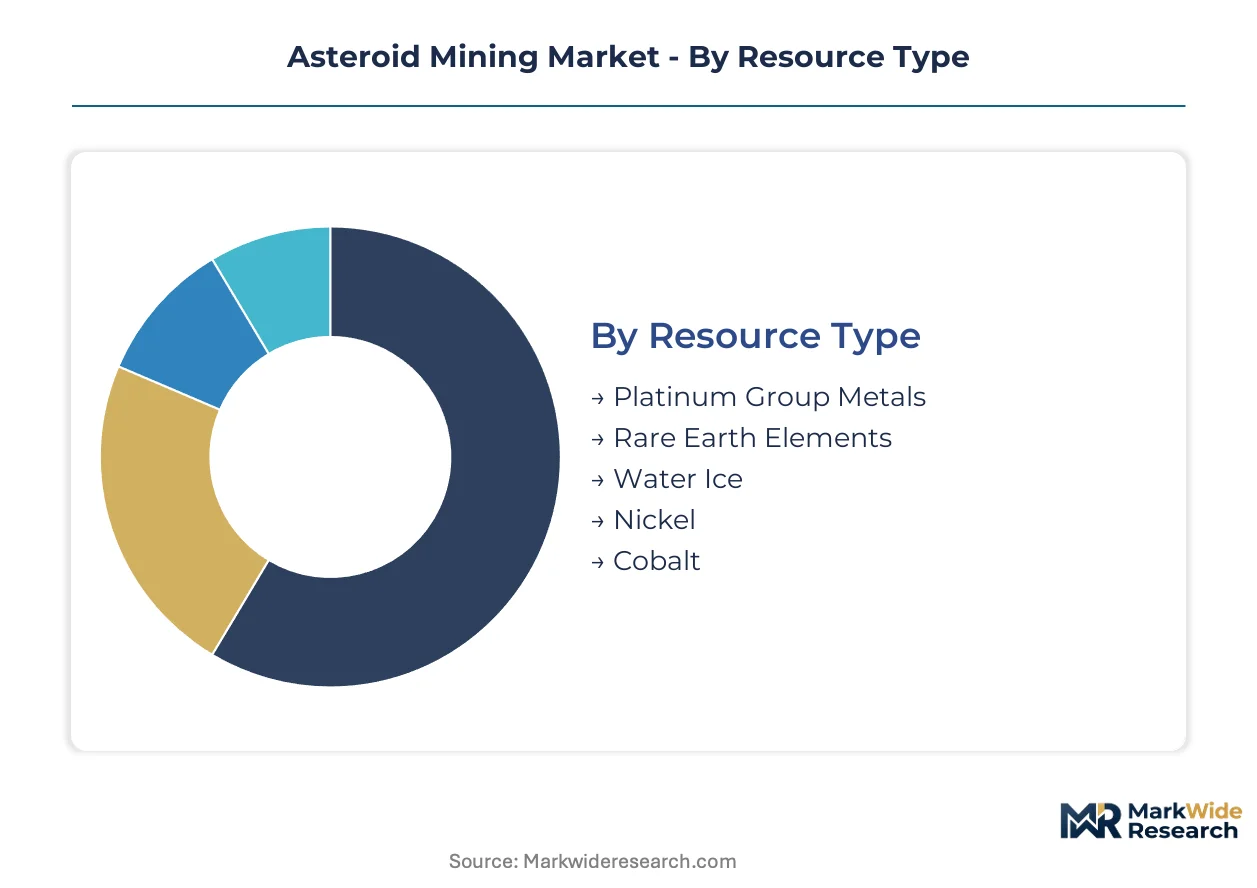
- Water Ice:This resource, primarily found on C-type asteroids, is critical for in-space propulsion and life support systems. Demand concentrates from national space agencies like NASA for lunar bases and Mars missions, driven by the imperative to reduce launch mass from Earth.
- Platinum Group Metals:These high-value metals, such as platinum, palladium, and rhodium, are abundant in M-type asteroids and possess high density and corrosion resistance. Earth-bound demand from the automotive and electronics industries drives long-term extraction objectives, despite current prohibitive return costs.
- Rare Earth Elements:These elements are vital for advanced electronics and renewable energy technologies. Extraction from asteroids offers a potential alternative to terrestrial supply chains, which face geopolitical and environmental challenges.
- Nickel:A common metallic element in asteroids, nickel serves as a foundational material for in-space construction and manufacturing. Its utility in structural components reduces reliance on Earth-launched materials.
- Cobalt:Important for high-strength alloys and battery technologies, cobalt from asteroids could support both in-space industrialization and future Earth markets. This metal offers superior temperature resistance for critical applications.
The dominant share belongs to Water Ice, while Platinum Group Metals is closing the gap fastest.
Mining Technology:
Technological application drives the evolution of extraction methodologies for celestial bodies.
- Robotic Extraction:Autonomous and semi-autonomous robotic systems perform the physical collection and initial processing of asteroid materials. These systems reduce human risk and enable continuous operations in harsh space environments, with companies like AstroForge deploying early prototypes.
- In-Situ Processing:Technologies for refining raw asteroid materials directly in space, such as electrolysis for water ice or chemical separation for metals, are essential for creating usable products. This capability eliminates the need for Earth-return and supports space infrastructure development.
- Automated Drilling:Specialized drills and excavation tools penetrate asteroid surfaces to access subsurface resources like water ice. These systems are designed for precision and durability in vacuum conditions.
- Tele-operated Systems:Remote-controlled robots allow human operators on Earth or in orbit to guide mining operations in real-time. This approach offers flexibility and human oversight for complex or unforeseen challenges.
- Sample Return Missions:Missions focused on bringing small quantities of asteroid material back to Earth for scientific analysis and technology validation. These missions provide crucial data for future large-scale mining endeavors.
Robotic Extraction systems currently dominate operational deployments, but In-Situ Processing capabilities are expanding most quickly.
Application:
The demand profile for asteroid-derived materials shapes investment into specific resource types and infrastructure.
- Spacecraft Fuel Production:Water ice extracted from asteroids is converted into hydrogen and oxygen propellants for rockets and satellites. This application meets immediate demand from satellite operators and national space agencies, reducing Earth launch costs.
- Earth Resource Supply:High-value materials like platinum group metals and rare earth elements are returned to Earth for terrestrial industries. This long-term objective aims to supplement or diversify global mineral supplies.
- Satellite Refueling:Orbital propellant depots supplied by asteroid-derived fuels enable satellites to extend their operational lifespan. This service offers significant cost savings for commercial satellite operators.
- Space Infrastructure:Asteroid materials, such as nickel and iron, can be used for constructing orbital platforms, lunar bases, and deep-space habitats. This reduces the need to launch heavy components from Earth.
- Deep Space Exploration:Resources harvested from asteroids support human and robotic missions beyond Earth orbit. This provides essential consumables and propellants for long-duration journeys to Mars and beyond.
Spacecraft Fuel Production represents the largest immediate market, with Earth Resource Supply gaining significant long-term strategic importance.
End User:
The operational focus of various entities dictates the specific types of asteroid mining products and services they procure.
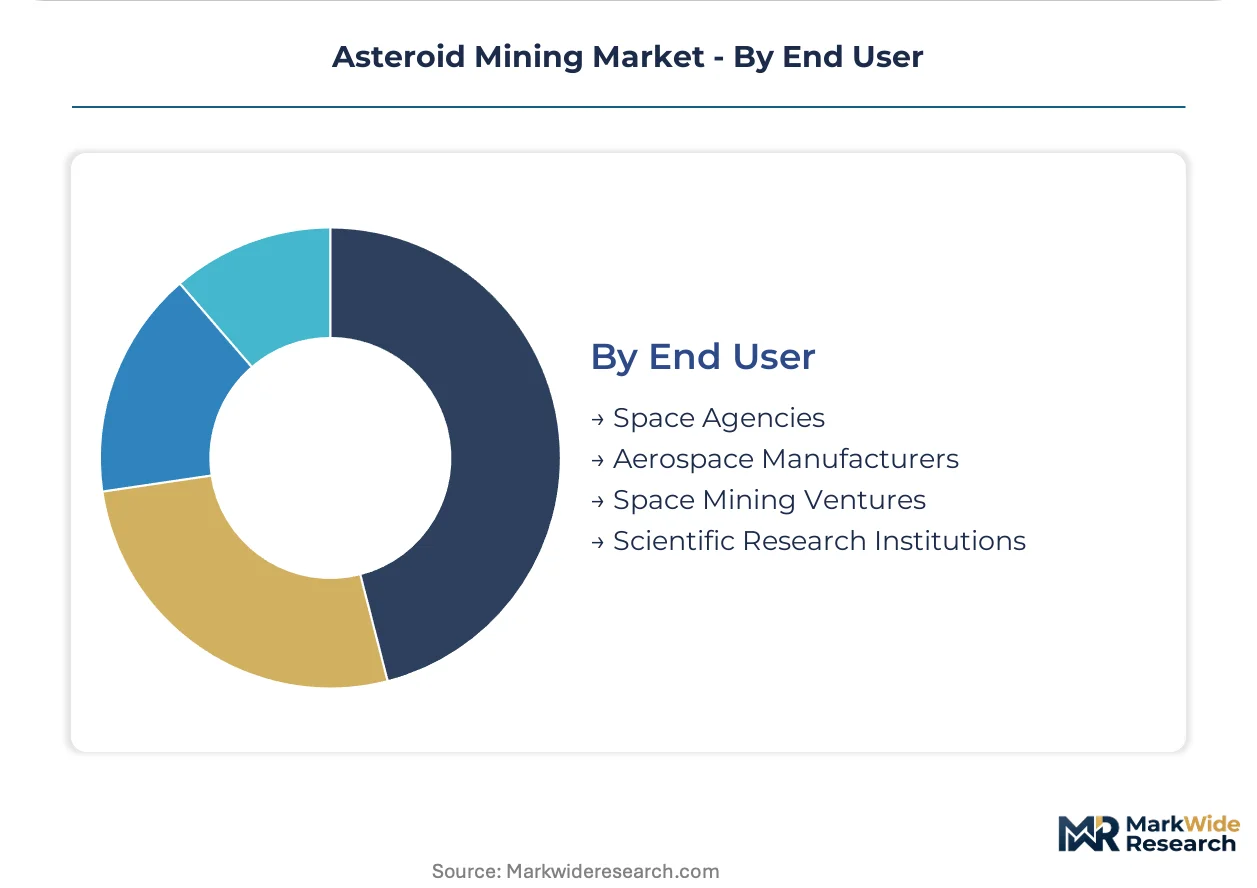
- Space Agencies:Government-funded organizations like NASA and ESA require asteroid resources for scientific missions, lunar exploration, and future human spaceflight programs. They often act as foundational customers and technology demonstrators.
- Space Mining Ventures:Commercial companies specializing in prospecting, extracting, and processing resources from asteroids. These entities aim to establish profitable supply chains for in-space and Earth-bound markets.
- Aerospace Manufacturers:Companies that build spacecraft, satellites, and launch vehicles. They represent a key customer base for asteroid-derived propellants and construction materials, seeking to reduce costs and increase mission flexibility.
- Scientific Research Institutions:Universities and research labs studying asteroid composition, geology, and resource extraction techniques. They often collaborate on early-stage missions and data analysis.
Space Agencies provide foundational demand, while Space Mining Ventures are rapidly expanding their commercial footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nascent asteroid mining market sees initial resource flows from concept to application, primarily originating from technology hubs in the United States and extending to international partners. This emerging industry builds foundational capabilities for future in-space economies. Demand for spacecraft fuel production drives early investment.
United States
Demand for asteroid resources primarily stems from national space agencies like NASA for lunar bases and Mars missions, aiming to reduce Earth launch mass. The US Space Act of 2015 provides critical legal clarity, granting private entities ownership rights over extracted materials. California's Silicon Valley attracts significant venture capital, supporting the development of advanced space mining technologies and commercial ventures.
Luxembourg
Luxembourg's strong legal and financial framework actively supports the development of space mining ventures. The country's space resources law provides a clear legal basis for companies to own and sell materials extracted in space. The financial sector in Luxembourg City actively supports early-stage space mining ventures, fostering an environment for innovation and investment.
Japan
Japanese companies and agencies show strategic interest in deep space exploration and resource utilization for future missions. The Ministry of Economy, Trade and Industry (METI) promotes space resource utilization initiatives through funding and policy support. Tokyo's aerospace industry integrates asteroid mining technologies, focusing on robotic systems and advanced materials processing.
United Arab Emirates
United Arab Emirates' long-term space ambitions and economic diversification strategy drive interest in space resource development. The UAE Space Agency actively funds space exploration and resource utilization research as part of its national agenda. Dubai's free zones attract international space startups, offering a conducive environment for technology development and commercialization.
Australia
Australia leverages its extensive expertise in terrestrial mining and remote operations for potential technology transfer to space resource extraction. The Australian Space Agency supports research into in-situ resource utilization and space-based manufacturing. Perth's mining technology hub explores advanced robotics and autonomous systems applicable to asteroid mining operations.
Asteroid Mining Market Key Industry Players
Channel-controlling players compete with product-specialist players across the asteroid mining market. The industry structure exhibits a tiered approach, with large aerospace firms pursuing full-service integration alongside smaller, agile technology providers. Key strategic archetypes include dedicated resource extraction companies, orbital logistics specialists, and in-situ processing solution developers. Companies frequently engage in strategic partnerships to mitigate risk and license advanced technologies for rapid deployment.
Specialists in resource extraction and processing, such as AstroForge, exemplify the focused approach required for specific celestial materials like platinum-group metals, demonstrating the viability of high-value resource targeting. TransAstra, on the other hand, occupies a position among companies developing critical orbital logistics and propellant depot infrastructure, crucial for sustaining in-space operations. The Japanese firm ispace highlights the growing interest in lunar resource utilization, anchoring a segment focused on near-Moon operations and supply chain development. These entities represent distinct yet complementary strategies within the nascent space resource economy, collectively advancing the industry's capabilities.
| Leading Market Players |
|---|
| TransAstra |
| Pixxel |
| ispace |
| Lunasonde |
| Interlune |
| AstroForge |
| Karman Plus |
| Asteroid Mining Corporation |
| Fleet Space |
| Others |
Cost & Logistics Intelligence
Limited capacity in orbital logistics infrastructure currently shapes supplier behavior and pricing posture within the asteroid mining market. This under-utilization drives cautious investment decisions and influences the cost structures for early-stage missions.
Pricing Analysis
The pricing gap between first-generation demonstration missions and future commercial-scale operations remains substantial. Early projects often operate on a project-based pricing model, covering high initial R&D and operational costs. Price differentiation stems from resource purity levels and the specific mission's complexity. Pricing pressure stems from national space agencies seeking to reduce long-term costs for in-space operations. Space agencies exhibit lower price sensitivity for strategic missions, while commercial ventures are highly sensitive to profitability margins.
Supply Chain Analysis
Early-stage technology development for asteroid mining concentrates within specialized robotics firms and aerospace manufacturers. Geographic supply concentration includes the United States for advanced robotics, Japan for precision engineering, and Luxembourg for financial and legal support. The supply chain draws from specialized alloys for spacecraft construction and high-performance computing components. Single-source vulnerability for niche components represents a structural risk. Distribution runs through direct contracts with national space agencies and aerospace manufacturers for mission-specific requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asteroid mining market presents a fragmentation opportunity, driven by diverse demand for in-space resources creating specialized niches.
For Market Incumbents: Build proprietary IP moats around advanced in-situ resource utilization (ISRU) technologies. Consolidate expertise in specific resource extraction, such as water ice or platinum-group metals, to achieve economies of scale. Invest in modular hardware standardization to reduce mission costs for future operations. The threat from agile technology providers necessitates continuous innovation in autonomous systems.
For New Entrants and Emerging Players: Build out partnerships with established aerospace manufacturers and orbital logistics providers. Target white-space opportunities in small-scale propellant depots or specialized sensor development for prospecting missions. The most penetrable segment lies in offering cost-effective, modular mission support services. A viable go-to-market angle involves demonstrating rapid prototyping and deployment capabilities for specific resource extraction challenges.
For Investors and Strategic Acquirers: Capital is best deployed toward companies specializing in in-space resource processing and orbital logistics infrastructure. The long-term viability for this market remains high over the next 5-10 years, driven by expanding lunar and Mars programs. Acquisition targets should include firms with proven demonstration missions in water ice extraction. A key signal to watch is the successful deployment of a commercial orbital propellant depot.
| Strategic Initiative | Industry Significance |
|---|---|
| Standardized ISRU Module Development | Reduces mission costs for commercial space agencies by providing interchangeable components. |
| Orbital Propellant Depot Network | Establishes critical infrastructure for deep space missions and satellite refueling operations. |
| Legal Framework Advocacy | Encourages unified international consensus on celestial property rights, attracting conservative institutional investors. |
| Specialized Talent Training Programs | Addresses the scarcity of professionals with combined expertise in astrodynamics and robotic engineering. |
| Strategic Partnership with Aerospace OEM | Secures a foundational customer base for asteroid-derived materials and in-space propellants. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. This involved discussions with space agency officials, space mining venture CEOs, aerospace manufacturer R&D leads, and astrodynamics researchers. Secondary data sources included national space agency reports, aerospace industry white papers, academic journals on space resources, and financial disclosures of public space companies. Bottom-up and top-down triangulation verified market size estimates.
A multi-stage calibration approach refined volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including resource type, mining technology, application area, and end-user group. Compound annual growth rates were derived from historical data extrapolation and projected technology adoption curves. Industry-specific forecast inputs included planned mission schedules and anticipated regulatory developments.
Stress conditions across technological readiness levels and international legal consensus were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect current assumptions regarding capital investment and mission success rates. Quarterly review of space agency budgets and private investment rounds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
India Space Electronics Market
Space
North America Spacesuit Market
Space
Deep Space Exploration Market
Space
Spacesuit Market
Space
Space Service Market
Space
Space Wheel Market
Space
South Korea Space Electronics Market
Space
Space Ground Station Equipment Market
Space
Space Management Solutions Market
Space
Space-Based Solar Power Market
Space
Europe Space Logistics Market
Space
US Reusable Launch Vehicle Market
Space
Space Blanket Market
Space
Mexico Space Electronics Market
Space
Canada Space Electronics Market
Space
Carrier Rocket Market