
 UK Space Propulsion System Market | 2026-2036
UK Space Propulsion System Market Size, Share, and Industry Trends Forecast 2026-2036
UK Space Propulsion System Market Insights
Modular propulsion packaging is consolidating buyer choice around integrated thruster-plus-power-processing units rather than discrete component sourcing. Airbus Defence and Space leverages its vertical integration across satellite platforms to anchor large-order propulsion supply. Safran SA competes through specialized chemical thruster production for European launch vehicles. Clyde Space Ltd differentiates with compact electric propulsion systems tailored for small satellite buses.
A space propulsion system generates thrust through controlled expulsion of propellant mass to alter spacecraft velocity, attitude, or orbital parameters, with specific impulse ranging from seconds for cold gas systems to thousands of seconds for gridded ion engines. Electric propulsion dominates research investment due to propellant efficiency gains for station-keeping missions, while chemical thrusters retain operational precedence for launch vehicle boost stages requiring high thrust-to-weight ratios. Satellite maneuvering applications command the largest addressable volume as constellation operators prioritize on-orbit servicing flexibility. Hall Effect Thrusters attract capital allocation from defense agencies seeking extended mission endurance for surveillance spacecraft.
The UK Space Agency regulates national launch and orbital activity licensing, while the Civil Aviation Authority oversees spaceport safety certification under the Space Industry Act. Export control alignment with the Wassenaar Arrangement shapes technology transfer boundaries for dual-use propulsion components. Stakeholders must monitor evolving debris mitigation rules that will mandate de-orbit capability specifications for new propulsion procurements.
Market Dynamics
The UK Space Propulsion System Market is being fundamentally restructured by the shift from chemical to electric propulsion architectures, as constellation operators prioritize propellant mass efficiency over raw thrust performance for station-keeping and orbital transfer missions.
Growth Catalysts
- National Space Strategy funding:UK Space Agency capital allocation is accelerating domestic thruster manufacturing capability through targeted grants for Hall Effect and gridded ion engine development.
- Constellation deployment surge:Low Earth orbit satellite operators are scaling procurement of integrated electric propulsion units for orbit-raising and de-orbit compliance.
- Spaceport infrastructure activation:Civil Aviation Authority licensing of Scottish and Cornish launch sites is creating captive demand for indigenous propulsion system integration services.
Market Restraints
- Xenon supply concentration:Electric propulsion dependency on xenon propellant faces sourcing vulnerability from limited global refining capacity concentrated in Russia and Qatar.
- Launch cost pass-through:Chemical thruster procurement remains constrained by launch vehicle economics, where propulsion system mass directly impacts payload pricing tiers.
- Wassenaar Arrangement controls:Dual-use classification of high-specific-impulse thruster technologies creates export licensing friction for UK manufacturers targeting non-allied markets.
Strategic Opportunities
- Scottish space cluster expansion:Glasgow's satellite manufacturing density creates localized demand for just-in-time propulsion module delivery and on-site integration services.
- Green propellant transition:Regulatory pressure from ESA's Clean Space initiative and UK debris mitigation guidelines is opening procurement windows for non-toxic monopropellant systems replacing hydrazine.
- On-orbit servicing emergence:Rendezvous and proximity operations missions require precision micro-thruster arrays, a capability gap where UK specialists can establish early positioning.
Industry Challenges
- Propulsion-electronics integration complexity:Power processing unit thermal management and electromagnetic compatibility testing extends qualification timelines for satellite prime contractors.
- Specialized vacuum facility access:Thuster performance validation requires large-space-simulation chambers, with UK test infrastructure concentrated at single national facilities creating queue bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Space Propulsion System Market |
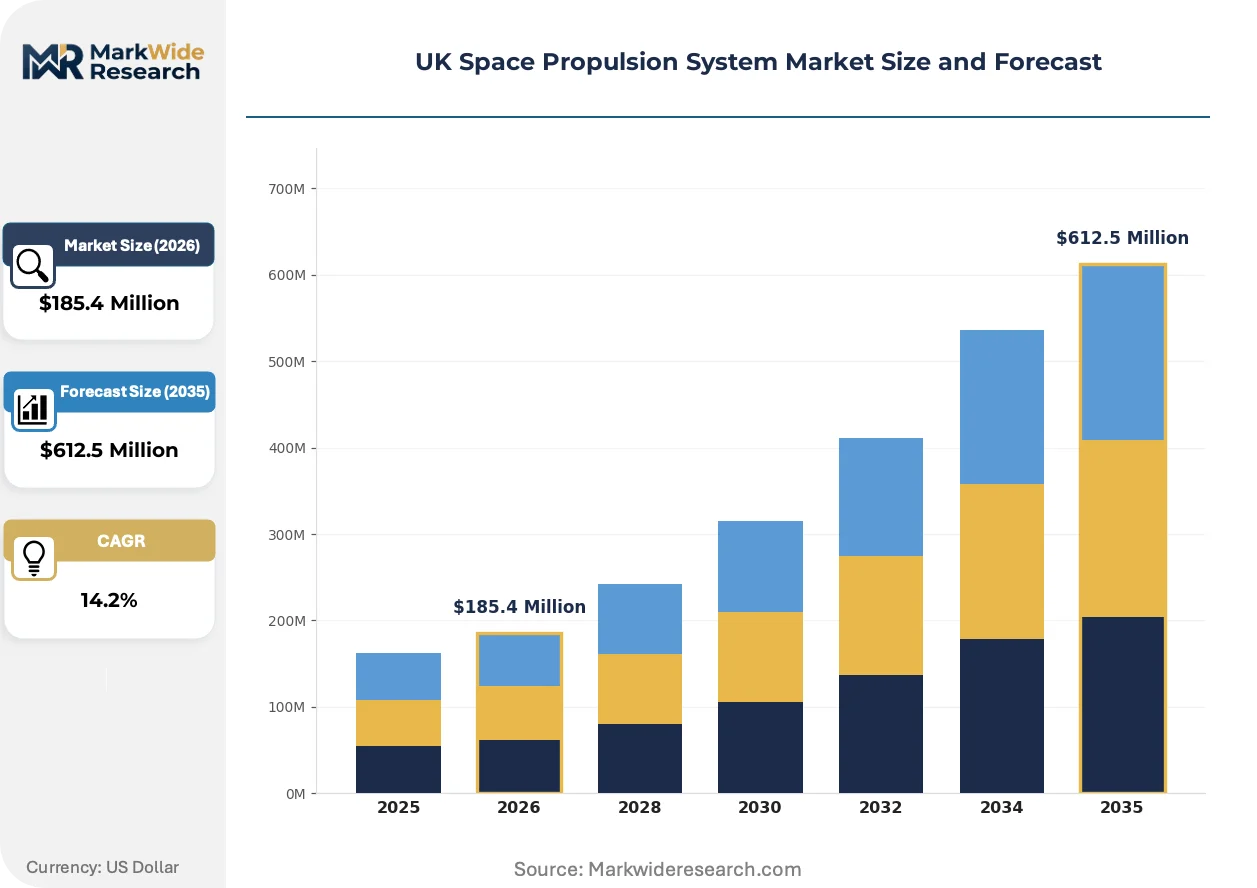
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $612.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Chemical Thrusters, Electric Propulsion, Hybrid Propulsion, Cold Gas Thrusters, Nuclear Thermal Application: Satellite Maneuvering, Orbital Transfer, Deep Space Exploration, Space Station Resupply, Launch Vehicle Boost Technology: Ion Engines, Hall Effect Thrusters, Resistojets, Arcjets, Magnetoplasmadynamic End User: Satellite Operators, Space Research Institutes, Defense Agencies, Commercial Space Companies, Academic Organizations |
| Companies Covered | Airbus Defence and Space, Surrey Satellite Technology Limited, Clyde Space Ltd, OneWeb, Telespazio VEGA UK, STAR-Dundee, Gravitilab, Craft Prospect, Safran SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Space Propulsion System Market Trends and Innovations
Active technology maturation is compressing the gap between laboratory thruster performance and flight-qualified reliability, while regulatory pressure on orbital debris is mandating propulsion-enabled end-of-life maneuvers as a baseline procurement requirement.
Additive manufacturing is converging with refractory metal thruster component production, enabling lattice-structured combustion chambers and regenerative cooling channels previously impossible through conventional machining. Satellite prime contractors are qualifying these printed parts for flight heritage on small satellite buses. The technology is converging with supply chain localization strategies, allowing UK manufacturers to bypass traditional forging and casting supplier networks concentrated in continental Europe.
The UK Space Agency's evolving debris mitigation licensing requirements under the Space Industry Act are mandating propulsion-enabled de-orbit capability for all new satellite authorizations. Operators must now demonstrate residual delta-v margins and operational reliability for end-of-life disposal maneuvers. Small satellite constellations in sun-synchronous orbits face the steepest compliance burden, driving procurement of compact but flight-proven electric propulsion units over unqualified novel architectures.
Buyer concentration among three dominant UK satellite prime contractors is compressing supplier negotiation leverage and accelerating long-term framework agreements over transactional procurement. Component vendors are responding with captive engineering resource allocation and co-development contracts replacing catalog sales. The shift is most visible in the CubeSat and small satellite segment, where Glasgow-based manufacturers are integrating vertically into propulsion subsystem design to secure supply security and schedule control.
UK Space Propulsion System Market Segmentation
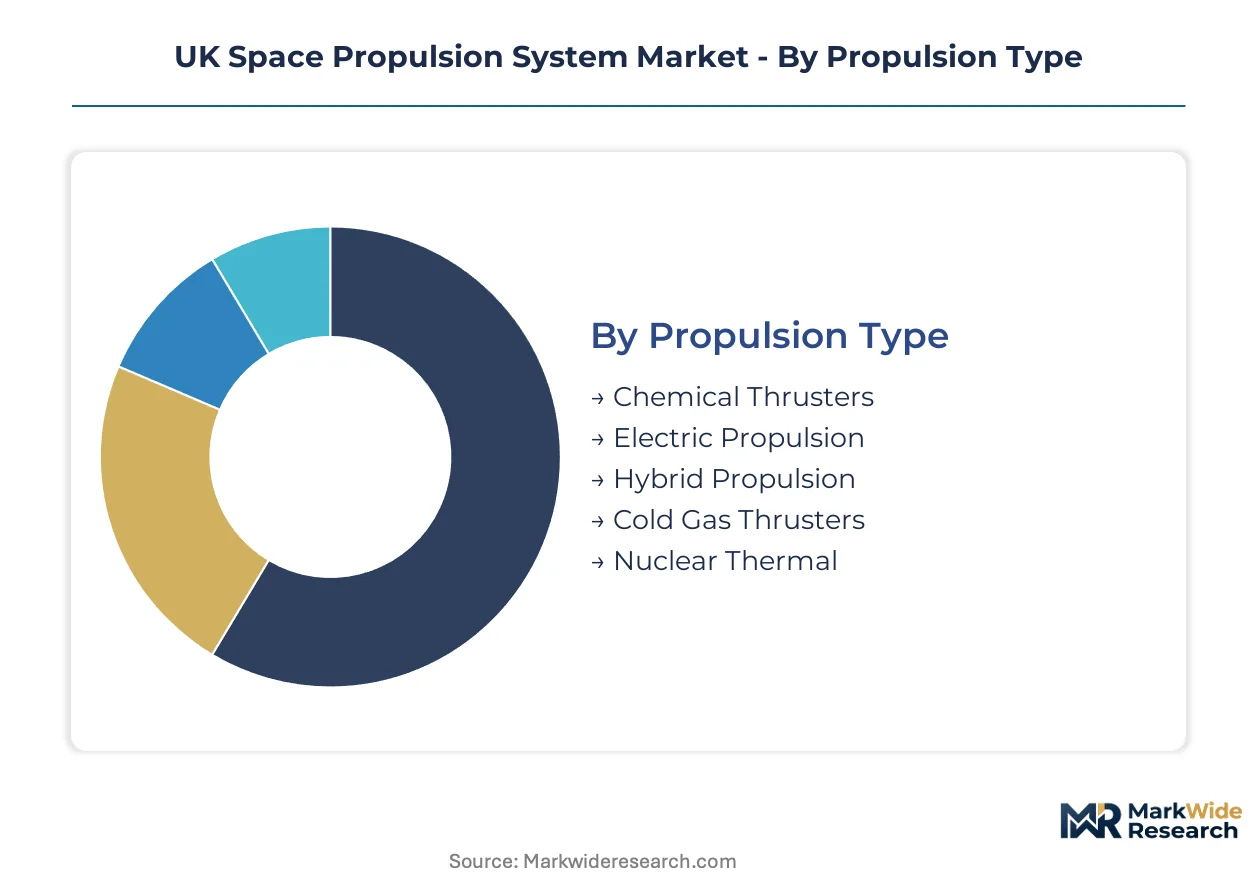
Propulsion system procurement in the UK splits along mission-critical performance thresholds. Buyers prioritize specific impulse efficiency for station-keeping or thrust density for orbit-raising. Each segmentation axis reveals distinct supplier qualification barriers and capital deployment patterns.
Propulsion Type:
Electric propulsion architectures demand the heaviest upfront engineering investment in power processing units and vacuum test infrastructure. Chemical thruster lines require substantial propellant handling certification and combustion stability programs.
- Chemical Thrusters:Bi-propellant and monopropellant systems generate high thrust-to-weight ratios through controlled decomposition or combustion reactions. UK launch vehicle integrators at Scottish spaceports source these for boost stages where raw impulse density outweighs mass efficiency concerns.
- Electric Propulsion:Gridded ion and Hall Effect configurations accelerate ions electrostatically or electromagnetically, achieving specific impulses ten times chemical alternatives. Satellite operators deploying LEO constellations concentrate procurement here for orbit-raising and de-orbit compliance under UK Space Agency licensing.
- Hybrid Propulsion:Combines solid fuel with liquid oxidizer for throttleable thrust profiles. Academic organizations and small satellite developers trial these for cost-sensitive technology demonstration missions.
- Cold Gas Thrusters:Compressed nitrogen or argon expulsion provides precise attitude control with minimal system complexity. CubeSat manufacturers in Glasgow integrate these for reaction wheel desaturation and fine pointing.
- Nuclear Thermal:Fission-heated hydrogen propulsion remains pre-commercial, with UK research institutes conducting materials qualification for future deep space architectures.
Most installed capacity flows through Chemical Thrusters. Expansion is steepest in Electric Propulsion.
Application:
Volume concentration skews toward missions requiring frequent delta-v maneuvers rather than single-burn events. Customer procurement cycles vary from multi-year framework agreements for constellation operators to grant-funded single orders for research missions.
- Satellite Maneuvering:Station-keeping, collision avoidance, and end-of-life disposal consume the majority of on-orbit propellant budgets. UK-licensed satellite operators must demonstrate de-orbit capability, mandating propulsion reserves across all new authorizations.
- Orbital Transfer:Moving payloads between LEO, MEO, and GEO altitudes requires substantial delta-v and precise burn sequencing. Space tugs and orbital servicing vehicles under development in Oxfordshire and Harwell anchor emerging demand.
- Deep Space Exploration:Interplanetary missions prioritize specific impulse maximization over thrust magnitude. UK research institutes contribute Hall Effect thruster components to ESA science missions targeting outer planets.
- Space Station Resupply:Automated cargo vehicles require rendezvous and docking propulsion with fault-tolerant redundancy. Commercial space companies near Bristol and Stevenage pursue this capability for future UK orbital platforms.
- Launch Vehicle Boost:First and second stage engines demand combustion stability across wide throttle ranges. Indigenous launch programs at SaxaVord and Spaceport Cornwall drive qualification of domestically manufactured pressure-fed systems.
Satellite Maneuvering commands the largest addressable volume. Orbital Transfer applications are climbing the fastest as on-orbit servicing architectures mature.
Technology:
Technical maturity curves separate flight-proven options from laboratory-stage alternatives. Qualification heritage determines supplier selection more than raw performance specifications for risk-averse prime contractors.
- Ion Engines:Electrostatic acceleration of xenon ions yields the highest demonstrated specific impulse among flight systems. Defense agencies funding surveillance satellites with decade-plus mission lifetimes prioritize this technology for station-keeping endurance.
- Hall Effect Thrusters:Closed electron drift channels generate thrust densities superior to gridded alternatives at moderate efficiency penalties. Constellation operators scaling LEO deployments source these for orbit-raising speed and manufacturing repeatability.
- Resistojets:Electrical resistance heating of propellant offers simplicity and rapid pulsing for attitude control. Small satellite buses with limited power budgets integrate these for momentum management.
- Arcjets:Electrical arcs superheat hydrogen or hydrazine for intermediate specific impulse performance. Limited UK flight heritage constrains adoption to experimental technology demonstration payloads.
- Magnetoplasmadynamic:Lorentz force acceleration of plasma achieves theoretical thrust densities exceeding Hall thrusters. Research institutes at Surrey and Southampton pursue electrode erosion mitigation for future qualification.
Hall Effect Thrusters dominate current procurement volumes. Ion Engines are gaining share fastest among extended-duration defense and science missions.
End User:
Buyer concentration among a handful of satellite prime contractors compresses supplier margins and accelerates captive engineering arrangements. Fragmentation at the research and academic tier sustains catalog sales for standardized components.
- Satellite Operators:Commercial constellation deployers purchase integrated propulsion subsystems through multi-year framework agreements. Glasgow-based manufacturers increasingly backward-integrate into thruster design to secure supply security.
- Space Research Institutes:ESA and UK Research and Innovation fund technology maturation programs with milestone-based payments. These customers tolerate higher technical risk in exchange for performance advancement.
- Defense Agencies:UK Ministry of Defence and allied European militaries procure radiation-hardened systems with encrypted telemetry. Wassenaar Arrangement compliance requirements restrict vendor pools to cleared suppliers.
- Commercial Space Companies:Venture-funded launch and satellite ventures prioritize schedule certainty over optimization. These buyers accept commercial-off-the-shelf thrusters with limited customization.
- Academic Organizations:University-led CubeSat programs operate on constrained budgets with student labor integration. Cold gas and resistojet systems dominate this price-sensitive tier.
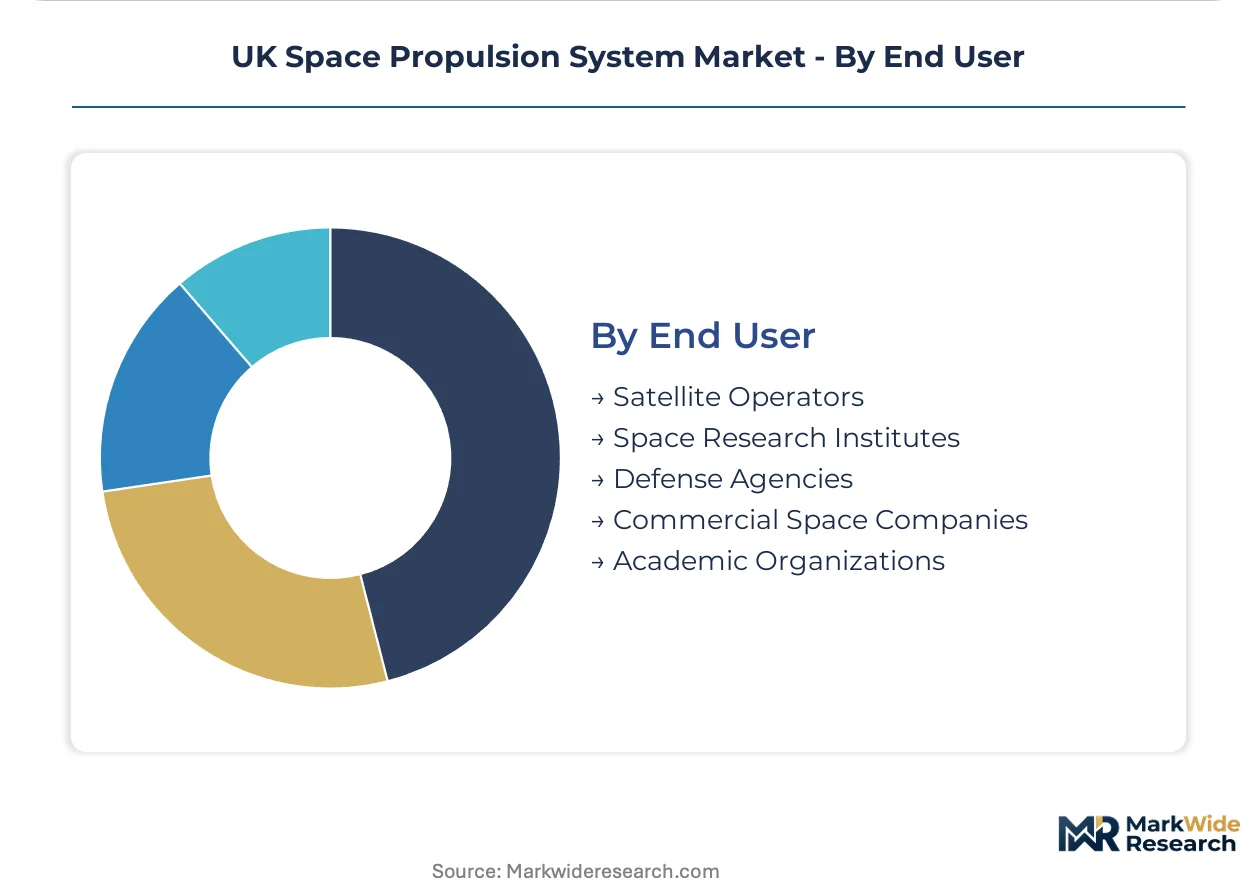
Satellite Operators represent the largest revenue concentration. Defense Agencies are expanding most quickly as sovereign space capabilities become strategic priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK space propulsion industry traces its lineage to post-war rocket research at Farnborough and Woomera, with sustained government investment through the British National Space Centre and its successor UK Space Agency anchoring domestic capability development.
Scotland
SaxaVord and Spaceport Cornwall licensing under the Civil Aviation Authority is driving demand for indigenous chemical thruster integration. The Scottish Government's space strategy funds orbital launch infrastructure. Glasgow's satellite manufacturing cluster concentrates procurement of compact electric propulsion units for constellation buses.
South East England
Harwell Science and Innovation Campus hosts satellite prime contractors scaling Hall Effect thruster procurement for ESA science missions. UK Research and Innovation's National Space Technology Programme channels grants into power processing unit development. Oxfordshire research institutes pursue electrode erosion mitigation for advanced plasma thrusters.
South West England
Spaceport Cornwall's horizontal launch licensing creates captive demand for pressure-fed propulsion system qualification. The Cornwall and Isles of Scilly Local Enterprise Partnership coordinates supply chain localization for launch vehicle integrators. Goonhilly Earth Station's ground segment expansion supports propulsion telemetry validation for satellite operators.
Midlands
Leicester Space Park's academic-industry partnerships accelerate resistojet and cold gas thruster maturation for CubeSat applications. The Midlands Engine investment fund backs additive manufacturing of refractory metal combustion chambers. Coventry's automotive supply chain crossover firms are entering spacecraft component fabrication.
Wales
Cardiff-based compound semiconductor foundries supply power electronics for electric propulsion systems. The Welsh Government's Advanced Manufacturing Research Centre supports vacuum facility infrastructure for thruster performance validation. North Wales aerospace suppliers are diversifying into satellite propulsion subsystem integration.
UK Space Propulsion System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology qualification spectrum, with flight heritage commanding pricing power over laboratory-stage alternatives. The UK market structures around three tiers: satellite prime contractors with captive propulsion design, specialized thruster manufacturers with ESA heritage, and emerging ventures targeting small satellite cost points. Consolidation pressures are intensifying as Glasgow-based manufacturers backward-integrate into thruster production, while framework agreements are displacing transactional procurement for constellation operators.
Among UK-based satellite prime contractors, Airbus Defence and Space and Surrey Satellite Technology Limited exemplify the vertically integrated tier, anchoring large-order propulsion supply through in-house subsystem design. Clyde Space Ltd occupies a specialist position within the small satellite segment, representing the compact electric propulsion archetype tailored for CubeSat and nanosatellite buses. These three entities collectively illustrate the competitive segmentation between scale-driven platform integration and focused thruster technology development.
| Leading Market Players |
|---|
| Airbus Defence and Space |
| Surrey Satellite Technology Limited |
| Clyde Space Ltd |
| OneWeb |
| Telespazio VEGA UK |
| STAR-Dundee |
| Gravitilab |
| Craft Prospect |
| Safran SA |
| Others |
Pricing and Supply Chain Analysis
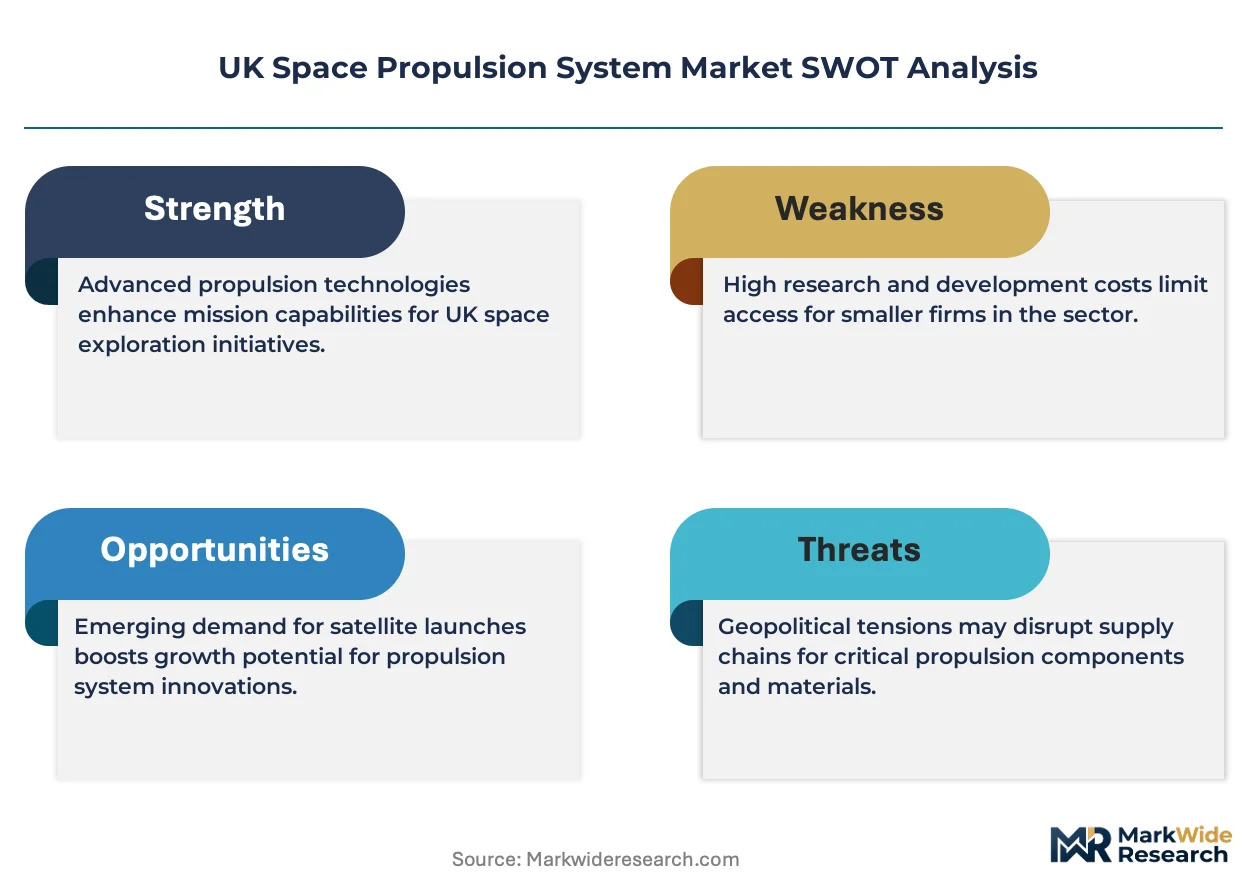
Xenon propellant costs cascade through electric propulsion supply chains, concentrating pricing power with Russian and Qatari refiners upstream while squeezing margins for UK thruster integrators downstream. Hall Effect Thruster manufacturers pass through volatile noble gas pricing via long-term framework agreements with satellite operators, insulating constellation deployers from spot market spikes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments UK propulsion procurement by flight heritage and certification grade. Premium tiers command substantial markups for ESA-qualified Hall Effect thrusters with radiation-hardened power processing units, while economy tiers serve Glasgow-based CubeSat developers with catalog cold gas systems. Cost compression in the mid-tier intensifies because Glasgow manufacturers backward-integrate into thruster production, eroding supplier margins. Academic organizations exhibit highest price sensitivity, while UK Ministry of Defence procurement shows lowest sensitivity due to encrypted telemetry and sovereign capability requirements.
Supply Chain Analysis
Regional distribution centers for propulsion subsystems cluster around Harwell Science and Innovation Campus and Glasgow satellite manufacturing corridors, feeding just-in-time integration lines. Upstream supply draws from Russia and Qatar for xenon refining, Germany and France for precision machining of gridded ion engine components, and Japan for high-purity ceramics. Single-source vulnerability concentrates in xenon isotope separation capacity, where geopolitical disruption would immediately constrain UK electric propulsion output. Distribution runs through prime contractor captive logistics networks rather than independent distributors, with Airbus Defence and Space and Surrey Satellite Technology Limited controlling thruster-to-platform integration scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK space propulsion hinges on additive manufacturing cost-down trajectories for refractory metal thruster components, enabling domestic production to displace continental European forging networks. Premium-tier positioning accelerates as debris mitigation regulations mandate flight-proven de-orbit capability, disqualifying unqualified architectures from UK Space Agency licensing.
For Market Incumbents: Deploy captive engineering resource allocation to lock constellation operators into multi-year framework agreements before Glasgow manufacturers complete backward integration into thruster design. Incumbents must accelerate power processing unit thermal management R&D to compress qualification timelines that currently disadvantage UK suppliers against continental primes. The threat of Safran SA's specialized chemical thruster production expanding into electric propulsion via acquisition demands preemptive certification investment in Hall Effect heritage. For New Entrants and Emerging Players: Additive manufacturing of lattice-structured combustion chambers offers a technology-first wedge for penetrating the small satellite resistojet segment where legacy suppliers lack printed part flight heritage. New entrants should target the CubeSat cold gas thruster tier, where Leicester Space Park academic partnerships create low-barrier entry points and price-sensitive university programs tolerate higher technical risk. A go-to-market angle emphasizing rapid customization for technology demonstration missions, funded through UK Research and Innovation milestone-based payments, bypasses incumbent-dominated prime contractor procurement channels. For Investors and Strategic Acquirers: Consolidation pressure builds where Glasgow satellite manufacturers backward-integrate into propulsion subsystem design, eliminating standalone thruster vendor addressable market. Long-term viability over the coming decade favors acquisition targets with ESA flight heritage and existing power processing unit qualification, as UK Space Agency debris mitigation rules raise barriers for novel architectures. The signal to watch is Civil Aviation Authority licensing velocity at SaxaVord and Spaceport Cornwall, where indigenous launch demand creation would revalue domestic chemical thruster capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Scale-Up | Enables UK bypass of continental European forging networks for refractory metal thruster components. |
| Power Processing Unit Development | Reduces qualification timelines that currently disadvantage UK suppliers against ESA heritage primes. |
| De-Orbit Capability Certification | Secures UK Space Agency licensing compliance as debris mitigation rules tighten procurement requirements. |
| Xenon Supply Agreement Diversification | Mitigates Russian and Qatari refining concentration that threatens electric propulsion output continuity. |
| Scottish Space Cluster Integration | Captures Glasgow constellation manufacturer demand through localized just-in-time propulsion module delivery. |
Research Methodology
Bottom-up satellite operator procurement modeling reconciled against top-down thruster manufacturing capacity tracking forms the analytical core of this study. Primary interviews with UK Space Agency licensing officers, satellite prime contractor procurement directors, Hall Effect thruster engineering leads, and Civil Aviation Authority spaceport safety inspectors combined with secondary validation from UK Research and Innovation grant disclosures, ESA mission procurement records, and Civil Aviation Authority licensing registers. Trade data from HM Revenue and Customs on xenon and noble gas imports, alongside UK Space Agency National Space Strategy funding announcements, anchored supply-side triangulation against demand-side constellation deployment schedules.
Historical trendline analysis of electric propulsion adoption rates across LEO constellation programs established baseline penetration curves extended across the analysis window. Segmentation dimensions modeled include propulsion type, application mission profile, technology maturity tier, and end-user procurement authority. CAGRs derived from fitted growth curves adjusted for UK Space Agency capital allocation trajectories and Scottish spaceport infrastructure activation timelines. Industry-specific forecast inputs incorporated Wassenaar Arrangement export control friction coefficients and ESA Clean Space initiative regulatory pressure timelines.
The model holds under stable UK Space Agency funding continuity and Civil Aviation Authority licensing progression; deviation in xenon supply disruption or Scottish launch site delays would shift trajectory. Forecasts reflect documented assumptions regarding debris mitigation rule enforcement timing and additive manufacturing qualification velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Asia-Pacific Space Electronics Market
Space
Space Robotics Market
Space
US Space Launch Services Market
Space
Carrier Rocket Market
Space
Italy Space Electronics Market
Space
Suborbital Space Tourism Market
Space
Mexico Space Electronics Market
Space
Deep Space Robotics Market
Space
Space Robots Market
Space
Space Ground Station Equipment Market
Space
Space Oscillator Market
Space
Space Debris Monitoring and Removal Market
Space
Space Debris Monitoring Market
Space
Space Semiconductor Market
Space
UK Space Electronics Market
Space
Deep Space Exploration Market