
 Europe Space Logistics Market | 2026-2036
Europe Space Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Space Logistics Market Analytics
Heavy-lift certification tiers is rotating toward reusable-vehicle qualification standards as the baseline for competitive bidding. Airbus Defence and Space leverages its vertical integration across manufacturing and launch services to sustain program margins. Arianespace anchors European heavy-lift capacity through Ariane 6 operations from Kourou. OHB SE specializes in small-satellite logistics and orbital servicing platforms for institutional clients.
Europe space logistics encompasses the end-to-end movement of satellites, payloads, and orbital assets from terrestrial integration facilities to designated orbital slots, utilizing cryogenic propulsion systems rated to specific impulse thresholds above 440 seconds for geostationary transfer missions. Satellite deployment services command the largest revenue pool within service type segmentation due to constellation replenishment cycles for communications and Earth observation networks. Reusable rocket technology captures the fastest expansion trajectory among technology segments as ESA funding and national space agency programs de-risk recovery and refurbishment economics. Government agencies represent the most stable demand channel within end user segmentation, though commercial enterprises are narrowing the gap through venture-backed Earth observation and connectivity ventures.
ESA procurement frameworks and EU Green Deal launch-emission benchmarks shape vehicle development priorities and operator licensing timelines across member states. France's CNES, Germany's DLR, and Italy's ASI coordinate national program allocations that determine facility investments at Guiana Space Centre and Bremen manufacturing clusters. REACH chemical regulations and CE marking requirements for space-grade materials constrain supplier qualification pathways for propellant systems and thermal protection components. Stakeholders must monitor how ESA's European Launcher Challenge and evolving EU space traffic management rules redistribute contract volumes between established primes and emerging launch providers.
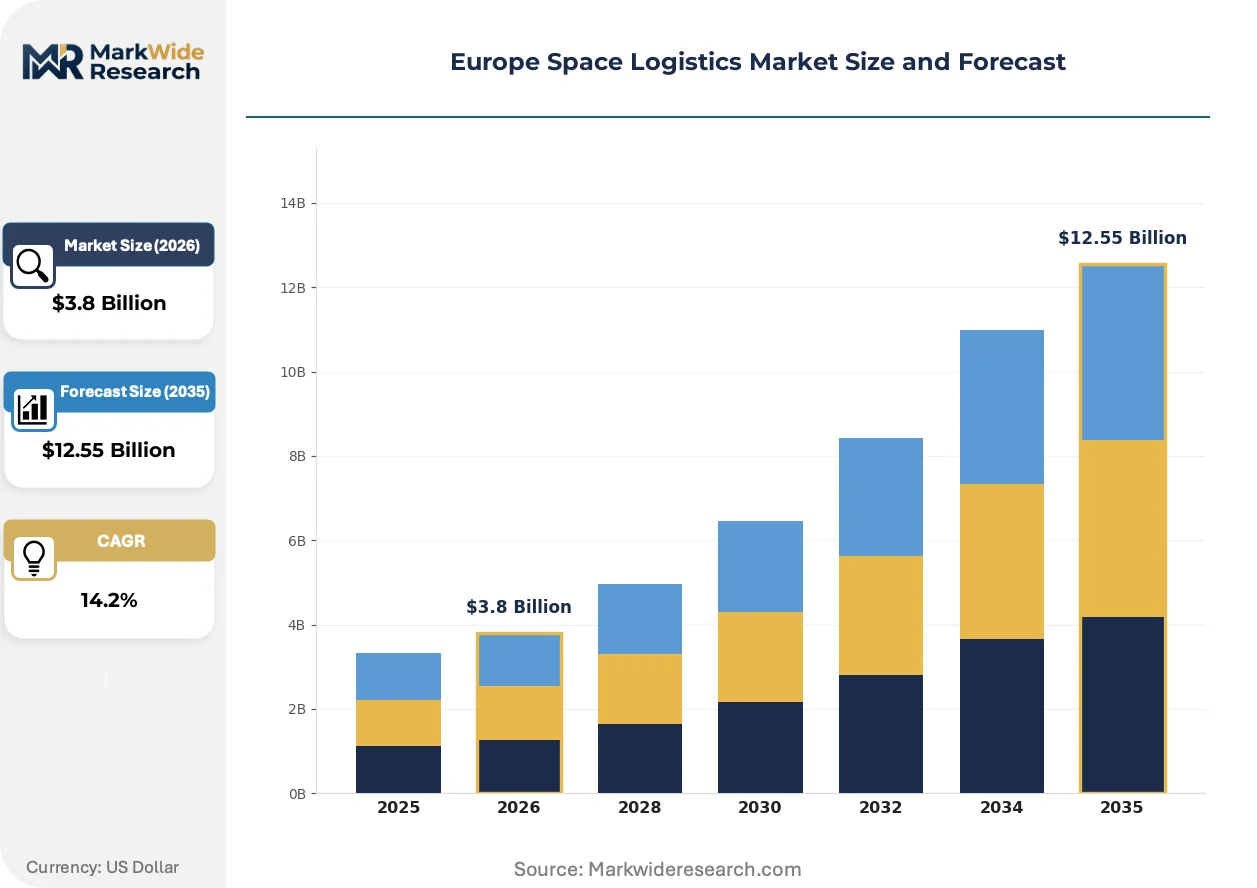
Market Dynamics
Reusable rocket recovery economics are compressing launch cost structures across European spaceports, forcing incumbent operators to requalify vehicle architectures for multiple-flight certification tiers. This technological pivot is redistributing procurement volumes between established heavy-lift programs and emerging recovery-capable entrants.
Growth Catalysts
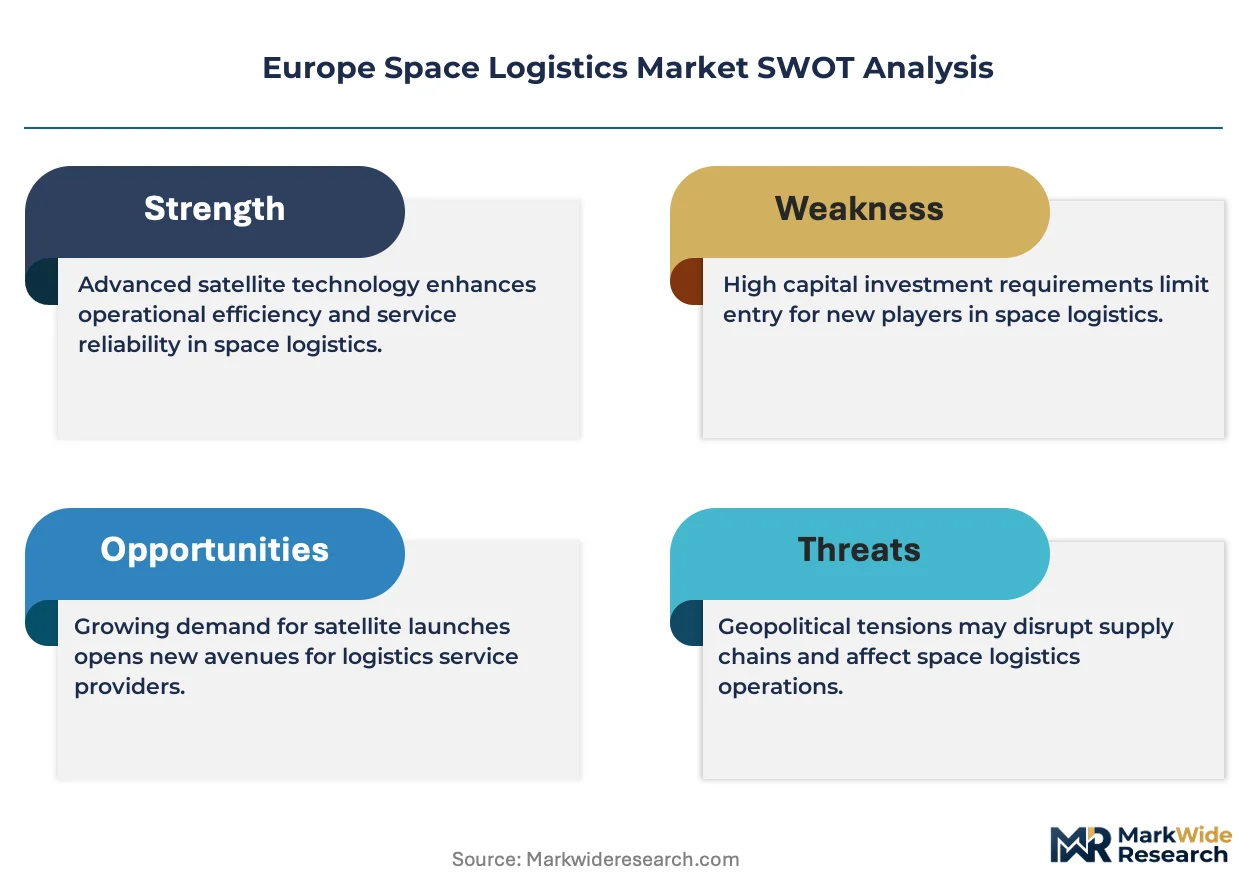
- EU Green Deal emission benchmarks:The framework mandates propulsion technology upgrades for launch vehicles operating from member state territories, accelerating investment in methane-oxygen engine architectures.
- Constellation replenishment cycles:Commercial Earth observation and broadband networks in Germany and France require sustained orbital transfer service procurement, stabilizing demand for payload integration facilities.
- ESA procurement frameworks:These structures de-risk development costs for reusable vehicle demonstrators, channeling public funding toward flight-proven recovery systems.
Market Restraints
- Cryogenic propellant supply concentration:Liquid hydrogen production clusters in specific industrial zones create logistics bottlenecks for launch site replenishment.
- REACH chemical compliance timelines:Extended qualification pathways for space-grade propellant systems delay supplier onboarding and contract execution.
- Geostationary slot scarcity:ITU coordination procedures for orbital positions extend mission planning horizons and tie up capital in pre-launch positioning.
Strategic Opportunities
- Orbital servicing platforms:Life extension missions for aging geostationary assets create demand for rendezvous and proximity operations capabilities.
- Small-satellite dedicated launch:Italy and Spain present underpenetrated demand for responsive launch services serving venture-backed constellation operators.
- EU space traffic management rules:Emerging collision avoidance mandates will require logistics providers to integrate tracking and maneuver coordination services.
Industry Challenges
- Flight-proven engineer scarcity:Recovery system refurbishment expertise concentrates within a limited talent pool, constraining operational scaling.
- Multi-flight certification complexity:Requalification protocols for reused thermal protection components extend vehicle turnaround timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Space Logistics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Satellite Deployment, Payload Integration, Orbital Transfer, Spacecraft Maintenance Technology: Reusable Rockets, Space Tug, Propulsion Systems, Autonomous Navigation End User: Government Agencies, Research Institutions, Commercial Enterprises, Defense Contractors Delivery Model: On-Demand Services, Dedicated Missions, Bulk Delivery, Collaborative Projects |
| Companies Covered | Airbus Defence and Space, Arianespace, RUAG Space, Thales Alenia Space, Ariane Group, OHB SE, Safran SA, Avio, PLD Space, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Space Logistics Market Evolving Landscape
Additive manufacturing of propulsion components is shortening supply chains for combustion chamber assemblies, with powder-bed fusion techniques now qualifying for flight-critical applications. This production shift is altering supplier qualification hierarchies across Bremen and Kourou manufacturing clusters.
Green propellant alternatives are decomposing the monopropellant hydrazine standard that has dominated attitude control systems for three decades. Institutional satellite operators in France and Germany are piloting ammonium dinitramide-based formulations for constellation buses, compressing ground handling infrastructure requirements and eliminating toxic fuel transport restrictions at the Guiana Space Centre.
EU Green Deal launch-emission benchmarks are mandating methane-oxygen propulsion architectures over storable hypergolic systems for new vehicle certifications. This regulatory pivot elevates development priorities for full-flow staged combustion cycles, with French and German national space agencies restructuring procurement timelines to accommodate extended test programs for cleaner-burning engines.
Service unbundling is fragmenting traditional integrated launch contracts into separable payload integration, orbital transfer, and deployment modules. Commercial constellation operators in Germany are procuring these elements through distinct vendor relationships rather than single-prime arrangements, compressing contract values for established launch providers while opening slots for specialized logistics entrants.
Europe Space Logistics Market Segmentation
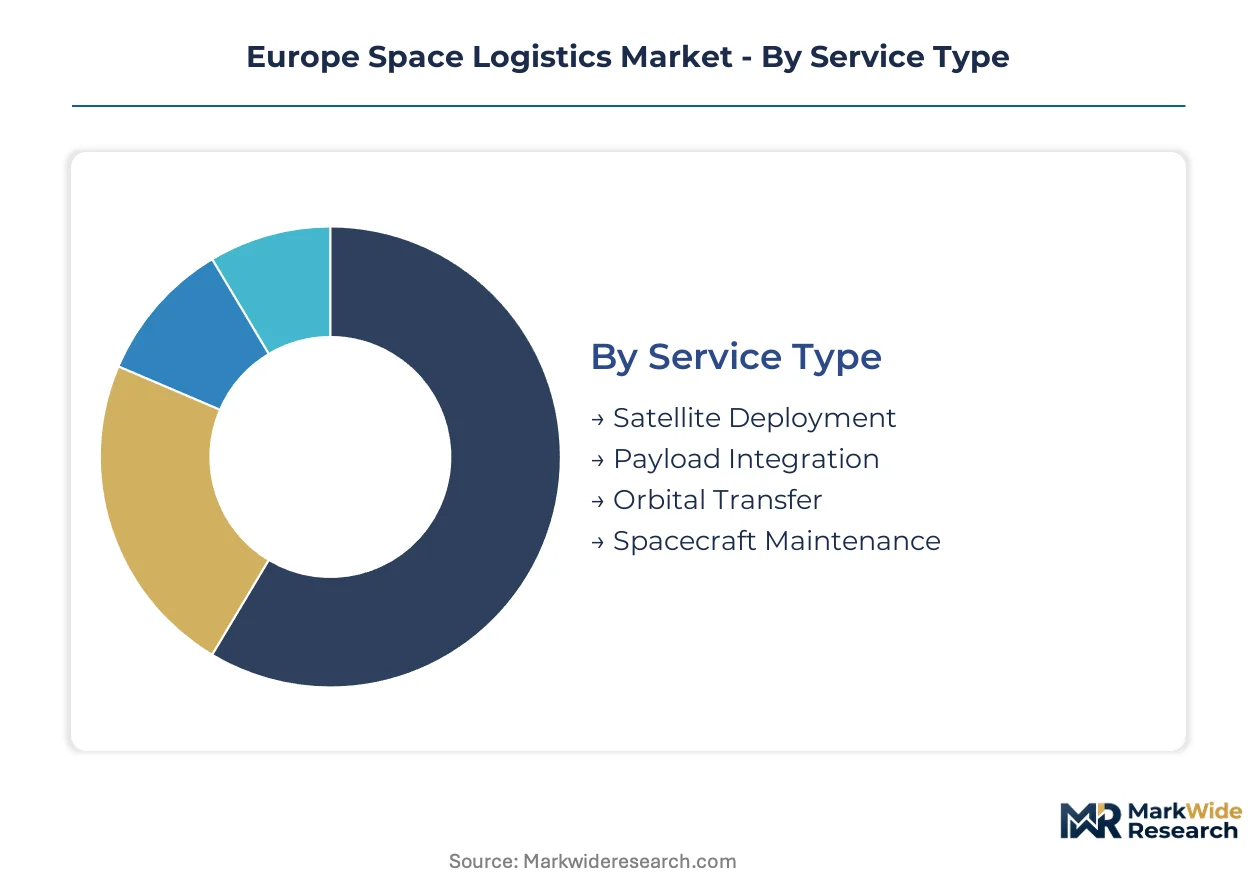
Service unbundling across European spaceports fragments traditional integrated contracts into separable modules. Procurement patterns now favor specialized vendors for distinct mission phases over single-prime arrangements.
Service Type:
Margin pools concentrate in pre-launch payload preparation and orbital insertion phases where technical certification requirements create supplier scarcity.
- Satellite Deployment:Constellation replenishment cycles for communications and Earth observation networks command the largest revenue pool. German and French commercial operators sustain procurement volumes through multi-year service agreements with launch providers.
- Orbital Transfer:Cryogenic propulsion systems rated above 440 seconds specific impulse enable geostationary transfer missions. France's Guiana Space Centre anchors demand concentration as the primary European facility for payload integration and dedicated mission services.
- Payload Integration:REACH chemical regulations and CE marking requirements constrain supplier qualification pathways for propellant systems and thermal protection components.
- Spacecraft Maintenance:Life extension missions for aging geostationary assets create emerging demand for rendezvous and proximity operations capabilities.
Satellite Deployment holds installed capacity. Orbital Transfer is rotating up the share rankings.
Technology:
Cost tier stratification separates flight-proven recovery systems from developmental architectures still seeking multi-flight certification.
- Reusable Rockets:Recovery and refurbishment economics are compressing launch cost structures across European spaceports. ESA funding and national space agency programs de-risk operational scaling for flight-proven systems.
- Propulsion Systems:EU Green Deal emission benchmarks mandate methane-oxygen engine architectures over storable hypergolic systems. French and German national space agencies restructure procurement timelines to accommodate extended test programs for cleaner-burning full-flow staged combustion cycles.
- Space Tug:Orbital servicing platforms enable payload repositioning without dedicated launch expenditure.
- Autonomous Navigation:Collision avoidance mandates under emerging EU space traffic management rules integrate tracking and maneuver coordination services.
Propulsion Systems holds installed capacity. Reusable Rockets is rotating up the share rankings.
End User:
Customer type determines contract stability, with institutional procurement providing baseline volumes and commercial ventures driving technology refresh cycles.
- Government Agencies:ESA procurement frameworks and coordinated national program allocations through France's CNES, Germany's DLR, and Italy's ASI determine facility investments. These structures provide the most stable demand channel through multi-year program commitments.
- Commercial Enterprises:Venture-backed Earth observation and connectivity ventures in Germany and France narrow the gap with institutional demand. Procurement of orbital transfer services expands as constellation operators seek dedicated mission flexibility.
- Research Institutions:Technology demonstration missions require responsive launch services for experimental payloads.
- Defense Contractors:Secure communications and surveillance requirements sustain demand for dedicated launch capacity outside commercial scheduling constraints.
Government Agencies holds installed capacity. Commercial Enterprises is rotating up the share rankings.
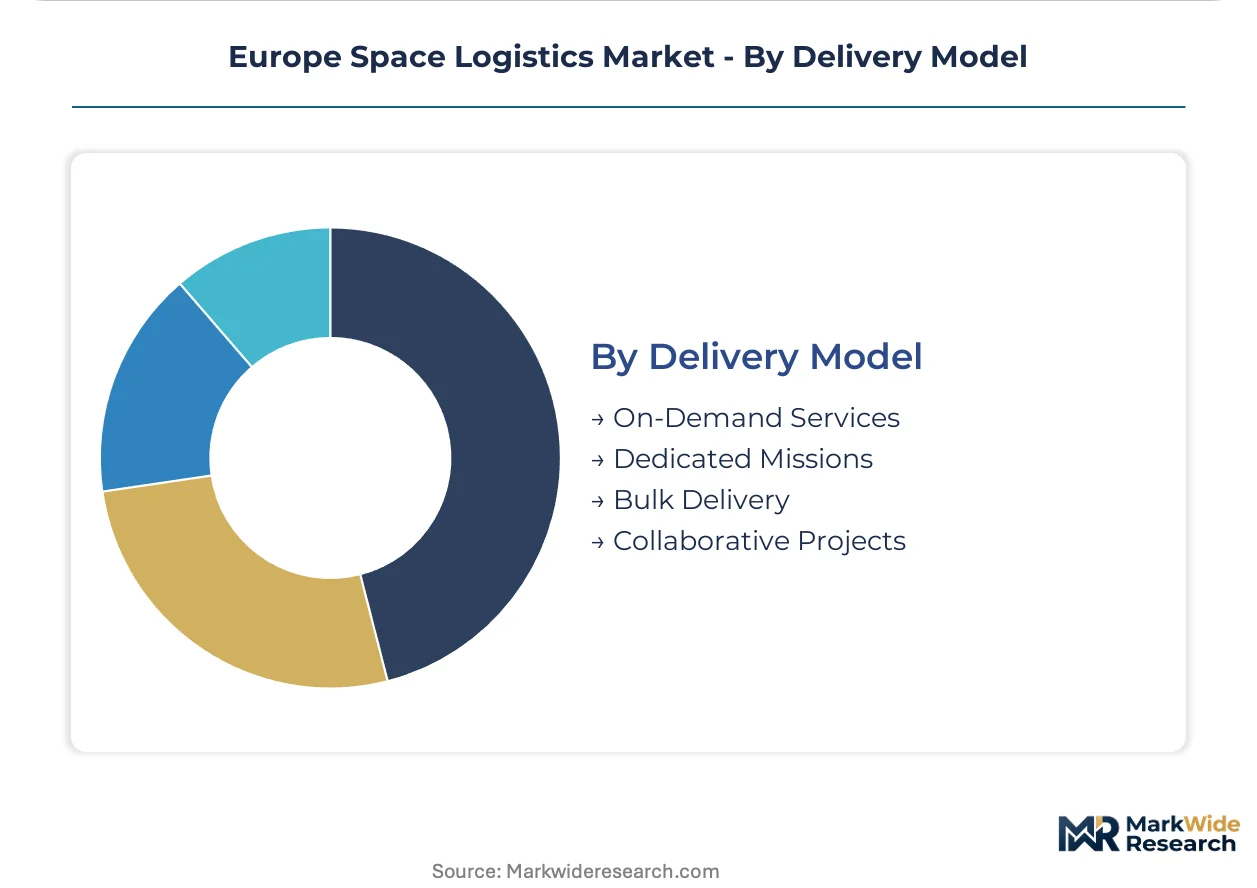
Delivery Model:
Volume concentration favors scheduled missions, while application flexibility drives on-demand premium positioning.
- Dedicated Missions:Single-payload launches from Kourou provide schedule certainty and orbital slot precision for high-value assets. Arianespace anchors European heavy-lift capacity through Ariane 6 operations serving this segment.
- On-Demand Services:Responsive launch capabilities address constellation replenishment urgency and orbital debris mitigation timelines. Italy and Spain present underpenetrated demand for venture-backed operators seeking rapid deployment.
- Bulk Delivery:Rideshare arrangements distribute fixed launch costs across multiple small-satellite operators.
- Collaborative Projects:Multi-national ESA missions pool development costs and facility access across member states.
Dedicated Missions holds installed capacity. On-Demand Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports launch services to commercial satellite operators across Germany, Italy, and Spain through payload integration facilities at Kourou. This trade corridor channels orbital transfer capacity toward constellation operators seeking dedicated mission access.
France
Guiana Space Centre operations anchor European heavy-lift capacity through Ariane 6 missions serving commercial and institutional clients. CNES coordinates national program allocations that determine facility investments and launch scheduling priorities. Kourou's equatorial positioning concentrates payload integration demand for geostationary transfer missions.
Germany
DLR-funded propulsion research drives methane-oxygen engine development for next-generation launch vehicles. EU Green Deal emission benchmarks accelerate technology upgrades across Bremen manufacturing clusters. Small-satellite constellation operators in Bavaria and Baden-Württemberg expand procurement of orbital transfer services.
Italy
ASI coordinates Vega launch vehicle operations serving Earth observation and scientific missions from Kourou. Underpenetrated demand for responsive launch services exists among venture-backed operators in Lazio and Lombardy. Rome-based institutional programs sustain baseline procurement volumes for dedicated mission services.
United Kingdom
Scotland's emerging spaceport infrastructure targets small-satellite launch services for constellation operators. UK Space Agency licensing frameworks shape vehicle qualification requirements for domestic launch activities. Cornwall and Sutherland facilities compete for responsive launch contracts from commercial ventures.
Spain
Andalusia's aerospace manufacturing base supplies propulsion components to European launch programs. INTA research programs de-risk autonomous navigation technologies for orbital servicing applications. Madrid concentrates satellite operator headquarters seeking dedicated launch procurement flexibility.
Europe Space Logistics Market Competitive Landscape
Listed leaders compete with private specialists across vehicle development and payload integration capabilities. The vendor base spans established aerospace primes with captive manufacturing assets and emerging launch providers seeking multi-flight certification. Three archetypes dominate: vertically integrated system houses controlling end-to-end production, specialized propulsion and subsystem suppliers, and venture-backed newcomers pursuing reusable recovery economics. Competitive moves concentrate on strategic partnerships for technology access and capacity expansion at underutilized spaceport sites.
Within the vertically integrated tier, Airbus Defence and Space and Ariane Group occupy positions spanning manufacturing through launch service delivery. Among specialized subsystem providers, OHB SE exemplifies the small-satellite logistics archetype, while Safran SA anchors propulsion component supply. Arianespace represents the established launch services model against which recovery-capable entrants benchmark pricing.
| Leading Market Players |
|---|
| Airbus Defence and Space |
| Arianespace |
| RUAG Space |
| Thales Alenia Space |
| Ariane Group |
| OHB SE |
| Safran SA |
| Avio |
| PLD Space |
| Others |
Value Network & Pricing Analysis
REACH chemical compliance timelines gate both supplier qualification pathways and price differentiation tiers across European space logistics, compressing margins for entrants while rewarding incumbents with pre-certified thermal protection and propellant system portfolios. This regulatory architecture concentrates pricing power among established primes that have absorbed extended CE marking costs, forcing newer vendors to absorb qualification delays or price at substantial discounts to compensate for uncertified status.
Pricing Analysis
Industrial OEM buyers anchor contract structures around multi-year service agreements with performance guarantees for dedicated mission access. Three-tier pricing stratifies across flight-proven recovery systems, developmental reusable architectures, and expendable legacy vehicles, with differentiation driven by certification tier and turnaround reliability. Pricing pressure stems from reusable rocket recovery economics compressing launch cost structures at Kourou and emerging spaceports. Commercial constellation operators exhibit highest price sensitivity due to venture-backed capital constraints, while defense contractors accept premium positioning for schedule certainty outside commercial manifests.
Supply Chain Analysis
Cryogenic propellant production clusters in France and Germany create supply chokepoints for liquid hydrogen replenishment at Guiana Space Centre launch campaigns. The European space logistics supply chain draws from Italian carbon-fiber composite sources, French precision machining corridors, and German propulsion component foundries. Single-source vulnerability concentrates in qualified thermal protection material suppliers subject to REACH authorization delays. Distribution runs through Bremen manufacturing clusters for payload integration, with final assembly and launch operations tethered to Kourou equatorial positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe space logistics exhibits defensive moat characteristics rooted in regulatory entrenchment, where multi-year ESA procurement frameworks and national space agency qualification protocols create switching costs that institutional buyers cannot readily circumvent.
For Market Incumbents: Shield program margins by deepening backward integration into methane-oxygen propulsion component production, capturing value that reusable rocket refurbishment economics would otherwise compress. Accelerate multi-flight certification timelines for thermal protection systems to maintain distance from emerging recovery-capable entrants threatening price positions at Kourou. For New Entrants and Emerging Players: Anchor in underpenetrated responsive launch demand across Italy and Spain, where venture-backed constellation operators seek rapid deployment flexibility absent from scheduled heavy-lift manifests. Pursue white-space positioning in orbital servicing platforms for aging geostationary assets, leveraging rendezvous capabilities as a differentiated entry vector against established launch providers. For Investors and Strategic Acquirers: EU space traffic management rule finalization reshapes the acquisition landscape by mandating collision avoidance infrastructure investments that smaller logistics vendors cannot self-fund. Target specialized propulsion subsystem suppliers with flight-proven methane-oxygen engine architectures positioned for Green Deal compliance premiums. Monitor ESA European Launcher Challenge award announcements as inflection signals for contract redistribution between primes and emerging entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Vehicle Certification Investment | Multi-flight qualification tiers unlock competitive bidding access at CNES-coordinated procurement frameworks. |
| Methane-Oxygen Propulsion Development | EU Green Deal emission benchmarks mandate cleaner-burning engine architectures for new vehicle approvals. |
| Orbital Servicing Platform Deployment | Life extension missions for aging geostationary assets create recurring revenue beyond single-launch economics. |
| Responsive Launch Capacity Buildout | Italy and Spain underpenetration offers first-mover positioning for venture-backed constellation operators. |
| Payload Integration Facility Expansion | Bremen and Kourou manufacturing clusters concentrate margin pools in pre-launch preparation phases. |
Research Methodology
Initial hypotheses were tested against primary input from launch operations directors, satellite procurement managers at constellation operators, ESA program officers, and propulsion subsystem engineers, then refined through secondary validation against ESA procurement databases, CNES annual activity reports, EU space traffic management regulatory filings, and customs records for space-grade material imports. Bottom-up demand modeling across service type and technology segments triangulated against top-down market sizing from national space agency budget allocations.
Variance decomposition across the projection horizon isolates volume drivers by delivery model, end user stability, and technology substitution rates. Segmentation dimensions modeled include service type, propulsion architecture, customer category, and geographic launch site access. CAGRs were derived from fitted growth curves anchored to ESA funding commitments and commercial constellation deployment schedules. Industry-specific forecast inputs incorporate Ariane 6 operational ramp timelines and methane-oxygen engine test program milestones.
Underlying assumptions cover ESA procurement continuity, REACH authorization timelines for green propellant alternatives, and ITU geostationary slot coordination procedures, with deviation risk concentrated in reusable rocket recovery economics maturation and EU space traffic management implementation pace. Practitioners should keep alternative scenarios live as national space agency budget reallocations and emerging launch provider certification progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Ground System Market
Space
Space Wheel Market
Space
Space Management Solutions Market
Space
Space Rover Market
Space
Orbital Spaceflight Market
Space
US Space Launch Services Market
Space
Space Burial Service Market
Space
China Space Electronics Market
Space
Space Debris Monitoring Market
Space
Near Space Robotics Market
Space
Space-Based C4ISR Market
Space
Space Mobile Service Market
Space
UK Space Propulsion System Market
Space
Space Lander and Rover Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Robotics Market