
 Mexico Space Electronics Market | 2026-2036
Mexico Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Space Electronics Market Insights
Modular subsystem packaging is decoupling integrated avionics from proprietary satellite bus architectures, giving Mexican buyers flexibility to mix communication devices with third-party power systems. Lockheed Martin Corporation leverages its vertical integration across satellite platforms to sustain long-term supply relationships with Mexican government programs. Honeywell International Inc. specializes in radiation-hardened sensor modules that anchor critical payload functions for domestic spacecraft integrators. Texas Instruments Incorporated competes through high-reliability analog components that occupy niche positions in launch vehicle instrumentation.
Mexico space electronics encompasses semiconductor devices, subsystems, and assemblies engineered to withstand ionizing radiation, extreme thermal cycling, and vacuum conditions for orbital and deep-space missions. These products typically employ silicon-on-insulator fabrication, triple-module redundancy, and hermetic ceramic packaging to maintain signal integrity across temperature ranges from minus 55 to 125 degrees Celsius. Avionics segments lead current procurement volumes as government satellite programs prioritize command-and-data handling upgrades. Power systems represent the fastest-growing category, driven by solar array regulation and battery management needs for extended LEO missions. Sensors maintain mature demand patterns tied to legacy spacecraft platforms, though margin pools concentrate in hybrid technology implementations combining analog front-ends with digital processing.
Secretaría de Economía industrial policy shapes foreign supplier access through local content requirements and aerospace cluster development incentives. The Agencia Espacial Mexicana coordinates national satellite program procurement standards that align with NASA technical specifications for component qualification. COFEPRIS and NOM standards govern environmental testing protocols for electronics manufactured within Mexican territory. Stakeholders must monitor evolving federal space agency budgets and state-level aerospace incentives to time facility investments and partnership commitments.
Market Dynamics
Modular subsystem packaging is fragmenting satellite procurement decisions across Mexican government programs, allowing spacecraft integrators to mix components from competing suppliers rather than accepting bundled bus architectures from single-source vendors.
Growth Catalysts
- Agencia Espacial Mexicana procurement alignment:Federal satellite programs now require NASA-heritage qualification standards, opening procurement channels for radiation-hardened component suppliers with existing US government contracts.
- Querétaro aerospace cluster incentives:Secretaría de Economía tax abatements and local content credits are drawing foreign subsystem manufacturers to establish Mexican assembly operations for regional satellite programs.
- Silicon-on-insulator fabrication:Advanced semiconductor processes enable Mexican spacecraft integrators to source higher-tolerance components for extended LEO missions without full custom design cycles.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet dependencies for satellite attitude control systems concentrate in Chinese processing facilities, exposing Mexican programs to export restriction risks.
- Hermetic ceramic packaging cost structure:Specialized sealing processes for radiation-hardened components require capital-intensive vacuum furnace infrastructure that few Mexican suppliers possess.
- NOM environmental testing compliance:Mandatory thermal cycling and vibration protocols for electronics manufactured within Mexican territory extend qualification timelines for foreign component suppliers.
Strategic Opportunities
- Baja California manufacturing corridor:Underutilized aerospace infrastructure near Tijuana offers proximity to US defense contractors while maintaining Mexican local content status for federal procurement.
- Solar array regulation electronics:Power management subsystems for extended LEO missions represent an emerging application category where Mexican integrators lack established domestic supplier relationships.
- Secretaría de Economía PLI-style incentives:Proposed federal production-linked subsidies for aerospace component manufacturing would reduce effective capital costs for radiation-hardened assembly facilities.
Industry Challenges
- Radiation effects engineering talent scarcity:Specialized skills for single-event upset analysis and total ionizing dose mitigation remain concentrated in US and European aerospace programs, complicating Mexican workforce development.
- Triple-module redundancy integration complexity:Fault-tolerant computing architectures require system-level verification expertise that Mexican spacecraft integrators must acquire through foreign partnership arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Space Electronics Market |
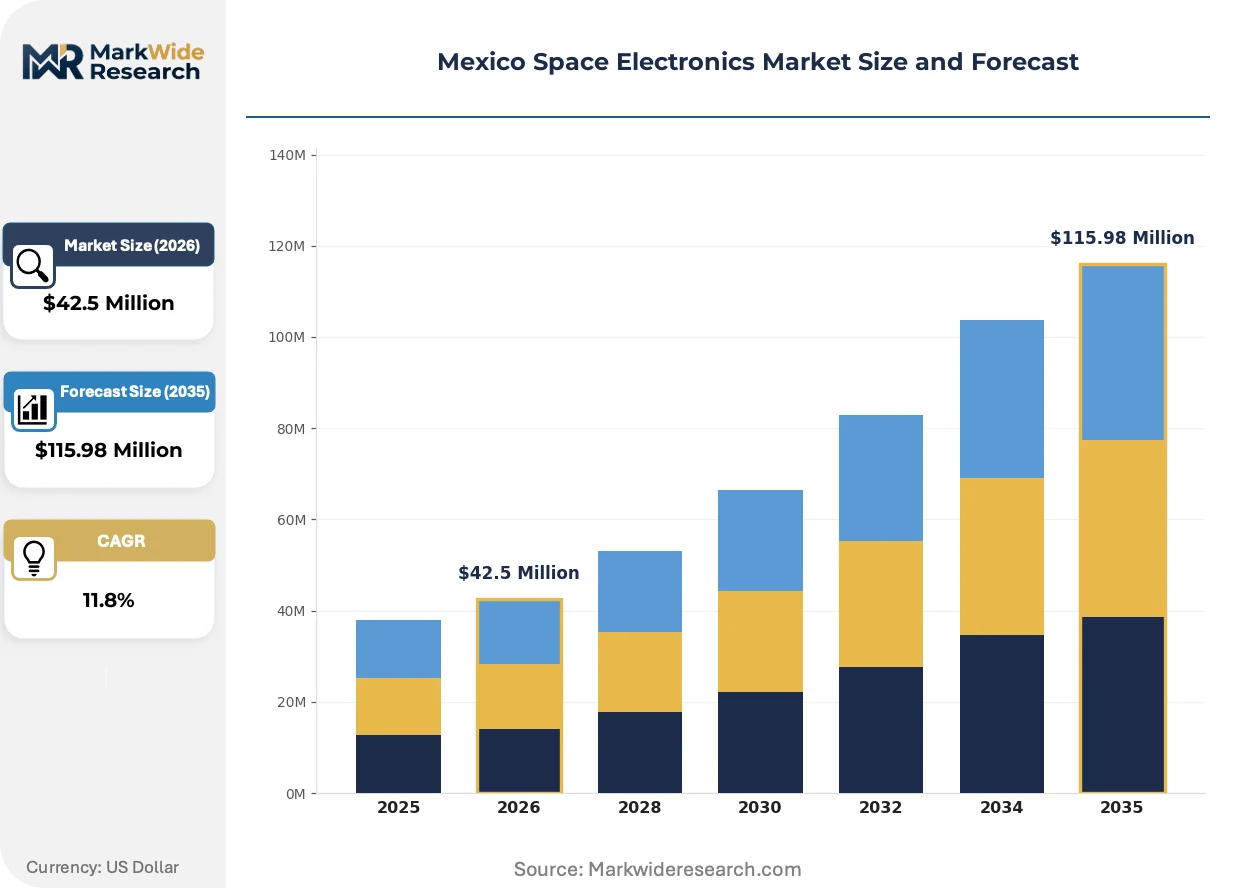
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $115.98 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avionics, Communication Devices, Power Systems, Sensors Technology: Analog, Digital, Hybrid, Microwave Application: Satellite, Launch Vehicle, Ground Station, Spacecraft End User: Government Agencies, Private Companies, Research Institutions, Commercial Providers |
| Companies Covered | Lockheed Martin Corporation, Ball Aerospace, Honeywell International Inc., BAE Systems, Texas Instruments Incorporated, STMicroelectronics, Renesas Electronics Corporation, Infineon Technologies, Microchip Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Space Electronics Market Trends and Innovations
Standardized mechanical and electrical interfaces for satellite subsystems are compressing procurement cycles and enabling component-level competition that was previously locked inside vertically integrated platform contracts.
Modular power distribution architectures are decentralizing spacecraft electrical design decisions away from prime contractors toward payload specialists and subsystem vendors. Mexican government satellite programs are adopting these open standards to accelerate procurement timelines for experimental missions. The shift enables smaller domestic integrators to bid on subsystem contracts without requiring full platform design capabilities.
Secretaría de Economía industrial policy revisions are tightening local content thresholds for aerospace manufacturing incentives, forcing foreign subsystem suppliers to expand Mexican assembly operations or sacrifice federal procurement eligibility. Component vendors with existing Querétaro facilities are absorbing additional manufacturing stages to maintain qualification status. The policy shift most affects power system suppliers seeking access to national satellite programs.
Buyer concentration among federal satellite programs is compressing supplier negotiation leverage and accelerating price transparency across component categories. Mexican spacecraft integrators are consolidating procurement functions and demanding detailed cost breakdowns that were previously treated as proprietary. The behavioral shift is most visible in avionics segments where command-and-data handling upgrades dominate current procurement volumes.
Mexico Space Electronics Market Segmentation
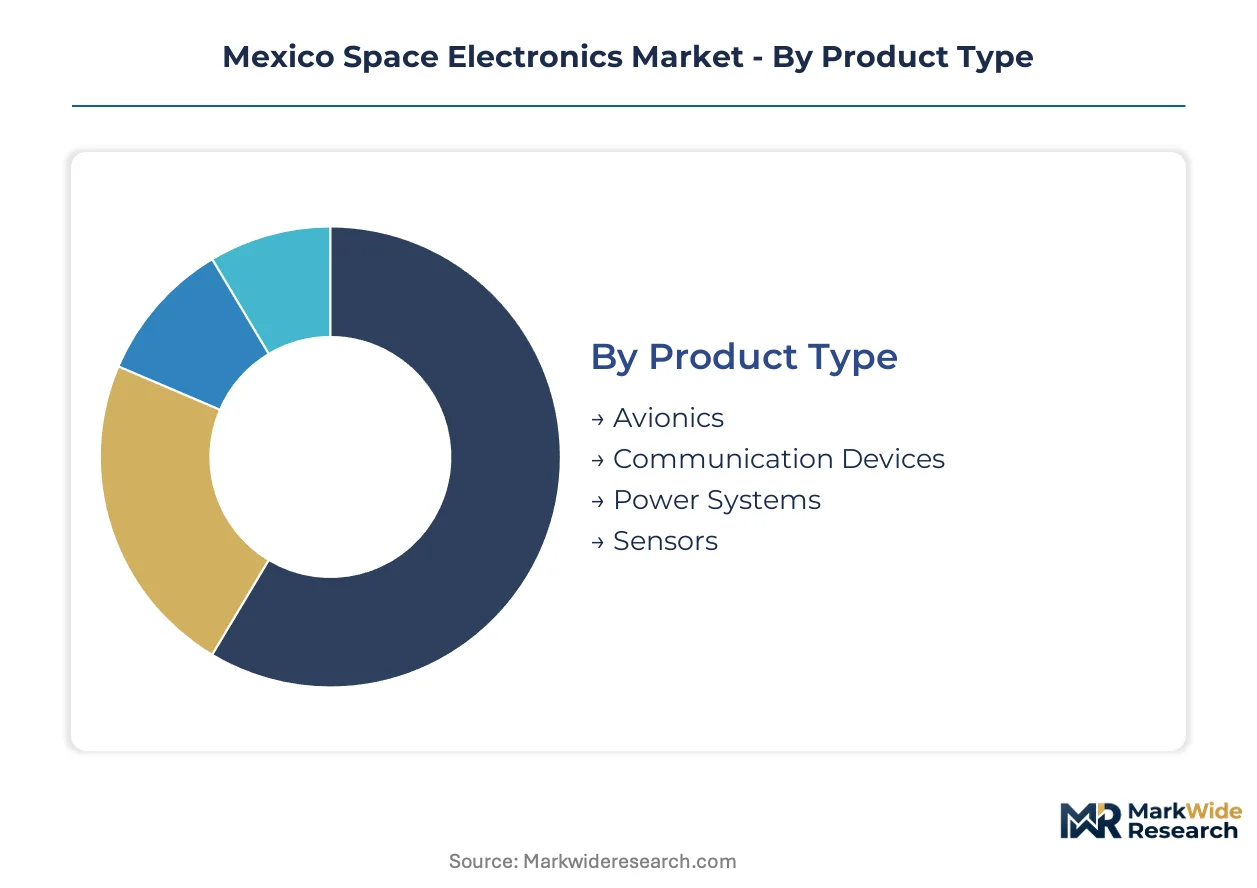
Segmentation in Mexico's space electronics market reveals how procurement decisions fragment across technical specifications, qualification standards, and mission requirements. Government satellite programs drive category concentration while commercial launch activity reshapes volume distribution.
Product Type:
Buyers prioritize radiation tolerance and thermal cycling resilience when selecting components for orbital missions, with qualification heritage determining supplier shortlists.
- Avionics:Command-and-data handling modules employ triple-module redundancy architectures to maintain computational integrity through single-event upset events. Demand concentrates in Agencia Espacial Mexicana satellite upgrades where NASA-heritage qualification standards govern procurement decisions.
- Power Systems:Solar array regulation electronics and battery management subsystems manage energy distribution across extended LEO missions. Procurement tilts toward Querétaro aerospace cluster suppliers seeking local content credits under Secretaría de Economía incentive programs.
- Communication Devices:RF transceivers and antenna control units enable telemetry and payload data downlink.
- Sensors:Radiation-hardened detector arrays support attitude determination and environmental monitoring functions.
Volume sits with Avionics; growth tilts toward Power Systems.
Technology:
Semiconductor fabrication processes determine component reliability margins, with process maturity influencing cost structures for Mexican spacecraft integrators.
- Hybrid:Combining analog front-ends with digital signal processing, hybrid architectures optimize power efficiency for payload-constrained satellites. Mexican government programs favor these implementations for their balance of heritage reliability and functional density.
- Analog:Voltage regulators, operational amplifiers, and sensor interface circuits maintain signal fidelity across extreme temperature swings. Demand clusters in launch vehicle instrumentation where Texas Instruments and Honeywell supply qualified component families.
- Digital:Microprocessors and FPGA implementations enable software-defined payload functions.
- Microwave:High-frequency components support radar and communications subsystems.
Procurement weight rests on Analog; Hybrid implementations gain share fastest.
Application:
Mission duration and radiation exposure levels dictate component grading requirements, with orbital altitude driving specification differentiation.
- Satellite:Bus and payload electronics for LEO, MEO, and GEO platforms require total ionizing dose tolerance ranging from 10 to 100 krad(Si). Agencia Espacial Mexicana procurement concentrates here, with modular subsystem packaging enabling multi-vendor integration strategies.
- Spacecraft:Deep-space probes and interplanetary missions demand the highest reliability grades with extended qualification protocols. Mexican research institutions participate through international consortium arrangements rather than autonomous programs.
- Launch Vehicle:Avionics for propulsion control and telemetry must survive intense vibration and acoustic environments.
- Ground Station:Tracking, telemetry, and command equipment supports mission operations infrastructure.
Revenue concentrates in Satellite applications; Spacecraft missions show steepest expansion trajectory.
End User:
Procurement authority and funding stability shape supplier relationship structures, with federal budget cycles influencing contract timing.
- Government Agencies:Agencia Espacial Mexicana and Secretaría de Defensa Nacional coordinate national satellite programs with centralized procurement functions. These buyers mandate NASA-heritage qualification standards and increasingly require Mexican local content for incentive eligibility.
- Commercial Providers:Emerging private launch and satellite operators seek cost-optimized components with reduced qualification overhead. Baja California manufacturing corridor proximity to US defense contractors attracts these buyers seeking cross-border supply flexibility.
- Private Companies:Telecommunications and Earth observation ventures procure subsystem components.
- Research Institutions:Universities and national laboratories source experimental payload electronics.
Contract value aggregates with Government Agencies; Commercial Providers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's space electronics production concentrates in federally designated aerospace clusters, while domestic consumption flows primarily through government satellite programs and cross-border supply chains serving US defense contractors.
Querétaro
Radiation-hardened component assembly and avionics subsystem integration dominate manufacturing activity here. Secretaría de Economía tax abatements require 35% local content thresholds for federal procurement eligibility, pushing foreign suppliers to expand Mexican operations. The Querétaro Aerospace Cluster now hosts subsystem packaging facilities from multiple US and European vendors seeking qualification for Agencia Espacial Mexicana contracts.
Baja California
Proximity to San Diego defense contractors drives cross-border supply chain integration for launch vehicle instrumentation. The Tijuana-Tecate corridor offers underutilized aerospace infrastructure with dual US-Mexico market access. COFEPRIS environmental testing protocols apply to electronics manufactured here, though streamlined NOM certification pathways exist for facilities serving both national satellite programs and US commercial launch operators.
Nuevo León
Monterrey's advanced manufacturing base attracts power system suppliers targeting solar array regulation electronics. State-level economic development incentives complement federal aerospace cluster programs. Local universities partner with foreign subsystem vendors to address radiation effects engineering talent scarcity through specialized graduate curricula.
Mexico City Metro
Agencia Espacial Mexicana headquarters and Secretaría de Defensa Nacional procurement functions centralize demand authority here. Policy coordination between federal space agency budgets and state-level aerospace incentives occurs through intergovernmental committees. Research institutions in the metropolitan area participate in international consortium arrangements for deep-space mission electronics.
Mexico Space Electronics Market Competitive Landscape
The competitive structure tilts toward vertically integrated platform vendors with established NASA-heritage qualification credentials. Three archetypes dominate: US defense primes leveraging satellite bus integration capabilities, European semiconductor specialists with radiation-hardened component portfolios, and Japanese electronics conglomerates supplying high-reliability analog devices. Competitive moves concentrate on strategic partnerships with Mexican spacecraft integrators and geographic expansion into federally incentivized manufacturing clusters.
Among US-based platform integrators, Lockheed Martin Corporation and Honeywell International Inc. occupy positions shaped by long-term supply relationships with Mexican government programs. Texas Instruments Incorporated exemplifies the component-level specialist archetype, anchoring niche positions in launch vehicle instrumentation through high-reliability analog families. These three names represent the spectrum from full-platform integration to discrete component supply.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Ball Aerospace |
| Honeywell International Inc. |
| BAE Systems |
| Texas Instruments Incorporated |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Infineon Technologies |
| Microchip Technology |
| Others |
Pricing and Supply Chain Analysis
Rare earth oxide price indices from Chinese processing facilities cascade through Mexican satellite procurement tiers, with neodymium and dysprosium cost volatility compressing margins for attitude control subsystem vendors while amplifying price differentiation between NASA-heritage qualified suppliers and commercial-grade alternatives.
Pricing Analysis
Margin tightening in radiation-hardened component tiers reflects hermetic ceramic packaging bottlenecks and vacuum furnace infrastructure scarcity. Three-tier pricing structure across NASA-heritage qualified, dual-use commercial, and unscreened industrial grades separates buyers by mission criticality. Cost-down pressure on power system subassemblies accelerates because Secretaría de Economía local content thresholds force foreign suppliers to absorb Mexican assembly overhead. Commercial launch operators exhibit highest price sensitivity, while Agencia Espacial Mexicana satellite programs prioritize qualification heritage over unit economics.
Supply Chain Analysis
NASA-heritage qualification gating restricts component sourcing to US, European, and Japanese fabricators with proven radiation tolerance track records. Supply chains draw from silicon-on-insulator wafer foundries in the United States, hermetic packaging specialists in Germany and France, and rare earth magnet processors concentrated in China. Single-source vulnerability pervades Chinese rare earth refining capacity, exposing Mexican programs to export restriction cascades. Distribution runs through Querétaro aerospace cluster facilities for federal procurement eligibility, with Baja California corridor serving cross-border commercial launch demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hermetic ceramic packaging furnace capacity scarcity props pricing power for qualified vendors, constraining Mexican government satellite program procurement timelines and amplifying returns for incumbent subsystem suppliers with certified in-house sealing operations.
For Market Incumbents: Acquire radiation effects engineering talent pools through targeted recruitment from US aerospace programs and European space agencies. Lockheed Martin Corporation and Honeywell International Inc. should deepen backward integration into silicon-on-insulator wafer supply through captive foundry arrangements or long-term offtake commitments with US fabricators, defending against emerging European semiconductor specialists seeking Mexican federal contracts. For New Entrants and Emerging Players: Capture solar array regulation electronics white space where Mexican integrators lack established domestic supplier relationships. Target Baja California manufacturing corridor for dual US-Mexico market access, leveraging streamlined NOM certification pathways for facilities serving commercial launch operators. Lead with modular subsystem packaging expertise to bypass vertically integrated platform vendor lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor radiation-hardened analog component specialists with existing COFEPRIS environmental testing protocols in Querétaro. Long-term viability hinges on Agencia Espacial Mexicana budget trajectory and Secretaría de Economía PLI-style incentive implementation. Watch federal production-linked subsidy announcements as inflection signals for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardened Assembly Facility Establishment | Secretaría de Economía tax abatements reduce effective capital costs for Querétaro cluster entry. |
| Silicon-on-Insulator Foundry Partnership | Texas Instruments and STMicroelectronics anchor supply security for extended LEO mission components. |
| Rare Earth Magnet Supply Diversification | Australian and Vietnamese processing alternatives mitigate Chinese export restriction exposure for attitude control systems. |
| Triple-Module Redesign Integration Service | Mexican spacecraft integrators acquire fault-tolerant computing expertise through foreign partnership arrangements. |
| NOM Environmental Testing Certification | COFEPRIS thermal cycling protocol compliance accelerates qualification timelines for federal procurement eligibility. |
Research Methodology
Agencia Espacial Mexicana procurement disclosures, Secretaría de Economía industrial policy filings, and NASA technical specification documents formed the secondary backbone, supplemented by customs records tracking radiation-hardened component imports. Primary interviews with spacecraft integration engineers, federal procurement officers, radiation effects specialists, and Querétaro aerospace cluster facility managers combined with secondary validation. Bottom-up and top-down triangulation cross-checked subsystem vendor revenue estimates against federal satellite program budget allocations.
Bottom-up modeling aggregated individual component categories across avionics, power systems, communication devices, and sensors, while top-down analysis calibrated aggregate market trajectory against aerospace manufacturing incentive uptake. Segmentation dimensions included product type, semiconductor fabrication technology, orbital application tier, and end-user procurement authority. CAGRs derived from fitted growth curves incorporating silicon-on-insulator process adoption rates and local content threshold policy evolution across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Agencia Espacial Mexicana budget continuity and rare earth supply chain disruption severity. Forecasts reflect documented assumptions regarding federal incentive program implementation timelines and NASA-heritage qualification standard persistence. A model refresh is warranted upon material change in Secretaría de Economía local content threshold adjustments or Chinese rare earth export policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Propulsion Systems Market
Space
Space Service Market
Space
North America Spacesuit Market
Space
Space Debris Monitoring Market
Space
Space Ground System Market
Space
Deep Space Robotics Market
Space
Space Travel Market
Space
Space Colonization Market
Space
Space Robots Market
Space
Spain Space Electronics Market
Space
Space Sensors Market
Space
China Space Electronics Market
Space
Carrier Rocket Market
Space
Space Wheel Market
Space
US Space Electronics Market
Space
Space Lander and Rover Market