
 Drone Battery System Market | 2026-2036
Drone Battery System Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Battery System Market Analysis
Buyer concentration among defense contractors and large logistics operators is hardening as multi-year fleet contracts replace spot procurement. Shenzhen Grepow Battery Co., Ltd. anchors high-volume supply to Asia-Pacific drone manufacturers through its lithium polymer cell production. EaglePicher Technologies leverages its defense heritage to sustain qualification-heavy military programs. Intelligent Energy Limited specializes in hydrogen fuel cell hybrid systems for extended-endurance applications.
A drone battery system comprises electrochemical cells, battery management circuitry, thermal regulation hardware, and enclosure structures engineered to deliver specific energy density exceeding 200 Wh/kg for flight-critical applications. These systems power propulsion motors, avionics, and payload systems across commercial, military, and industrial unmanned aerial vehicles. Lithium polymer dominates current production due to its form-factor flexibility and discharge rate tolerance, though fast charging technology is capturing investment as turnaround time becomes a competitive variable in delivery services. Small scale capacity segments serve consumer and light commercial drones, while high capacity configurations command premium positioning in heavy-lift and long-endurance military platforms.
FAA airworthiness standards for unmanned systems, EU REACH chemical restrictions on battery materials, and China's GB standards for lithium-ion transportation safety collectively shape product design cycles and market access conditions. The EU AI Act's emerging classification framework for autonomous flight systems will extend compliance burdens to battery-integrated power management architectures. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded certification investments.
Market Dynamics
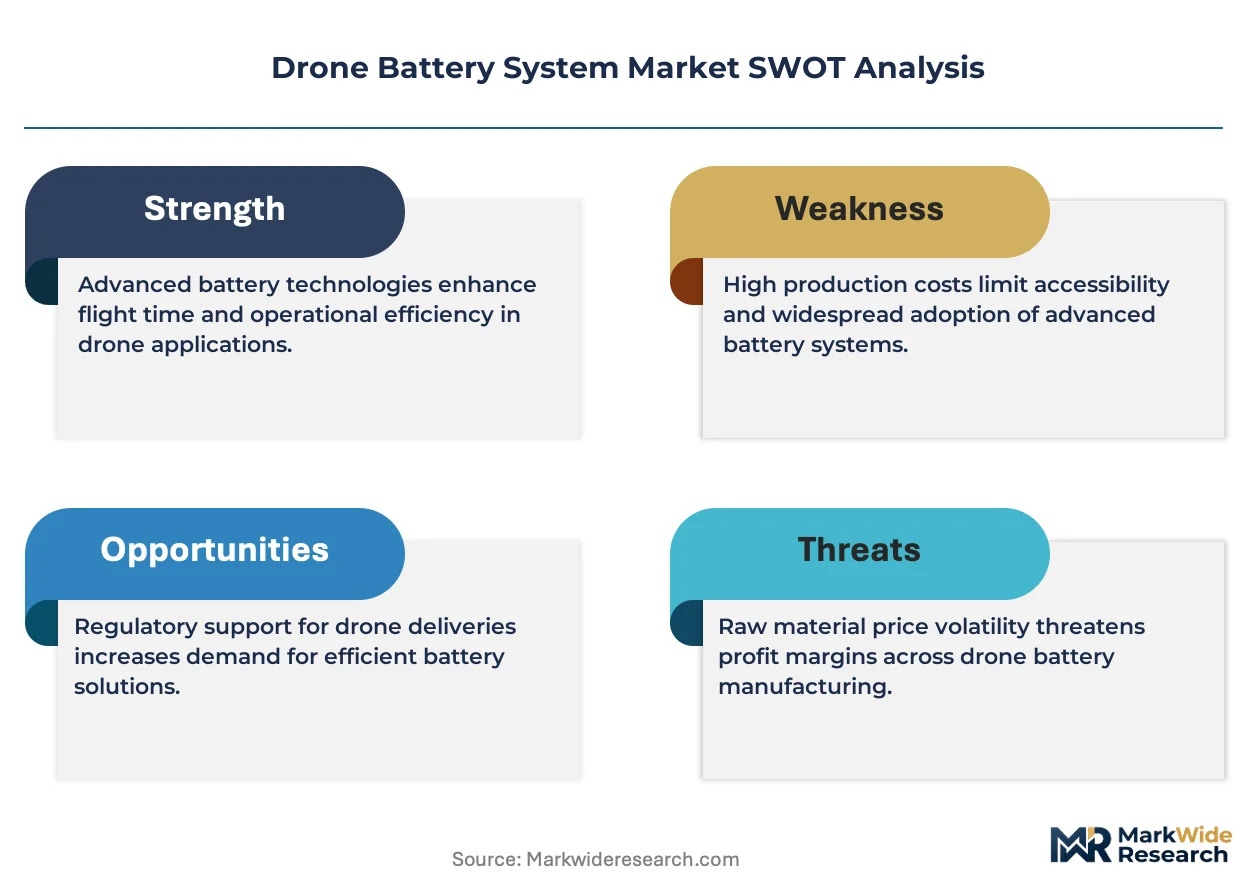
Solid-state electrolyte research is converging with defense electrification mandates to compress development timelines and reshape supplier qualification hierarchies. Military procurement programs now require specific energy densities exceeding 300 Wh/kg, forcing incumbent lithium polymer manufacturers to accelerate R&D partnerships or face disqualification from next-generation platform bids.
Growth Catalysts
- Fleet Electrification Mandates:Defense procurement programs in the United States and China now specify battery-electric propulsion for tactical unmanned systems, creating guaranteed offtake for qualified suppliers.
- Shenzhen Manufacturing Cluster:China's concentrated battery production infrastructure feeds domestic drone OEMs and export markets with lithium polymer cells at scale, reducing unit costs through shared component ecosystems.
- Fast Charging Infrastructure:Last-mile delivery operators are deploying rapid-swap battery stations, compressing turnaround times from hours to minutes and expanding flight-cycle economics for commercial fleets.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material cost swings in the Democratic Republic of Congo and Chilean salars destabilize cell pricing and force hedging costs onto battery pack integrators.
- Supply Concentration Risk:Separator membrane production concentrates in Japanese and South Korean chemical conglomerates, creating single-source vulnerabilities for non-integrated pack assemblers.
- Thermal Runaway Limitations:Conventional lithium-ion architectures face inherent safety ceilings that restrict energy density scaling without fundamental chemistry changes.
Strategic Opportunities
- Hydrogen Fuel Cell Hybrids:Extended-endurance military surveillance platforms are integrating proton exchange membrane stacks with lithium buffers, opening qualification pathways for fuel cell specialists.
- EU Green Deal Battery Passport Requirements:Traceability mandates create first-mover advantages for manufacturers with embedded supply chain visibility software.
- India Defense Indigenization:The country's PLI scheme for advanced chemistry cells offers tariff protection and production-linked incentives for local pack assembly operations.
Industry Challenges
- Electrolyte Formulation Expertise Gap:Solid-state development requires polymer chemistry and ceramic processing skills scarce in conventional lithium-ion engineering teams.
- FAA Airworthiness Certification Timelines:Type certification for novel battery architectures stretches 18-36 months, freezing product roadmaps and consuming capital without revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Battery System Market |
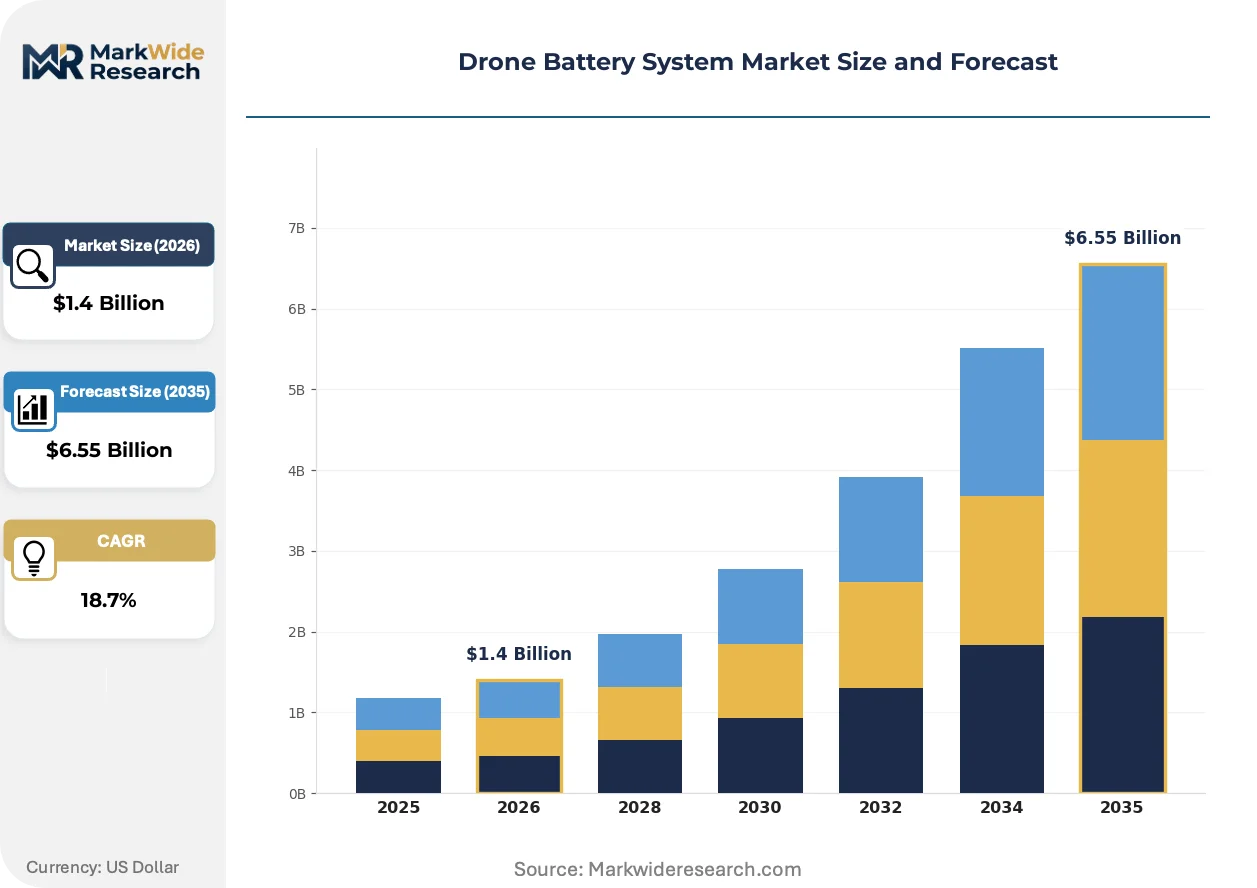
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Polymer, Lithium Ion, Nickel Cadmium, Lead Acid Technology: Fast Charging, Wireless Charging, Ultra-Fast Charging, Solar Charging End User: Agriculture, Military, Delivery Services, Entertainment Capacity: Small Scale, Medium Scale, Large Scale, High Capacity |
| Companies Covered | EaglePicher Technologies, Shenzhen Grepow Battery Co., Ltd., RRC Power Solutions GmbH, Plug Power Inc., Doosan Mobility Innovation, Intelligent Energy Limited, SES AI Corporation, H3 Dynamics, Oxis Energy Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Battery System Market Emerging Trajectories
Solid-state battery architectures are converging with silicon-anode designs to redefine energy density benchmarks across defense and commercial platforms. Three interconnected developments are compressing traditional technology adoption curves.
Solid-state electrolytes replace flammable liquid separators with ceramic or sulfide compounds, enabling higher voltage operation and reduced thermal management overhead. Defense contractors in the United States and Israel are qualifying solid-state packs for extended-range tactical systems, accepting premium unit costs for mission-critical reliability. This technology is converging with autonomous flight control systems to enable longer-duration missions without pilot intervention or battery swap infrastructure.
The EU AI Act's risk classification framework extends compliance obligations to battery-integrated power management systems in autonomous drones. Manufacturers must now document algorithmic decision-making in charge-state estimation and thermal regulation as part of conformity assessment. European commercial operators face the steepest adaptation costs, with German and French integrators restructuring supply agreements to capture algorithm audit trails from cell suppliers.
Multi-year fleet service contracts are displacing spot procurement across logistics and agricultural spraying operators. Large drone deployers in Brazil and Australia now negotiate bundled battery replacement schedules with performance guarantees, transferring degradation risk to pack manufacturers. Agricultural cooperatives in Australia's wheat belt pioneered this shift, with terms now spreading to Southeast Asian plantation operators seeking predictable operating expenditure structures.
Drone Battery System Market Segmentation
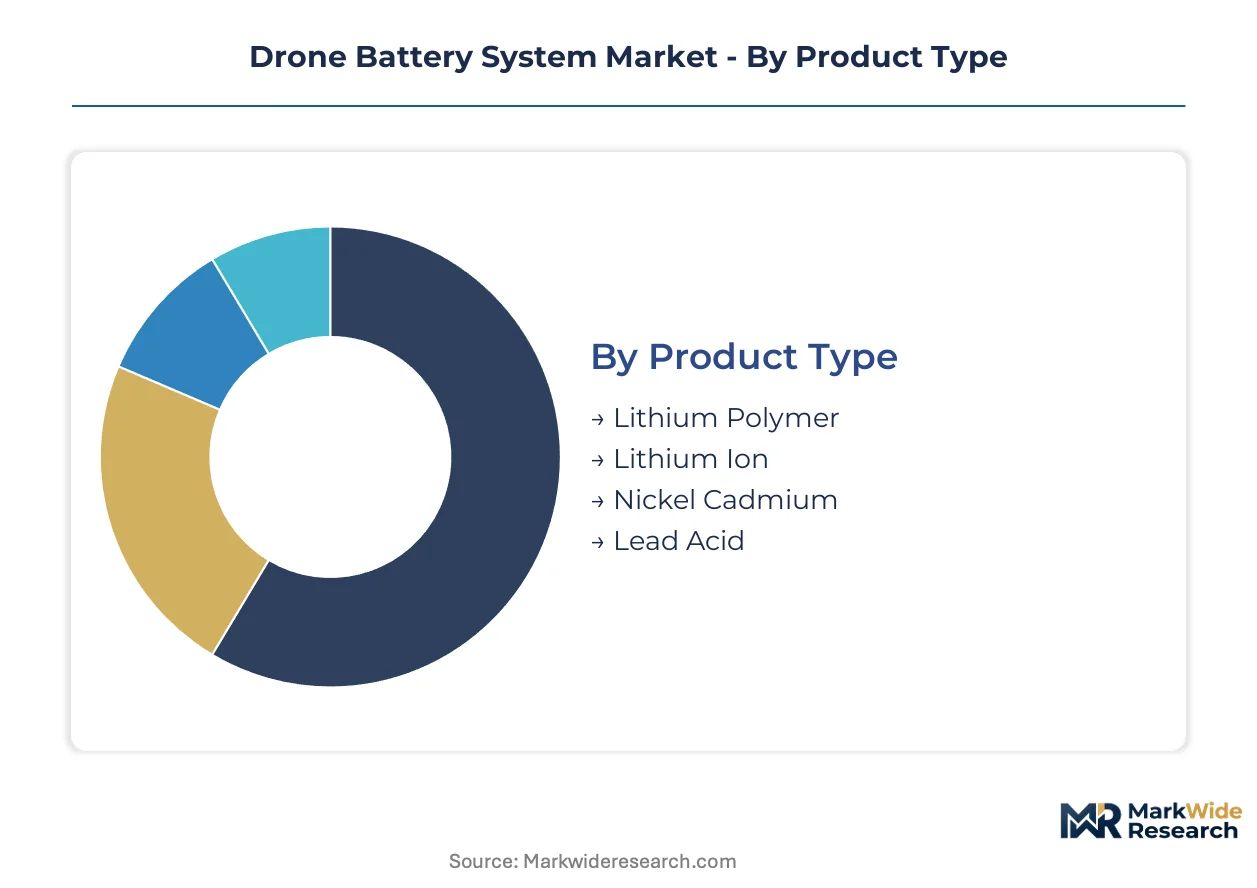
Drone battery system procurement varies sharply by application risk profile, with FAA airworthiness certification required for military platforms and commercial delivery fleets while consumer segments face lighter conformity burdens. Segment-specific chemistry choices and charging architectures directly determine qualification timelines, supplier eligibility, and pricing power across the value chain.
Product Type:
FAA type certification applies differentially across chemistries, with lithium polymer packs requiring extensive thermal runaway testing while nickel cadmium faces REACH substance restrictions in European markets.
- Lithium Polymer:Thin-film pouch cells with gel electrolyte enable conformal geometries fitting compact drone airframes. Demand clusters in Shenzhen's export manufacturing corridor for consumer and light commercial UAVs, where form-factor flexibility outweighs energy density limitations. FAA airworthiness timelines stretch 18-24 months for new pack designs.
- Lithium Ion:Cylindrical 18650 and 21700 formats deliver superior cycle life for heavy-lift platforms. Defense contractors in the United States specify these for tactical systems requiring 500+ charge cycles, with qualification protocols mandating nail penetration and crush testing per MIL-STD-810.
- Nickel Cadmium:Legacy chemistry persists in temperature-extreme military applications where proven reliability trumps energy density penalties.
- Lead Acid:Stationary ground support equipment and charging station backup power represent the sole viable demand pocket.
Leading the category by volume: Lithium Polymer. Growing fastest: Lithium Ion.
Technology:
Charging speed tiers segment procurement budgets, with ultra-fast infrastructure commanding 3-4x pack premiums over standard systems and reshaping fleet operator capital allocation.
- Fast Charging:2-4C charge rates enable 30-minute turnaround for agricultural spraying fleets. Brazilian soybean cooperatives deploy these systems during narrow application windows, prioritizing aircraft utilization over battery longevity.
- Ultra-Fast Charging:6C+ rates with active liquid cooling support continuous-loop delivery operations. Last-mile operators in Singapore and Dubai accept accelerated cell degradation for sub-15-minute swaps, treating batteries as consumables rather than assets.
- Wireless Charging:Inductive pads reduce connector wear in dusty agricultural environments and enable autonomous landing precision.
- Solar Charging:Extended-endurance surveillance platforms integrate photovoltaic top covers for trickle charging during loiter missions.
Ultra-fast systems claim the steepest expansion trajectory as delivery economics tighten. Fast charging retains the largest installed base.
End User:
Military procurement operates through multi-year indefinite-delivery contracts with cost-plus fee structures, while commercial segments favor spot purchasing or leased battery-as-a-service arrangements.
- Military:Electrification mandates in United States and Chinese defense programs specify 300 Wh/kg minimum energy density. Israel Aerospace Industries and Northrop Grumman qualify solid-state prototypes for extended-range tactical ISR platforms, accepting 40% unit cost premiums for reduced thermal signatures.
- Delivery Services:Amazon Prime Air and Zipline operate captive battery swap networks with predictive degradation analytics. FAA Part 135 certification for beyond-visual-line-of-sight flight requires documented battery state-of-health monitoring.
- Agriculture:Australian wheat belt cooperatives pioneered performance-guaranteed replacement schedules, now spreading to Indonesian palm oil plantations.
- Entertainment:Light-show drone swarms prioritize weight minimization and rapid field charging over cycle life.
Military programs anchor supplier margins through qualification-heavy procurement. Delivery services are gaining share fastest as regulatory frameworks mature.
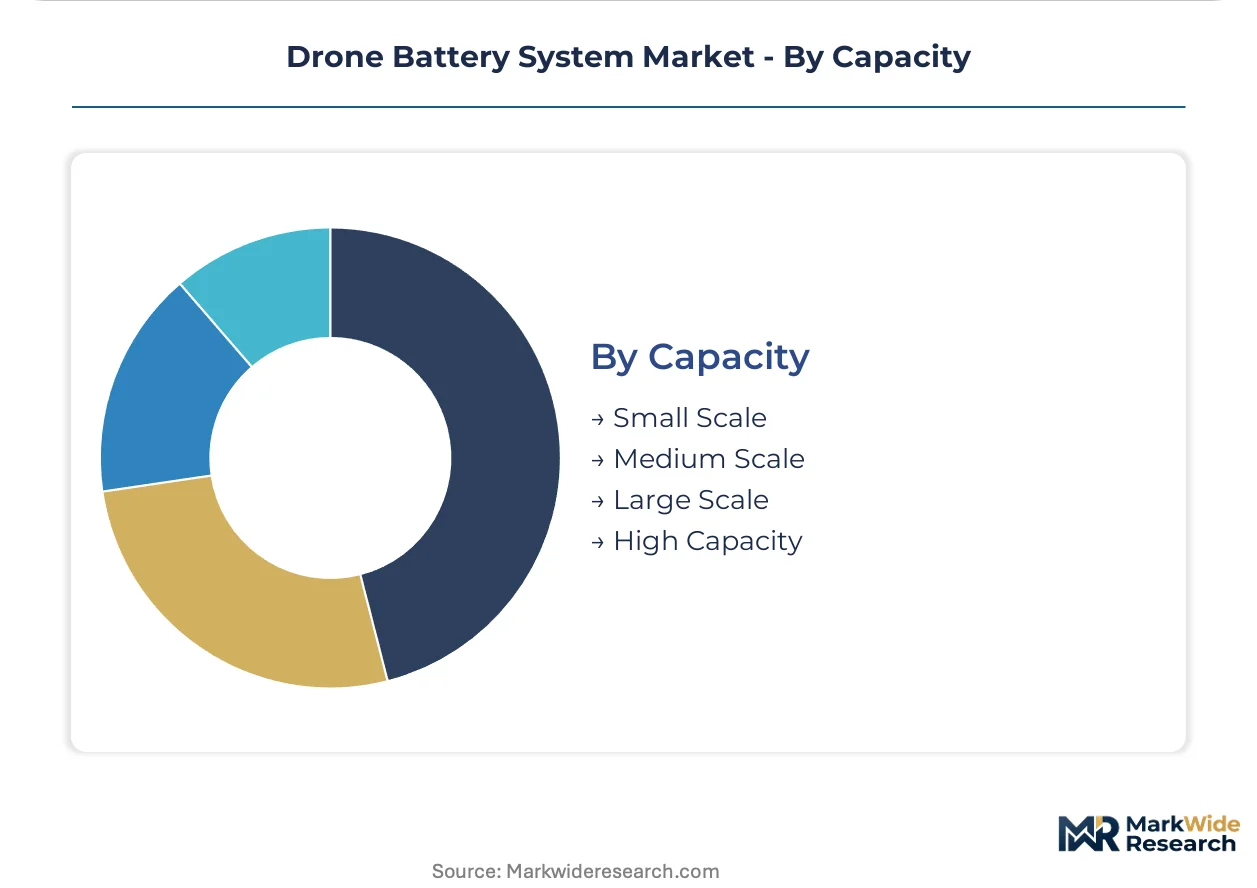
Capacity:
Scale thresholds determine pack architecture complexity, with high capacity systems requiring active thermal management and redundant battery management circuitry that smaller formats omit.
- High Capacity:Exceeding 20 kWh configurations power heavy-lift cargo drones and long-endurance surveillance platforms. Defense applications in the United States mandate distributed pack architectures with cell-level fusing to contain thermal propagation.
- Large Scale:5-20 kWh range serves agricultural sprayers and regional delivery UAVs. China's GB standards for lithium-ion transportation safety impose strict state-of-charge limits on these packs during ground transit.
- Medium Scale:1-5 kWh dominates commercial inspection and mapping drones.
- Small Scale:Sub-1 kWh formats power consumer racing drones and toy segments.
High capacity packs command premium positioning through defense and heavy-lift commercial demand. Large scale formats are expanding most quickly as agricultural fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electrification programs and commercial delivery networks concentrate procurement power across four distinct national markets, each with divergent regulatory frameworks and supplier qualification requirements.
United States
FAA Part 135 certification mandates for beyond-visual-line-of-sight operations drive battery pack documentation standards. The Inflation Reduction Act's domestic content incentives reshape supplier sourcing for defense contractors. California's aerospace corridor hosts qualification laboratories serving Northrop Grumman and other primes testing solid-state prototypes.
China
Shenzhen's manufacturing cluster feeds domestic drone OEMs and export markets with lithium polymer cells at scale. GB standards for lithium-ion transportation safety impose strict state-of-charge limits during ground transit. The Pearl River Delta's integrated supply chain reduces unit costs through shared component ecosystems across battery pack assemblers.
Germany
EU AI Act compliance obligations extend to battery-integrated power management systems in autonomous drones. REACH chemical restrictions on cobalt and nickel formulations limit cathode material sourcing options. Bavaria's industrial automation sector develops predictive degradation analytics for agricultural fleet operators.
Israel
Defense procurement programs specify 300 Wh/kg minimum energy density for extended-range tactical ISR platforms. The national regulator mandates thermal runaway containment testing for military pack architectures. Tel Aviv's defense technology corridor hosts qualification programs for solid-state electrolyte prototypes.
Australia
Agricultural cooperatives in the wheat belt pioneered performance-guaranteed battery replacement schedules with pack manufacturers. The TGA-equivalent aviation safety framework governs commercial drone operations across rural spraying networks. Queensland's plantation operators now adopt these contract structures for predictable operating expenditure.
Drone Battery System Market Vendor Landscape
Shenzhen-based producers anchor one tier; defense heritage specialists hold qualification-heavy positions in military procurement. The vendor base splits between high-volume lithium polymer fabricators and solid-state technology developers. Three strategic archetypes dominate: integrated cell-to-pack manufacturers, fuel cell hybrid specialists, and qualification-focused defense contractors. Competitive moves center on R&D partnerships with solid-state electrolyte developers and captive supply agreements with raw material processors.
Within the defense-contractor archetype, EaglePicher Technologies occupies a position tied to military qualification protocols. Shenzhen Grepow Battery Co., Ltd. exemplifies the high-volume manufacturing tier serving commercial drone OEMs. Intelligent Energy Limited represents the fuel cell hybrid specialization for extended-endurance applications.
| Leading Market Players |
|---|
| EaglePicher Technologies |
| Shenzhen Grepow Battery Co., Ltd. |
| RRC Power Solutions GmbH |
| Plug Power Inc. |
| Doosan Mobility Innovation |
| Intelligent Energy Limited |
| SES AI Corporation |
| H3 Dynamics |
| Oxis Energy Ltd |
| Others |
Supply Flow & Price Mechanics
Defense procurement programs and large logistics operators concentrate buying power through multi-year fleet contracts, anchoring contract-based long-term offtake as the dominant pricing model across military and commercial tiers. Pricing stratifies across qualification-heavy defense packs, performance-guaranteed commercial bundles, and spot-market consumer cells, with FAA airworthiness certification and raw material hedging costs driving tier separation.
Pricing Analysis
Volume concentrates in Shenzhen-exported lithium polymer cells serving consumer and light commercial OEMs, while margins accrue to qualification-heavy military packs meeting MIL-STD-810 thermal runaway protocols. Price differentiation hinges on certification grade—FAA Part 135 airworthiness versus CE self-declaration—and volume scale, with agricultural cooperatives negotiating performance-guaranteed replacement schedules. Cost compression in high-volume consumer tiers is intensifying because Shenzhen's manufacturing cluster feeds oversupply into export markets. Delivery services exhibit highest price sensitivity, treating batteries as consumables in sub-15-minute swap operations; defense contractors show lowest sensitivity, accepting 40% premiums for solid-state reliability.
Supply Chain Analysis
Reverse-logistics flows for degraded agricultural and delivery fleet batteries are emerging as a structural cost center, with Australian cooperatives pioneering performance-guaranteed replacement schedules that shift degradation risk upstream to pack manufacturers. Geographic supply concentration centers on China's Pearl River Delta for cell fabrication, South Korea and Japan for separator membranes, and Chile and the Democratic Republic of Congo for lithium and cobalt feedstocks. Raw material dependencies rest on ceramic electrolyte precursors, sulfide compounds for solid-state development, and high-purity lithium carbonate. Single-source vulnerability in Japanese and South Korean separator membrane production creates qualification bottlenecks for non-integrated pack assemblers. Distribution runs through defense prime contractor qualification programs, commercial fleet operator captive swap networks, and Shenzhen-based OEM export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drone battery system market is becoming a vertical-integration race, with players pursuing captive supply agreements with Chilean and Congolese raw material processors to lock in lithium and cobalt offtake ahead of solid-state chemistry transitions.
For Market Incumbents: To counter solid-state electrolyte developers displacing conventional lithium polymer architectures, accelerate R&D partnerships with ceramic processing specialists and secure backward integration into separator membrane production. Add qualification capacity in California's aerospace corridor to compress FAA Part 135 certification timelines for next-generation pack designs. For New Entrants and Emerging Players: Launch via battery-as-a-service leasing models targeting Indian defense indigenization programs under the PLI scheme for advanced chemistry cells. Agricultural cooperatives in Southeast Asian plantation operations represent the most penetrable segment, with performance-guaranteed replacement schedules offering predictable revenue streams absent in spot procurement markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor fuel cell hybrid specialists with proton exchange membrane stack expertise in Israel and the United States, where defense electrification mandates guarantee offtake. Long-term viability across the projection horizon hinges on qualification heritage transferable to solid-state architectures. Monitor FAA airworthiness certification queue lengths for novel battery architectures as an inflection indicator for incumbent R&D productivity.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Partnership | Qualification with Israel Aerospace Industries accelerates defense platform integration timelines. |
| Raw Material Captive Supply Agreement | Direct offtake from Chilean salars reduces lithium carbonate price volatility exposure. |
| Battery-as-a-Service Platform Launch | Australian agricultural cooperative contracts demonstrate predictable operating expenditure capture. |
| Fast Charging Infrastructure Deployment | Singapore last-mile operator networks validate sub-15-minute swap economics. |
| EU Battery Passport Compliance Investment | Embedded supply chain visibility software captures first-mover advantage under Green Deal traceability mandates. |
Methodological Framework
Multi-period observation of defense electrification procurement timelines, solid-state chemistry development milestones, and commercial fleet operator swap network deployments anchored the trend analysis, supplemented by interviews with battery pack engineering directors, defense procurement officers, agricultural fleet operations managers, and FAA certification specialists. Secondary validation drew from FAA Part 135 certification databases, MIL-STD-810 test protocols, EU AI Act draft guidance on autonomous system power management, and Shenzhen customs export records for lithium polymer cells. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Input-output matrix modeling connected raw material flow assumptions through cell fabrication capacity to pack assembly output across product type, technology, end user, and capacity segmentation dimensions. CAGRs were derived from segment-level demand elasticity estimates and substitution curve analysis for solid-state versus lithium polymer architectures. Forecast inputs included defense procurement program schedule acceleration risks and commercial delivery fleet electrification commitment trajectories.
Regulatory divergence between FAA, EASA, and China's GB standards, solid-state electrolyte formulation breakthrough delays, and cobalt supply disruptions from the Democratic Republic of Congo are the dominant revision risks. Forecasts reflect documented assumptions regarding qualification timeline compression and fleet operator contract structure adoption rates. Practitioners should monitor defense procurement program specification releases and solid-state prototype field test results for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Bomb Disposal Robot Market