
 South Korea Space Electronics Market | 2026-2036
South Korea Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Space Electronics Market Insights
South Korea's carbon-neutral satellite manufacturing roadmap is broadening procurement criteria for radiation-hardened components. Hanwha Aerospace leverages in-house foundry partnerships to secure domestic supply chains for power conditioning modules. LIG Nex1 anchors defense-to-space crossover programs, while Satrec Initiative specializes in compact satellite bus integration for commercial constellations.
South Korea space electronics encompasses semiconductor devices, subsystems, and integrated assemblies engineered to withstand ionizing radiation, thermal cycling, and vacuum conditions across orbital and deep-space missions. These components typically operate across temperature ranges from minus 55 degrees Celsius to 125 degrees Celsius with total ionizing dose tolerance exceeding 100 kilorads for geostationary applications. Communication Systems dominate procurement volumes as low Earth orbit broadband constellations expand ground-to-satellite bandwidth requirements. AI Hardware represents the fastest-expanding technology segment as on-board edge processing reduces downlink dependency for earth observation payloads.
MFDS standards for component traceability, KARI technical specifications for launch vehicle avionics, and Ministry of National Defense encryption mandates collectively shape supplier qualification pathways. The national space authority tightens radiation testing protocols while defense procurement rules extend cybersecurity requirements to commercial satellite operators. Stakeholders must track how domestic foundry capacity for gallium nitride and silicon carbide devices aligns with sovereign launch schedules.
Market Dynamics
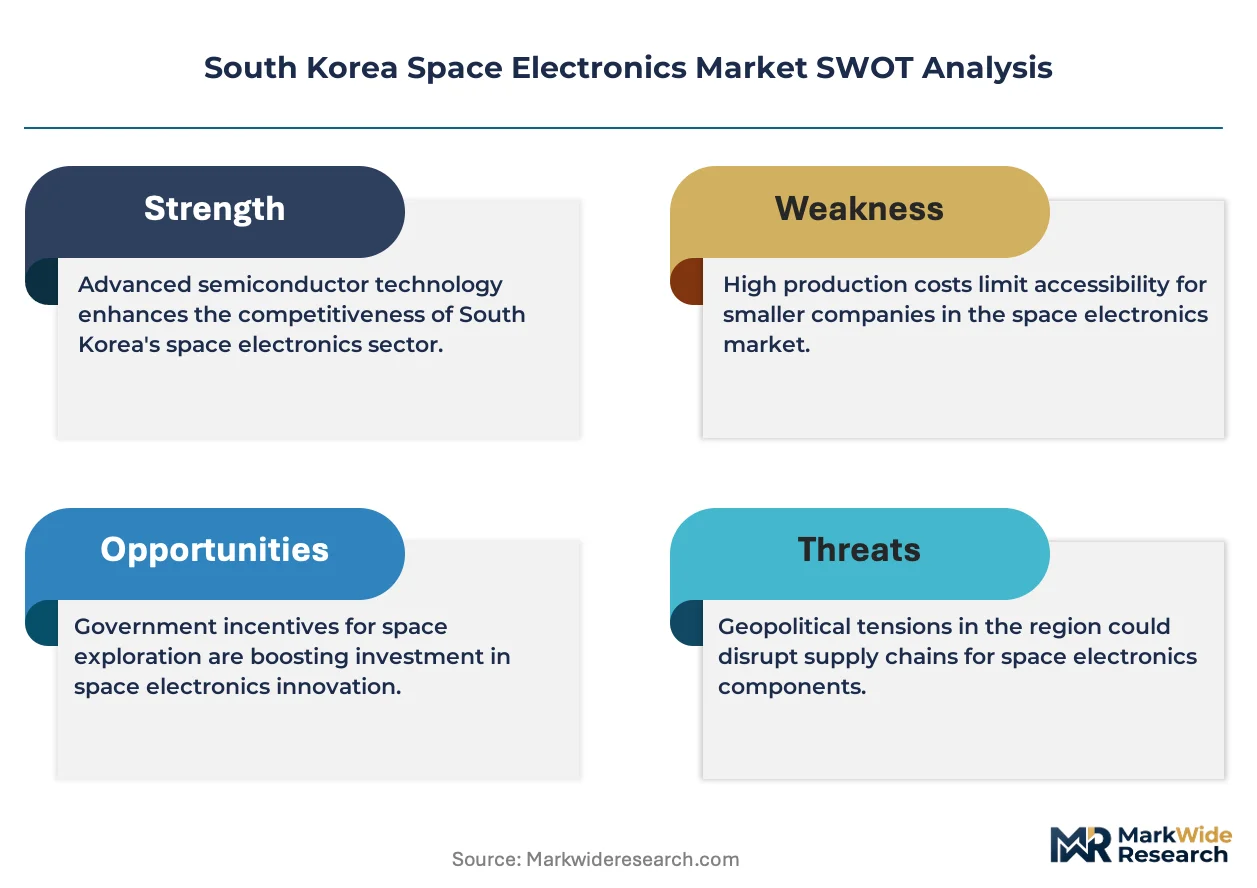
Radiation-hardened semiconductor qualification timelines are compressing as KARI accelerates sovereign launch schedules and domestic foundries expand gallium nitride capacity. This pressure is restructuring supplier relationships across the Naro Space Center supply base.
Growth Catalysts
- K-New Deal framework:The Ministry of Science and ICT's semiconductor initiative funds domestic qualification for orbital-grade components, reducing import dependency for power conditioning modules.
- Low Earth orbit constellations:Commercial broadband satellite operators are scaling procurement of high-bandwidth communication subsystems from Pangyo-based integrators.
- Carbon-neutral manufacturing mandates:Satellite bus producers now require radiation-hardened components sourced from fabs meeting renewable energy standards, reshaping supplier selection criteria.
Market Restraints
- Domestic foundry concentration:Gallium nitride and silicon carbide device fabrication remains concentrated among two domestic suppliers, creating single-source vulnerability for power electronics.
- MFDS traceability compliance costs:Component-level documentation requirements add 18-24 months to qualification cycles for new entrants.
- Test facility scarcity:Total ionizing dose validation capacity at KARI's Daejeon facility operates at sustained backlog, delaying flight heritage accumulation.
Strategic Opportunities
- Edge AI payload integration:Earth observation satellite operators are adopting on-board inference processors to reduce downlink bandwidth requirements, opening new subsystem categories.
- Defense-to-space crossover:Ministry of National Defense encryption mandates for commercial operators create demand for certified secure communication modules.
- Regional cluster expansion:Secondary suppliers are establishing qualification partnerships near the Naro Space Center to capture launch integration workflow proximity advantages.
Industry Challenges
- Radiation effects engineering talent:The specialized workforce for single-event upset analysis and latch-up mitigation remains insufficient relative to qualification pipeline demands.
- Legacy bus architecture integration:New gallium nitride power devices face interface compatibility friction with existing satellite bus designs from established platform providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Space Electronics Market |
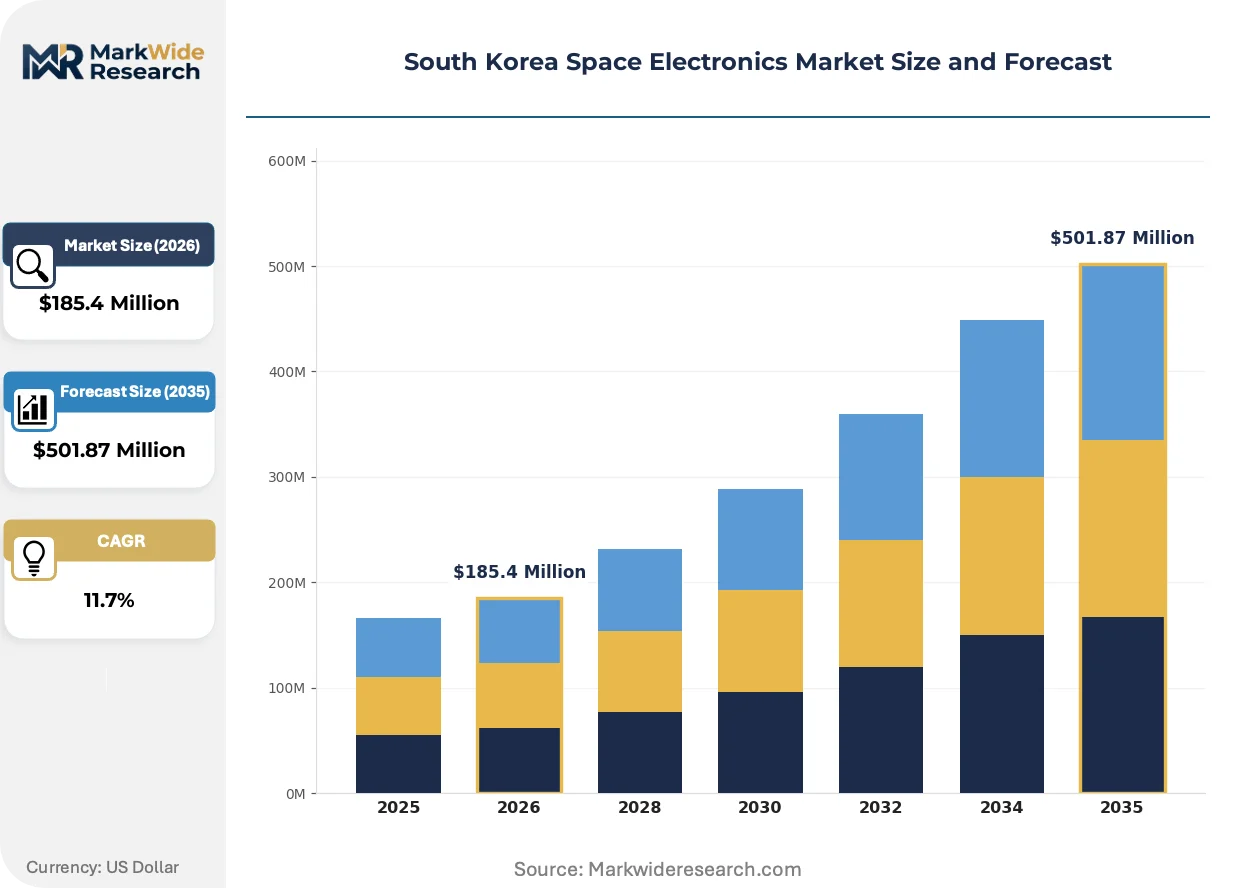
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $501.87 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Systems, Communication Systems, Control Systems, Sensors Technology: Microelectronics, FPGA, AI Hardware, Advanced Materials End User: Government Agencies, Private Companies, Research Institutions, Defense Organizations Application: Satellite Operations, Space Exploration, Scientific Research, Communication |
| Companies Covered | Hanwha Aerospace, Samsung Thales, South Korea Aerospace Research Institute (KARI), Doosan Corporation, KT SAT, Hanwha Systems, LIG Nex1, SeAH Besteel Holdings, Satrec Initiative, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Space Electronics Market Trends and Innovations
Three forces are actively restructuring South Korea's space electronics competitive landscape: component-level functional decomposition, tightening sovereign security requirements, and compressed procurement cycles for constellation deployments.
Silicon carbide power conversion modules are modularizing satellite electrical power subsystem architectures. Small satellite manufacturers in the Pangyo corridor are adopting standardized 28V and 100V bus interfaces at accelerating pace. This standardization is modularizing supplier tiers, enabling subsystem vendors to compete without full platform integration capabilities.
MFDS tightened component traceability protocols in late 2023, extending lot-level documentation requirements to commercial-grade space parts. Satellite integrators now face expanded compliance documentation burdens for mixed-heritage assemblies. Defense procurement rules from the Ministry of National Defense are compressing response timelines for cybersecurity certification submissions.
Constellation operators have compressed supplier qualification cycles from 36 months to 18 months for recurring bus orders. Tier-one satellite manufacturers are displacing traditional distributor relationships with direct foundry partnerships for radiation-hardened ASICs. This channel restructuring is most visible among earth observation payload providers seeking volume pricing leverage for multi-satellite deployments.
South Korea Space Electronics Market Segmentation
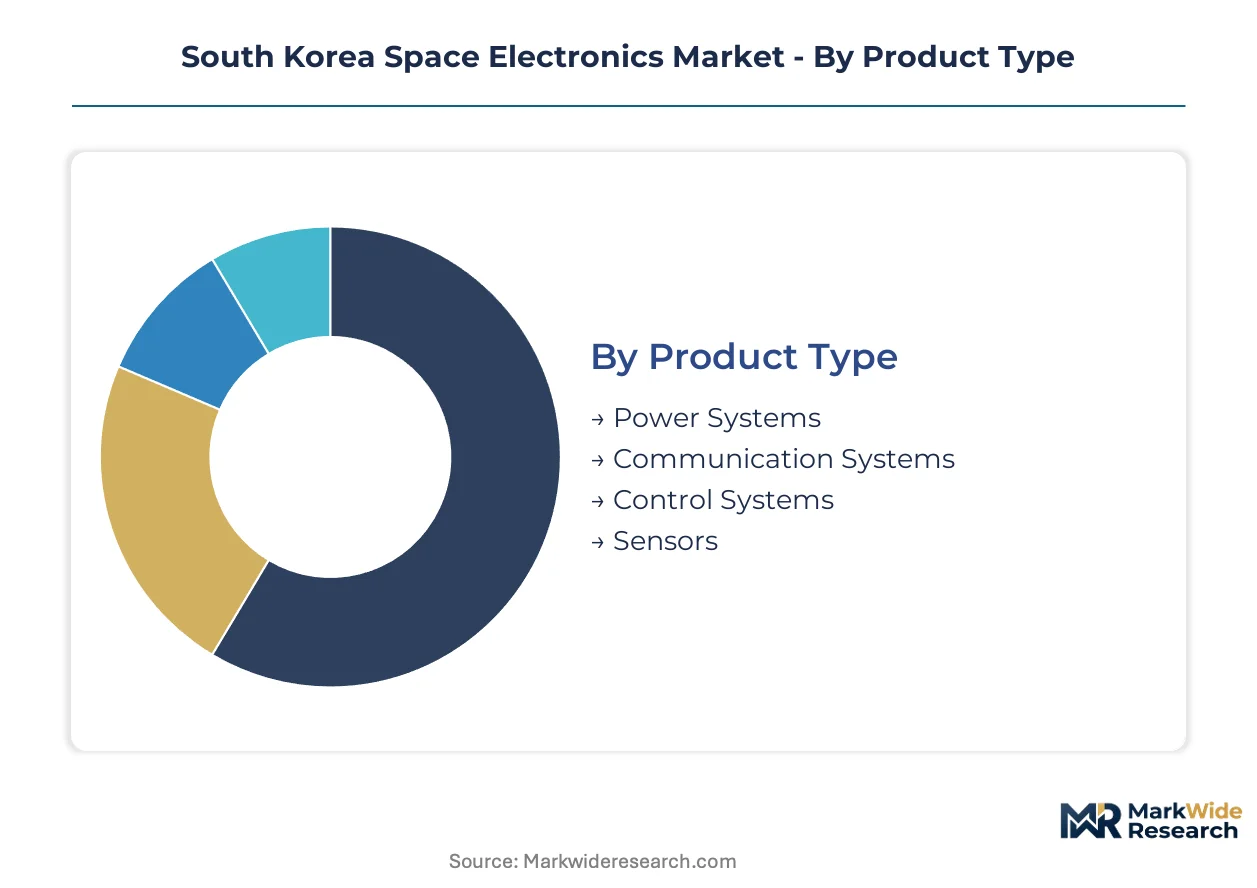
Segmentation reveals how procurement priorities diverge across South Korea's space electronics value chain. Radiation tolerance requirements, sovereign launch schedules, and constellation deployment timelines create distinct demand profiles that reshape supplier positioning.
Product Type:
Communication Systems dominate procurement volumes while Power Systems command premium pricing for gallium nitride qualification.
- Communication Systems:High-bandwidth transponders, antennas, and signal processing units engineered for low Earth orbit broadband constellations. Demand concentrates at Pangyo-based integrators serving commercial operators scaling ground-to-satellite capacity. KARI's sovereign launch acceleration compresses qualification timelines for domestic suppliers.
- Power Systems:Gallium nitride and silicon carbide power conditioning modules, battery management electronics, and solar array regulators. Naro Space Center procurement prioritizes domestic foundry partnerships for radiation-hardened devices. Single-source concentration among two domestic fabricators creates supply vulnerability for high-voltage bus architectures.
- Control Systems:Attitude determination and control electronics, including reaction wheel drivers and magnetic torque rod controllers. Hanwha Aerospace integrates these through in-house avionics programs.
- Sensors:Star trackers, sun sensors, and inertial measurement units for orbital navigation. Satrec Initiative specializes in compact sensor fusion for small satellite platforms.
Today's leader: Communication Systems. Tomorrow's challenger: Power Systems.
Technology:
Microelectronics anchor current revenue while AI Hardware expands most quickly for on-board edge processing.
- AI Hardware:Neural network accelerators and inference processors for earth observation payload data reduction. Earth observation operators at the Naro Space Center cluster adopt these to minimize downlink bandwidth costs. MFDS traceability protocols extend to commercial-grade AI components, lengthening documentation cycles.
- Microelectronics:Radiation-hardened integrated circuits, discrete semiconductors, and application-specific integrated circuits qualified for total ionizing dose exceeding 100 kilorads. Demand spans all orbital applications with geostationary missions requiring highest tolerance grades.
- FPGA:Field-programmable gate arrays for reconfigurable payload processing and software-defined radio implementations. LIG Nex1 leverages defense-qualified FPGA supply chains for space crossover programs.
- Advanced Materials:Ceramic substrates, specialized packaging compounds, and thermal interface materials for extreme temperature cycling. Carbon-neutral manufacturing mandates now require renewable energy sourcing for material processing.
Microelectronics maintain volume leadership. AI Hardware gains share fastest through constellation operator procurement.
End User:
Government Agencies drive qualification standards while Private Companies scale procurement volumes for commercial constellations.
- Government Agencies:KARI and Ministry of Science and ICT procurement for sovereign launch vehicles and national satellite programs. The K-New Deal framework directs semiconductor qualification funding toward domestic orbital-grade component development.
- Private Companies:Commercial satellite operators and constellation deployers procuring high-volume, cost-optimized subsystems. Pangyo corridor integrators serve this segment with standardized bus interfaces.
- Research Institutions:University and laboratory-led technology demonstration missions requiring experimental payload electronics. KARI's Daejeon facility supports radiation testing for heritage accumulation.
- Defense Organizations:Ministry of National Defense procurement for secure communication modules and encrypted satellite systems. Cybersecurity certification mandates now extend to commercial operators serving defense applications.
Government Agencies set technical baselines. Private Companies determine volume scaling trajectories.
Application:
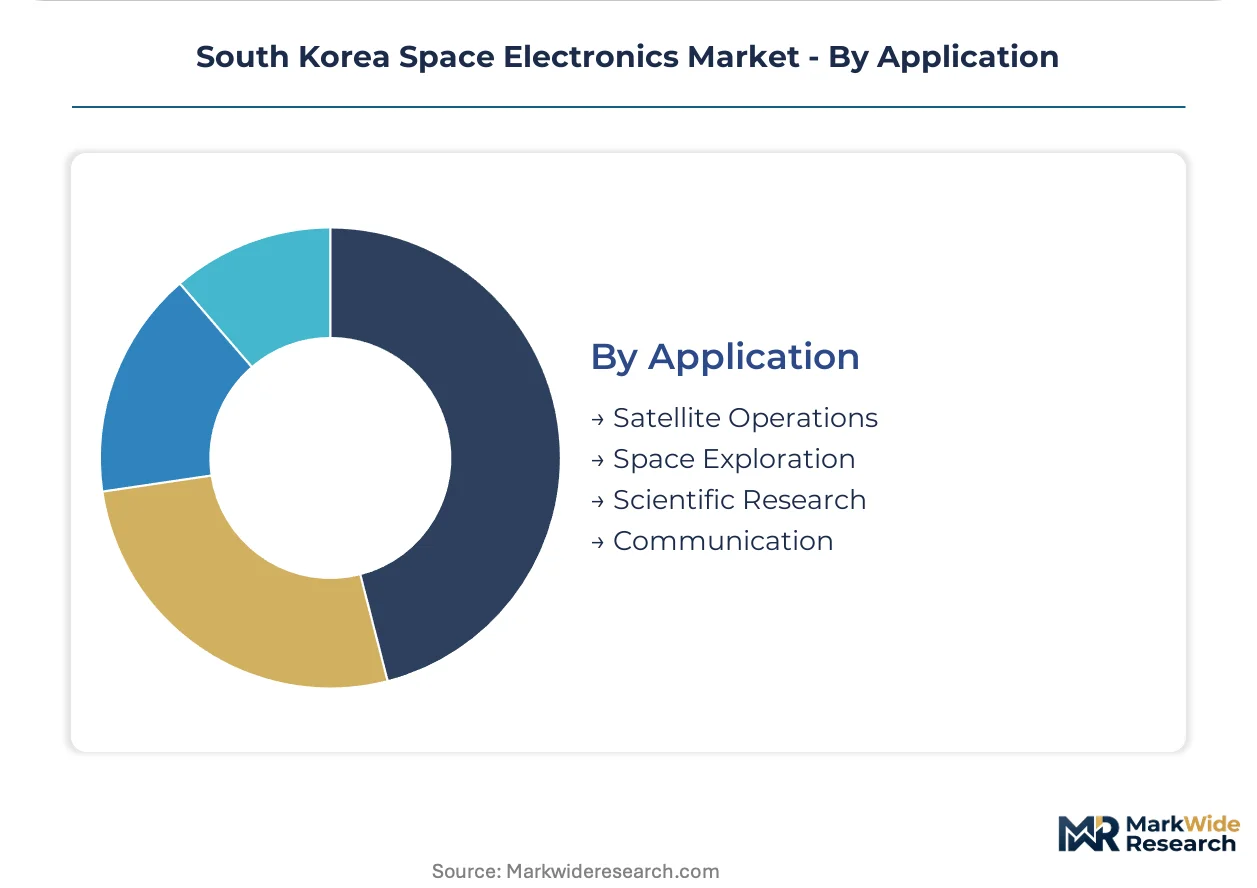
Satellite Operations absorb the majority of procurement while Space Exploration commands longest qualification cycles.
- Satellite Operations:Electronics for communications, navigation, and earth observation satellites across low Earth orbit, medium Earth orbit, and geostationary deployments. Constellation operators have compressed supplier qualification from 36 months to 18 months for recurring orders.
- Space Exploration:Deep-space mission electronics requiring extended radiation tolerance and autonomous operation capabilities. KARI's lunar and interplanetary programs drive demand for hardened systems with multi-year operational lifespans.
- Scientific Research:Payload electronics for space science missions including astronomy, heliophysics, and microgravity experiments. Research institutions prioritize novel sensor integration over cost optimization.
- Communication:Dedicated ground-to-satellite and inter-satellite link electronics. Low Earth orbit broadband expansion drives bandwidth scaling requirements for this segment.
Satellite Operations anchor current procurement. Space Exploration shapes next-generation qualification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's space electronics industry traces its modern origins to KARI's establishment in 1989 and the Naro Space Center's 2009 launch infrastructure activation. The sector has since clustered around sovereign launch capabilities and domestic semiconductor manufacturing heritage.
Seoul Capital Area
Pangyo technoplex hosts the densest concentration of satellite subsystem integrators serving commercial constellation operators. The Ministry of Science and ICT's K-New Deal framework channels semiconductor qualification funding through this corridor. Samsung Thales and Hanwha Systems anchor defense-to-space crossover development here.
South Jeolla Province
The Naro Space Center in Goheung drives launch vehicle avionics demand and ground support equipment procurement. KARI's sovereign launch acceleration compresses supplier qualification timelines for local vendors. Radiation-hardened power conditioning module suppliers cluster within 50 kilometers of the launch complex.
Daejeon-Sejong
KARI headquarters and the national radiation test facility concentrate research infrastructure in this central corridor. MFDS traceability protocols for component documentation extend compliance burdens to suppliers establishing qualification partnerships here. The facility backlog for total ionizing dose validation shapes regional supplier capacity planning.
Busan-Ulsan
Heavy industrial conglomerates with shipbuilding heritage reorient manufacturing capabilities toward satellite bus structures and thermal management systems. SeAH Besteel Holdings exemplifies this industrial transition. The region's metallurgical expertise supports advanced material processing for carbon-neutral manufacturing mandates.
South Korea Space Electronics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Korea's space electronics value chain. Domestic foundry partnerships anchor the supply side, while subsystem integrators concentrate in Pangyo without captive fabrication. Three archetypes dominate: vertically integrated defense conglomerates, specialized small satellite platform providers, and research-to-commercial crossover entities. Competitive positioning hardens around radiation-hardened ASIC qualification speed and direct foundry access rather than distributor relationships.
Among defense-heritage conglomerates, Hanwha Aerospace and Hanwha Systems occupy positions spanning launch vehicle avionics through satellite power subsystems. LIG Nex1 exemplifies the encryption-certified secure communications specialist archetype. Satrec Initiative represents the compact satellite platform pure-play, anchoring the Pangyo corridor's commercial constellation supplier tier without defense procurement heritage.
| Leading Market Players |
|---|
| Hanwha Aerospace |
| Samsung Thales |
| South Korea Aerospace Research Institute (KARI) |
| Doosan Corporation |
| KT SAT |
| Hanwha Systems |
| LIG Nex1 |
| SeAH Besteel Holdings |
| Satrec Initiative |
| Others |
Pricing and Supply Chain Analysis
Radiation effects engineering talent concentration in the Daejeon-Sejong corridor feeds directly into labor-cost differentials that separate premium qualification-grade components from standard commercial-space tiers. MFDS traceability compliance burdens amplify these spreads as documentation-intensive suppliers command pricing premiums over entrants facing 18-24 month qualification cycles.
Pricing Analysis
Three-tier pricing structure across radiation-hardened ASIC, commercial-space-grade, and industrial-temperature tiers dominates procurement. Price differentiation hinges on total ionizing dose certification grade and KARI flight heritage documentation depth. Cost compression in the commercial-space tier is intensifying because constellation operators have compressed supplier qualification cycles from 36 months to 18 months. Private constellation deployers exhibit highest price sensitivity while Ministry of National Defense procurement shows lowest sensitivity due to encryption mandate compliance requirements.
Supply Chain Analysis
MFDS lot-level documentation requirements and KARI radiation test protocols gate supplier entry before fabrication capacity even enters consideration. Gallium nitride and silicon carbide wafer supply concentrates in South Korea and the United States, with epitaxial growth equipment anchored in Germany and Japan. Raw material dependencies span high-purity gallium substrates, specialized ceramic packaging compounds, and radiation-tolerant silicone encapsulants. Single-source vulnerability runs through domestic foundry concentration among two qualified suppliers for power electronics. Distribution runs through direct foundry partnerships displacing traditional distributor relationships for volume constellation orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's space electronics market represents a late-cycle quality story as sovereign launch acceleration and carbon-neutral manufacturing mandates shift procurement toward premium-grade, fully-traceable components with established flight heritage.
For Market Incumbents: Acquire radiation test facility capacity to secure qualification pipeline control against KARI Daejeon backlog constraints. Deepen backward integration into gallium nitride epitaxy to eliminate single-source exposure for power conditioning modules. Lock in long-term foundry partnerships before domestic GaN capacity tightens further under K-New Deal funding allocations.
For New Entrants and Emerging Players: Secondary satellite subsystem suppliers near the Naro Space Center represent an underserved buyer archetype seeking proximity advantages for launch integration workflows. Target research institution technology demonstration missions requiring experimental payload electronics with shortened heritage requirements. Pursue qualification partnerships with Satrec Initiative for compact satellite bus integration as a go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among defense-to-space crossover specialists with encryption certification already in hand. Long-term viability over the next decade hinges on direct foundry access rather than distributor relationships. Watch for inflection when KARI announces sovereign lunar mission avionics procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic GaN Foundry Partnership | Secures supply chain autonomy for Hanwha Aerospace power subsystem programs under K-New Deal funding. |
| Radiation Test Facility Expansion | Reduces KARI Daejeon backlog delays that currently stall flight heritage accumulation for new entrants. |
| Edge AI Payload Integration | Captures constellation operator procurement for on-board inference processors reducing downlink bandwidth costs. |
| Carbon-Neutral Manufacturing Certification | Meets satellite bus producer renewable energy sourcing requirements reshaping supplier selection criteria. |
| Defense Encryption Crossover | Leverages LIG Nex1-certified secure communication modules for commercial operators under Ministry mandates. |
Research Methodology
Direct dialogue with satellite subsystem integrators, radiation effects engineers, KARI program managers, and MFDS compliance officers grounded the qualitative foundation. Secondary validation drew from KARI technical specifications, MFDS component traceability protocols, Ministry of Science and ICT K-New Deal framework documents, and Ministry of National Defense encryption procurement guidelines. Bottom-up and top-down triangulation cross-checked foundry capacity announcements against sovereign launch schedule acceleration timelines.
Segment-level outputs across product type, technology, end user, and application dimensions were generated through the analytical framework. CAGRs were derived from elasticity modeling against KARI launch cadence projections and constellation deployment scaling assumptions. Industry-specific inputs included gallium nitride domestic foundry capacity buildout schedules and carbon-neutral manufacturing mandate compliance cost curves.
Inputs from KARI program disclosures and MFDS regulatory filings were available through the study window; gaps in private constellation operator procurement volume data introduce uncertainty bands around commercial segment projections. Forecasts reflect assumptions regarding sovereign launch schedule adherence and domestic foundry qualification timeline compression. A model refresh is warranted upon material change in KARI lunar mission avionics procurement specifications or MFDS traceability protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
China Space Electronics Market
Space
Space Semiconductor Market
Space
Space Launch Services Market
Space
US Space Launch Services Market
Space
Space Management Solutions Market
Space
India Space Electronics Market
Space
India Aviation, Defense, and Space Market
Space
Asia-Pacific Space Logistics Market
Space
Space Radar Market
Space
Italy Space Electronics Market
Space
Japan Space Electronics Market
Space
Space Traffic Management Market
Space
Space Colonization Market
Space
Orbital Spaceflight Market
Space
Spacesuit Market
Space
Space Mining Market