
 US Reusable Launch Vehicle Market | 2026-2036
US Reusable Launch Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
US Reusable Launch Vehicle Market Intelligence
A divergence between high-cost, mission-specific launches for government payloads and lower-cost, high-cadence satellite deployments is repositioning the competitive landscape in the US. SpaceX dominates the high-frequency launch segment with its partially reusable Falcon 9 vehicle, creating a new market standard for cost-per-kilogram. In contrast, United Launch Alliance specializes in providing high-reliability launch services for sensitive national security missions. Blue Origin competes across segments with its New Glenn rocket, targeting both commercial satellite and government markets.
A US reusable launch vehicle is a space-faring craft designed for multiple flights, significantly lowering the cost per launch to Earth orbit. These complex systems feature first stages capable of propulsive vertical landings, using advanced engines like the Raptor or BE-4, for recovery and refurbishment. Vertical Takeoff Vertical Landing (VTVL) configurations represent the most commercially proven vehicle type. Within applications, satellite deployment for commercial internet constellations constitutes the largest volume driver for the US market.
The Federal Aviation Administration (FAA) oversees all commercial launch and re-entry licensing, directly influencing operational safety protocols and flight cadence. Concurrently, the Federal Communications Commission (FCC) manages spectrum allocation and orbital debris mitigation rules for satellite communications, a key factor for constellation operators. Stakeholders must navigate these evolving regulatory frameworks while investing in technologies that improve reusability and reduce critical turnaround times between missions.
Market Dynamics
The bifurcation of launch services into high-cadence commercial deployments and high-assurance government missions is the central structural force. This division creates separate value propositions, competitive arenas, and operational tempos within the US reusable launch vehicle market.
Growth Catalysts
- FAA Regulatory Streamlining:The Federal Aviation Administration's modernized commercial space transportation regulations are reducing the administrative burden, enabling a higher frequency of licensed launch and re-entry operations.
- Commercial Satellite Demand:Deployment of large-scale internet constellations by commercial operators constitutes the primary volume driver, requiring a consistent and high-cadence launch schedule that favors reusable systems.
- Infrastructure Concentration:Focused investment in launch and recovery infrastructure in key states like Florida and Texas creates operational efficiencies and supports rapid turnaround for reusable vehicles.
Market Restraints
- High Capital Expenditure:The immense upfront investment required to design, test, and certify reusable systems, particularly Vertical Takeoff Vertical Landing (VTVL) first stages, presents a significant barrier to entry.
- Complex Licensing Processes:Despite streamlining, navigating FAA launch and re-entry licensing remains a complex and time-consuming process that can introduce schedule uncertainty for new vehicles and launch sites.
- Specialized Component Scarcity:The supply chain for critical components, including high-performance alloys and advanced avionics needed for reusable engines and control systems, is constrained and subject to bottlenecks.
Strategic Opportunities
- Point-to-Point Cargo:Development of suborbital, point-to-point cargo delivery services represents a new application for reusable rocket technology, offering unprecedented speed for high-value logistics on Earth.
- AI in Refurbishment:Integrating artificial intelligence and robotics into the refurbishment process can automate inspection and repair, drastically reducing the critical turnaround time between missions for launch providers.
- DoD Rapid Launch Contracts:Future Department of Defense procurement for responsive space capabilities creates an opportunity for contracts specifically tailored to the rapid deployment advantages of reusable launch vehicles.
Industry Challenges
- Aerospace Talent Shortages:A limited pool of experienced engineers and technicians with expertise in propulsion, flight controls, and the refurbishment of flight-proven hardware constrains operational scaling.
- Orbital Debris Regulation:Adherence to evolving Federal Communications Commission rules for orbital debris mitigation imposes significant design and mission-planning challenges for large satellite constellation operators.
- Ground Support Investment:The ongoing capital required to build and maintain the extensive ground infrastructure for landing, processing, and refurbishing reusable stages is a persistent financial challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Reusable Launch Vehicle Market |
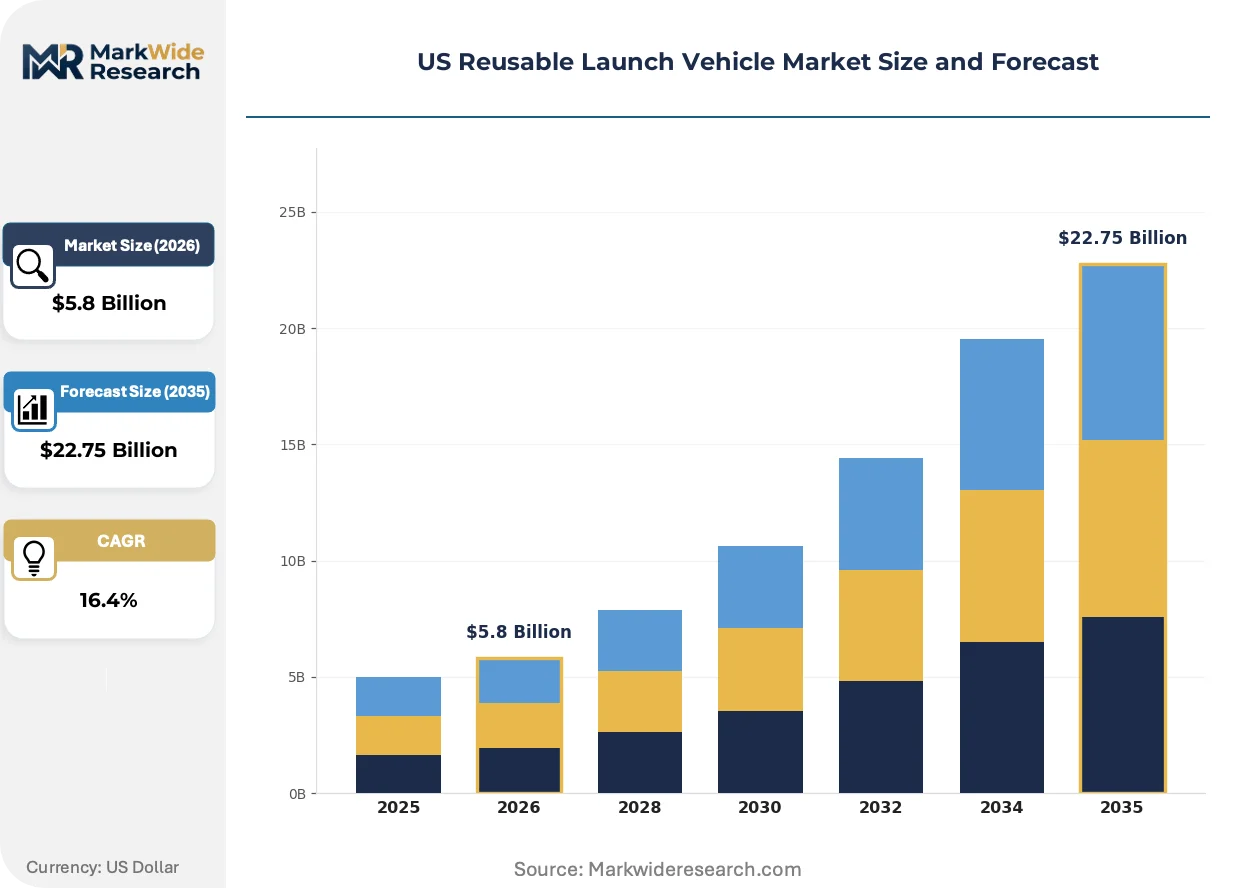
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $22.75 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Vertical Takeoff Vertical Landing, Winged Reusable, Expendable Booster, Spaceplane Propulsion Technology: Merlin Engine, BE-4 Engine, Raptor Engine, Vulcain Engine, RS-25 Engine Application: Satellite Deployment, Space Tourism, Government Missions, Cargo Resupply, Scientific Research End User: Space Agencies, Commercial Satellite Operators, Military, Research Institutions |
| Companies Covered | Rocket Lab, Firefly Aerospace, SpaceX, Sierra Nevada Corporation, Stoke Space Technologies, Blue Origin, Relativity Space, Astra Space, United Launch Alliance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Reusable Launch Vehicle Market Strategic Shifts & Innovations
The fundamental economics of space access are being rewritten by a manufacturing-style approach to launch operations. This shift prioritizes rapid turnaround and high flight rates, moving the industry away from bespoke, single-use vehicle paradigms toward standardized, reusable platforms.
Advanced additive manufacturing, or 3D printing, allows for the rapid fabrication of complex engine components like injectors and turbopumps. Both new entrants and established providers are adopting this technology to shorten development cycles. The use of in-house 3D printing is decentralizing critical component production away from traditional aerospace suppliers, enabling faster design improvements.
Implementation of the FAA's Part 450 regulation consolidates multiple launch licenses into a single, performance-based framework. This rule significantly reduces administrative overhead for operators planning frequent launches from one site. High-cadence commercial providers in the satellite deployment segment are the primary beneficiaries, gaining predictability for their business models.
A shift toward rideshare missions aggregates multiple small payloads from different customers onto a single launch. This model enables direct-to-customer booking through online portals, bypassing traditional launch brokers. This purchasing behavior is most visible among US university research programs and commercial small satellite startups seeking lower-cost access to orbit.
US Reusable Launch Vehicle Market Segmentation
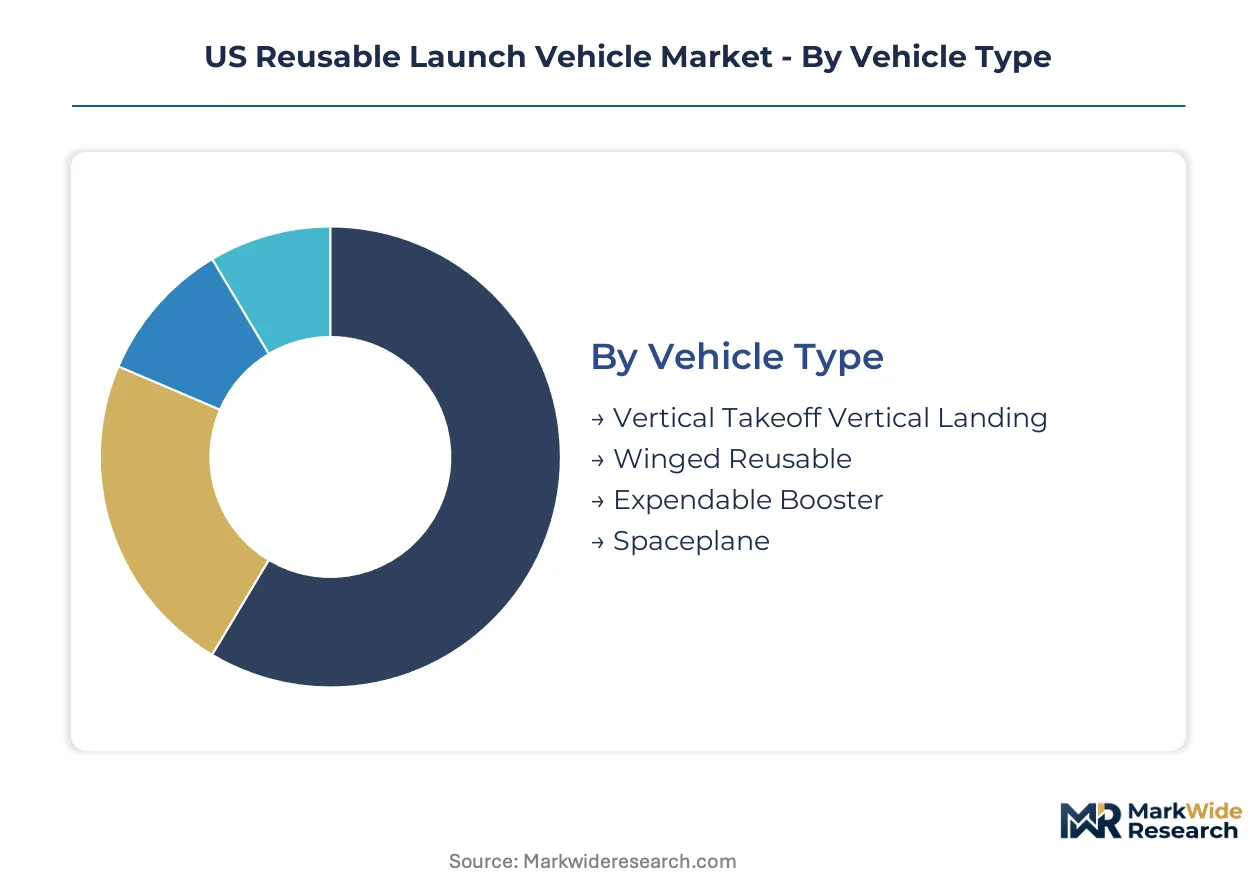
The US Reusable Launch Vehicle Market exhibits varied operational and technological characteristics across its core segments. Understanding these distinctions helps stakeholders identify specific growth drivers and regulatory influences within the national space economy.
Vehicle Type:
The certification burden varies significantly across vehicle types, with the Federal Aviation Administration (FAA) imposing rigorous safety and operational standards on all designs.
- Vertical Takeoff Vertical Landing:These vehicles feature first stages capable of propulsive landings, enabling rapid recovery and refurbishment for subsequent missions. SpaceX's Falcon 9, a prominent example, demonstrates high flight cadence for commercial satellite deployments from Florida launch sites.
- Winged Reusable:These systems incorporate aerodynamic surfaces for atmospheric re-entry and horizontal landings, often on runways. They offer potential for diverse payload delivery and rapid turnaround, though their development requires extensive testing for re-entry thermal management and flight control.
- Expendable Booster:These launch vehicles are designed for single-use, with components typically discarded after launch. While not reusable, they serve as a benchmark for cost and performance comparisons within the broader launch market.
- Spaceplane:A fully reusable winged vehicle capable of orbital flight and horizontal landing, spaceplanes represent a long-term vision for space access.
Leading the category by volume: Vertical Takeoff Vertical Landing. Growing fastest: Winged Reusable.
Propulsion Technology:
Supply concentration for propulsion technology dictates performance characteristics and launch provider capabilities.
- Raptor Engine:Developed by SpaceX, these full-flow staged combustion engines use methane and liquid oxygen, providing high thrust-to-weight ratios for Starship vehicles. Their advanced design enables deep throttling for precise landing maneuvers, crucial for rapid reusability.
- BE-4 Engine:Blue Origin's BE-4 engine, fueled by liquid natural gas and liquid oxygen, powers the New Glenn rocket and is also used by United Launch Alliance's Vulcan Centaur. This engine emphasizes robustness and reusability for heavy-lift applications, supporting both commercial and government missions.
- Merlin Engine:SpaceX's Merlin engines power the Falcon 9 and Falcon Heavy rockets, using rocket-grade kerosene and liquid oxygen.
- Vulcain Engine:This cryogenic engine powers the core stage of the European Ariane 5 and upcoming Ariane 6 rockets, primarily operating in an expendable capacity.
- RS-25 Engine:Formerly used on the Space Shuttle, these high-performance engines now power the Space Launch System (SLS) core stage for NASA missions.
Merlin Engine dominates current output, with Raptor Engine climbing the fastest.
Application:
Application diversity reflects the expanding utility of reusable launch systems across commercial and government sectors.
- Satellite Deployment:This application involves launching communication, Earth observation, and navigation satellites into various orbits. Commercial internet constellations represent the primary volume driver, demanding frequent, cost-effective launches to establish and maintain their networks.
- Government Missions:These missions encompass national security payloads, scientific research satellites, and interplanetary probes for agencies like NASA and the Department of Defense. High reliability and mission assurance are paramount for these critical deployments, often involving specialized launch requirements.
- Space Tourism:This emerging application focuses on providing suborbital and orbital flights for private individuals. Reusable systems are essential for making space tourism economically viable and scalable for a broader market.
- Cargo Resupply:Delivering supplies and equipment to orbital platforms, such as the International Space Station, constitutes a vital application. Reusable vehicles can reduce the logistical costs associated with these regular missions.
- Scientific Research:Launching telescopes, experimental payloads, and scientific instruments supports advancements in astrophysics, planetary science, and Earth sciences.
Satellite Deployment leads overall volume, with Space Tourism gaining share fastest.
End User:
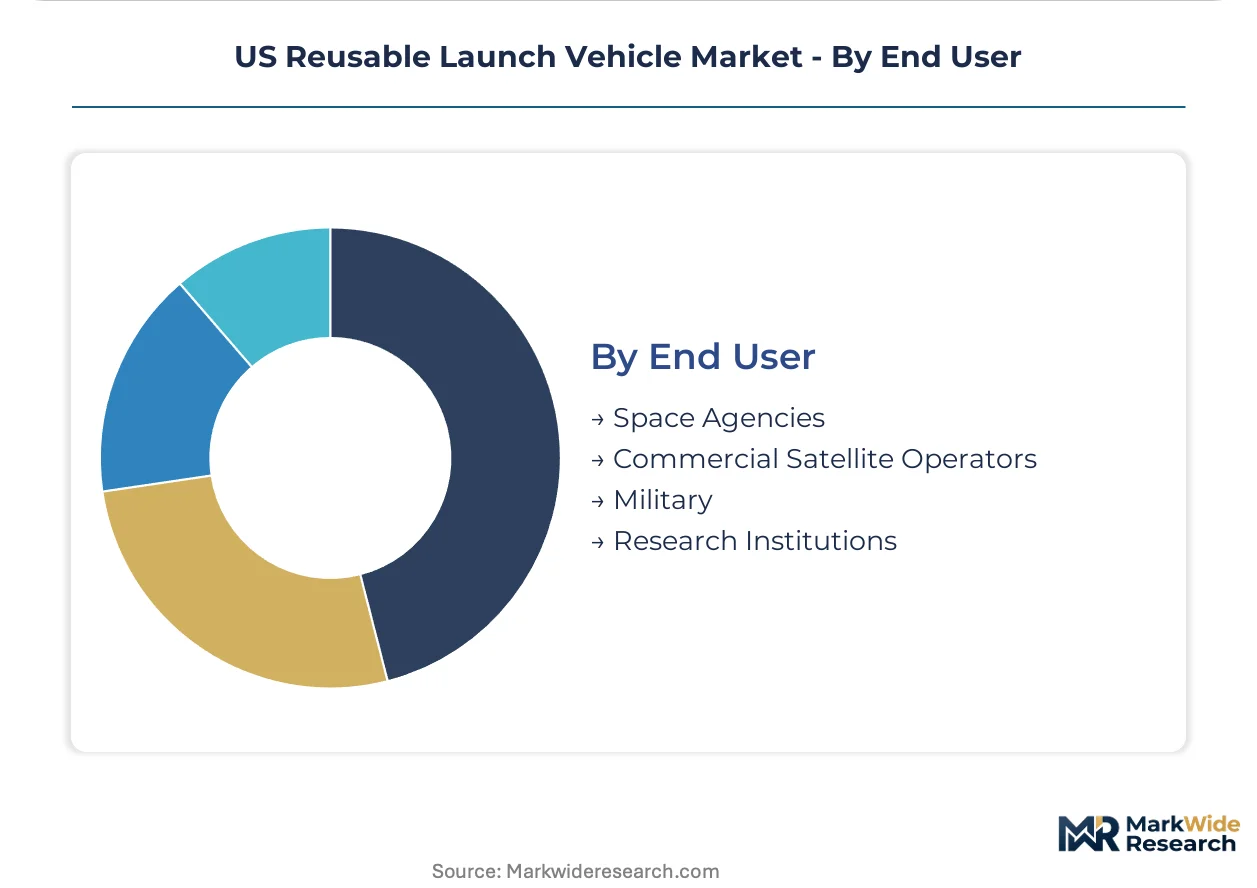
End-user requirements drive specific vehicle configurations and mission profiles within the US market.
- Commercial Satellite Operators:These entities deploy and manage large constellations for internet connectivity, Earth imaging, and other commercial services. Their demand for high-cadence, low-cost launches significantly influences reusable vehicle development, particularly around Florida and Texas launch sites.
- Space Agencies:Government space agencies, such as NASA, utilize reusable launch vehicles for scientific exploration, human spaceflight programs, and technology demonstration missions. They prioritize reliability and mission-specific capabilities, often requiring complex integration.
- Military:The Department of Defense and other military branches employ launch services for national security payloads, reconnaissance, and responsive space capabilities. Rapid deployment and assured access to space are critical requirements for these users.
- Research Institutions:Universities and private research organizations use launch services for experimental payloads, CubeSat deployments, and scientific studies. They often seek cost-effective access to orbit for smaller-scale projects.
Commercial Satellite Operators represent the largest customer base, while Military deployments show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cape Canaveral, Florida, stands as a primary hub for US reusable launch vehicle operations. This region benefits from established launch infrastructure and favorable regulatory conditions. Significant investment drives both commercial and government space endeavors across the country.
Florida
Commercial satellite operators drive demand for high-cadence launches from Florida's Space Coast. The FAA's streamlined Part 450 regulation facilitates frequent operations from existing sites. Infrastructure concentration around Cape Canaveral supports rapid turnaround and refurbishment of reusable stages. These capabilities are crucial for maintaining large internet constellations.
Texas
Large-scale internet constellations require consistent launch schedules, boosting activity in Texas. The state's supportive environment for aerospace innovation complements federal initiatives. Boca Chica has become a focal point for advanced reusable vehicle testing and launch operations. This concentration attracts further investment in ground support facilities.
California
Research institutions and private aerospace firms in California contribute to advanced reusable launch vehicle development. Federal funding through NASA programs supports cutting-edge propulsion and materials research. Southern California's aerospace cluster concentrates expertise in design and manufacturing of complex systems. This region also fosters a strong talent pool for engineering.
Washington
Aerospace companies in Washington focus on next-generation reusable rocket technologies and engine development. The state's skilled workforce benefits from long-standing aerospace industry presence. The Seattle metropolitan area serves as a key center for Blue Origin's engineering and manufacturing operations. Investment in advanced manufacturing facilities supports this growth.
US Reusable Launch Vehicle Market Key Industry Players
Premium-margin players sit above commodity-margin players across the US reusable launch vehicle market, differentiating by mission assurance and service reliability. The industry exhibits a tiered structure, with established providers serving both government and commercial clients. Strategic archetypes include high-cadence commercial operators, specialized national security contractors, and integrated aerospace developers. Companies frequently prioritize capacity expansion and technology licensing to secure market share in this capital-intensive sector.
Within the high-frequency commercial launch archetype, SpaceX represents a dominant force, setting new cost-per-kilogram standards through its Falcon 9 vehicle. Blue Origin occupies a position targeting both commercial satellite deployments and government missions with its New Glenn rocket, emphasizing advanced engine development and robust system design. United Launch Alliance, meanwhile, exemplifies a provider focused on high-reliability services for sensitive national security payloads, often integrating cutting-edge propulsion systems and specialized mission assurance protocols. These key players collectively shape the market's competitive dynamics and investment patterns across the US.
| Leading Market Players |
|---|
| Rocket Lab |
| Firefly Aerospace |
| SpaceX |
| Sierra Nevada Corporation |
| Stoke Space Technologies |
| Blue Origin |
| Relativity Space |
| Astra Space |
| United Launch Alliance |
| Others |
Cost & Logistics Intelligence
A pronounced operational bifurcation between high-reliability government missions and high-cadence commercial deployments shapes both pricing structures and supply chain configurations within the US reusable launch vehicle market. This divergence necessitates distinct procurement strategies and component specifications across the industry.
Pricing Analysis
Value-based pricing for launch services anchors to payload-to-orbit success, particularly for sensitive national security missions. Contract-based long-term offtake agreements characterize government procurement, while per-unit transactional models dominate commercial satellite deployments. Price differentiation stems from mission assurance levels and payload mass capacity. Pricing pressure intensifies in the commercial segment due to the competitive cost-per-kilogram advantage of reusable vehicles. Commercial satellite operators exhibit the highest price sensitivity, whereas government agencies prioritize reliability over cost.
Supply Chain Analysis
Single-source vulnerability sits with critical propulsion components, particularly advanced engines like the Raptor and BE-4, primarily developed and manufactured within the United States. The supply chain relies heavily on high-performance alloys and specialized avionics for reusable stages. Specialized component scarcity represents a significant structural risk, leading to potential bottlenecks for rapid scaling. Distribution runs through direct B2B relationships between launch providers and their highly specialized component suppliers, reflecting the market's technical complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US reusable launch vehicle market functions as a cost-of-compliance story, where the FAA's rigorous licensing and operational safety protocols create a significant barrier to entry for non-compliant players.
For Market Incumbents: Cement market leadership by expanding launch and recovery infrastructure in key states like Florida and Texas. Invest aggressively in AI and robotics for automated refurbishment processes to further reduce turnaround times and operational costs. This defends against emerging entrants offering niche services and mitigates supply chain bottlenecks for specialized components through vertical integration.
For New Entrants and Emerging Players: Technology-first innovation in advanced materials and automated inspection systems offers a viable wedge into the market. Target underpenetrated segments such as US university research programs and commercial small satellite startups seeking lower-cost access to orbit. A go-to-market angle focusing on online portals for rideshare mission booking can streamline customer acquisition.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized component manufacturers given the ongoing demand for high-performance propulsion and avionics systems. The long-term viability of the market over the next decade is strong, driven by persistent demand for space access. A signal to watch for inflection is the consistent reduction in critical turnaround times for Vertical Takeoff Vertical Landing stages.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Florida | Increases launch cadence for commercial satellite operators, supporting large constellation deployments. |
| AI Integration in Refurbishment | Automates inspection and repair, drastically reducing turnaround time between reusable vehicle missions. |
| Advanced Material R&D | Enhances reusability and durability of rocket components, lowering long-term operational expenditures. |
| Partnerships for Point-to-Point Cargo | Opens new revenue streams for reusable rocket technology beyond traditional orbital launches. |
| Investment in Talent Development | Addresses aerospace talent shortages, ensuring a skilled workforce for propulsion and flight controls. |
Research Approach
Independent corroboration across primary interviews, secondary validation, and bottom-up modeling underwrites the qualitative findings and quantitative projections within this analysis. The research engaged launch provider executives, satellite constellation operators, Federal Aviation Administration officials, and aerospace engineers to gather direct insights. Secondary data sources included SEC filings, government space agency reports, aerospace industry association publications, and academic research on propulsion systems.
The forecast framework anchored the analysis window to historical reference periods, establishing a baseline for future projections across the modeling period. Segmentation dimensions modeled included vehicle type, propulsion technology, application, end user, and US state. Compound annual growth rates were derived from a combination of historical performance trends and projected demand from planned satellite constellation deployments and government space budgets.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or major technological breakthroughs. Forecasts reflect assumptions regarding regulatory stability and continued investment in space infrastructure. Deviation in US regulatory policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Asia-Pacific Space Electronics Market
Space
France Space Electronics Market
Space
China Space Propulsion System Market
Space
Space-Based Solar Power Market
Space
Space on Board Computing Platform Market
Space
Space Launch Services Market
Space
Space Traffic Management Market
Space
Rocket Launchpad Market
Space
Space Technology (Spacetech) Market
Space
Deep Space Robotics Market
Space
Space-Based C4ISR Market
Space
UK Space Propulsion System Market
Space
Space Sensors Market
Space
Asteroid Mining Market
Space
Space Ground Station Equipment Market
Space
Space Designing Market