
 Commercial Aircraft Carbon Brakes Market | 2026-2036
Commercial Aircraft Carbon Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Carbon Brakes Market Intelligence
Aerospace metallurgist and composite technician shortages is unwinding production capacity across the carbon brake supply base. Safran leverages its vertically integrated carbon weave-to-disc manufacturing to secure OEM positions on next-generation single-aisle programs. Honeywell sustains aftermarket dominance through long-term thermal barrier refurbishment contracts with North American carriers. Collins Aerospace anchors its competitive stance via proprietary oxidation-resistant coating technologies that extend disc life cycles.
Commercial aircraft carbon brakes are friction devices fabricated from carbon-carbon or carbon-ceramic matrices, typically operating at surface temperatures exceeding 1,500°C during rejected takeoff events while delivering weight savings of 30-40% versus steel alternatives. Their primary purpose is to dissipate kinetic energy during landing and aborted takeoffs while minimizing brake-induced aircraft downtime. Carbon-carbon formulations occupy the mature revenue core due to decades of in-service validation on wide-body platforms, though carbon-ceramic variants represent the fastest-growing product class as OEMs seek enhanced thermal shock resistance for high-cycle narrow-body operations. The aftermarket distribution channel commands disproportionate margin pools because airline MRO procurement shifts toward performance-based brake management agreements rather than transactional disc replacement.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements jointly govern brake energy capacity and thermal soakback limits, compelling manufacturers to invest in expanded dynamometer testing infrastructure. The EU Green Deal aviation emissions framework indirectly shapes demand by incentivizing weight-reduction technologies that improve fuel efficiency per available seat-kilometer. Stakeholders must monitor evolving thermal management certification thresholds and assess whether in-house carbon preform production or outsourced supply offers superior cost resilience against raw material price volatility.
Market Dynamics
FAA thermal management certification thresholds are compressing development cycles while carbon weave supply concentrates among a handful of aerospace-grade preform manufacturers, forcing brake OEMs to secure captive fiber supplies or absorb volatile input costs.
Growth Catalysts
- EU Green Deal aviation emissions framework:Weight-reduction mandates from Brussels incentivize carbon brake retrofits on existing narrow-body fleets, accelerating replacement demand across European low-cost carriers.
- Rejected takeoff thermal loads:Escalating aircraft maximum takeoff weights and runway-constrained operations at hub airports drive specification upgrades toward carbon-ceramic matrices with superior heat flux capacity.
- United States MRO hub concentration:Atlanta, Dallas-Fort Worth, and Miami maintenance clusters generate dense aftermarket volumes as legacy steel brake replacement intervals compress under high-cycle utilization patterns.
Market Restraints
- Acrylonitrile precursor cost volatility:Aerospace-grade PAN fiber prices swing with oil-derived feedstock markets, squeezing margin stability for carbon preform producers without long-term supply contracts.
- Japanese carbon fiber supply concentration:Toray, Mitsubishi Chemical, and Toho Tenax control over seventy percent of aerospace-qualified fiber output, creating single-source vulnerability for brake disc manufacturers.
- FAA Part 25 brake energy capacity certification:Expanded dynamometer testing requirements extend validation timelines and capital intensity for new disc designs entering commercial service.
Strategic Opportunities
- India narrow-body fleet expansion:IndiGo and Air India order backlogs for A320neo and 737 MAX families create greenfield carbon brake penetration potential as domestic MRO infrastructure matures.
- Performance-based brake management agreements:Airlines in the United States are unbundling disc ownership from maintenance, opening recurring revenue streams for thermal barrier refurbishment and predictive wear monitoring.
- Carbon-ceramic and ceramic-matrix composite convergence:Hybrid formulations integrating silicon carbide phases promise enhanced oxidation resistance for high-frequency short-haul operations in Middle Eastern ambient conditions.
Industry Challenges
- Aerospace metallurgist and composite technician scarcity:Specialized layup and densification expertise required for carbon-carbon disc production is retiring faster than vocational pipelines replenish, constraining output expansion.
- FAA-EASA certification divergence on thermal soakback testing:Divergent interpretation of maximum allowable heat transfer to hydraulic systems forces redundant validation campaigns for dual-certification brake designs.
- Legacy fleet steel brake inventory amortization:Carriers with capitalized steel disc stocks delay carbon conversion decisions, compressing retrofit program timelines against airframe retirement schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Carbon Brakes Market |
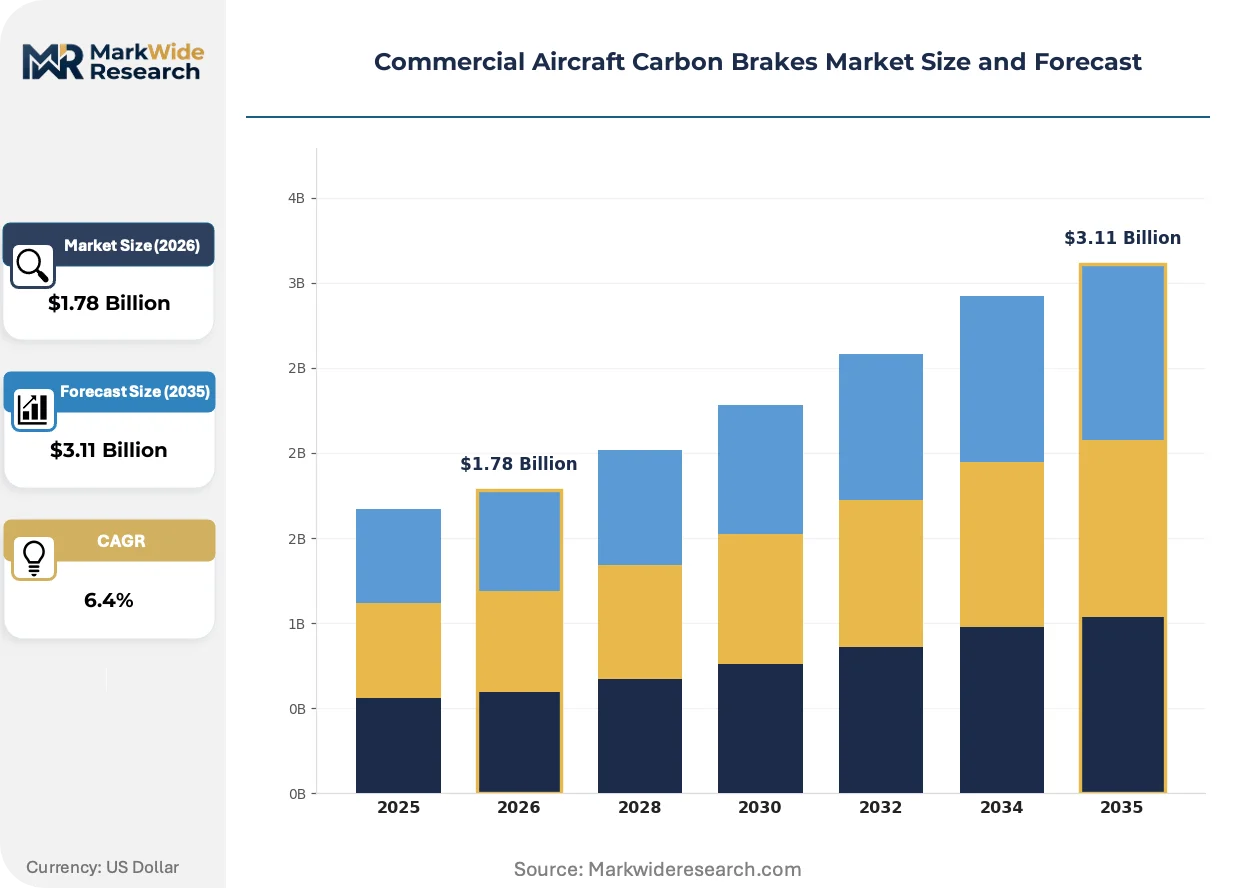
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Matrix Composites, Phenolic Resin, Carbon-Carbon, Carbon Ceramic Application: Landing Gear, Wheels, Engine Components, Brake Systems End User: Commercial Airlines, Cargo Carriers, Private Jet Operators, Maintenance, Repair, and Overhaul (MRO) Distribution Channel: OEMs, Aftermarket, Direct Sales, Distributors |
| Companies Covered | Honeywell, Safran, Collins Aerospace, Meggitt, SGL Carbon, Mersen, Parker Hannifin Corp, UTC Aerospace Systems, Rubin Aviation Corporation JSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Carbon Brakes Market Strategic Shifts & Innovations
Carbon brake technology is fragmenting across multiple performance tiers as OEMs balance thermal capacity against cost targets, while regulatory pressure on aircraft emissions intensifies scrutiny of landing gear weight reduction pathways.
Carbon-ceramic matrix formulations are fragmenting the traditional carbon-carbon dominance in narrow-body applications. Low-cost carriers operating high-cycle routes in Turkey and Vietnam specify these variants for enhanced thermal shock resistance during rapid turnarounds. The shift is compressing price premiums between ceramic-enhanced and baseline carbon-carbon discs as production scales.
EASA CS-25 amendments on brake energy certification are tightening thermal soakback limits for new type designs. Manufacturers must demonstrate reduced heat transfer to adjacent structures during rejected takeoff scenarios. Wide-body programs with extended development timelines face the steepest compliance costs, while single-aisle derivatives adapt more rapidly.
Airline technical procurement departments are consolidating brake spend under fleet-wide performance contracts. North American network carriers now specify availability guarantees rather than unit pricing, displacing transactional spot purchasing. This behavior is most visible among United States legacy operators managing mixed Boeing and Airbus fleets under unified MRO agreements.
Commercial Aircraft Carbon Brakes Market Segmentation
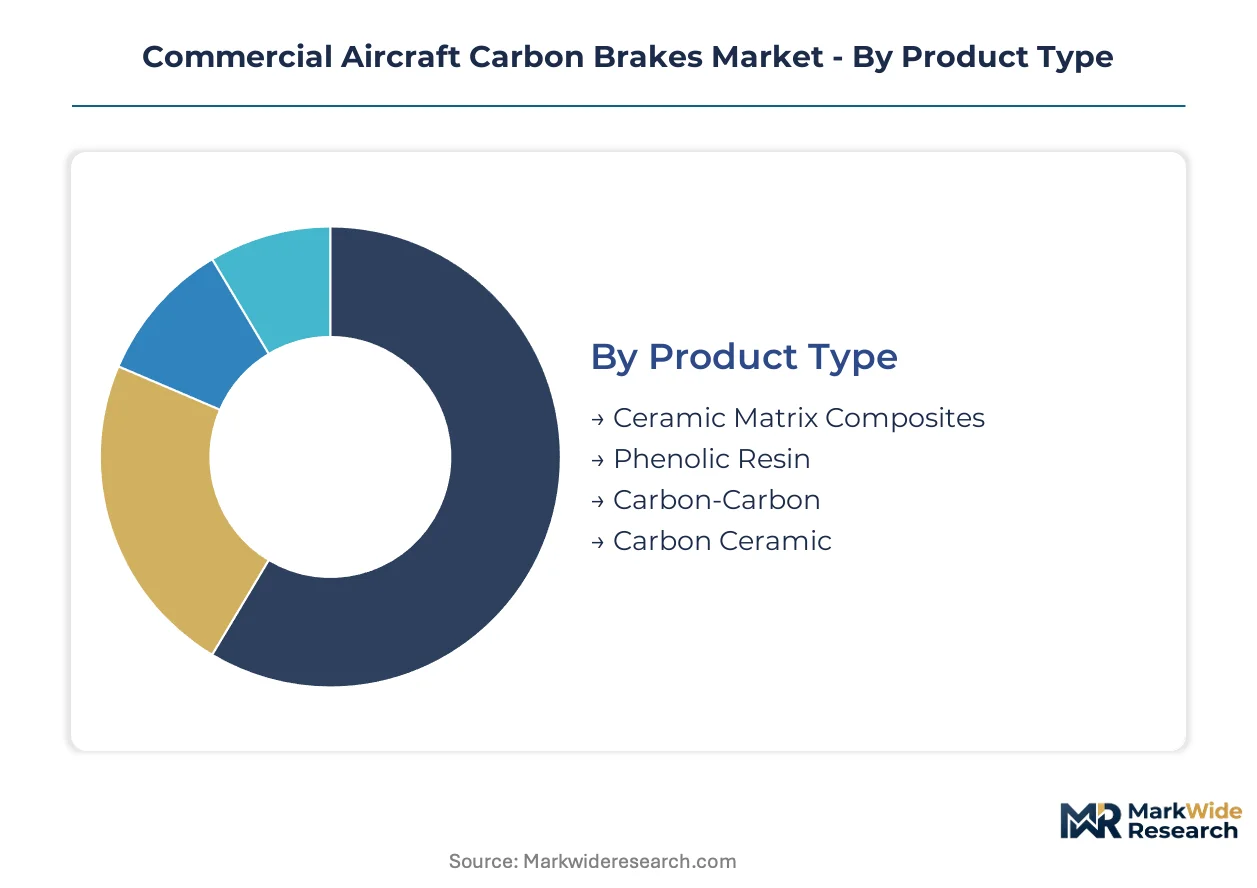
Carbon brake procurement flows through sharply divergent channels depending on whether discs enter new aircraft production or fleet maintenance cycles. Understanding these pathway distinctions illuminates where margin pools concentrate and which technical specifications dominate each volume stream.
Product Type:
Aftermarket refurbishment contracts favor mature formulations with established thermal performance databases, while OEM sourcing increasingly weights next-generation matrices against emerging certification thresholds.
- Carbon-Carbon:Fabricated from woven carbon fiber preforms densified through chemical vapor infiltration, these discs operate reliably above 1,500°C during rejected takeoff events. Demand concentrates among United States legacy carriers retrofitting wide-body fleets, constrained by long lead times for aerospace-grade PAN fiber from Japanese suppliers.
- Carbon Ceramic:Silicon carbide phases embedded within carbon matrices deliver superior thermal shock resistance for rapid-turnaround narrow-body operations. European low-cost carriers operating high-cycle routes specify these variants as EU Green Deal weight-reduction mandates accelerate fleet retrofit programs.
- Ceramic Matrix Composites:Hybrid architectures combining oxide and non-oxide ceramics suit next-generation propulsion integration.
- Phenolic Resin:Binder systems for initial carbon preform stabilization, primarily consumed in-house by vertically integrated manufacturers.
By volume, Carbon-Carbon leads. By growth pace, Carbon Ceramic is gaining share fastest.
Application:
Cost tiers separate emergency-rated systems from routine wear components, with certification grade determining which applications command premium positioning.
- Brake Systems:Energy absorption assemblies integrating stators, rotors, and thermal barriers face the most stringent FAA Part 25 certification requirements. United States MRO hubs in Atlanta and Dallas-Fort Worth generate dense replacement volumes as high-cycle utilization compresses inspection intervals.
- Landing Gear:Weight-critical strut and truck assemblies increasingly specify carbon brakes as OEMs target fuel efficiency per available seat-kilometer improvements.
- Wheels:Rim and hub structures incorporate carbon composites for mass reduction on regional jet platforms.
- Engine Components:Thrust reverser cascades and nacelle elements utilize carbon-ceramic thermal protection.
Brake Systems capture the majority of aftermarket revenue. Landing Gear shows the steepest specification upgrade trajectory.
End User:
Customer type dictates contract structure, with fleet scale determining whether procurement favors transactional disc replacement or integrated performance agreements.
- Commercial Airlines:Network carriers with mixed Boeing and Airbus fleets consolidate brake spend under unified MRO agreements specifying availability guarantees rather than unit pricing. North American operators lead this behavioral shift.
- Maintenance, Repair, and Overhaul (MRO):Independent and airline-captive facilities capture disproportionate margin pools through thermal barrier refurbishment and predictive wear monitoring services.
- Cargo Carriers:Express freight operators with high-cycle nighttime schedules prioritize rapid turnaround compatibility.
- Private Jet Operators:Fractional ownership fleets drive sporadic demand for premium-grade replacement intervals.
Commercial Airlines dominate absolute volume. MRO channels are climbing fastest as airlines unbundle disc ownership from maintenance.
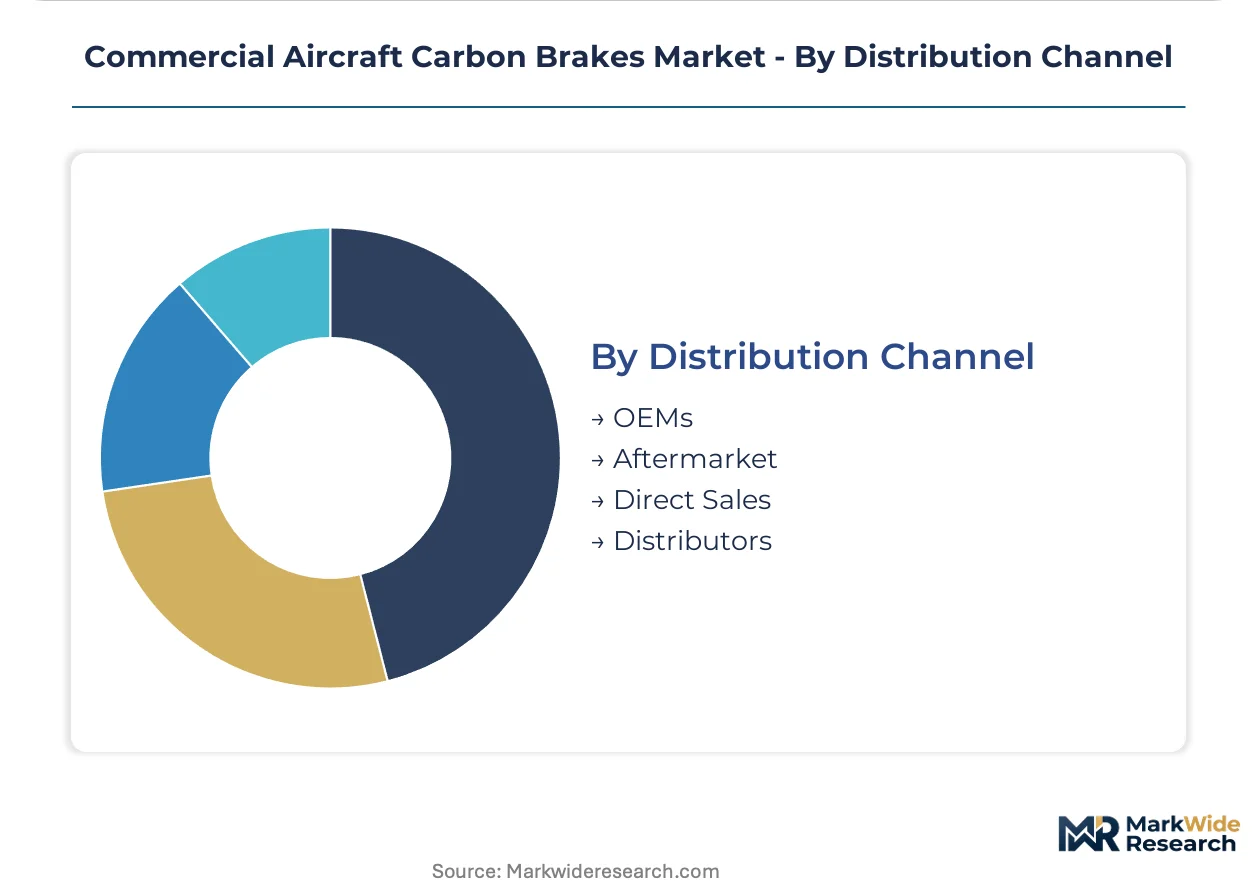
Distribution Channel:
Supply concentration among brake OEMs with captive carbon weave capabilities shapes which channels control pricing leverage.
- Aftermarket:Performance-based brake management agreements now displace transactional spot purchasing among United States legacy operators. Long-term thermal barrier refurbishment contracts lock in recurring revenue streams for suppliers with in-house densification expertise.
- OEMs:Original equipment manufacturers specify next-generation single-aisle programs, with positions secured through vertically integrated carbon preform production.
- Distributors:Regional inventory holders serve fragmented private jet and cargo operator demand.
- Direct Sales:Large fleet operators with technical procurement departments negotiate directly for fleet-wide specifications.
Aftermarket leads by margin contribution. OEM channels anchor technology transition timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 25 certification standards anchor demand concentration in the United States, where major carriers and dense MRO infrastructure drive replacement volumes. European regulatory pressure through EASA CS-25 amendments and the EU Green Deal framework accelerates retrofit adoption across high-cycle narrow-body fleets.
United States
Legacy carriers operating mixed Boeing and Airbus fleets consolidate brake procurement under unified MRO agreements. FAA airworthiness directives on thermal management tighten certification timelines for new disc designs. Atlanta, Dallas-Fort Worth, and Miami maintenance clusters generate dense aftermarket volumes as inspection intervals compress under high-cycle utilization.
France
Next-generation single-aisle program positions secure OEM supply chains through vertically integrated carbon preform production. EASA CS-25 brake energy certification amendments impose expanded dynamometer testing requirements on Toulouse-based development programs. The aerospace manufacturing corridor between Toulouse and Bordeaux concentrates carbon weave-to-disc capabilities.
Germany
EU Green Deal aviation emissions frameworks incentivize weight-reduction retrofits on existing narrow-body fleets operated by European low-cost carriers. REACH compliance obligations shape chemical handling protocols at carbon fiber densification facilities. The Bavarian aerospace cluster around Munich hosts thermal barrier coating development for extended disc life cycles.
Japan
Toray, Mitsubishi Chemical, and Toho Tenax control over seventy percent of aerospace-qualified PAN fiber output, creating single-source vulnerability for brake disc manufacturers. METI industrial policy supports carbon fiber precursor supply chain resilience. The Nagoya aerospace manufacturing region supplies preform materials to global brake OEMs.
India
IndiGo and Air India order backlogs for A320neo and 737 MAX families create greenfield carbon brake penetration potential as domestic MRO infrastructure matures. DGFT import regulations shape raw material access for emerging carbon preform producers. The Karnataka-Telangana aerospace corridor near Bangalore attracts brake component assembly investments.
Commercial Aircraft Carbon Brakes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the carbon brake supply base. The market structure concentrates around brake OEMs with captive carbon weave capabilities and independent material specialists serving secondary sourcing needs. Three archetypes dominate: vertically integrated aerospace conglomerates controlling fiber-to-disc production, specialized carbon preform manufacturers supplying external brake makers, and diversified industrial conglomerates with materials science portfolios. Competitive moves center on securing long-term PAN fiber supply contracts and expanding thermal barrier refurbishment service networks.
Within the vertically integrated tier, Honeywell and Safran exemplify archetypes combining carbon preform production with OEM brake system positions. Collins Aerospace occupies a technology-specialist position anchored by proprietary coating formulations. Meggitt represents the diversified aerospace component model with carbon brake portfolios nested within broader landing gear capabilities.
| Leading Market Players |
|---|
| Honeywell |
| Safran |
| Collins Aerospace |
| Meggitt |
| SGL Carbon |
| Mersen |
| Parker Hannifin Corp |
| UTC Aerospace Systems |
| Rubin Aviation Corporation JSC |
| Others |
Cost & Logistics Intelligence
Long-term thermal barrier refurbishment contracts lock in both aerospace-grade PAN fiber supply access and price visibility for brake OEMs serving United States legacy carriers, insulating procurement teams from acrylonitrile precursor volatility while compressing spot-market leverage for non-integrated competitors.
Pricing Analysis
United States aftermarket pricing runs 15-20% above European spot quotations due to dense MRO hub concentration and FAA-mandated certification premiums. Performance-based brake management agreements stratify across premium, standard, and economy tiers based on thermal cycle guarantees and predictive wear monitoring inclusion. Cost compression in carbon-ceramic formulations is intensifying because European low-cost carrier retrofit volumes are scaling faster than Japanese fiber supply expansion. Cargo carriers operating high-cycle nighttime schedules exhibit the highest price sensitivity, while network carriers with unified fleet agreements prioritize availability guarantees over unit economics.
Supply Chain Analysis
Extended lead times for aerospace-grade carbon preforms stretch 18-24 months as Japanese suppliers ration output across competing aerospace programs. Manufacturing gravity centers on Japan, France, and the United States, with Toray and Mitsubishi Chemical controlling upstream PAN fiber supply. Brake disc production draws from acrylonitrile precursors, chemical vapor infiltration equipment, and proprietary oxidation-resistant coating chemistries. Single-source vulnerability pervades the Japanese carbon fiber tier, where METI industrial policy shapes export allocation. Distribution runs through OEM direct channels for new aircraft programs and airline-captive MRO facilities for aftermarket refurbishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake system procurement is consolidating under platform-economics logic as airlines unbundle disc ownership from maintenance, creating interoperability standards that favor suppliers with integrated thermal barrier refurbishment networks and predictive wear data architectures.
For Market Incumbents: Secure captive aerospace-grade PAN fiber supply through long-term offtake agreements with Japanese producers before METI export allocation tightens further. Expand in-house densification capacity at United States MRO hubs to defend margin position against independent refurbishment specialists entering the Atlanta and Dallas-Fort Worth clusters. Prioritize FAA-EASA dual-certification investment to preempt redundant validation campaigns as thermal soakback testing thresholds diverge. For New Entrants and Emerging Players: Anchor in India's Karnataka-Telangana aerospace corridor, where IndiGo and Air India fleet expansion outpaces domestic brake disc assembly capacity. Target carbon-ceramic refurbishment specialization for rapid-turnaround narrow-body operations, a segment where European low-cost carrier demand exceeds incumbent thermal barrier service throughput. Pursue direct technical procurement relationships with cargo carriers seeking availability guarantees rather than competing for legacy airline unified MRO agreements. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated brake OEMs with captive carbon weave-to-disc capabilities and established FAA Part 25 certification track records, as these assets compound defensive moats over the projection horizon. Monitor EASA CS-25 amendment implementation velocity as the inflection signal—accelerated thermal soakback limit enforcement will compress development timelines and strand non-compliant disc inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Preform Production | Captive aerospace-grade PAN fiber supply insulates margin stability against Toray allocation decisions. |
| Performance-Based Brake Management Agreement Expansion | United States network carriers now specify availability guarantees, displacing transactional spot purchasing. |
| Dual-Certification Testing Infrastructure Investment | Redundant FAA-EASA validation campaigns compress timelines for brake designs entering commercial service. |
| Predictive Wear Monitoring Platform Development | Airline MRO procurement shifts toward integrated thermal barrier refurbishment and data-driven replacement scheduling. |
| India MRO Hub Joint Venture Formation | Domestic carbon brake assembly capacity lags behind A320neo and 737 MAX delivery backlogs at IndiGo and Air India. |
Research Approach
Initial hypotheses were tested against primary input from brake system engineering directors, airline technical procurement managers, MRO facility operations heads, and carbon fiber densification specialists, and refined through secondary validation against FAA airworthiness directive filings, EASA CS-25 certification amendment records, METI industrial policy disclosures, and customs trade data for aerospace-grade PAN fiber shipments. Bottom-up fleet retrofit demand estimates triangulated with top-down OEM production schedules across the analysis window.
Variance decomposition across product type, application, end user, and distribution channel dimensions anchored the analytical framework, with carbon-ceramic versus carbon-carbon technology transition curves modeled separately. CAGRs derived from segmented volume projections weighted by replacement interval compression rates and EU Green Deal retrofit incentive uptake. Industry-specific forecast inputs incorporated rejected takeoff thermal load specifications and narrow-body fleet utilization patterns at hub-constrained airports.
Material uncertainties — acrylonitrile precursor cost volatility, Japanese carbon fiber export allocation shifts, and FAA-EASA certification divergence — sit outside the modeled envelope. Forecasts reflect assumptions about MRO infrastructure maturation timelines and airline procurement behavioral shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Aircraft Door Dampers Market