
 France Satellite Imagery Services Market | 2026-2036
France Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
France Satellite Imagery Services Market Insights
The EU Green Deal is expanding requirements for land-use verification and carbon stock monitoring across member states, pushing French agencies and private operators toward higher-resolution satellite data subscriptions. Airbus Defence and Space leverages its Pleiades constellation to dominate defense and institutional contracts across Europe. CNES sustains public R&D funding for next-generation optical payloads. Thales Alenia Space competes on radar and telecommunications satellite integration.
France Satellite Imagery Services encompass the capture, processing, analysis, and distribution of Earth observation data from orbital platforms, typically resolving features at sub-meter precision for commercial and government clients. Synthetic aperture radar penetrates cloud cover and darkness, enabling all-weather monitoring for maritime surveillance and infrastructure integrity. Optical and multispectral technologies lead service revenue due to mature agricultural and urban planning demand, while hyperspectral analytics represent the fastest-expanding margin pool for precision agriculture and mineral exploration. Data processing and analytics segments outpace raw imagery acquisition in growth as end users shift from pixel purchases to decision-ready intelligence.
France's national space policy operates under CNES oversight with compliance to EU Space Programme regulations and the French Space Operations Act, which mandates debris mitigation and orbital accountability for all licensed service providers. ANSM and CNIL frameworks govern health and data privacy applications when satellite imagery intersects with medical geography or personal identification. GDPR constraints on geospatial data handling shape product architecture and limit automated feature extraction in populated areas. Stakeholders must weigh sovereign data requirements against commercial cloud delivery models as institutional buyers renegotiate access terms.
Market Dynamics
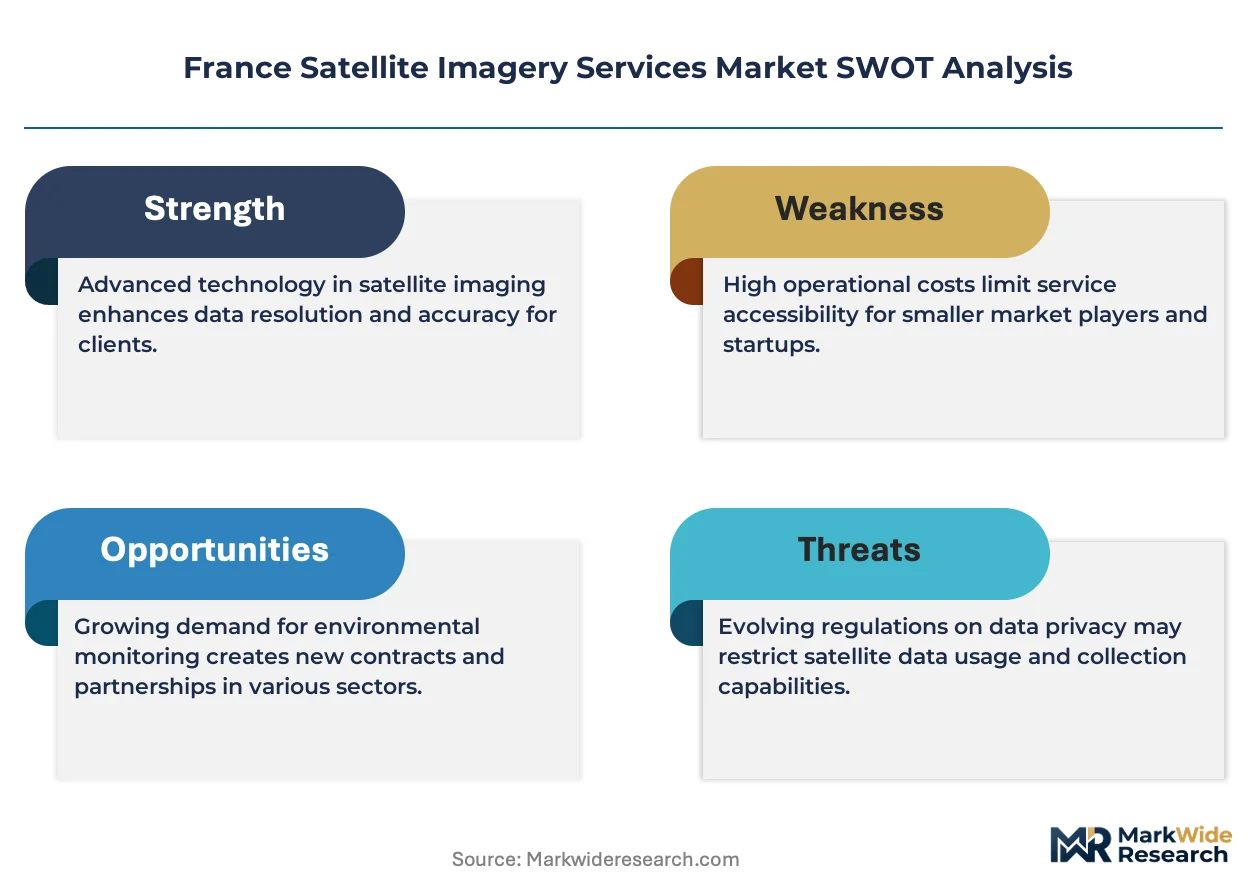
France's satellite imagery sector is being restructured by sovereign data localization mandates under the French Space Operations Act, which compels operators to maintain domestic ground segment infrastructure and orbital accountability systems rather than relying on transnational cloud delivery models.
Growth Catalysts
- EU Green Deal verification mandates:Land-use carbon stock monitoring requirements are pulling French forestry agencies and agricultural cooperatives toward higher-resolution subscription models for compliance reporting.
- Defense procurement expansion:The Ministry of the Armed Forces is embedding satellite imagery into sovereign intelligence architectures, creating institutional demand for all-weather synthetic aperture radar capabilities.
- Île-de-France cluster density:Concentrated aerospace engineering talent around Toulouse and Paris-Saclay accelerates payload-to-service commercialization cycles for emerging operators.
Market Restraints
- Launch cost volatility:Ariane 6 schedule uncertainties and geopolitical launch site access restrictions inflate satellite deployment economics for new constellation operators.
- Optical payload limitations:Persistent cloud cover over metropolitan France and Atlantic maritime zones degrades usable capture windows for electro-optical systems below acceptable availability thresholds.
- GDPR geospatial friction:Automated feature extraction in populated areas triggers CNIL scrutiny, constraining product architectures for urban analytics and personal identification applications.
Strategic Opportunities
- Hyperspectral precision agriculture:Vineyard and cereal cooperative networks in Bordeaux and Champagne regions represent underpenetrated demand for mineral stress and irrigation optimization analytics.
- Maritime surveillance integration:Convergence between automatic identification system data and radar imagery is opening service contracts for Mediterranean and Atlantic fisheries enforcement.
- CSRD disclosure acceleration:Corporate sustainability reporting requirements are forcing listed French enterprises to procure environmental monitoring subscriptions for supply chain verification.
Industry Challenges
- Signal processing talent scarcity:French engineering schools produce insufficient specialists in synthetic aperture radar interferometry and atmospheric correction algorithms for expanding service pipelines.
- Legacy infrastructure integration:Established defense and civil institutional buyers operate proprietary ground systems that resist interoperability with commercial API-based data delivery architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Satellite Imagery Services Market |
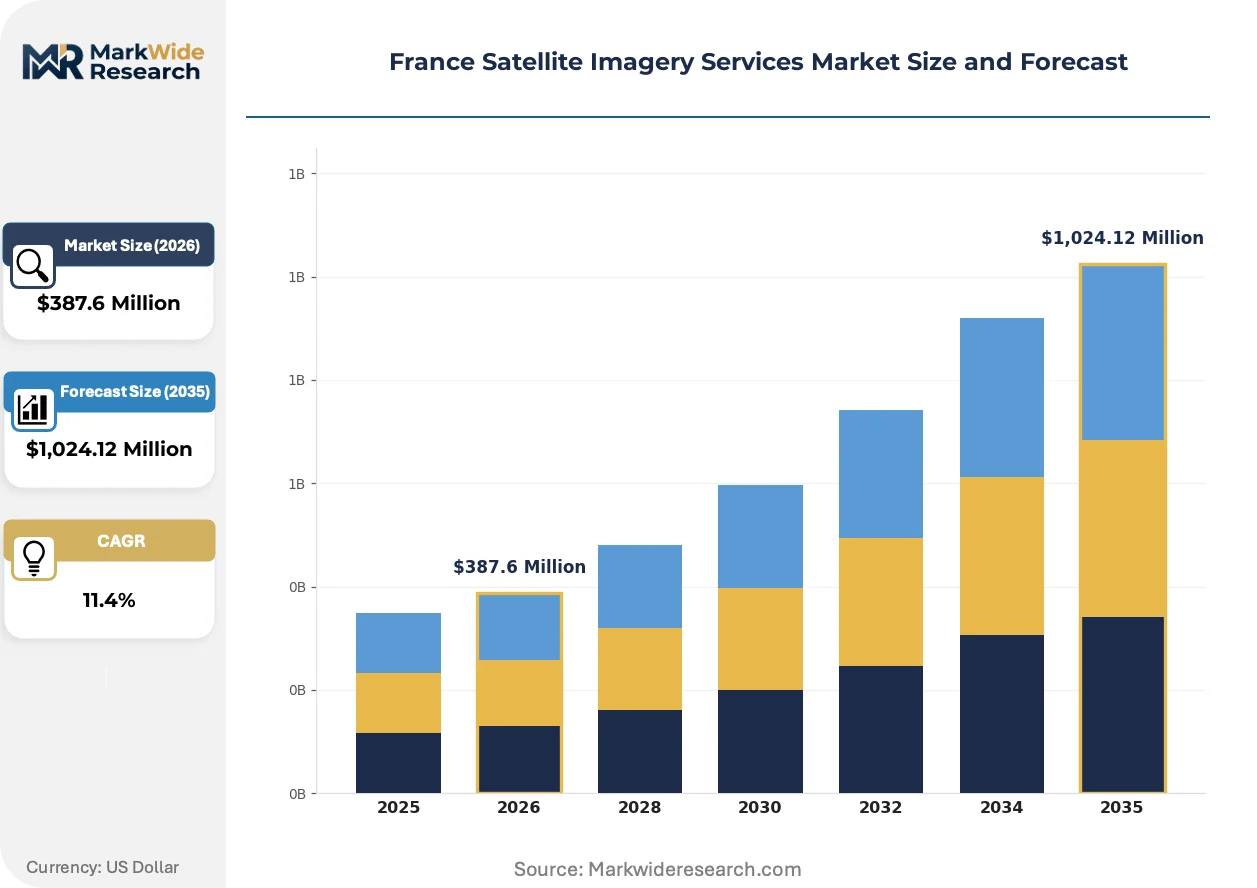
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Imagery Acquisition, Data Processing, Analytics, Custom Solutions End User: Agriculture, Defense, Urban Planning, Environmental Monitoring Technology: Optical, Radar, Hyperspectral, Multispectral Distribution Channel: Direct Sales, Online Platforms, Partnerships, Resellers |
| Companies Covered | CLS, CNES, Airbus Defence and Space, Kermap, IGN, Thales Alenia Space, Spot Image, Maxar Technologies, Telespazio France, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Satellite Imagery Services Market Trends and Innovations
Payload miniaturization and edge computing architectures are compressing the latency between orbital capture and actionable intelligence delivery, shifting competitive advantage from raw spatial resolution to processing speed and vertical-specific algorithm training.
Artificial intelligence inference engines deployed on-board small satellites are unifying image preprocessing and feature detection steps that previously required ground-based supercomputing. French New Space operators are adopting these edge payloads to serve defense and emergency response clients demanding sub-hourly turnaround. This unification is collapsing the traditional value chain separation between satellite operators and downstream analytics providers, forcing incumbents to restructure service offerings around decision-ready outputs rather than pixel deliveries.
CSRD implementation timelines are mandating granular environmental disclosure from French listed companies, creating regulatory pull for standardized satellite-derived land-use and emissions verification products. The European Securities and Markets Authority is drafting technical standards that specify remote sensing methodologies for Scope 3 supply chain reporting. Agricultural processing and construction material sectors face the steepest compliance burdens, driving consortium procurement of multi-year monitoring subscriptions.
Institutional buyers are consolidating vendor relationships around integrated platform contracts that bundle imagery acquisition, analytics, and regulatory reporting preparation. French water agencies and regional planning authorities are displacing fragmented point-solution purchasing with multi-source data fusion services. This consolidation is most visible in the Provence-Alpes-Côte d'Azur and Occitanie regions, where inter-municipal cooperation frameworks aggregate demand across fragmented administrative boundaries.
France Satellite Imagery Services Market Segmentation
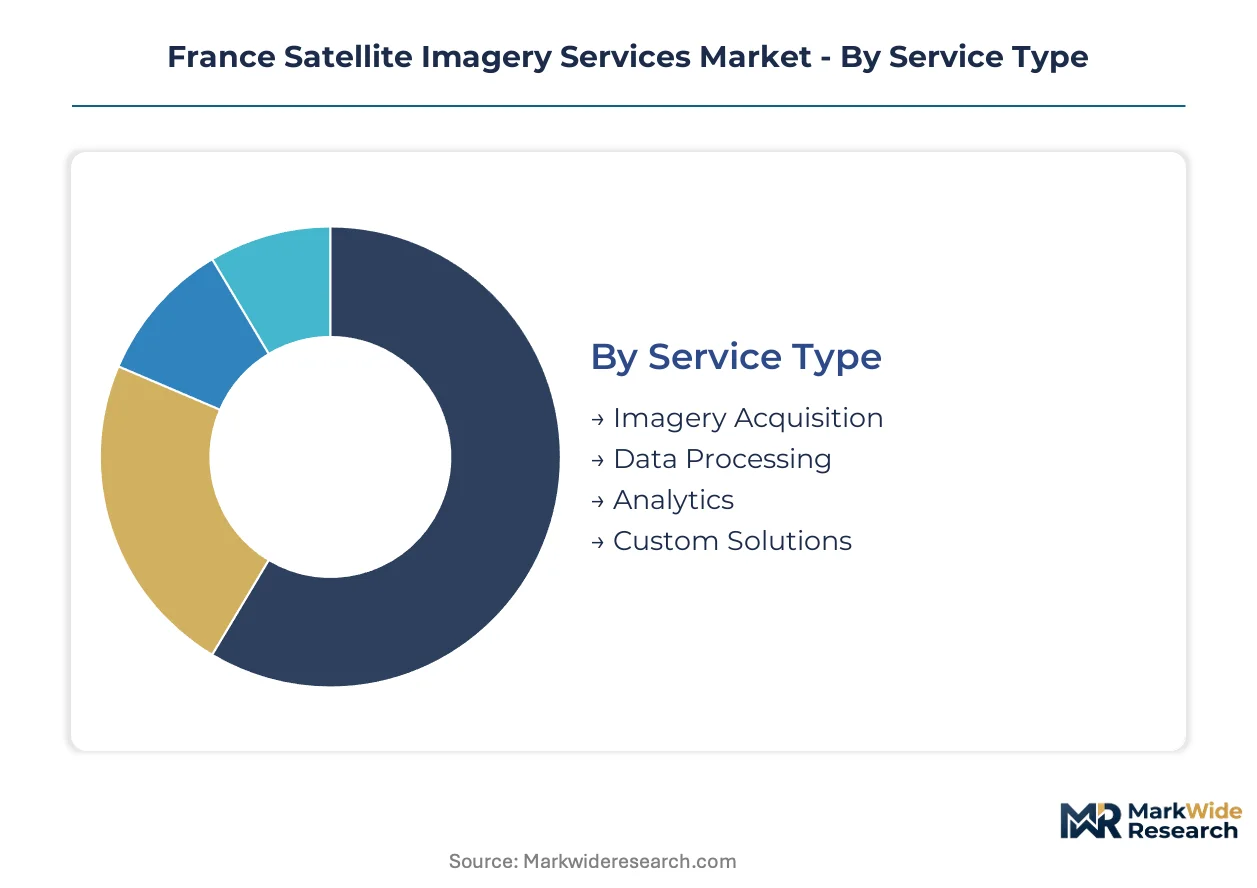
Segmentation in the France Satellite Imagery Services Market reveals distinct procurement patterns across institutional buyers, with defense and environmental agencies driving premium service tiers while agricultural cooperatives optimize for cost-efficient analytics bundles. Understanding these divides enables vendors to align payload investments with buyer readiness for decision-ready intelligence versus raw imagery purchases.
Service Type:
Upgrade cycles in French institutional procurement are compressing as buyers shift from multi-year imagery archives toward subscription-based analytics platforms that refresh underlying algorithms quarterly.
- Imagery Acquisition:Raw orbital capture services resolve features at sub-meter precision across optical, radar, and multispectral bands. French defense procurement under the Ministry of the Armed Forces anchors demand here, though margin pressure intensifies as buyers bundle acquisition with downstream processing.
- Data Processing:Atmospheric correction, orthorectification, and cloud masking transform raw pixels into analysis-ready datasets. Île-de-France aerospace clusters around Toulouse concentrate specialized processing talent, creating geographic supply advantages for domestic operators serving CSRD compliance timelines.
- Analytics:Vertical-specific algorithm outputs include crop stress indices, urban heat maps, and maritime vessel detection. Bordeaux vineyard cooperatives and Champagne cereal networks represent underpenetrated demand for mineral stress and irrigation optimization outputs.
- Custom Solutions:Bespoke integration with proprietary defense ground systems or municipal GIS platforms. Legacy infrastructure interoperability constraints limit addressable market expansion for API-native delivery architectures.
Volume placements concentrate in Imagery Acquisition; the faster expansion belongs to Analytics.
End User:
Cost tier differentiation separates sovereign defense budgets from constrained municipal planning authorities and cooperative agricultural buyers.
- Agriculture:Vineyard and cereal production networks leverage multispectral crop health monitoring for precision irrigation and fertilizer targeting. EU Green Deal land-use verification mandates are pulling French forestry agencies and agricultural cooperatives toward higher-resolution subscription models.
- Defense:Sovereign intelligence architectures require all-weather synthetic aperture radar capabilities with sub-hourly turnaround for maritime surveillance. The Ministry of the Armed Forces embeds satellite imagery into classified operational workflows, creating insulated procurement channels.
- Urban Planning:Regional planning authorities in Provence-Alpes-Côte d'Azur and Occitanie aggregate demand across inter-municipal cooperation frameworks. GDPR constraints on automated feature extraction in populated areas trigger CNIL scrutiny, constraining product architectures.
- Environmental Monitoring:Water agencies and carbon stock verification services for CSRD disclosures. Corporate sustainability reporting requirements are forcing listed French enterprises to procure environmental monitoring subscriptions for supply chain verification.
Defense commands premium pricing tiers; Environmental Monitoring climbs fastest on regulatory compliance timelines.
Technology:
Application-specific performance requirements dictate technology selection, with cloud penetration and spectral resolution driving divergent procurement patterns.
- Optical:Electro-optical systems deliver highest spatial resolution for urban planning and agricultural boundary mapping. Persistent cloud cover over metropolitan France and Atlantic maritime zones degrades usable capture windows below acceptable availability thresholds for certain buyers.
- Radar:Synthetic aperture radar penetrates cloud cover and darkness for all-weather maritime surveillance and infrastructure integrity monitoring. Mediterranean and Atlantic fisheries enforcement contracts are opening at the convergence of automatic identification system data and radar imagery.
- Hyperspectral:Hundreds of narrow spectral bands enable mineral stress detection and precision agriculture optimization. This segment is expanding most quickly as vineyard and cereal cooperative networks adopt subscription models for irrigation and nutrient management.
- Multispectral:Mature agricultural and urban planning demand across red-edge and near-infrared bands. Standardized product offerings face commoditization pressure as processing algorithms improve on legacy capture archives.
Optical retains volume leadership; Hyperspectral posts the steepest expansion trajectory on precision agriculture adoption.
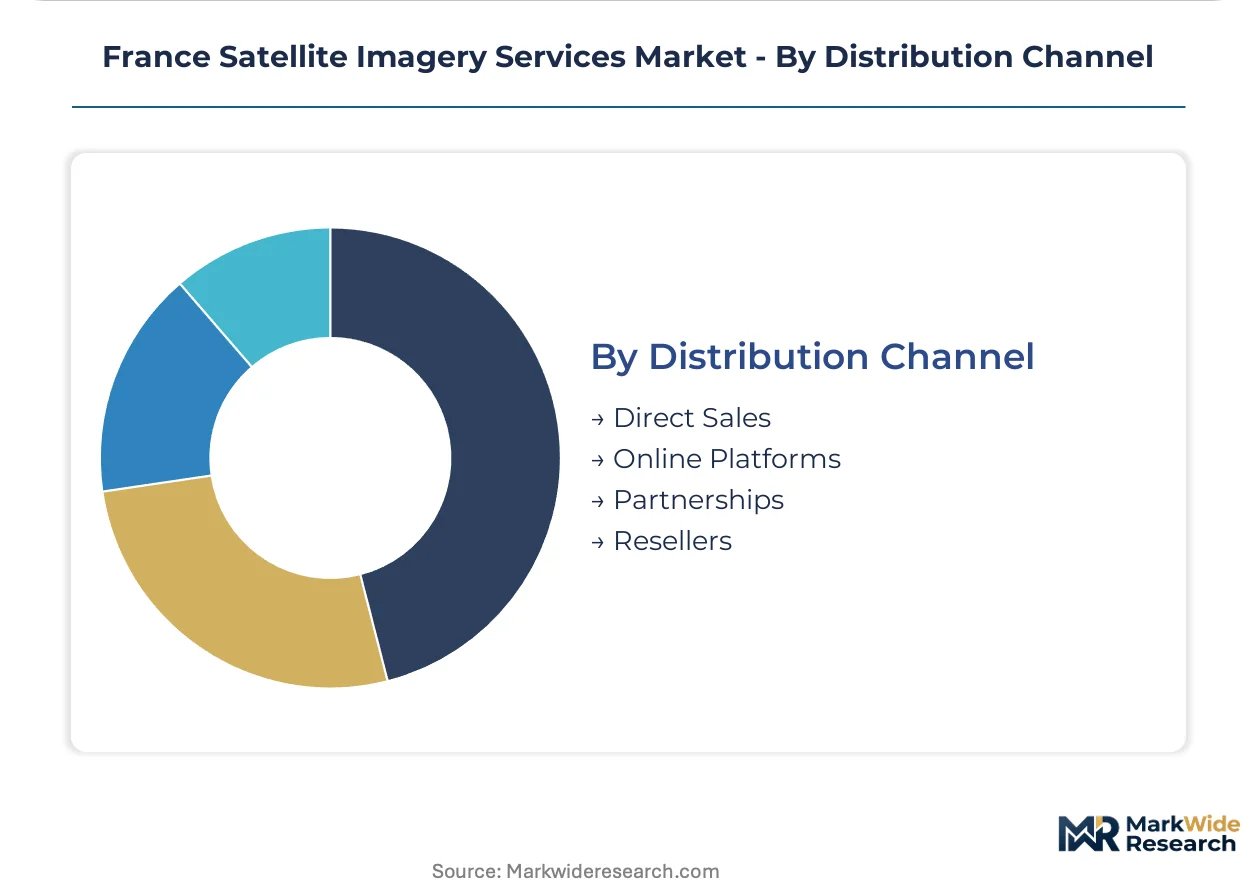
Distribution Channel:
Customer type and procurement scale determine channel selection, with institutional buyers favoring direct relationships and smaller agricultural operators migrating to platform-based access.
- Direct Sales:Long-term framework agreements with defense ministries and national agencies. French Space Operations Act sovereign data localization mandates compel domestic ground segment infrastructure commitments in contract terms.
- Online Platforms:Self-service API access for developers and mid-size agricultural cooperatives. Cloud delivery friction persists as institutional buyers renegotiate access terms against sovereign data requirements.
- Partnerships:System integrators bundle satellite-derived intelligence with ERP and GIS software deployments. Agricultural processing and construction material sectors face the steepest CSRD compliance burdens, driving consortium procurement structures.
- Resellers:Regional specialists serve fragmented municipal planning authorities with localized support. Inter-municipal cooperation frameworks in Occitanie and Provence-Alpes-Côte d'Azur are consolidating vendor relationships around integrated platform contracts.
Direct Sales dominates defense and institutional volume; Online Platforms gain share fastest among agricultural technology adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors France's satellite imagery ecosystem through its concentrated aerospace engineering corridor, where payload development and service commercialization cycles compress delivery timelines for emerging operators.
Île-de-France
Paris-Saclay's research cluster generates specialized signal processing talent for atmospheric correction algorithms, though engineering school output trails expanding service pipeline requirements. CNES headquarters in Paris coordinates national space policy with EU Space Programme compliance frameworks. The metropolitan concentration of defense procurement offices and institutional buyers sustains premium direct sales channels for sovereign intelligence contracts.
Provence-Alpes-Côte d'Azur
Mediterranean maritime surveillance demand converges automatic identification system data with radar imagery for fisheries enforcement contracts. Regional water agencies aggregate procurement across inter-municipal cooperation frameworks, consolidating vendor relationships around integrated platform contracts. Thales Alenia Space operations in Cannes anchor telecommunications satellite integration capabilities for dual-use applications.
Occitanie
Inter-municipal frameworks in this region consolidate fragmented municipal planning authority demand through multi-source data fusion services. GDPR constraints on automated feature extraction trigger CNIL scrutiny for urban analytics applications. The aerospace supply chain connects Toulouse engineering capacity with downstream service delivery for environmental monitoring subscriptions.
Nouvelle-Aquitaine
Bordeaux vineyard cooperative networks represent underpenetrated demand for hyperspectral mineral stress and irrigation optimization analytics. EU Green Deal land-use verification mandates pull agricultural operators toward higher-resolution subscription models for compliance reporting. The region's cereal production networks complement precision agriculture service expansion beyond established optical and multispectral offerings.
Brittany
Atlantic maritime zones expose persistent cloud cover limitations that degrade electro-optical capture availability, driving synthetic aperture radar adoption for all-weather monitoring. Fisheries enforcement agencies procure integrated vessel detection services combining orbital radar with coastal sensor networks. The peninsula's exposure to maritime surveillance requirements sustains defense-adjacent service demand distinct from inland agricultural markets.
France Satellite Imagery Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sovereign defense contract access and proprietary constellation ownership. The vendor base stratifies between state-affiliated entities with guaranteed institutional procurement channels and commercial operators competing on processing speed and vertical algorithm specialization. Three archetypes dominate: sovereign mission operators with classified workflow integration, commercial analytics platforms serving CSRD compliance demand, and New Space constellation ventures compressing capture-to-delivery latency. Competitive moves center on M&A consolidation of downstream analytics capabilities and strategic partnerships embedding satellite-derived intelligence into ERP and GIS software deployments.
Within the sovereign mission tier, CNES and Airbus Defence and Space exemplify state-affiliated positioning through domestic ground segment infrastructure mandated under the French Space Operations Act. Thales Alenia Space occupies a position spanning radar payload integration and telecommunications satellite capabilities. These three entities anchor the premium contract layer where sovereign data localization requirements insulate domestic operators from transnational cloud delivery competition.
| Leading Market Players |
|---|
| CLS |
| CNES |
| Airbus Defence and Space |
| Kermap |
| IGN |
| Thales Alenia Space |
| Spot Image |
| Maxar Technologies |
| Telespazio France |
| Others |
Pricing and Supply Chain Analysis
Signal processing specialists concentrated around Toulouse and Paris-Saclay command wage premiums that propagate through service pricing tiers, compressing margins for operators unable to automate atmospheric correction and orthorectification workflows.
Pricing Analysis
Outcome-based pricing tied to carbon stock verification accuracy anchors premium subscriptions for CSRD compliance buyers. Three-tier pricing structure across premium, standard, and economy levels separates sovereign defense contracts with sub-hourly turnaround guarantees from agricultural cooperative bundles with quarterly refresh cycles. Cost compression in standard-tier analytics is intensifying because hyperspectral payload miniaturization lowers barrier-to-entry for New Space operators. Municipal planning authorities exhibit highest price sensitivity due to inter-municipal budget pooling constraints, while Ministry of the Armed Forces procurement shows lowest elasticity given classified workflow requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision optics suppliers for high-resolution electro-optical payloads. French operators draw from US semiconductor foundries for edge computing chipsets and from Italian composite manufacturers for satellite bus structures. Tariff exposure on radiation-hardened electronics creates procurement uncertainty for constellation expansion timelines. Distribution runs through direct sales frameworks for institutional buyers and API-based platforms for agricultural technology adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated platform contracts as institutional buyers displace fragmented point-solution purchasing, forcing sub-scale analytics providers toward acquisition or exit.
For Market Incumbents: Cement sovereign defense channel insulation through French Space Operations Act compliance certification and domestic ground segment infrastructure investments. Acquire hyperspectral algorithm specialists in Bordeaux and Champagne agricultural networks before CSRD disclosure deadlines consolidate vendor relationships. Threat of New Space latency compression demands edge payload integration to preserve sub-hourly turnaround premiums. For New Entrants and Emerging Players: EU Green Deal verification mandates in France open a window for vineyard cooperative penetration with mineral stress and irrigation optimization analytics. Target maritime surveillance integration in Mediterranean fisheries enforcement where automatic identification system convergence with radar imagery remains underdeveloped. Go-to-market through agricultural technology reseller partnerships bypasses direct competition with Airbus Defence and Space institutional channels. For Investors and Strategic Acquirers: Re-rating potential sits with vertical-specific analytics platforms given CSRD implementation timelines forcing multi-year environmental monitoring subscriptions. Long-term viability favors operators with proprietary algorithm training datasets and regulatory reporting preparation capabilities. Watch European Securities and Markets Authority technical standards publication as inflection indicator for standardized remote sensing methodology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Downstream Analytics Acquisition | Consolidates crop stress algorithm capabilities for Bordeaux vineyard cooperative contracts. |
| Edge Payload Development | Compresses capture-to-delivery latency for Ministry of the Armed Forces maritime surveillance. |
| CSRD Compliance Platform Launch | Bundles imagery acquisition with regulatory reporting for listed French construction material enterprises. |
| Hyperspectral Constellation Deployment | Targets Champagne cereal network demand for irrigation optimization subscriptions. |
| Maritime Surveillance Partnership | Integrates automatic identification system data with radar for Mediterranean fisheries enforcement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with satellite payload engineers at Toulouse aerospace clusters, defense procurement officers at the Ministry of the Armed Forces, vineyard cooperative agronomists in Bordeaux, and water agency planning directors in Provence-Alpes-Côte d'Azur. Secondary sources included CNES annual reports, EU Space Programme compliance documentation, French Space Operations Act implementation guidance, and CSRD technical standard drafts. Bottom-up service revenue estimates triangulated against top-down national space expenditure allocations.
Segment-level modeling operated at technology-by-end-user granularity, with optical, radar, hyperspectral, and multispectral capture volumes projected across defense, agriculture, urban planning, and environmental monitoring applications. CAGRs derived from satellite deployment schedules, institutional procurement cycle analysis, and regulatory compliance timeline acceleration. Payload miniaturization cost curves and edge computing adoption rates informed technology transition assumptions across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for on-board artificial intelligence inference would alter the outlook if ground-based processing cost compression outpaces orbital edge payload reliability improvements. Forecasts reflect assumptions about Ariane 6 launch cadence recovery and EU Green Deal verification mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite GPS Receivers Market
Satellite
Optical Satellite Communication Market
Satellite
Canada Satellite Connectivity Market
Satellite
Communication Satellite Launch Services Market
Satellite
Germany Satellite Communications Market
Satellite
Satellite Manufacturing Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Satellite Link Emulator Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Satellite Operation Service Market
Satellite
Military Satellite Market
Satellite
EMEA Satellite Antenna Market
Satellite
Indonesia Satellite Communications Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Connectivity Market