
 Space Blanket Market | 2026-2036
Space Blanket Market Size, Share, and Industry Trends Forecast 2026-2036
Space Blanket Market Insights
Online retail is rewriting how space blankets reach adventure enthusiasts and first responders alike. DuPont leverages its materials science heritage to sustain premium positioning in thermal insulated variants. Berry Global anchors North American supply through its extensive flexible packaging infrastructure. Sealed Air competes on manufacturing scale, extending its protective packaging expertise into emergency-use formats.
A space blanket is a thin, lightweight sheet constructed from metallized polyethylene terephthalate film, typically vacuum-deposited with aluminum to achieve reflectivity exceeding 90 percent of radiated body heat, designed primarily for emergency thermal management in outdoor, medical, and military contexts. The thermal insulated product type commands the widest margin pool due to multi-layer lamination complexity and certification requirements. Emergency use applications lead volume through institutional contracts with defense and disaster relief agencies. The foil blanket segment remains mature, with price competition intensifying among commodity producers.
The FDA regulates emergency space blankets marketed for hypothermia treatment as Class I medical devices, mandating biocompatibility and performance labeling that elevates compliance costs for new entrants. The EPA's REACH-aligned chemical restrictions on perfluorinated compounds constrain coating options for water-resistant variants. Stakeholders must monitor evolving military procurement specifications from the Department of Defense, as thermal signature requirements increasingly favor advanced metallized films over standard mylar constructions.
Market Dynamics
Emergency medical services are expanding procurement of thermal insulated variants for hypothermia management, while the FDA's medical device classification rules for emergency thermal blankets are tightening quality thresholds. This dual pressure from institutional demand pull and regulatory compliance push is compressing margin structures for commodity producers and elevating certified manufacturers.
Growth Catalysts
- Wilderness Rescue Protocols:United States federal and state agencies mandate space blanket inclusion in backcountry emergency kits, institutionalizing bulk purchasing through standardized equipment lists.
- REACH-Aligned Chemical Restrictions:The EPA's constraints on perfluorinated compounds are accelerating substitution toward metallized PET films with compliant water-resistant coatings.
- Military Cold-Weather Training:Department of Defense procurement specifications favor advanced metallized films over standard mylar constructions for thermal signature management.
Market Restraints
- Aluminum Price Volatility:Vacuum-deposited aluminum metallization depends on commodity metal inputs subject to energy-cost-driven fluctuations.
- Biocompatibility Certification Burden:FDA Class I medical device labeling mandates elevate compliance costs and extend validation timelines for new entrants.
- Commodity Foil Substitution:Basic mylar blankets from flexible packaging converters compete on price in non-certified recreational segments.
Strategic Opportunities
- Disaster Relief Agency Stockpiling:FEMA and international humanitarian organizations are building thermal protection reserves with multi-year supply agreements.
- Multi-Layer Lamination Convergence:Integration of aerogel and phase-change materials with metallized films creates next-generation thermal management products.
- Direct-to-Responder E-Commerce:Specialized platforms bypass traditional medical distributors to reach individual first responders and expedition operators.
Industry Challenges
- Metallization Process Engineering Talent:Vacuum deposition expertise concentrates in legacy packaging and semiconductor industries, creating recruitment competition.
- ISO 13485 Quality System Implementation:Medical device certification requires documented manufacturing controls that stretch thinly capitalized producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Blanket Market |
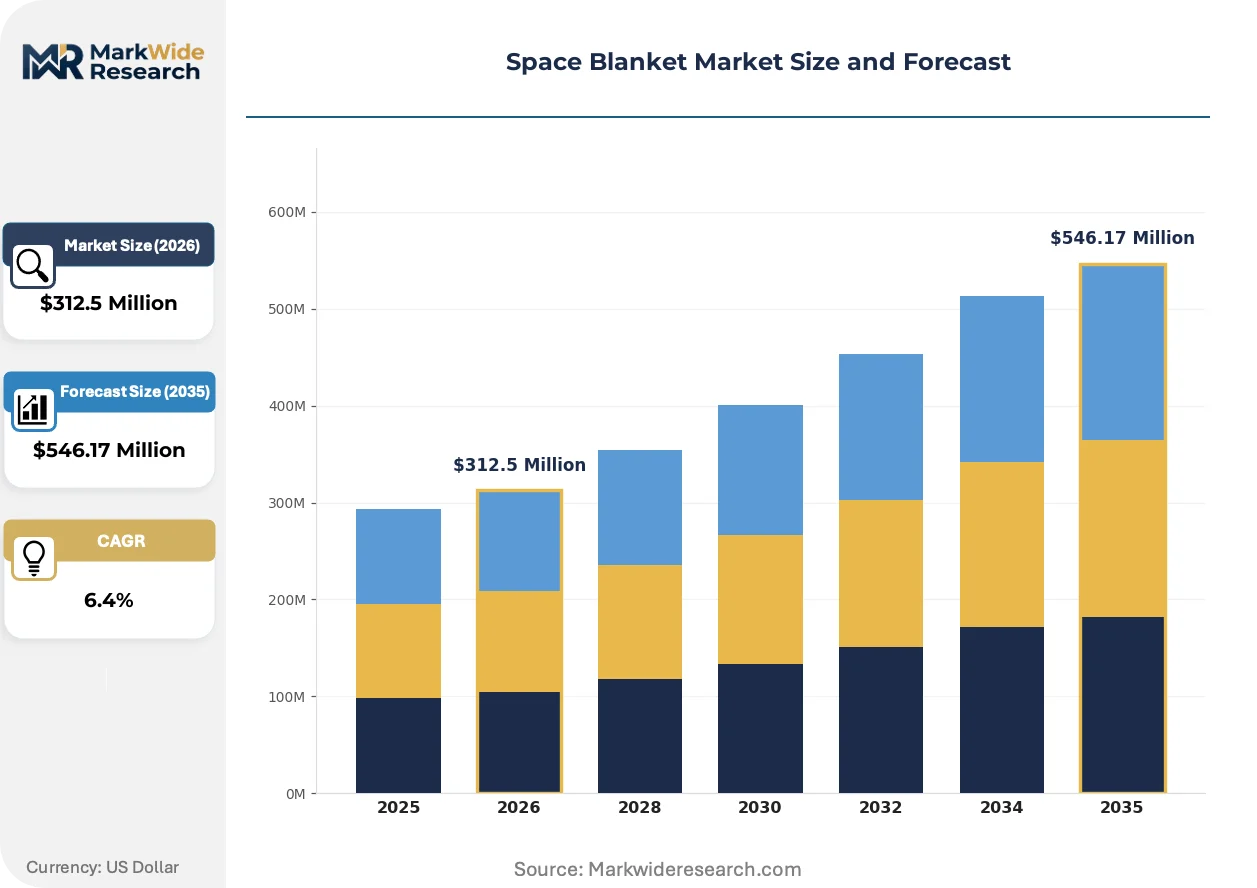
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blanket, Thermal Insulated, Emergency Use, Foil Blanket, Survival Blanket Application: Outdoor Activities, Medical Emergency, Military Operations, Disaster Relief, Sports Events End User: Professional Athletes, First Responders, Defense Personnel, Adventure Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Medical Supply Outlets, Sporting Goods Stores |
| Companies Covered | DuPont, 3M, Avery Dennison, Berry Global, Amcor, Sealed Air, Huhtamaki, Transcontinental, Sonoco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Blanket Market Trends and Innovations
Material science advances are compressing the performance gap between emergency-grade and consumer-grade thermal blankets. Three developments are restructuring how value is created and captured across the supply chain.
Phase-change material integration is virtualizing the traditional thickness-performance tradeoff in thermal insulation. Military procurement offices in the United States and allied nations are piloting these composites for extended-field hypothermia prevention. The technology is virtualizing the market's segmentation logic by enabling thin-film products to achieve previously bulky insulation performance.
The EU Medical Device Regulation's emergency thermal blanket provisions are harmonizing quality documentation requirements across member states. Manufacturers serving European emergency services must now maintain technical files demonstrating radiative heat retention under standardized test conditions. German and French medical device distributors are consolidating supplier bases to reduce audit complexity, favoring producers with established notified body relationships.
Expedition operators and search-and-rescue volunteers are bypassing traditional retail channels through specialized preparedness platforms. These buyers prioritize batch-traceable products with documented metallization thickness and biocompatibility certifications over commodity alternatives. The shift is most pronounced in Rocky Mountain and Pacific Northwest wilderness corridors where professional guide services influence equipment standards.
Space Blanket Market Segmentation
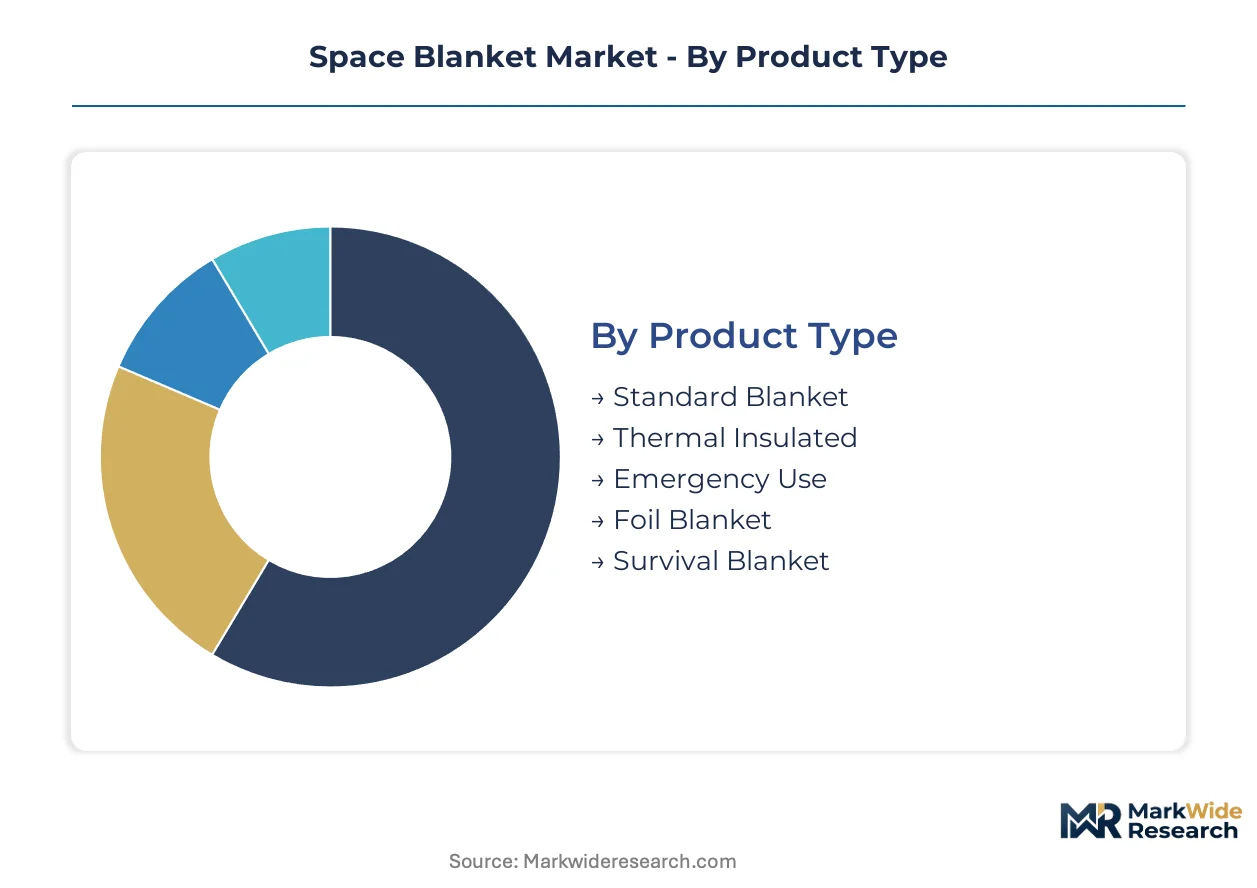
Space blanket manufacturers configure production lines around distinct performance tiers and certification grades. Product architecture decisions cascade through pricing, distribution partnerships, and regulatory compliance pathways.
Product Type:
After-sales service intensity varies sharply across product tiers, with medical-grade variants requiring batch traceability and recall management infrastructure that commodity producers rarely maintain.
- Thermal Insulated:Multi-layer laminates incorporate aerogel or phase-change materials between metallized PET films. United States military cold-weather training programs specify these for extended-field hypothermia prevention, driving procurement volume through Defense Logistics Agency contracts.
- Emergency Use:FDA Class I medical device classification mandates biocompatibility testing and performance labeling for hypothermia treatment claims. Emergency medical services in the United States and European Union favor certified producers with ISO 13485 quality systems, compressing supplier bases.
- Standard Blanket:Single-layer mylar construction targets recreational campers and casual outdoor users through mass retail channels.
- Foil Blanket:Vacuum-deposited aluminum on thin PET film remains the lowest-cost format, with price competition among flexible packaging converters.
- Survival Blanket:Reinforced edges and tear-resistant substrates appeal to backcountry guides and search-and-rescue volunteers in the Rocky Mountain states.
By volume, Foil Blanket leads. By growth pace, Thermal Insulated is expanding most quickly.
Application:
Application segmentation tracks how end-use environments dictate material specifications and certification requirements, with institutional buyers imposing stricter validation than consumer markets.
- Medical Emergency:Hospital systems and ambulance services require documented radiative heat retention under standardized test conditions. German medical device distributors are consolidating supplier bases to reduce audit complexity under EU Medical Device Regulation harmonization.
- Military Operations:Department of Defense procurement specifications increasingly favor advanced metallized films with managed thermal signatures over standard constructions. NATO allied nations are piloting phase-change material composites for extended-field deployment.
- Outdoor Activities:Wilderness rescue protocols in United States national parks mandate space blanket inclusion in backcountry emergency kits.
- Disaster Relief:FEMA and international humanitarian organizations are building thermal protection reserves with multi-year supply agreements.
- Sports Events:Marathon operators and triathlon organizers deploy disposable thermal wraps at finish lines for rapid core temperature management.
Medical Emergency commands the widest margin pool. Military Operations shows the steepest expansion trajectory.
End User:
End user segmentation reveals divergent purchasing behaviors, with institutional buyers prioritizing certification documentation while individual consumers respond to portability and price.
- First Responders:Fire departments and emergency medical technicians require batch-traceable products with documented metallization thickness. Specialized preparedness platforms are bypassing traditional medical distributors to reach this segment directly.
- Defense Personnel:Cold-weather training commands from the Department of Defense drive bulk institutional purchasing with multi-year procurement cycles.
- Adventure Enthusiasts:Expedition operators in Pacific Northwest wilderness corridors influence equipment standards through professional guide service networks.
- Professional Athletes:Elite competitors use thermal management products for recovery protocols, though volume remains limited.
Defense Personnel anchors procurement scale. First Responders are gaining share fastest through direct-to-responder e-commerce channels.
Distribution Channel:
Distribution channel segmentation captures the shift from traditional medical and retail intermediaries toward specialized digital platforms serving institutional and professional buyers.
- Online Retail:Amazon and dedicated preparedness platforms aggregate demand from adventure enthusiasts and individual first responders. These channels prioritize products with visible certification badges and user-submitted field performance reviews.
- Medical Supply Outlets:Cardinal Health and McKesson distribute FDA-registered variants to hospital systems and ambulance services under group purchasing organization contracts.
- Specialty Stores:REI and regional mountaineering retailers curate premium thermal insulated products for serious backcountry users.
- Sporting Goods Stores:Dick's Sporting Goods and Academy Sports move commodity foil blankets through seasonal promotional cycles.
Online Retail leads volume growth. Medical Supply Outlets retain the highest average transaction values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where military procurement specifications command premium thermal insulated variants, while commodity foil blankets from Asian flexible packaging converters compete on thinner margins in recreational segments.
United States
Wilderness rescue protocols mandate space blanket inclusion in backcountry emergency kits across national parks and federal lands. The FDA's Class I medical device classification for hypothermia treatment blankets tightens biocompatibility thresholds. Defense Logistics Agency contracts in Virginia and Maryland drive bulk procurement of advanced metallized films for cold-weather training programs.
Germany
Medical device distributors consolidate supplier bases under EU Medical Device Regulation harmonization to reduce audit complexity. REACH-aligned chemical restrictions from ECHA accelerate substitution away from perfluorinated compounds in water-resistant coatings. Industrial clusters in Bavaria and Baden-Württemberg host flexible packaging converters developing compliant metallized PET films.
China
Flexible packaging infrastructure in the Yangtze River Delta supplies commodity foil blankets to global recreational markets. The country's national standards body aligns metallized film specifications with international quality benchmarks. Zhejiang and Jiangsu provinces concentrate vacuum deposition capacity serving both domestic and export demand.
United Kingdom
Search-and-rescue volunteer networks in Scotland and the Lake District influence equipment procurement standards through professional guide associations. MHRA medical device registration requirements parallel EU MDR documentation burdens post-Brexit. Greater London anchors distribution hubs for European emergency services supply chains.
Japan
METI industrial standards for emergency thermal materials support domestic manufacturers competing on precision metallization. PMDA medical device oversight applies to blankets marketed for clinical hypothermia management. Osaka-based flexible packaging specialists supply both domestic outdoor retailers and regional disaster relief stockpiles.
Space Blanket Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with metallization and lamination expertise. The vendor base spans multinational materials conglomerates, regional flexible packaging converters, and specialized emergency equipment suppliers. Three archetypes dominate: premium-certified medical-grade producers, scale-driven commodity foil manufacturers, and technology-integrated defense contractors. Competitive moves concentrate on ISO 13485 quality system implementation and multi-layer lamination capacity expansion.
Among materials science conglomerates, DuPont and 3M exemplify premium positioning through metallized film heritage and institutional certification relationships. Berry Global anchors North American supply infrastructure through extensive flexible packaging operations. These three occupy positions across the medical-grade and defense procurement tiers where documented radiative heat retention and batch traceability separate certified suppliers from commodity competitors.
| Leading Market Players |
|---|
| DuPont |
| 3M |
| Avery Dennison |
| Berry Global |
| Amcor |
| Sealed Air |
| Huhtamaki |
| Transcontinental |
| Sonoco Products |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's vacuum deposition cluster supplies the metallized PET films that anchor downstream pricing power across emergency thermal blanket tiers. Capacity expansion in Jiangsu and Zhejiang provinces feeds commodity foil blanket production, while certified medical-grade variants draw from tighter metallization specifications that command configured-to-order premiums.
Pricing Analysis
Configured-to-order thermal insulated variants carry spreads exceeding standard foil blankets by multiples reflecting ISO 13485 certification costs and batch-traceability infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates FDA-registered medical devices from recreational-grade commodities. Cost compression in the foil blanket tier intensifies because Asian flexible packaging converters flood recreational channels with undifferentiated mylar products. Emergency medical services exhibit lowest price sensitivity due to liability and protocol requirements, while casual campers drive volume through promotional sporting goods cycles.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for North American medical device distributors. Vacuum deposition capacity concentrates in China, South Korea, and Japan, with raw material dependencies spanning aluminum ingot, PET resin, and phase-change material precursors. Single-source vulnerability in metallization process engineering talent stretches lead times for ISO 13485-certified producers. Distribution runs through Defense Logistics Agency contracts for military procurement, medical supply outlets for hospital systems, and specialized preparedness platforms reaching individual first responders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through direct-to-responder e-commerce channels that bypass traditional medical distributors, as expedition operators and search-and-rescue volunteers demand batch-traceable products with documented certifications over commodity alternatives.
For Market Incumbents: Harden ISO 13485 quality system implementation against emerging flexible packaging converters seeking medical device registration. Expand multi-layer lamination capacity in Virginia and Maryland to capture Defense Logistics Agency contract renewals. Secure backward integration into aerogel and phase-change material supply to defend margin position against substitute thermal management technologies.
For New Entrants and Emerging Players: Pursue disaster relief agency stockpiling contracts with multi-year supply agreements as the most penetrable procurement channel. Target Pacific Northwest wilderness corridor guide services through specialized preparedness platforms with visible certification badges and user-submitted field performance reviews. Leverage direct-to-responder e-commerce to bypass entrenched medical distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ISO 13485-certified producers with established notified body relationships serving European emergency services. Long-term viability over the analysis window favors medical-grade specialists over commodity foil manufacturers facing aluminum price volatility and Asian import competition. Watch FEMA and international humanitarian organization stockpiling announcements as inflection indicators for thermal protection reserve buildouts.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Implementation | Batch traceability and recall management infrastructure separate certified suppliers from commodity competitors in FDA-regulated segments. |
| Multi-Layer Lamination Capacity Expansion | Aerogel and phase-change material integration enables next-generation thermal management products for military cold-weather training programs. |
| Direct-to-Responder E-Commerce Launch | Specialized preparedness platforms bypass Cardinal Health and McKesson to reach individual first responders and expedition operators directly. |
| Defense Logistics Agency Contract Renewal | Department of Defense procurement specifications favor advanced metallized films with managed thermal signatures over standard mylar constructions. |
| REACH-Aligned Coating Substitution | EPA constraints on perfluorinated compounds accelerate compliant water-resistant metallized PET film development for United States and European Union markets. |
Research Methodology
Operator-level perspectives from vacuum deposition engineers, emergency medical services procurement managers, Defense Logistics Agency contracting officers, and flexible packaging plant managers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EPA chemical restriction registers, Defense Federal Acquisition Regulation supplements, and customs trade data. Bottom-up demand modeling across product tiers triangulated with top-down metallized film production capacity estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchors. Segmentation dimensions modeled included product architecture, application environment, end-user purchasing behavior, and distribution channel structure. CAGRs derived from installed base growth, replacement cycle analysis, and procurement specification evolution. Forecast inputs incorporated aluminum commodity price trajectory assumptions and military training program budget allocation patterns.
Sensitivities concentrate around aluminum price volatility, FDA medical device classification rule changes, and Department of Defense procurement specification shifts. Forecasts reflect documented assumptions subject to revision from regulatory, technological, or macroeconomic developments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Mexico Space Electronics Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Carrier Rocket Market
Space
Space Radar Market
Space
Space Sensors Market
Space
Space-Based C4ISR Market
Space
Europe Space Electronics Market
Space
Space Battery Market
Space
Italy Space Electronics Market
Space
Space Ground Station Equipment Market
Space
Space Launch Services Market
Space
Deep Space Robotics Market
Space
Germany Space Electronics Market
Space
Space Management Solutions Market
Space
Space Service Market
Space
Space Colonization Market