
 Spacesuit Market | 2026-2036
Spacesuit Market Size, Share, and Industry Trends Forecast 2026-2036
Spacesuit Market Outlook
NASA's Human Rating Certification is unwinding the competitive field for next-generation lunar spacesuits. Collins Aerospace leverages its pressure garment heritage from Apollo-era programs to sustain bidding credibility on major agency contracts. ILC Dover anchors domestic manufacturing capacity through its long-standing NASA supply relationship. Axiom Space competes by positioning commercial alternatives that navigate fixed-price contracting structures rather than cost-plus award mechanisms.
A spacesuit constitutes a self-contained anthropomorphic spacecraft engineered to maintain human life in vacuum, thermal extremes, and micrometeoroid environments, typically integrating a pressure bladder of urethane-coated nylon, a restraint layer of Dacron, and a thermal micrometeoroid garment of aluminized Mylar and Kevlar to sustain metabolic functions for eight to twelve hours of extravehicular activity. Its primary commercial purpose centers on enabling crewed operations outside pressurized habitats during orbital assembly, planetary surface exploration, and emergency spacecraft egress. Extravehicular Mobility Units retain the largest installed base but face replacement pressure as NASA shifts toward modular architectures, while Space Tourism applications represent the fastest-growing demand pool where private companies seek lighter, shorter-duration configurations. Government Agencies dominate current procurement volumes, though Private Space Companies command disproportionate R&D attention and venture capital flow.
FAA commercial spaceflight regulations, NASA's technical standards for human spaceflight, and ESA's evolving safety directives collectively shape product qualification timelines and market access barriers for new entrants. These frameworks mandate redundant life support validation, crew escape system compatibility, and cross-agency interoperability testing that extends development cycles and capital requirements. Stakeholders must monitor how Artemis contract awards and emerging suborbital passenger safety rules reshape manufacturer backlog composition and certification investment priorities.
Market Dynamics
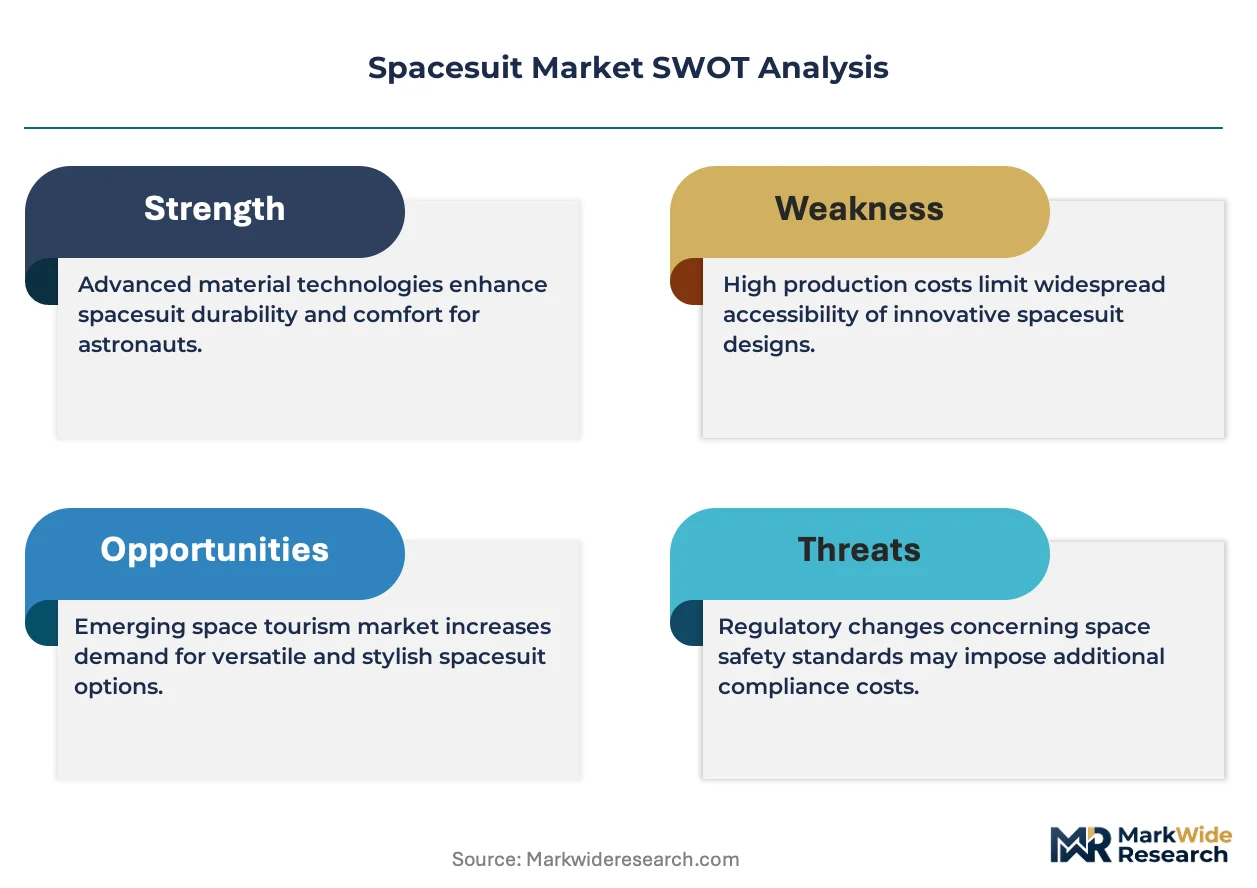
NASA's transition from cost-plus to fixed-price contracting is compressing supplier margins while forcing modular architecture adoption. This procurement pivot redistributes risk toward manufacturers and accelerates consolidation among life-support subsystem vendors.
Growth Catalysts
- Artemis lunar surface mandates:NASA's crewed return requirements sustain multi-year procurement pipelines for next-generation extravehicular mobility systems. Fixed-price contracts attract commercial bidders seeking recurring revenue visibility.
- REACH chemical compliance deadlines:European manufacturers accelerate material substitutions in thermal micrometeoroid garments ahead of 2025 restriction dates. ESA astronaut programs absorb incremental qualification costs.
- Space tourism payload specifications:Suborbital flight operators specify lighter, shorter-duration suit configurations for passenger experience differentiation. Virgin Galactic and Blue Origin procurement teams issue iterative performance requirements.
Market Restraints
- Specialized textile supply concentration:Aluminized Mylar and Kevlar thermal layer production clusters in United States defense-industrial corridors. Single-source dependencies amplify price volatility during Department of Defense procurement surges.
- FAA commercial human spaceflight rulemaking delays:Incomplete occupant safety standards freeze passenger suit certification pathways. Operators defer fleet expansion commitments pending final rule publication.
- Legacy EMU replacement cost structures:International Space Station inventory amortization extends incumbent system lifecycles. NASA budget cycles prioritize Artemis development over near-term extravehicular mobility unit refresh.
Strategic Opportunities
- Chinese Tiangong station interoperability:ESA's 2023 astronaut selection expansion creates demand for suits compatible with both ISS and Chinese docking interfaces. Bilateral mission agreements open qualification pathway diversification.
- In-suit biomedical monitoring convergence:Integration of wearable health sensors with pressure garment systems enables real-time crew performance optimization. MIT and Stanford research consortia pilot fiber-optic vital sign integration.
- India's Gaganyaan program supplier qualification:ISRO's crewed orbital mission timeline creates entry points for pressure garment manufacturers meeting BIS aerospace material standards. Domestic production incentives under PLI scheme reduce import dependency.
Industry Challenges
- Soft goods engineering talent scarcity:Apollo-era pattern makers and seamstress specialists retire without pipeline replacement. Technical universities lack accredited programs combining textile engineering with human factors design.
- Human-rating certification timeline compression:NASA's 2024 lunar surface readiness targets force parallel rather than sequential testing protocols. Redundant life support validation requires simultaneous thermal vacuum and neutral buoyancy facility access.
- Cross-agency interoperability standards fragmentation:ESA's evolving safety directives diverge from NASA technical standards on glove dexterity metrics. Dual-certification requirements duplicate engineering validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spacesuit Market |
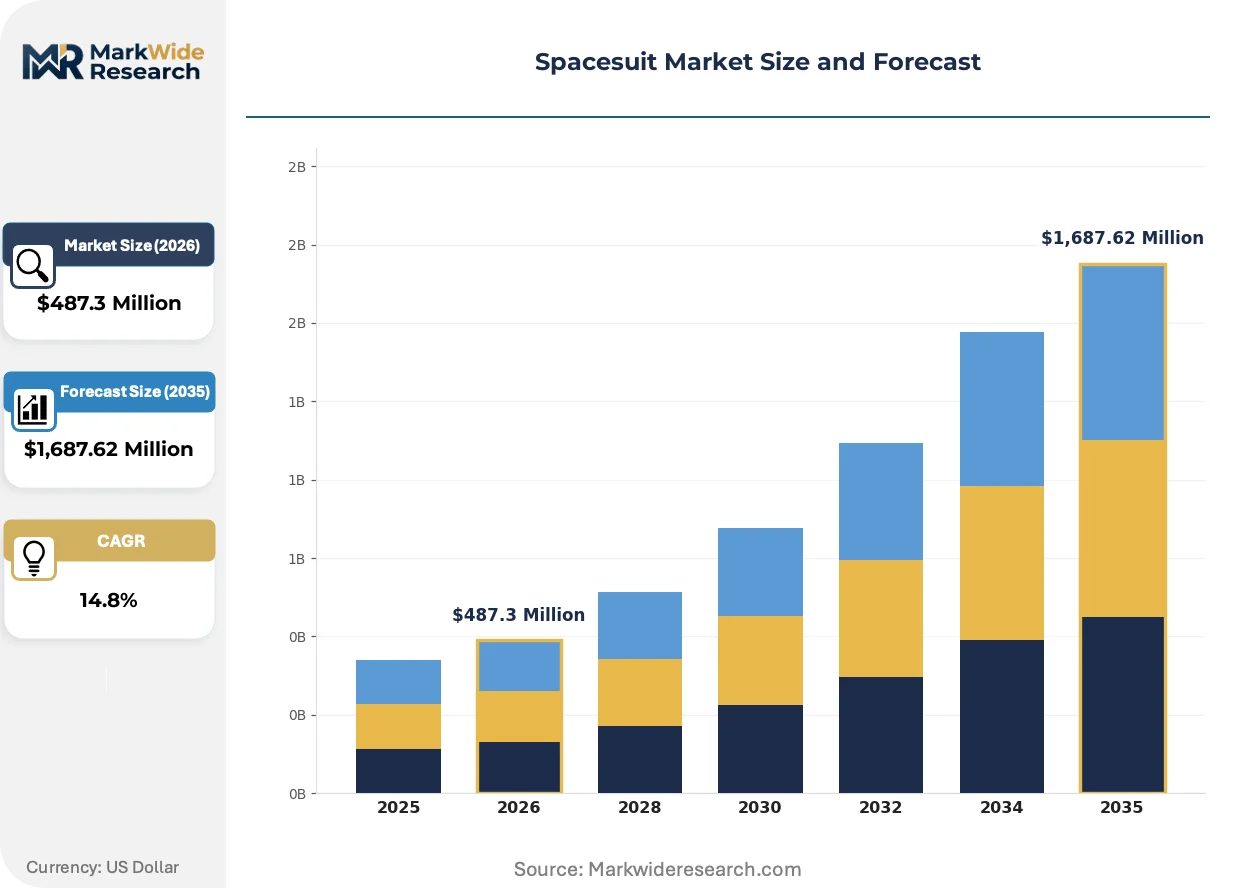
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,687.62 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extravehicular Mobility Unit, Pressure Garment, Thermal Control Layer, Helmet Application: Space Exploration, Astronaut Training, International Space Station, Space Tourism End User: Government Agencies, Private Space Companies, Research Institutions, Educational Organizations Technology: Advanced Fabrics, Life Support Systems, Communication Devices, Safety Harness |
| Companies Covered | Axiom Space, Collins Aerospace, David Clark Company, ILC Dover, RTX Corporation, Oceaneering International, The Boeing Company, Lockheed Martin, Zvezda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spacesuit Market Strategic Shifts
Digital engineering workflows are compressing prototype-to-qualification cycles while enabling mass-customization of anthropometric fits. These capabilities reshape competitive differentiation away from heritage performance toward adaptive manufacturing responsiveness.
Soft robotic actuation layers embedded in pressure garment joints is supplanting traditional hard-bearing mobility architectures. NASA's xEMU development program and commercial lunar service providers adopt electroactive polymer muscle systems for enhanced dexterity. This transition reduces suit mass while expanding operational range across kneeling and climbing surface activities previously excluded from extravehicular task profiles.
FAA's 2023 supplemental notice of proposed rulemaking on crew and spaceflight participant safety introduces explicit physiological monitoring requirements for commercial operations. Suborbital operators must demonstrate real-time biometric data transmission capabilities during powered flight phases. Passenger suit manufacturers integrate fiber-optic sensing arrays to satisfy these mandates, with Mojave Desert test ranges serving as primary validation sites.
Fixed-price milestone contracting now dominates NASA's Exploration Extravehicular Activity Services procurement methodology. Traditional cost-plus heritage relationships yield to performance-based payment schedules tied to design review completion. This restructuring concentrates contract awards among entities with balance sheet capacity to absorb development risk, with Houston and Denver aerospace clusters capturing disproportionate program management roles.
Spacesuit Market Segmentation
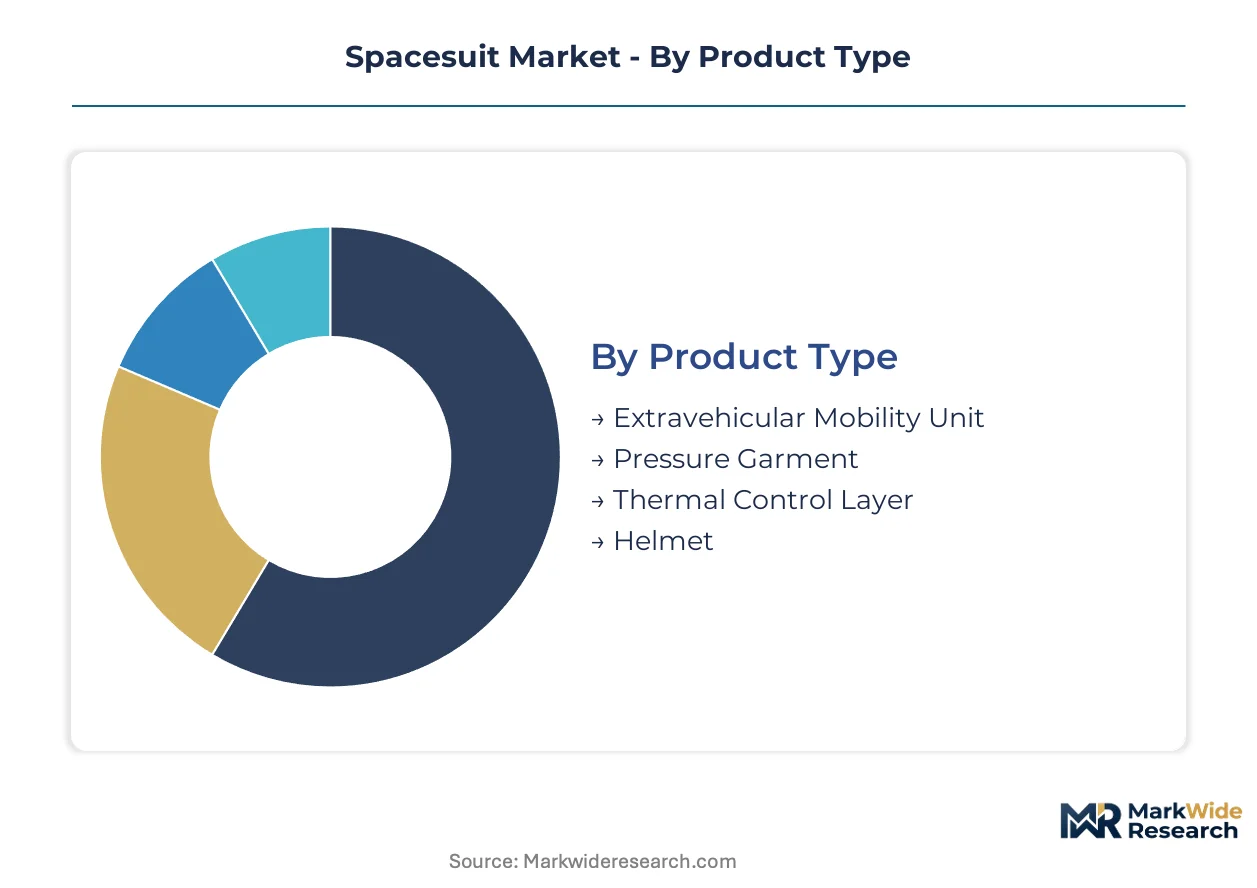
Spacesuit procurement flows through distinct channels that favor different product configurations. Government contracts anchor high-specification systems while commercial operators drive demand for lighter, shorter-duration alternatives.
Product Type:
Channel mix varies sharply by product complexity, with integrated systems flowing through NASA's fixed-price contracting and modular components reaching private operators through direct manufacturer relationships.
- Extravehicular Mobility Unit:Self-contained anthropomorphic spacecraft integrating pressure bladder, restraint layer, and thermal micrometeoroid garment. NASA's Artemis program sustains multi-year procurement pipelines for lunar-capable configurations, with fixed-price contracts redistributing development risk toward manufacturers.
- Pressure Garment:Urethane-coated nylon bladder with Dacron restraint layer forming the suit's structural core. ILC Dover and Collins Aerospace compete on heritage credentials for government agency awards, while commercial bidders seek entry through modular architecture offerings.
- Thermal Control Layer:Aluminized Mylar and Kevlar composite managing thermal extremes and micrometeoroid protection.
- Helmet:Polycarbonate pressure shell with gold-coated visor assembly for solar radiation filtering.
By volume, Pressure Garment leads due to replacement cycling. By growth pace, Extravehicular Mobility Unit is ahead on Artemis program acceleration.
Application:
Cost tier stratification separates billion-dollar government exploration programs from suborbital tourism operations seeking passenger experience differentiation.
- Space Exploration:Lunar surface and deep-space missions requiring eight-to-twelve-hour metabolic support and redundant life support validation. NASA's Human Rating Certification mandates drive qualification timelines and capital requirements for this tier.
- Space Tourism:Suborbital and orbital passenger experiences demanding lighter, shorter-duration configurations. Virgin Galactic and Blue Origin procurement teams issue iterative performance requirements, with FAA physiological monitoring rules reshaping sensor integration specifications.
- Astronaut Training:Neutral buoyancy facility and vacuum chamber simulations for mission rehearsal.
- International Space Station:Legacy EMU inventory sustaining orbital assembly and maintenance operations.
By contract value, Space Exploration dominates. By expansion trajectory, Space Tourism is climbing the fastest on venture capital inflows.
End User:
Customer type determines procurement methodology, with government agencies favoring cost-plus heritage relationships and private operators adopting fixed-price milestone structures.
- Government Agencies:NASA, ESA, and ISRO procurement anchoring manufacturer order books through multi-year exploration program commitments. NASA's shift toward modular architectures and fixed-price contracting compresses supplier margins while concentrating awards among balance-sheet-capable entities.
- Private Space Companies:Axiom Space and commercial lunar service providers seeking commercial alternatives outside traditional cost-plus mechanisms. These operators command disproportionate R&D attention despite smaller current volumes.
- Research Institutions:MIT and Stanford consortia piloting fiber-optic vital sign integration for biomedical monitoring convergence.
- Educational Organizations:University programs and museum exhibits driving limited demand for training replicas and display units.
By procurement volume, Government Agencies lead. By technology investment intensity, Private Space Companies is gaining share fastest.
Technology:
Maturity gradients separate proven textile architectures from emerging electroactive polymer and fiber-optic sensing systems still navigating qualification protocols.
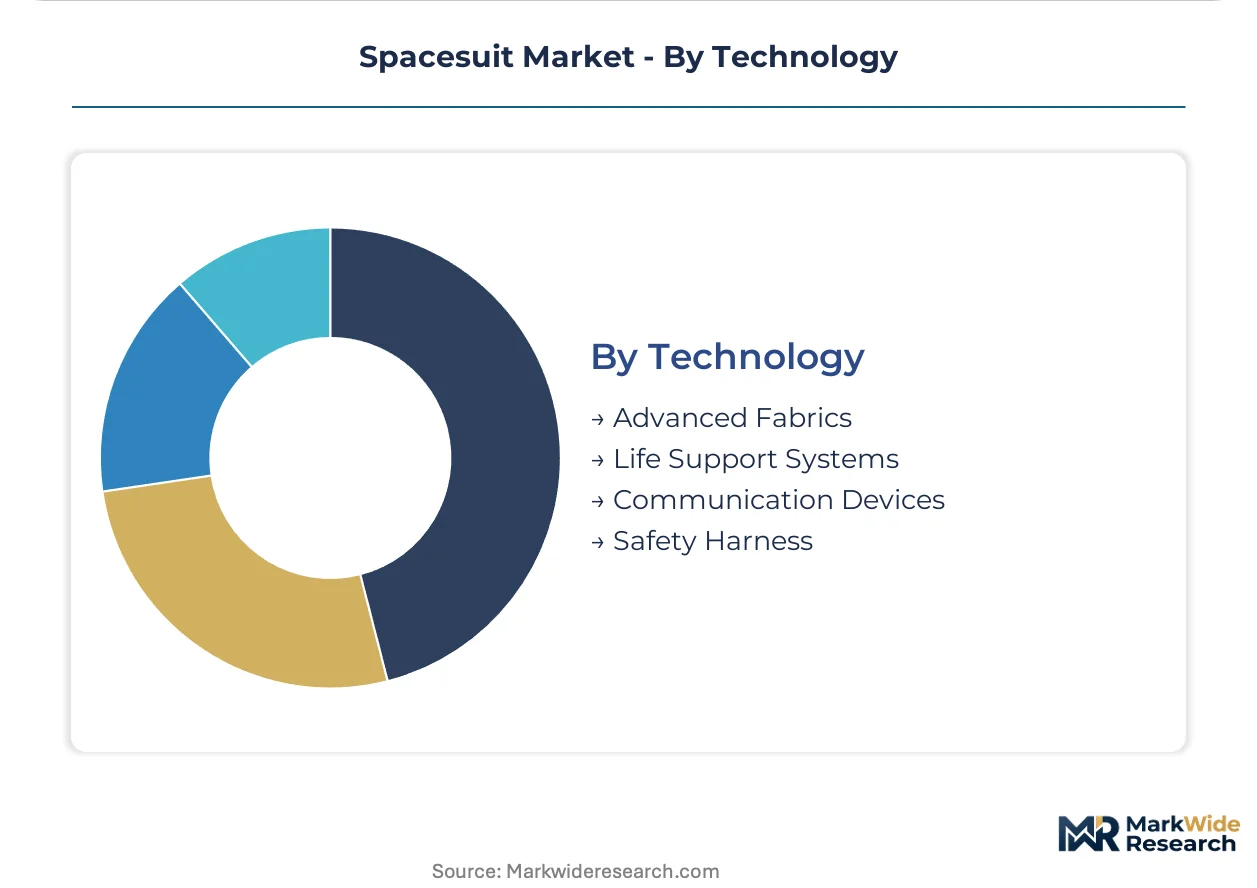
- Life Support Systems:Oxygen generation, carbon dioxide scrubbing, and thermal regulation subsystems forming the critical path for human-rating certification. NASA's parallel testing protocols under 2024 readiness targets force simultaneous thermal vacuum and neutral buoyancy validation.
- Advanced Fabrics:Soft robotic actuation layers with electroactive polymer muscle systems supplanting hard-bearing mobility architectures. NASA's xEMU development program and commercial lunar providers adopt these for enhanced dexterity across kneeling and climbing surface activities.
- Communication Devices:Radio frequency and fiber-optic data transmission systems integrated with biomedical monitoring arrays.
- Safety Harness:Restraint and tether systems for emergency spacecraft egress and surface fall protection.
By installed base, Advanced Fabrics leads. By development priority, Life Support Systems shows the steepest expansion trajectory on human-rating mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement teams and private space operators concentrate their spacesuit demand across five national markets, each shaped by distinct human-rating certification regimes and exploration program timelines.
United States
NASA's Artemis program sustains the largest extravehicular mobility unit procurement pipeline, with fixed-price contracts redistributing development risk toward manufacturers. FAA commercial spaceflight regulations mandate real-time physiological monitoring for suborbital passenger operations, reshaping sensor integration specifications. Houston and Denver aerospace clusters capture disproportionate program management roles as balance-sheet-capable entities absorb milestone-based payment schedules.
China
Tiangong station construction accelerates demand for life support systems compatible with both orbital and lunar surface operations. MIIT technical standards for crewed spacecraft equipment establish domestic qualification pathways that reduce import dependency. Beijing-Tianjin-Hebei industrial corridor concentrates pressure garment manufacturing capacity under state-directed aerospace conglomerates.
India
ISRO's Gaganyaan crewed orbital mission timeline creates entry points for pressure garment manufacturers meeting BIS aerospace material standards. PLI scheme production incentives reduce import dependency for thermal micrometeoroid garment components. Bengaluru and Hyderabad satellite manufacturing hubs extend their electronics integration capabilities toward life support subsystem development.
Germany
ESA astronaut selection expansion generates demand for suits compatible with both ISS and Chinese docking interfaces. REACH chemical compliance deadlines accelerate material substitutions in thermal layers ahead of restriction dates. Bavaria and North Rhine-Westphalia defense-industrial corridors host specialized textile suppliers serving dual-use aerospace applications.
Japan
METI space industry development programs channel funding toward soft robotic actuation research for enhanced suit dexterity. JIS standards for human spaceflight equipment align with NASA technical specifications to enable cross-agency interoperability. Nagoya aerospace manufacturing belt supplies precision components for pressure garment restraint layer fabrication.
Spacesuit Market Competitive Environment
Player mix skews toward heritage aerospace contractors with established NASA supply relationships, creating a tiered structure where fixed-price contract capacity determines award concentration. Consolidation pressures mount among life-support subsystem vendors as modular architecture adoption accelerates. Two strategic archetypes dominate: balance-sheet-capable prime contractors absorbing development risk, and commercial alternatives navigating milestone-based procurement outside cost-plus mechanisms. Competitive moves center on strategic partnerships for neutral buoyancy facility access and geographic expansion into emerging national space programs.
Within the heritage contractor tier, Collins Aerospace leverages pressure garment credentials from Apollo-era programs to sustain bidding credibility on major agency awards. ILC Dover anchors domestic manufacturing capacity through its long-standing NASA supply relationship. Axiom Space occupies a position representing commercial alternatives that navigate fixed-price contracting structures rather than cost-plus award mechanisms, exemplifying the emerging challenger archetype in next-generation lunar suit development.
| Leading Market Players |
|---|
| Axiom Space |
| Collins Aerospace |
| David Clark Company |
| ILC Dover |
| RTX Corporation |
| Oceaneering International |
| The Boeing Company |
| Lockheed Martin |
| Zvezda |
| Others |
Value Chain & Pricing Dynamics
Apollo-era manufacturing scale economies in Delaware and Houston pressure garment facilities anchor both supply concentration and price floors for lunar-capable systems. NASA's fixed-price contract migration compresses margins across tier-one suppliers while concentrating awards among balance-sheet-capable entities with captive thermal layer production.
Pricing Analysis
Cost-plus contracts with CPI indexation historically governed NASA extravehicular mobility unit procurement, though fixed-price milestone structures now dominate Artemis awards. Price differentiation centers on human-rating certification tier and life support redundancy level, with lunar-surface configurations commanding substantial premiums over orbital alternatives. Pricing pressure intensifies as commercial bidders absorb development risk to secure recurring revenue visibility. Government agencies exhibit lowest price sensitivity given mission-critical requirements, while suborbital tourism operators demonstrate acute cost consciousness on passenger suit specifications.
Supply Chain Analysis
Aluminized Mylar and Kevlar thermal layer production chokepoints in United States defense-industrial corridors tether global supply to Department of Defense procurement cycles. Critical inputs draw from domestic urethane-coated nylon suppliers, Dacron restraint layer weavers, and electroactive polymer research consortia. Single-source vulnerability in specialized textile engineering talent amplifies disruption risk during qualification surges. Distribution runs through NASA's Exploration Extravehicular Activity Services contracting vehicle and direct manufacturer relationships with commercial lunar service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market enters cyclical recovery driven by Artemis program procurement acceleration following pandemic-delayed qualification timelines. Multi-year government exploration commitments provide demand visibility absent from prior budget-constrained cycles.
For Market Incumbents: Compound heritage credentials through neutral buoyancy facility partnerships that lock out emerging competitors from parallel testing protocols. Deepen backward integration into electroactive polymer muscle systems to capture modular architecture value migration away from hard-bearing joint suppliers. Fixed-price contract absorption capacity remains the decisive competitive moat as milestone-based payment schedules concentrate awards.
For New Entrants and Emerging Players: Differentiate on commercial lunar service provider relationships outside NASA's traditional cost-plus supplier base. ISRO's Gaganyaan program supplier qualification and ESA's Chinese docking interface compatibility requirements represent the most penetrable entry vectors. Pursue direct manufacturer relationships with fixed-price milestone structures rather than heritage agency supply chain integration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors soft robotic actuation specialists with fiber-optic sensing integration capabilities over legacy hard-bearing mobility architectures. Long-term viability hinges on qualification pathway diversification across multiple national space programs rather than single-agency dependency. Watch FAA commercial human spaceflight rulemaking finalization as the signal for suborbital passenger suit certification demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Adoption | NASA's fixed-price contracting rewards suppliers with interchangeable life support subsystems across mission profiles. |
| Soft Robotic Actuation Investment | Electroactive polymer muscle systems displace hard-bearing joints for kneeling and climbing surface mobility. |
| Cross-Agency Interoperability Qualification | ESA-Chinese docking interface compatibility opens revenue streams outside NASA procurement cycles. |
| In-Suit Biomedical Monitoring Integration | FAA physiological monitoring mandates drive fiber-optic sensor array adoption for suborbital operations. |
| Neutral Buoyancy Facility Partnership | Parallel testing protocol access compresses human-rating timelines under 2024 readiness targets. |
Study Parameters
A spread of perspectives from NASA procurement officers, ESA astronaut program managers, pressure garment engineering leads, commercial lunar service provider executives, and FAA regulatory affairs specialists converged on the working assumptions. Secondary validation drew from NASA contract award announcements, FAA docket filings on commercial spaceflight rulemaking, ESA technical standards documentation, and MIT-Stanford research consortium publications. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type complexity tier, application mission duration and environment severity, end user procurement methodology, and technology maturity gradient. CAGRs were derived from procurement pipeline analysis and exploration program timeline alignment across the projection horizon. Forecast inputs incorporated Artemis contract award schedules, REACH chemical restriction implementation timelines, and Gaganyaan mission supplier qualification windows.
Material uncertainties — FAA rulemaking finalization delays, Artemis budget reallocation, and electroactive polymer qualification failures — sit outside the modeled envelope. Forecasts reflect assumptions about fixed-price contract migration pace and modular architecture adoption rates. Practitioners should keep alternative scenarios live as bilateral mission agreements and suborbital passenger safety standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space-Based Smart Sensors Market
Space
Space Launch Services Market
Space
Europe Space Logistics Market
Space
Space Oscillator Market
Space
Europe Space Electronics Market
Space
Canada Space Electronics Market
Space
Mexico Space Electronics Market
Space
Space Blanket Market
Space
India Space Electronics Market
Space
Space Mobile Service Market
Space
Space Debris Monitoring and Removal Market
Space
Asteroid Mining Market
Space
China Space Propulsion System Market
Space
Space Rover Market
Space
US Reusable Launch Vehicle Market
Space
UK Space Electronics Market