
 India Space Electronics Market | 2026-2036
India Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
India Space Electronics Market Insights
Modular subsystem packaging is broadening buyer choice across launch vehicle and satellite programs. Bharat Electronics leverages its defense electronics heritage to anchor high-reliability power supply contracts for ISRO missions. Data Patterns competes through vertical integration into PCB fabrication and precision mechanical assemblies for space-qualified enclosures. Centum Electronics specializes in radiation-hardened microelectronics, sustaining R&D intensity that differentiates its FPGA-based signal processing modules from commercial-grade alternatives.
India space electronics encompasses components and subsystems engineered to withstand extreme thermal cycling, vacuum conditions, and ionizing radiation while maintaining operational integrity across orbital lifespans typically exceeding five years. These systems employ hermetic sealing, tantalum capacitors, and silicon-on-insulator fabrication to achieve total ionizing dose tolerance exceeding 100 krad(Si), serving critical functions in telemetry, attitude control, and payload data handling. Communication systems command substantial margin pools given the complexity of Ka-band and X-band transponder design for Indian remote sensing satellites. Radiation-hardened technology leads investment priority as domestic foundry partnerships mature under government funding. Satellite systems applications absorb the largest procurement volumes, though launch vehicle electronics represent the fastest-growing segment with the emergence of private orbital launch providers.
BIS certification requirements and ISRO's vendor qualification protocols shape product standards, mandating extended thermal vacuum testing and vibration screening for all space-grade components. The Department of Space's liberalized FDI norms and NSIL's commercialization mandate are reconfiguring market access, enabling private firms to bid directly for satellite manufacturing contracts previously reserved to public sector units. Stakeholders must monitor how the proposed Indian Space Activities Bill codifies liability frameworks and spectrum allocation rules for private constellation operators.
Market Dynamics
ISRO's vendor indigenization mandate is compressing foreign component share across satellite bus and payload electronics, forcing domestic suppliers to absorb qualification timelines previously managed through imported heritage parts.
Growth Catalysts
- PLI Scheme for Specialty Steel and Electronics:Production-linked incentives covering space-grade alloys and semiconductor packaging materials reduce landed cost differentials versus imported alternatives.
- Ka-band satellite constellations:NSIL's commercialization push for high-throughput broadband satellites multiplies demand for indigenous transponder and antenna electronics.
- Bengaluru-Hyderabad corridor concentration:Proximity of ISRO headquarters, DRDO labs, and private launch vehicle developers creates supplier ecosystem density unmatched elsewhere in India.
Market Restraints
- Tantalum capacitor supply:Global ore concentration in Central Africa and limited domestic refining capacity expose Indian manufacturers to price volatility and export control risks.
- Single-source foundry dependency:Domestic radiation-hardened ASIC fabrication remains concentrated at one government-owned semiconductor facility with constrained throughput.
- BIS certification timelines:Extended thermal vacuum and vibration testing protocols add 18-24 months to product qualification, delaying revenue recognition for new entrants.
Strategic Opportunities
- Small satellite launch vehicle electronics:Private orbital launch providers in Andhra Pradesh and Tamil Nadu require flight-proven avionics at commercial price points below traditional ISRO missions.
- Space Policy 2023 liberalization:Direct bidding rights for private firms on satellite manufacturing contracts previously reserved to public sector units.
- FPGA-ASIC convergence:Reconfigurable radiation-tolerant computing platforms enable single hardware designs to serve multiple mission profiles without full respin.
Industry Challenges
- Radiation effects engineering talent:Domestic universities graduate fewer than fifty specialists annually in total ionizing dose modeling and single-event upset mitigation.
- Legacy MIL-STD-883D integration:Newer commercial-off-the-shelf components require extensive requalification to interface with ISRO's established subsystem architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Space Electronics Market |
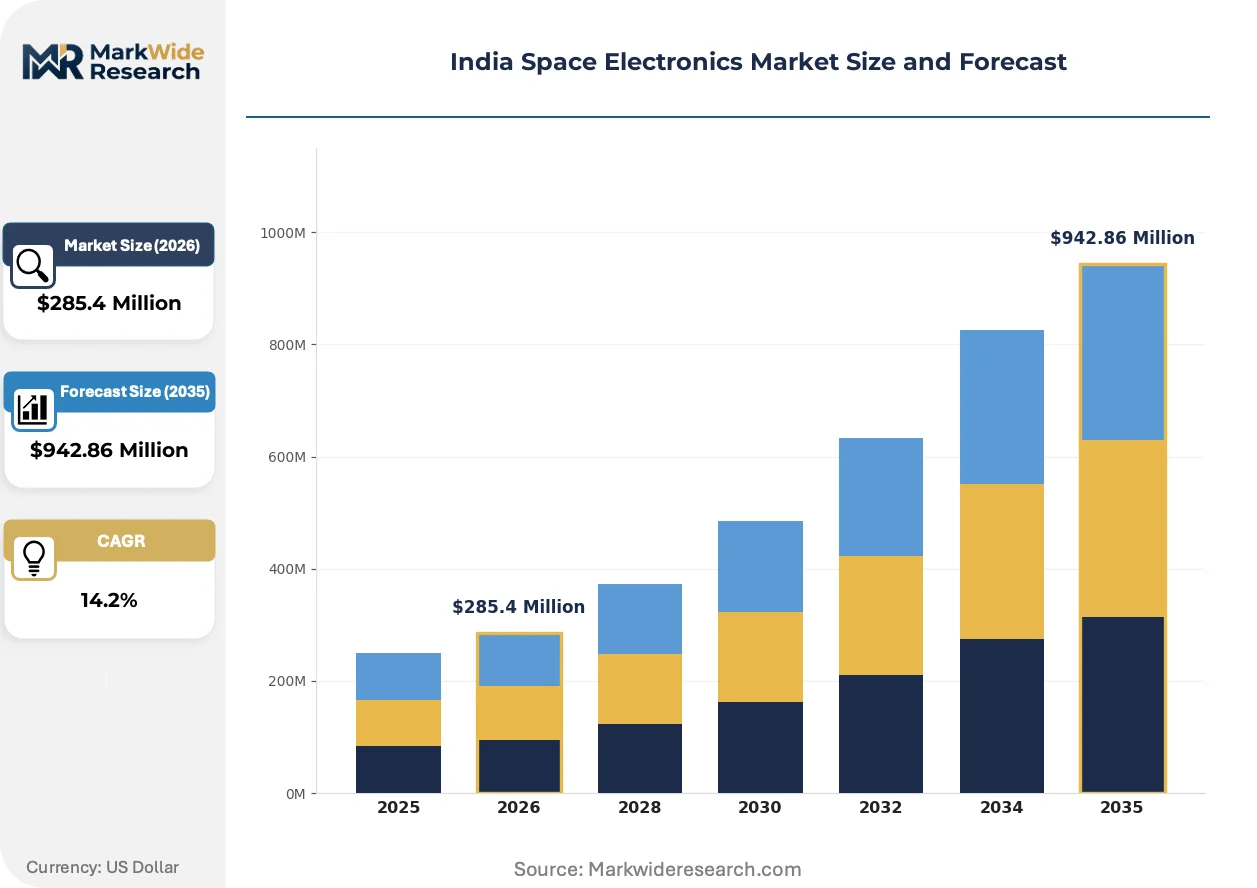
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $942.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processors, Power Supply Units, Communication Systems, Sensors Technology: Microelectronics, FPGA, ASIC, Radiation-Hardened Application: Satellite Systems, Launch Vehicles, Ground Stations, Research Programs End User: Government Agencies, Private Companies, Defense Forces, Research Institutions |
| Companies Covered | Bharat Electronics, Centum Electronics, Data Patterns, Ananth Technologies, Alpha Design Technologies, Paras Defence and Space Technologies, Tata Advanced Systems, Larsen and Toubro Defence, Godrej Aerospace, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Space Electronics Market Trends and Innovations
Packaging architectures and procurement protocols are diverging from heritage space industry templates as private launch economics and accelerated mission cadences reshape supplier relationships.
Silicon-on-insulator fabrication processes for radiation-hardened microcontrollers are modularizing subsystem designs across ISRO's upcoming remote sensing satellites. Satellite integrators now specify standardized pin-compatible modules rather than custom ASICs for attitude determination functions. This modularity is compressing procurement cycles from multi-year development contracts to catalog-based component selection.
The Department of Space's revised FDI norms now permit 74 percent foreign investment in satellite manufacturing ventures without prior approval. This policy shift enables technology transfer partnerships with European and Israeli radiation-hardened component specialists. Domestic firms in Hyderabad's defense electronics corridor are responding by deepening captive testing capabilities to maintain qualification autonomy.
Consolidated mission procurement by NSIL is displacing the historical project-by-project tendering model that fragmented demand across ISRO centers. Large satellite operators now negotiate multi-mission component supply agreements spanning five-year horizons. This concentration is most visible in Bengaluru, where three major integrators have shifted from transactional vendor relationships to strategic supply partnerships with radiation-hardened power supply specialists.
India Space Electronics Market Segmentation
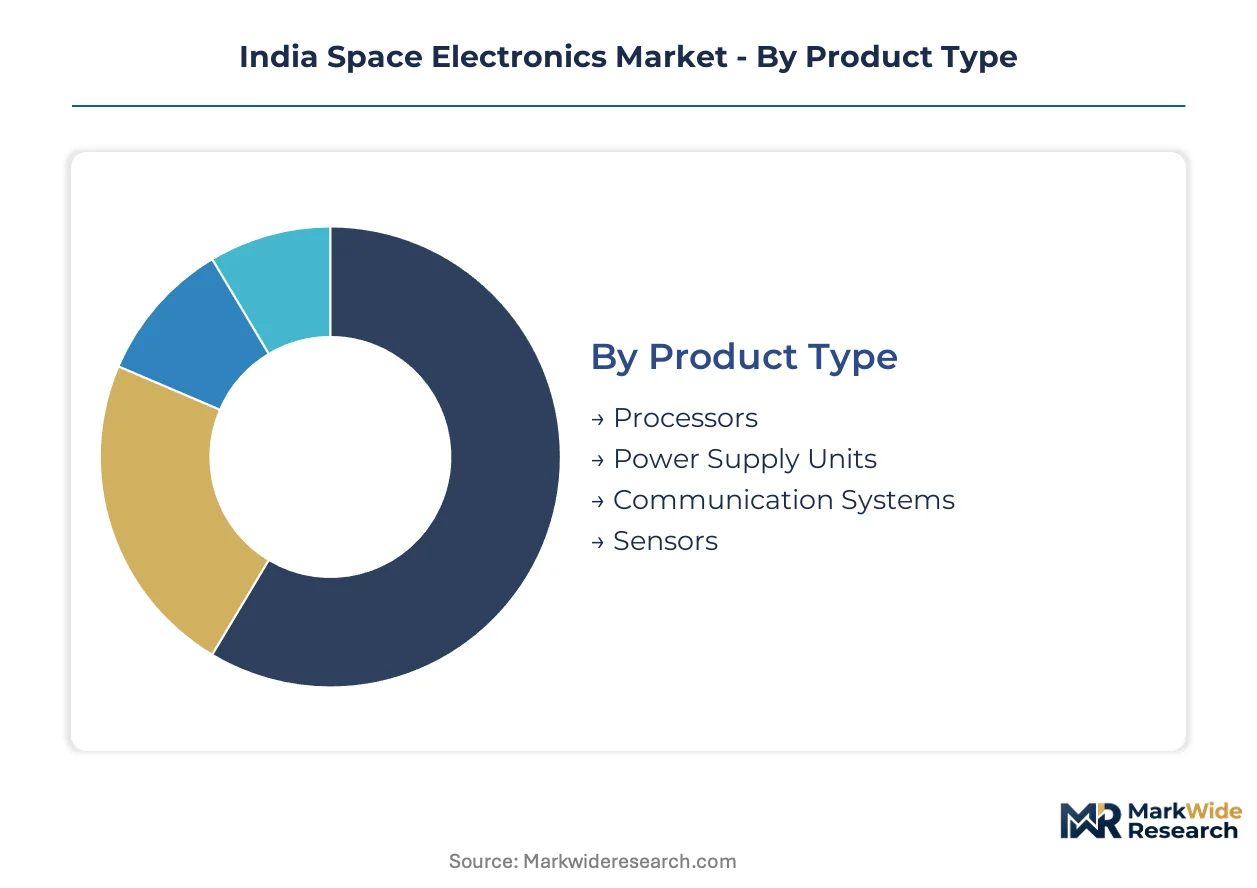
Segmentation in India's space electronics market reveals how procurement patterns diverge across mission-critical applications. Technical specifications, radiation tolerance requirements, and end-user qualification protocols create distinct commercial pathways for component suppliers.
Product Type:
Radiation tolerance thresholds and thermal cycling specifications differentiate component categories across ISRO's satellite and launch vehicle programs.
- Processors:Silicon-on-insulator fabrication achieves total ionizing dose tolerance exceeding 100 krad(Si). Bengaluru's aerospace cluster concentrates design activity for attitude control and payload data handling functions.
- Power Supply Units:Hermetic sealing and tantalum capacitors ensure voltage stability across extreme thermal gradients. Bharat Electronics anchors high-reliability contracts through its defense electronics heritage and ISRO vendor qualification.
- Communication Systems:Ka-band and X-band transponder complexity commands substantial engineering margins.
- Sensors:Precision measurement for telemetry and orbital positioning applications.
Communication systems lead on scale; power supply units lead on momentum.
Technology:
Foundry access and qualification timelines shape competitive positioning across semiconductor fabrication approaches.
- Microelectronics:Standard CMOS processes require additional shielding and error-correction logic for orbital deployment. Domestic foundry partnerships mature under government PLI scheme funding.
- FPGA:Reconfigurable radiation-tolerant computing enables single hardware designs to serve multiple mission profiles. Hyderabad's defense electronics corridor specializes in FPGA-based signal processing modules.
- ASIC:Custom radiation-hardened designs demand 18-24 month qualification cycles at the government-owned semiconductor facility.
- Radiation-Hardened:Purpose-built fabrication processes achieve inherent single-event upset immunity without external mitigation.
FPGA technology dominates current procurement; radiation-hardened ASICs command the steepest expansion trajectory as domestic fabrication capacity expands.
Application:
Mission cadence and commercialization pressure are reconfiguring demand distribution across orbital and terrestrial infrastructure.
- Satellite Systems:Bus electronics and payload data handling absorb the largest procurement volumes. NSIL's multi-mission component supply agreements concentrate demand among three major Bengaluru integrators.
- Launch Vehicles:Flight-proven avionics at commercial price points attract private orbital providers in Andhra Pradesh and Tamil Nadu.
- Ground Stations:Telemetry and tracking infrastructure for constellation management.
- Research Programs:Experimental payloads with specialized qualification requirements.
Satellite systems anchor procurement volume; launch vehicle electronics are gaining share fastest.
End User:
Procurement autonomy and qualification protocols create divergent supplier relationships across institutional buyer categories.
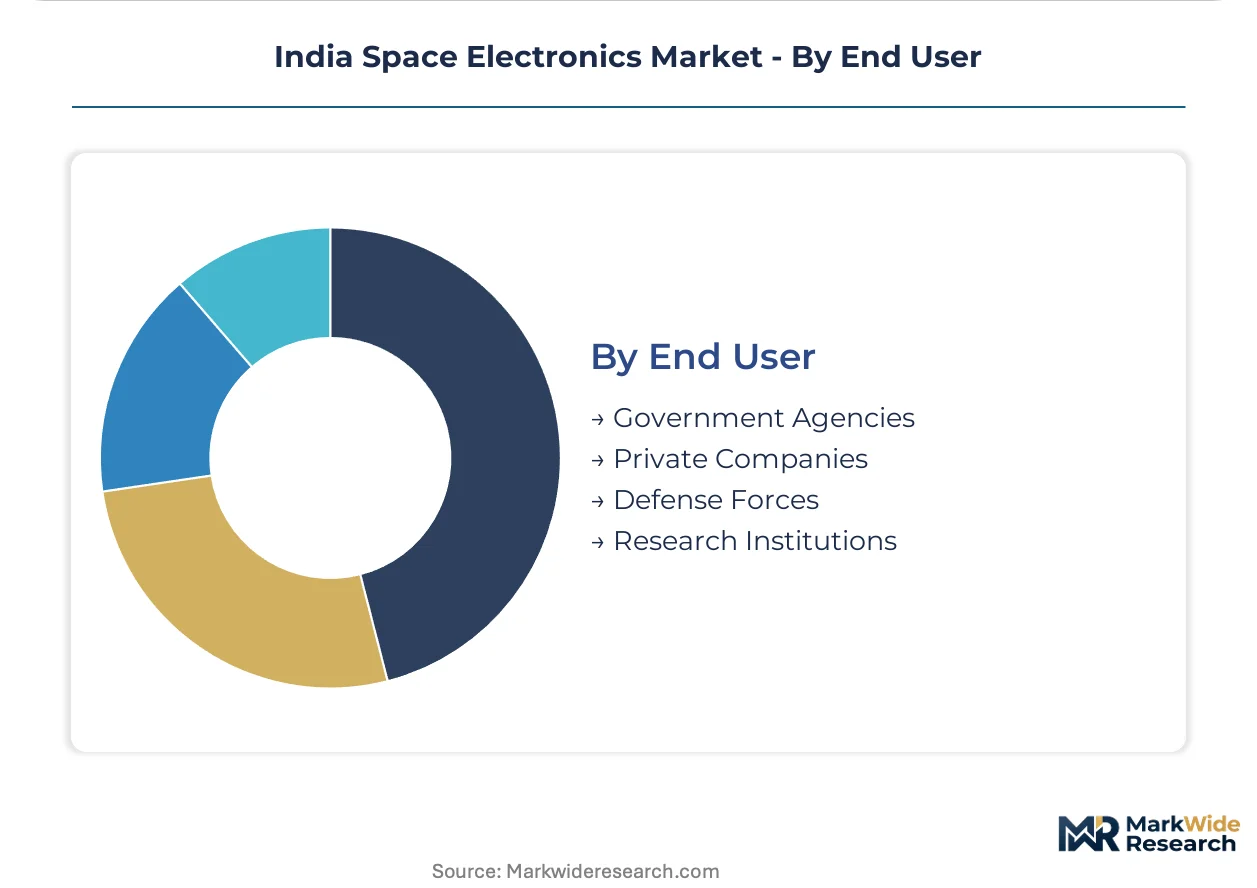
- Government Agencies:ISRO centers and the Department of Space maintain heritage vendor relationships with extended thermal vacuum testing requirements.
- Private Companies:NSIL's commercialization mandate enables direct bidding on satellite manufacturing contracts previously reserved to public sector units.
- Defense Forces:Indigenous satellite communication procurement expands under self-reliance mandates.
- Research Institutions:Academic and laboratory missions with specialized payload requirements.
Government agencies retain procurement scale; private companies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's space electronics industry traces its institutional roots to ISRO's establishment in Bengaluru during the 1960s, when satellite fabrication and launch vehicle development created the foundation for a specialized component ecosystem. Domestic manufacturing capacity has since clustered around defense-aerospace corridors where radiation-hardened qualification protocols intersect with commercial launch economics.
Karnataka
Bengaluru anchors national satellite integration activity, housing ISRO headquarters and three major spacecraft manufacturers. The state's Electronics System Design and Manufacturing policy extends capital subsidies for radiation-hardened component testing facilities. Peenya Industrial Area and Electronic City concentrate precision mechanical fabrication for space-qualified enclosures alongside PCB assembly operations.
Telangana
Hyderabad's defense electronics corridor specializes in FPGA-based signal processing and microwave component design for communication payloads. The Telangana State Industrial Project Approval and Self Certification System accelerates environmental clearances for aerospace manufacturing units. Hardware Park and Genome Valley host captive testing laboratories serving both ISRO missions and private constellation developers.
Tamil Nadu
Sriharikota's Satish Dhawan Space Centre drives demand for launch vehicle avionics and ground support electronics. Tamil Nadu's Aerospace and Defence Industrial Policy offers land allotment priority for space-grade alloy foundries. Ambattur and Oragadam industrial belts attract private orbital launch providers seeking proximity to the country's primary spaceport.
Andhra Pradesh
Sri City and Visakhapatnam harbor emerging private launch vehicle developers requiring flight-proven avionics at commercial price points. The Andhra Pradesh Industrial Development Corporation provides single-window clearance for space electronics manufacturing units. The state's missile testing range at Abdul Kalam Island creates dual-use demand for radiation-tolerant guidance systems.
Maharashtra
Pune and Mumbai house defense research laboratories contributing to indigenous satellite communication system development. Maharashtra's Package Scheme of Incentives extends tax exemptions for electronics manufacturing in designated zones. The Mumbai-Pune industrial corridor supports precision machining for satellite structural components and antenna subsystems.
India Space Electronics Market Competitive Landscape
The competitive structure tilts toward public sector heritage players with ISRO vendor qualification. Defense electronics contractors leverage existing radiation-hardening expertise to anchor high-reliability power supply and communication subsystem contracts. Three archetypes dominate: state-owned enterprises with multi-decade ISRO relationships, mid-cap specialists with captive testing infrastructure, and diversified industrial conglomerates entering through strategic partnerships. Competitive dynamics center on qualification timeline compression and multi-mission supply agreement consolidation.
Among defense heritage specialists, Bharat Electronics and Centum Electronics exemplify the qualification-intensive tier, while Data Patterns occupies a position emphasizing in-house PCB fabrication and precision mechanical capabilities. These three anchors represent distinct pathways to ISRO vendor status: legacy defense relationships, specialized radiation-hardened microelectronics R&D, and vertical integration into manufacturing processes previously outsourced.
| Leading Market Players |
|---|
| Bharat Electronics |
| Centum Electronics |
| Data Patterns |
| Ananth Technologies |
| Alpha Design Technologies |
| Paras Defence and Space Technologies |
| Tata Advanced Systems |
| Larsen and Toubro Defence |
| Godrej Aerospace |
| Others |
Pricing and Supply Chain Analysis
Certification-grade stratification between ISRO-qualified heritage suppliers and unqualified commercial component vendors creates divergent pricing architectures that feed directly into supply chain sourcing decisions. Premium-tier suppliers command 40-60 percent cost premiums over commercial-grade alternatives, yet procurement officers absorb these differentials to avoid 18-24 month BIS recertification cycles that strand inventory value.
Pricing Analysis
Three-tier pricing structure across radiation-hardened, radiation-tolerant, and commercial-off-the-shelf levels dominates component transactions. Price differentiation rests on total ionizing dose certification thresholds and hermetic sealing protocols. Cost compression in commercial-tier alternatives is intensifying because private launch providers in Andhra Pradesh and Tamil Nadu prioritize mission-cost minimization over orbital lifespan extension. Defense procurement channels exhibit lowest price sensitivity; commercial constellation developers show highest elasticity.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Bengaluru's Peenya Industrial Area and Electronic City to Hyderabad's Hardware Park and Sriharikota's launch complex. Geographic supply concentration draws from Taiwan for advanced semiconductor foundry services, Central Africa for tantalum ore, and the United States for radiation-hardened FPGA intellectual property. Single-source vulnerability at India's government-owned semiconductor fabrication facility exposes ASIC qualification timelines to capacity constraints. Distribution runs through ISRO-approved vendor consignment stock arrangements rather than open-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's space electronics sector offers geographic-arbitrage value against European and Israeli radiation-hardened component specialists, where comparable qualification protocols carry 30-50 percent labor cost premiums and lengthier regulatory pathways.
For Market Incumbents: Acquire captive testing infrastructure to compress vendor qualification timelines from 24 months toward 12-month competitive benchmarks. Consolidate multi-mission supply agreements with NSIL before private launch providers fragment procurement volumes. Anchor position against emerging FPGA-ASIC convergence threats by deepening silicon-on-insulator process partnerships with the government-owned foundry. For New Entrants and Emerging Players: Private orbital launch providers in Andhra Pradesh represent the most penetrable buyer segment, given their price sensitivity and tolerance for commercial-grade avionics with radiation-tolerant rather than radiation-hardened specifications. Target small satellite bus electronics for constellation developers seeking catalog-based component selection rather than custom development cycles. Pursue technology licensing partnerships with European radiation-hardened specialists to bypass internal R&D intensity requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor qualification backlogs exceed 18 months and captive testing infrastructure differentiates revenue recognition velocity. Five-to-ten year viability favors mid-cap specialists with backward integration into PCB fabrication and precision mechanical assembly rather than pure-play design houses. Monitor ISRO's vendor indigenization mandate enforcement as inflection indicator for import-substitution valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Infrastructure Acquisition | Compresses BIS certification timelines from 24 months toward 12-month benchmarks for ISRO vendor status. |
| Multi-Mission Supply Agreement Negotiation | Locks five-year revenue visibility with NSIL as consolidated procurement displaces project-by-project tendering. |
| Domestic Foundry Partnership Deepening | Reduces single-source dependency at the government-owned semiconductor facility for radiation-hardened ASIC fabrication. |
| Technology Licensing with European Specialists | Accelerates FPGA-based signal processing module qualification without internal R&D intensity investment. |
| Commercial-Grade Avionics Portfolio Expansion | Captures private launch provider demand in Andhra Pradesh and Tamil Nadu at price points below heritage ISRO missions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ISRO procurement officers, defense electronics program managers, private launch vehicle CTOs, and radiation effects engineering faculty at Indian Institutes of Technology with secondary validation against Department of Space annual reports, NSIL commercialization disclosures, BIS certification registries, and PLI scheme implementation bulletins. Bottom-up component demand aggregation and top-down mission budget allocation analysis provided cross-verification.
Segment-weighting approaches distributed value across product type, technology, application, and end-user dimensions, with additional modeling of regional cluster concentration effects. CAGRs derived from installed base expansion rates, mission cadence projections, and import substitution elasticity coefficients across the analysis window. Industry-specific inputs included tantalum capacitor price volatility indices and domestic foundry capacity utilization assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Space Activities Bill liability framework codification and spectrum allocation rule finalization. Outputs reflect documented assumptions regarding ISRO vendor indigenization enforcement velocity and private launch provider market entry success rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Robots Market
Space
Space-Based Solar Power Market
Space
Spacecraft Market
Space
Space Propulsion Systems Market
Space
Space on Board Computing Platform Market
Space
Asia-Pacific Space Electronics Market
Space
UK Space Propulsion System Market
Space
US Space Launch Services Market
Space
Mexico Space Electronics Market
Space
Deep Space Exploration Market
Space
Japan Space Electronics Market
Space
Space Ground Station Equipment Market
Space
Space Wheel Market
Space
Suborbital Space Tourism Market
Space
France Space Electronics Market
Space
Space-Based C4ISR Market