
 Space Ground Station Equipment Market | 2026-2036
Space Ground Station Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Space Ground Station Equipment Market Insights
RF engineering talent scarcity is bifurcating the competitive landscape into firms that cultivate specialized workforces and those that outsource critical design functions. General Dynamics Corporation leverages decades of defense contracting relationships to sustain classified program access. Thales Group anchors European sovereign capabilities through vertically integrated antenna and signal processing operations. Lockheed Martin Corporation dominates large-diameter reflector deployments for deep-space missions.
Space ground station equipment encompasses terrestrial systems that transmit, receive, and process radio frequency signals to and from orbital assets, typically operating across S-band through Ka-band frequencies with aperture diameters ranging from sub-meter terminals to 70-meter deep-space dishes. These installations enable command uplink, telemetry downlink, and payload data retrieval for commercial, civil, and military satellite operators. Antenna systems command the largest installed base but face margin compression as commoditization spreads among sub-meter Very Small Aperture Terminal suppliers. Software defined radio architectures represent the fastest-expanding technology segment, allowing operators to reconfigure modulation schemes without hardware swaps. Satellite communications applications absorb the majority of procurement volumes, though military surveillance segments retain superior pricing power due to hardened specifications and security certification requirements.
FCC spectrum allocation proceedings in the United States, ESA procurement standards across European member states, and China's MIIT radio frequency licensing regime collectively determine equipment certification pathways and market access conditions. ITU coordination procedures for orbital slot and spectrum assignments directly shape ground station deployment timelines and geographic density requirements. Stakeholders must monitor evolving national security export controls and spectrum sharing frameworks as these will determine which technology architectures achieve scale deployment.
Market Dynamics
Phased array antenna systems are decomposing legacy parabolic dish architectures as constellation operators demand electronically steerable beams capable of tracking multiple satellites simultaneously without mechanical repositioning delays.
Growth Catalysts
- LEO constellation proliferation:Commercial satellite operators in the United States are deploying thousands of orbital assets requiring dense ground terminal networks for continuous connectivity.
- Software-defined radio adoption:Military end-users are reconfiguring modulation schemes in real-time through firmware updates rather than hardware replacement cycles.
- ITU spectrum coordination:International Telecommunication Union procedures for orbital slot assignments are accelerating licensed ground station deployment timelines across member states.
Market Restraints
- Gallium nitride substrate costs:RF power amplifier fabrication depends on constrained semiconductor wafer supply chains concentrated in East Asian foundries.
- Deep-space aperture limitations:Ka-band signal attenuation through atmospheric moisture restricts reliable data rates for distant planetary missions.
- FCC equipment authorization delays:Certification backlogs for novel antenna configurations extend product launch timelines for non-incumbent suppliers.
Strategic Opportunities
- Quantum key distribution networks:Research institutions in Germany are piloting optical ground stations for satellite-based cryptographic key exchange.
- Mobile deployable terminals:Defense agencies are procuring transportable 3.7-meter S-band systems for expeditionary command posts.
- Dual-use technology convergence:Commercial phased arrays are integrating military-grade anti-jam waveforms through software licensing arrangements.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave design expertise concentrates among defense contractors with security clearance barriers limiting workforce mobility.
- Legacy system integration complexity:New software-defined architectures must interface with decades-old telemetry processing infrastructure at established range facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Ground Station Equipment Market |
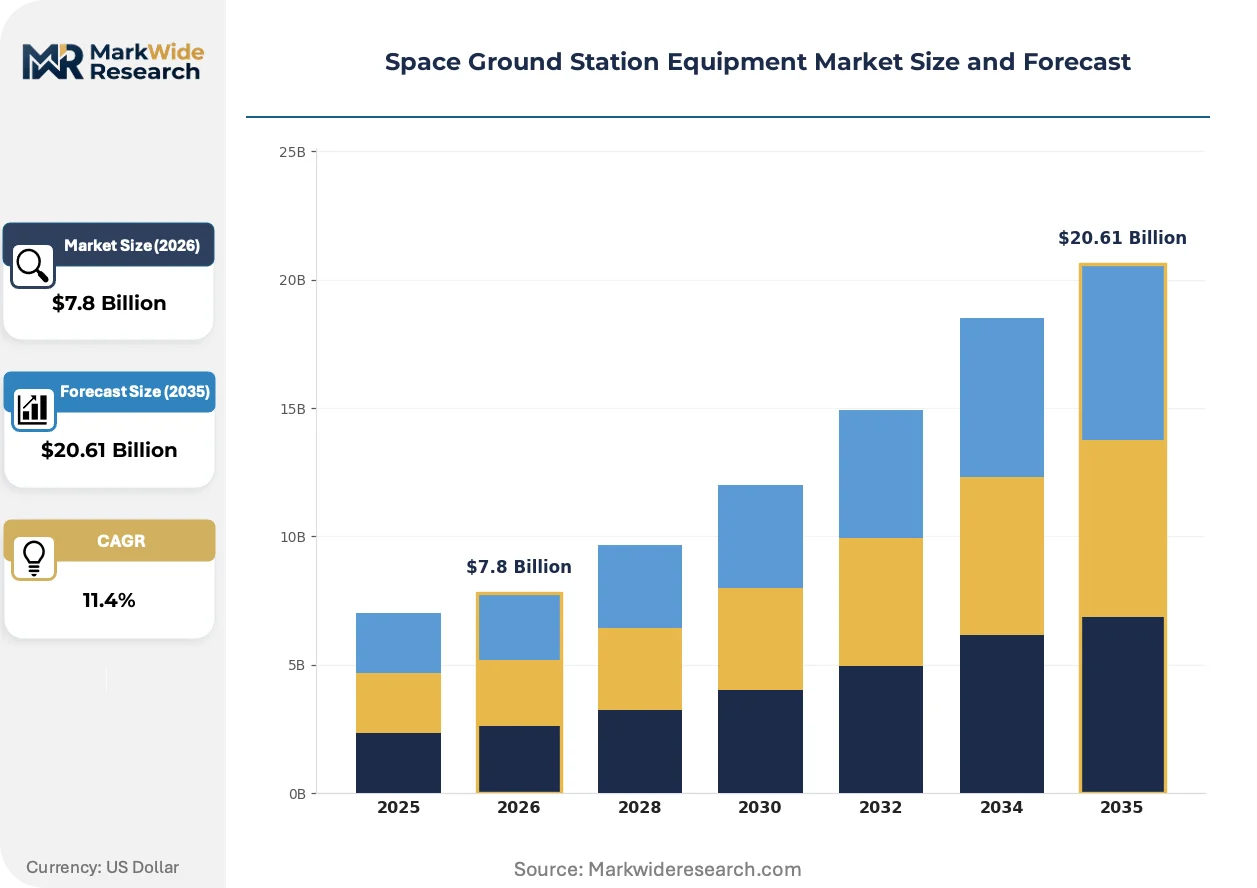
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antenna Systems, Signal Processors, Modulators, Demodulators, Frequency Converters, Power Amplifiers Technology: Phased Array, Parabolic Reflector, Software Defined Radio, Cryogenic Receivers, High Noise Figure, Wideband Transceivers Application: Satellite Communications, Space Exploration, Earth Observation, Scientific Research, Military Surveillance, Weather Monitoring End User: Space Agencies, Telemetry Services, Defense Contractors, Telecommunication Providers, Research Institutions, Satellite Operators |
| Companies Covered | General Dynamics Corporation, Thales Group, Lockheed Martin Corporation, EchoStar Corporation, Viasat Inc., Northrop Grumman Corporation, Raytheon Technologies Corporation, Kongsberg Satellite Services AS, L3Harris Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Ground Station Equipment Market Trends and Innovations
Three concurrent developments are compressing equipment replacement cycles while elevating software content in system value. Hardware commoditization is accelerating as digital signal processing absorbs functions previously executed in analog front-ends.
Phased array technology is decomposing mechanical antenna positioning systems across commercial and defense installations. Satellite operators deploying medium Earth orbit constellations are adopting electronically scanned apertures to eliminate acquisition time losses during satellite handovers. This shift is compressing maintenance contracts and extending mean time between failures by eliminating motor-driven azimuth-elevation assemblies.
ITU-R coordination procedures are tightening orbital spacing requirements for non-geostationary constellations. Operators must now demonstrate interference mitigation capabilities through advanced ground station filtering architectures before receiving spectrum assignments. European member states are mandating these compliance demonstrations prior to national licensing, affecting equipment procurement specifications for terminal suppliers.
Service unbundling is fragmenting traditional integrated supply contracts. Satellite operators are separating antenna procurement from signal processing subsystem sourcing, creating openings for specialized software vendors. This pattern is most pronounced in United States commercial markets where venture-backed constellation developers prioritize capital efficiency through multi-vendor integration strategies.
Space Ground Station Equipment Market Segmentation
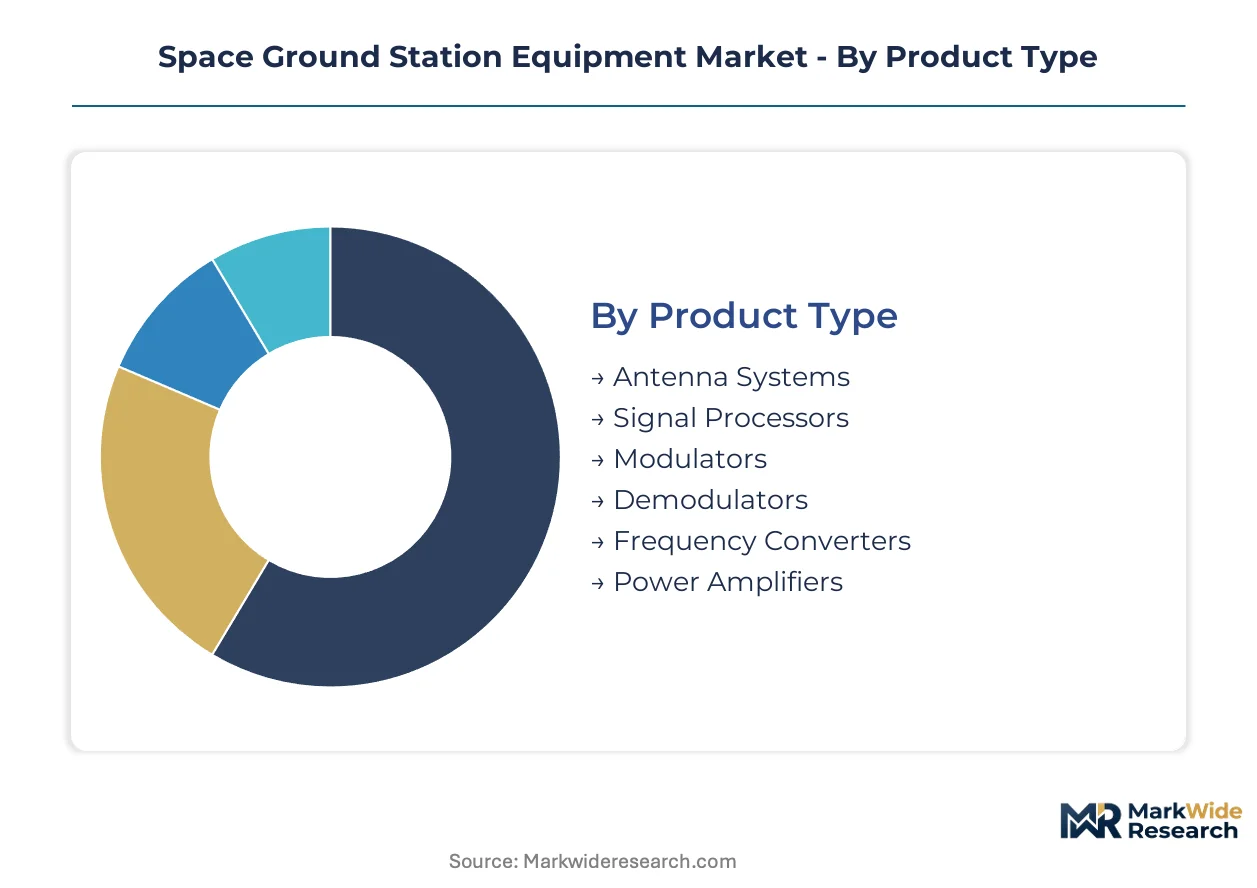
Segmentation in ground station equipment reveals how procurement patterns split across mission-critical defense programs and cost-sensitive commercial constellations. Equipment specifications diverge sharply between hardened military installations and rapidly deployable commercial terminals. Understanding these fault lines clarifies where margin pools concentrate versus where volume scales.
Product Type:
Antenna systems and signal processors move through defense prime contractors with long-term service attach rates, while power amplifiers and frequency converters flow increasingly through commercial distributors serving constellation operators.
- Antenna Systems:Parabolic reflectors and electronically scanned arrays form the physical RF interface with orbital assets. Demand concentrates at NASA's Deep Space Network facilities and China's Xi'an satellite control center, where 70-meter apertures for lunar and planetary missions require precision fabrication tolerances unavailable from commercial suppliers.
- Signal Processors:Digital baseband units execute modulation, coding, and protocol conversion functions. Procurement is shifting toward software-defined implementations at German research institutions and U.S. venture-backed constellation operators seeking firmware-upgradeable architectures over hardware replacement cycles.
- Modulators:Equipment encoding baseband data onto RF carriers for uplink transmission.
- Demodulators:Subsystems recovering digital bitstreams from received satellite signals.
- Frequency Converters:Units translating between intermediate frequency and RF bands for antenna interface.
- Power Amplifiers:Solid-state and traveling-wave tube amplifiers boosting transmit signals to overcome path losses.
Antenna systems dominate installed base. Signal processors are where expansion concentrates.
Technology:
Cost tiers separate cryogenically cooled deep-space receivers commanding premium pricing from commodity software-defined radios penetrating commercial markets.
- Phased Array:Electronically steerable antenna elements eliminate mechanical positioning latency. SpaceX and Amazon's Project Kuiper are driving procurement volumes in the United States for gateway terminals capable of tracking multiple LEO satellites without azimuth-elevation motor assemblies.
- Software Defined Radio:Reconfigurable signal processing through firmware updates rather than hardware swaps. Military end-users in Germany and the United States are mandating these architectures for multi-band, multi-mission flexibility against evolving threat environments.
- Parabolic Reflector:Traditional mechanically steered dish antennas for fixed ground installations.
- Cryogenic Receivers:Ultra-low-noise amplifiers cooled to liquid helium temperatures for deep-space weak signal detection.
- High Noise Figure:Receiver architectures tolerating higher noise floors for cost-constrained applications.
- Wideband Transceivers:Multi-octave RF front-ends supporting spectrum agility requirements.
Phased array technology is climbing the fastest in procurement volume. Parabolic reflectors retain dominance in deep-space mission bookings.
Application:
Volume concentrates in satellite communications infrastructure, while margin pools align with military surveillance and space exploration specifications demanding hardened qualification testing.
- Satellite Communications:Commercial broadband and broadcast relay ground infrastructure. Deployment is accelerating across the United States, China, and Germany as Starlink, OneWeb, and domestic constellation operators build dense gateway networks for continuous connectivity.
- Military Surveillance:Classified signal intelligence and reconnaissance ground stations. Procurement flows through U.S. defense primes with security clearance barriers, where anti-jam and low-probability-of-intercept specifications sustain pricing premiums unavailable in commercial markets.
- Space Exploration:Deep-space mission support for lunar, planetary, and interplanetary probes.
- Earth Observation:Ground stations for remote sensing satellite data downlink and processing.
- Scientific Research:Radio astronomy and fundamental physics experiment infrastructure.
- Weather Monitoring:Meteorological satellite command and data acquisition facilities.
Satellite communications commands the largest equipment procurement volumes. Military surveillance sustains the steepest margin structure.
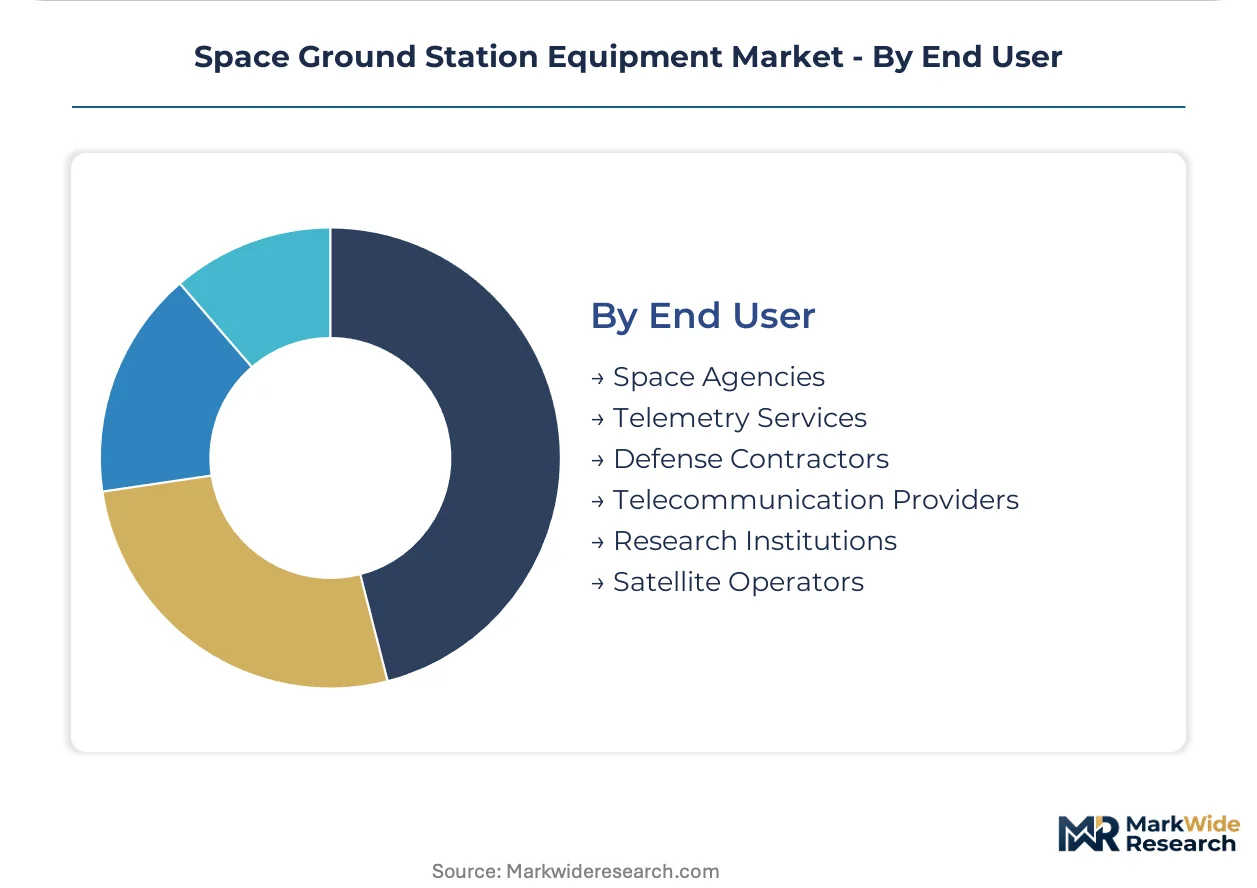
End User:
Customer type determines procurement channel structure, with space agencies and defense contractors integrating complex subsystems internally while satellite operators unbundle specifications for multi-vendor sourcing.
- Space Agencies:NASA, ESA, and CNSA operate dedicated deep-space networks with multi-decade capital planning horizons. These institutions anchor demand for large-aperture antennas and cryogenic receiving systems in the United States, Germany, and China.
- Satellite Operators:Commercial constellation developers procuring at volume for rapid network deployment. Procurement patterns favor software-defined architectures and phased array terminals that minimize per-site commissioning time.
- Telemetry Services:Commercial ground station-as-a-service providers.
- Defense Contractors:Systems integrators delivering classified ground segments to military end-users.
- Telecommunication Providers:Cellular backhaul and enterprise connectivity service operators.
- Research Institutions:Universities and national laboratories operating experimental ground stations.
Space agencies dominate heritage architecture procurement. Satellite operators are driving the fastest expansion in next-generation terminal demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States prioritizes software-defined architectures for rapid constellation deployment. China concentrates on sovereign deep-space networks. Germany anchors European quantum-communications research.
United States
SpaceX and Amazon's Project Kuiper are procuring phased array gateway terminals at volume for LEO broadband constellations. FCC equipment authorization procedures govern certification timelines for novel antenna configurations. Colorado and California host dense clusters of RF subsystem suppliers serving defense primes and commercial operators alike.
China
CNSA's Xi'an satellite control center is expanding 70-meter aperture capacity for lunar and planetary missions. MIIT radio frequency licensing determines ground station deployment density and spectrum access conditions. Beijing-Tianjin corridor concentrates domestic antenna fabrication for both civil and military programs.
Germany
ESA procurement standards are mandating interference mitigation demonstrations for non-geostationary constellation ground segments. German research institutions are piloting optical ground stations for satellite-based quantum key distribution. Bavaria's aerospace cluster around Munich anchors European signal processing subsystem development.
United Kingdom
OneWeb's constellation operations are driving demand for transportable S-band terminals and gateway infrastructure refresh. UK Space Agency funding programs support ground station-as-a-service providers serving small satellite operators. Harwell Science and Innovation Campus hosts emerging RF technology ventures focused on software-defined implementations.
Japan
JAXA deep-space missions require cryogenic receiver systems for weak signal detection at lunar and asteroid distances. METI industrial policy promotes domestic phased array manufacturing to reduce import dependency for satellite communications infrastructure. Tokyo-Yokohama corridor concentrates precision microwave component suppliers serving regional constellation operators.
Space Ground Station Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in ground station equipment supply. Defense primes with decades of classified program access occupy the upper tier, while commercial antenna specialists and software vendors fill gaps below. Two strategic archetypes dominate: vertically integrated subsystem houses controlling antenna-through-processor stacks, and modular component suppliers enabling multi-vendor integration. Competitive moves concentrate on strategic partnerships for constellation-specific terminal development and technology licensing for dual-use waveform integration.
Within the integrated defense tier, General Dynamics Corporation and Lockheed Martin Corporation exemplify prime-contractor positioning sustained by security-cleared workforce depth and long-term service attach rates. Thales Group anchors European sovereign capability through vertically integrated antenna and signal processing operations. These three represent contrasting geographic anchors—US-based primes versus European integrated suppliers—each occupying positions shaped by national procurement channel structures rather than direct product competition.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Thales Group |
| Lockheed Martin Corporation |
| EchoStar Corporation |
| Viasat Inc. |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| Kongsberg Satellite Services AS |
| L3Harris Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term service attach contracts at NASA Deep Space Network facilities and ESA ground stations lock in both gallium nitride substrate supply access and predictable pricing visibility across multi-decade mission support cycles. These arrangements insulate prime contractors from spot market volatility in RF component procurement while embedding hardware refresh obligations.
Pricing Analysis
Project-based contracting dominates deep-space antenna procurement, with cost-plus structures at NASA and fixed-price competition for commercial constellation terminals. Price differentiation rests on security certification tier and aperture diameter scale, with ITAR-restricted programs commanding premiums over commercial equivalents. Cost compression in sub-meter VSAT terminals intensifies as Chinese manufacturers penetrate global distribution. Satellite operators exhibit highest price sensitivity, while defense agencies tolerate premium pricing for hardened specifications.
Supply Chain Analysis
Inbound logistics costs for gallium nitride wafers from Japanese and South Korean foundries feed into RF power amplifier pricing, with container availability constraints affecting delivery schedules to Colorado and California assembly clusters. Supply draws from Taiwan for semiconductor substrates, Germany for precision microwave components, and the United States for cryogenic receiver assemblies. Single-source vulnerability concentrates in East Asian gallium nitride wafer fabrication. Distribution runs through defense prime contractor channels for classified programs and commercial distributors for constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
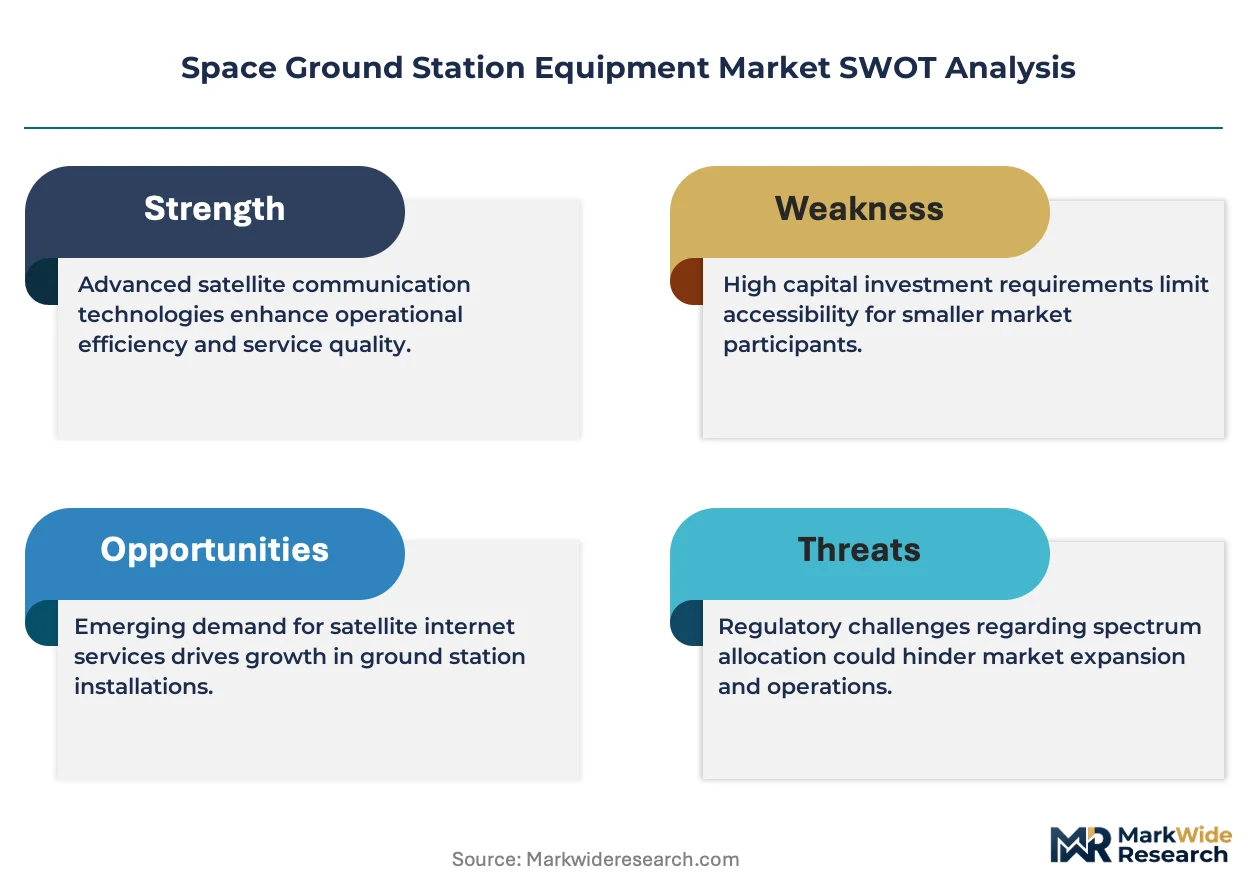
Buyer power has shifted toward satellite operators consolidating procurement volumes across phased array gateway networks, fragmenting traditional integrated supply relationships.
For Market Incumbents: Fortify classified program access through security-cleared workforce retention and long-term service contract extensions at NASA and ESA facilities. Deepen backward integration into gallium nitride substrate sourcing to offset foundry concentration risk. Prioritize firmware upgrade pathways that extend hardware replacement cycles and capture recurring revenue streams.
For New Entrants and Emerging Players: Differentiate on software-defined radio architectures targeting German research institutions and U.S. venture-backed constellation operators seeking multi-band reconfigurability. White-space opportunities concentrate in mobile deployable terminals for expeditionary defense applications and optical ground stations for quantum key distribution pilots. Pursue direct licensing arrangements with commercial phased array manufacturers for military waveform integration.
For Investors and Strategic Acquirers: RF subsystem specialists with ITAR-compliant facilities and established ESA supplier status represent priority acquisition targets. Long-term viability hinges on positioning within sovereign space agency procurement channels rather than commodity commercial terminal supply. Monitor FCC equipment authorization backlogs as an inflection indicator for non-incumbent market access conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Phased Array Gateway Deployment | SpaceX and Amazon procurement volumes reshape antenna supplier competitive positioning. |
| Software-Defined Radio Licensing | Military waveform integration through commercial hardware expands addressable market. |
| Cryogenic Receiver Capacity Addition | NASA Deep Space Network expansion anchors demand for ultra-low-noise systems. |
| GaN Substrate Backward Integration | Upstream control over constrained semiconductor supply reduces foundry dependency. |
| Optical Ground Station Pilot | German quantum communications research creates early-mover positioning. |
Research Methodology
Cross-validation between primary interviews with satellite procurement directors, RF engineering leads at defense primes, ESA program managers, and ground station-as-a-service operators anchors the qualitative findings against secondary validation. Secondary sources include FCC equipment authorization databases, ITU spectrum coordination filings, ESA procurement registries, and defense contract announcements. Bottom-up terminal deployment counts triangulate with top-down space agency capital expenditure assessments.
Sensitivity analysis across constellation deployment scenarios, spectrum allocation timelines, and gallium nitride substrate supply constraints informs the analytical framework over the projection horizon. Segmentation dimensions encompass product type, technology architecture, application mission profile, and end-user procurement channel. CAGRs derive from installed base replacement cycles and new constellation gateway deployment schedules, with inputs from phased array adoption curves and software-defined radio penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained LEO constellation deployment, stable ITU coordination procedures, or unconstrained semiconductor supply would require recalibration. Forecasts reflect assumptions regarding defense budget continuity and commercial operator capital access. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Asteroid Mining Market
Space
India Space Electronics Market
Space
Japan Space Electronics Market
Space
LAMEA Space As a Service Market
Space
Rocket Launchpad Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Management Solutions Market
Space
Near Space Robotics Market
Space
Carrier Rocket Market
Space
Space Robots Market
Space
Space-Based Solar Power Market
Space
Astronaut Spacesuit Market
Space
Africa Space Electronics Market
Space
Deep Space Robotics Market
Space
Africa Space Propulsion System Market
Space
Asia-Pacific Space Electronics Market