
 Space Mining Market | 2026-2036
Space Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Space Mining Market Intelligence
Platinum group metals from asteroid targets is rebalancing mission economics away from Earth-launched raw materials. Astroforge leverages autonomous drilling architectures to reduce payload mass for deep-space prospecting missions. Fleet Space anchors its competitive position through satellite-integrated mineral detection networks that feed real-time spectral data to extraction planners. ispace dominates lunar regolith demonstration programs with iterative landing systems designed to validate commercial viability.
Space mining encompasses the robotic extraction, processing, and utilization of extraterrestrial resources including water ice, regolith minerals, and metallic deposits for in-space consumption or return to Earth. The practice relies on autonomous systems operating in microgravity and vacuum conditions, with processing temperatures ranging from cryogenic ice sublimation to molten regolith electrolysis exceeding 1,600°C, primarily to produce propellant, structural materials, and life support consumables without Earth launch costs. Asteroid resource targeting leads current investment flows due to concentrated platinum group metal deposits and lower gravity wells versus lunar operations. In-situ resource utilization represents the fastest-expanding extraction technology segment as agencies and private firms prioritize fuel production over sample return. Propellant supply applications command the deepest margin pools because orbital refueling contracts extend mission duration and reduce launch frequency for satellite operators.
The US FAA governs commercial launch licensing for extraction mission deployment, while NASA's Artemis Accords framework shapes international resource-claiming norms among signatory nations. The absence of binding UN space resource treaties creates regulatory fragmentation that permits unilateral national legislation like the US Commercial Space Launch Competitiveness Act to define property rights. Stakeholders must monitor which regulatory jurisdictions capture mission control infrastructure, as flag-of-convenience strategies for spacecraft registration will determine liability exposure and permit access for decades ahead.
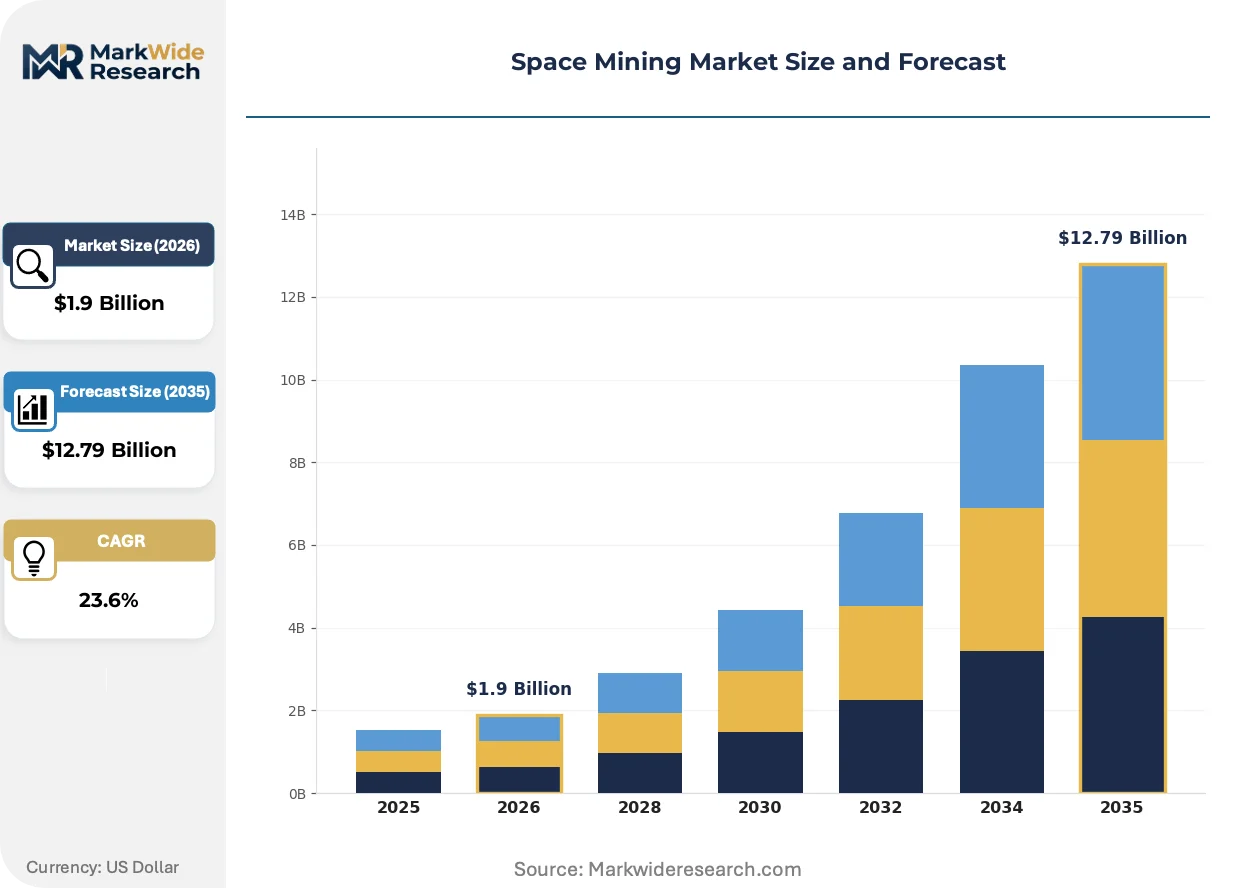
Market Dynamics
Autonomous extraction architectures are compressing mission payload requirements while orbital refueling infrastructure creates captive demand for in-situ propellant production.
Growth Catalysts
- Artemis Accords Framework:The US-led international agreement establishes resource-claiming norms that reduce legal uncertainty for lunar extraction ventures.
- Platinum Group Metal Concentration:Asteroid targets yield metal grades orders of magnitude above terrestrial deposits, rebalancing deep-space mission economics.
- FAA Streamlined Licensing:Accelerated commercial launch approvals compress deployment timelines for private extraction missions.
Market Restraints
- Launch Cost Structure:Earth-to-orbit transportation consumes 60-80% of mission capital, constraining payload mass for extraction equipment.
- Regulatory Fragmentation:Absence of binding UN space resource treaties permits conflicting national property rights legislation.
- Microgravity Processing Limitations:Molten regolith electrolysis above 1,600°C requires novel containment systems absent Earth-based equivalents.
Strategic Opportunities
- Colorado Technology Cluster:Dense concentration of space hardware engineering talent and NASA contractor infrastructure enables rapid prototyping cycles.
- In-Space Manufacturing Convergence:Integration of additive manufacturing with regolith-derived feedstocks creates closed-loop production without Earth resupply.
- Satellite Operator Channel:Orbital refueling contracts from communications constellation operators establish recurring revenue streams distinct from sample-return missions.
Industry Challenges
- Aerospace-Geology Skill Synthesis:Extraction system design demands hybrid expertise in planetary science and autonomous robotics that university pipelines rarely combine.
- Mission Certification Timelines:Deep-space hardware qualification protocols extend development cycles beyond venture capital fund horizons.
- Propulsion-Electronics Integration:Cryogenic ice sublimation systems must interface with satellite-integrated mineral detection networks without thermal contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Mining Market |
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $12.79 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resource Type: Asteroids, Lunar Regolith, Martian Soil, Comet Ice, Metallic Deposits Extraction Technology: Robotic Systems, Autonomous Drilling, Laser Ablation, 3D Printing, In-Situ Resource Utilization Application: Fuel Production, Construction Materials, Propellant Supply, Scientific Research, Space Manufacturing End User: Space Agencies, Private Aerospace Firms, Satellite Operators, Research Institutions, Defense Organizations |
| Companies Covered | Pixxel, Karman Plus, Esper, Interlune, Wyvern, ispace, Astroforge, Lunasonde, Fleet Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Mining Market Strategic Shifts & Innovations
Extraction technology is pivoting from sample-return demonstration toward continuous production systems, while regulatory competition between jurisdictions accelerates mission incorporation strategies.
Autonomous drilling architectures are overtaking teleoperated systems as the dominant approach for deep-space prospecting. Satellite operators now specify self-directed penetration capabilities in procurement requirements for regolith characterization missions. This shift compresses ground-control staffing costs while enabling operations beyond real-time communication windows.
The US Commercial Space Launch Competitiveness Act unilaterally defines private property rights for extracted space resources. This legislative framework attracts mission control infrastructure incorporation to Delaware and Colorado jurisdictions. European operators face competitive pressure as Luxembourg and the United Arab Emirates draft competing national space resource statutes.
End-use buyers now contract for propellant delivery rather than extraction equipment ownership. Satellite operators in geostationary and cislunar orbits purchase orbital refueling as a service, displacing capital expenditure on extended fuel reserves. This consumption pattern concentrates most visibly around NASA-funded lunar gateway programs and commercial communications constellations.
Space Mining Market Segmentation
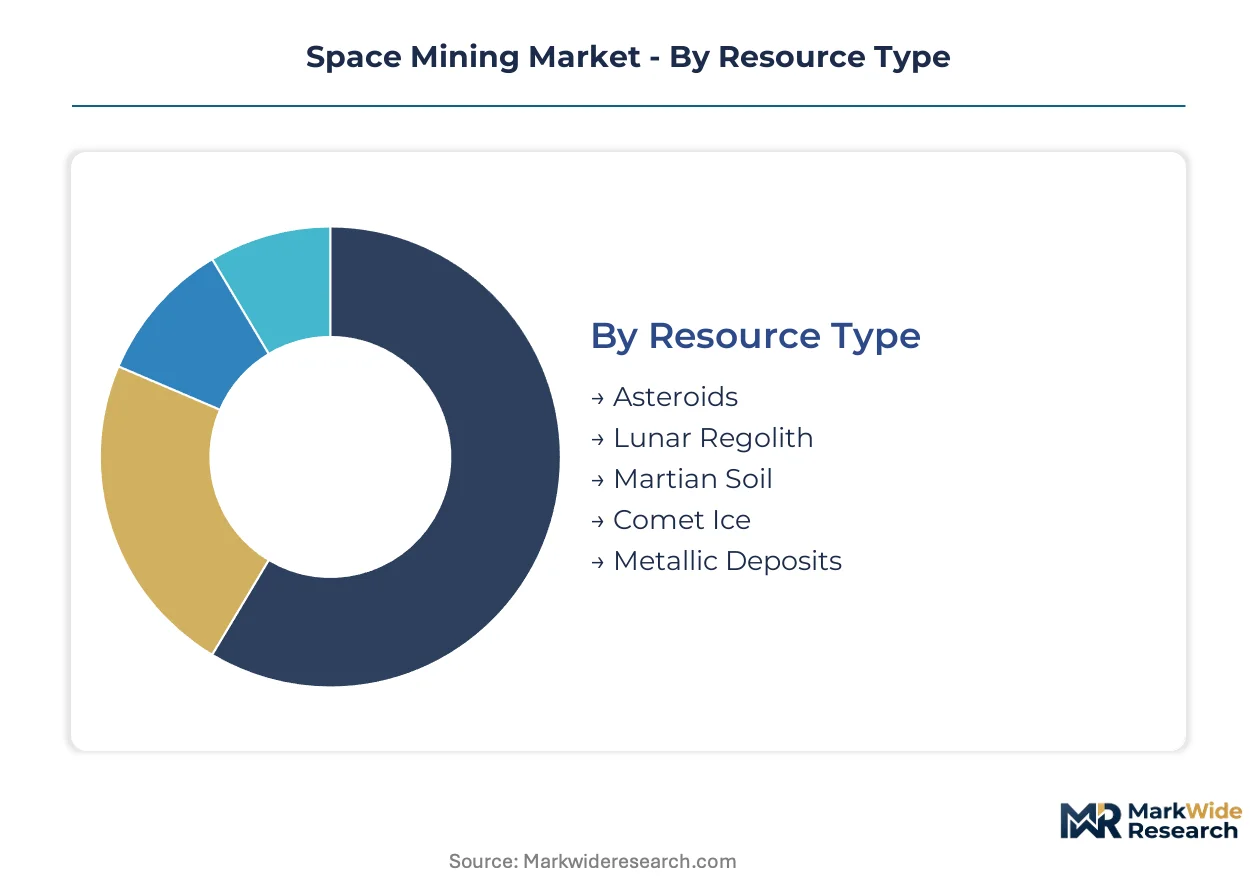
Segmentation in space mining reveals distinct technology maturity curves and capital intensity profiles across resource targets and extraction methods. Each category carries specific regulatory footprints and customer procurement patterns that shape vendor positioning.
Resource Type:
Customization versus standardization tensions run deepest here — asteroid targeting demands bespoke trajectory calculations while lunar regolith offers repeatable extraction protocols.
- Asteroids:Concentrated platinum group metal deposits in M-type near-Earth objects command premium mission economics. Demand concentrates in US-based ventures pursuing deep-space prospecting, constrained by extended mission timelines and communication lag beyond real-time control windows.
- Lunar Regolith:Water ice deposits at permanently shadowed polar regions enable propellant production for cislunar logistics. NASA-funded Artemis infrastructure programs in Colorado and Texas anchor procurement, driven by validated landing technologies and shorter supply loops to Earth orbit.
- Martian Soil:Perchlorate-rich substrate requires novel processing chemistry for life support applications.
- Comet Ice:Cryogenic volatiles demand specialized containment architectures for deep-space transport.
- Metallic Deposits:Iron-nickel concentrations support in-space manufacturing feedstocks without Earth launch mass penalties.
Volume leadership sits with Lunar Regolith given Artemis program commitments. Steepest expansion trajectory belongs to Asteroids as platinum economics improve.
Extraction Technology:
Cost tier stratification separates capital-intensive autonomous systems from modular robotic platforms with lower mission integration overhead.
- Robotic Systems:Teleoperated manipulators with force-feedback haptics handle delicate sample collection and precursor validation missions. Satellite operators in geostationary orbit specify these for orbital refueling precursor missions, prioritizing proven reliability over full autonomy.
- Autonomous Drilling:Self-directed penetration architectures with real-time geologic interpretation reduce ground-control staffing. Colorado-based engineering clusters dominate development, driven by compressed payload mass requirements for deep-space launch economics.
- Laser Ablation:Pulsed energy deposition enables contactless material vaporization for volatile analysis.
- 3D Printing:Additive manufacturing with regolith-derived feedstocks closes production loops for structural components.
- In-Situ Resource Utilization:Integrated extraction-processing systems convert raw material to usable propellant and life support consumables on location.
Robotic Systems capture current procurement volume. Autonomous Drilling gains share fastest as communication windows constrain teleoperation beyond lunar distance.
Application:
Application maturity correlates with customer willingness to accept performance risk — fuel production commands near-term contracts while space manufacturing remains developmental.
- Fuel Production:Water electrolysis and cryogenic liquefaction systems generate hydrogen and oxygen propellants from lunar ice. Satellite operators contract for orbital refueling services around NASA lunar gateway programs, displacing on-board fuel reserves with pay-per-use models.
- Propellant Supply:Stored and delivered propellant for third-party spacecraft extends mission duration without dedicated fuel mass at launch. Communications constellation operators in cislunar orbits anchor demand, driven by station-keeping requirements for extended operational lifespans.
- Construction Materials:Sintered regolith bricks and molten metal casting support habitat infrastructure.
- Scientific Research:Sample return missions prioritize geologic characterization over commercial extraction yields.
- Space Manufacturing:Microgravity production environments enable novel material properties unattainable on Earth.
Propellant Supply leads by contract value. Fuel Production climbs fastest as electrolysis technology matures.
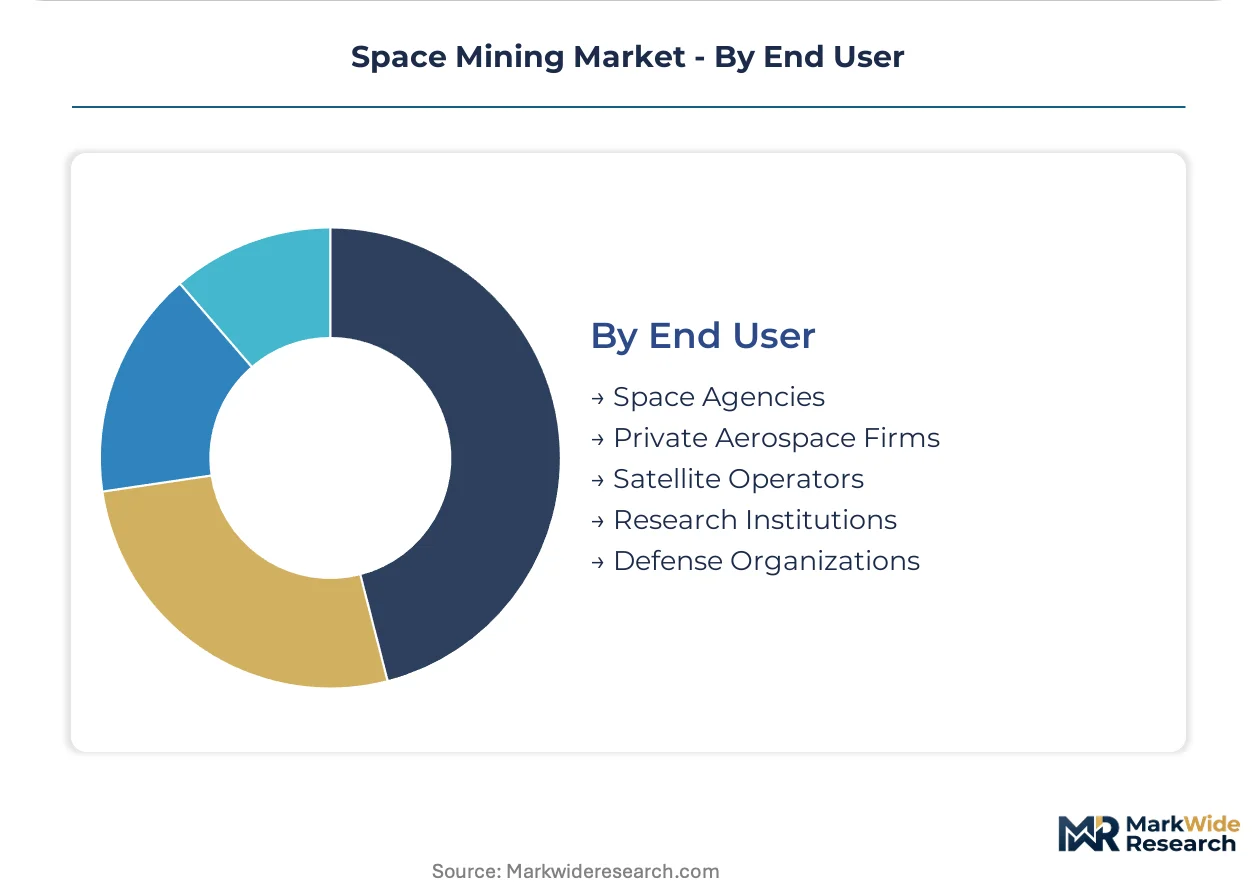
End User:
Customer type determines procurement modality — space agencies fund development while satellite operators purchase operational services.
- Space Agencies:NASA, ESA, and JAXA anchor public investment in lunar resource demonstration missions. Artemis Accords signatory nations concentrate procurement through national space technology clusters, prioritizing technology validation and international partnership frameworks.
- Satellite Operators:Commercial communications and Earth observation constellation owners purchase orbital refueling as operational expenditure. US-based operators leverage FAA streamlined licensing for rapid mission deployment, avoiding capital-intensive fuel reserve hardware.
- Private Aerospace Firms:Venture-backed extraction ventures pursue asteroid and lunar resource commercialization.
- Research Institutions:Universities and national laboratories access shared infrastructure for planetary science objectives.
- Defense Organizations:Military space commands evaluate resource autonomy for strategic logistics resilience.
Space Agencies dominate current funding volume. Satellite Operators expand procurement fastest as service-based models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States concentration around NASA-funded lunar programs and Colorado-based engineering clusters is reshaping investment flows toward cislunar infrastructure. Satellite operator procurement for orbital refueling services anchors commercial demand in this geography.
United States
Colorado and Texas host dense concentrations of space hardware engineering talent and NASA contractor infrastructure. The FAA governs commercial launch licensing through streamlined approval pathways that compress mission deployment timelines. Denver-Boulder corridor firms prototype autonomous drilling systems for Artemis-supported lunar demonstration programs.
Luxembourg
National space resource legislation attracts mission control infrastructure incorporation from European operators seeking competitive positioning. The country's financial regulator shapes venture capital fund structures for deep-space hardware qualification cycles. Luxembourg City anchors administrative functions for asteroid prospecting ventures targeting platinum group metal deposits.
United Arab Emirates
Draft national space resource statutes create regulatory competition with Western frameworks for mission incorporation. The national space agency funds technology demonstration partnerships with commercial extraction ventures. Dubai and Abu Dhabi clusters concentrate satellite-integrated mineral detection network development for regional communications operators.
Japan
JAXA anchors public investment in lunar regolith demonstration missions through iterative landing system validation. METI industrial policy prioritizes in-situ resource utilization technology maturation for cislunar logistics. Tokyo-Osaka corridor engineering groups develop cryogenic ice sublimation systems for propellant production applications.
United Kingdom
Space Agency funding concentrates on robotic systems for precursor validation missions with force-feedback haptic specifications. The national regulator coordinates with FAA frameworks for launch licensing reciprocity on extraction mission deployment. Harwell-Oxfordshire cluster hosts additive manufacturing research integrating regolith-derived feedstocks for structural components.
Space Mining Market Key Industry Players
Strategic partnerships dominate the current landscape as venture-backed ventures align with established aerospace contractors for qualification protocols. The vendor base clusters around three archetypes: satellite-integrated detection network operators, autonomous drilling system developers, and lunar landing platform specialists. Portfolio diversification into orbital refueling services separates service-based revenue models from capital-intensive sample-return missions. Technology licensing agreements compress development cycles for microgravity processing containment systems.
Within the autonomous drilling tier, Astroforge and Lunasonde exemplify payload mass reduction strategies for deep-space launch economics. Among satellite-integrated detection specialists, Fleet Space anchors real-time spectral data architectures feeding extraction planners. The lunar landing platform category includes ispace, which occupies a position in iterative demonstration programs validating commercial viability. Pixxel and Wyvern represent the Earth-observation-to-extraction pivot archetype, leveraging existing constellation infrastructure for resource targeting applications.
| Leading Market Players |
|---|
| Pixxel |
| Karman Plus |
| Esper |
| Interlune |
| Wyvern |
| ispace |
| Astroforge |
| Lunasonde |
| Fleet Space |
| Others |
Cost & Logistics Intelligence
Platinum group metal spot indices from Johnson Matthey and London Metal Exchange benchmarks cascade through mission economics into three distinct pricing tiers for extraction services, with Earth-launch mass premiums compressing margins at the lower tier while Artemis-backed lunar infrastructure commands premium contract values.
Pricing Analysis
Volume-mission economics split sharply from margin-rich service contracts. Project-based long-term offtake agreements dominate sample-return missions, while orbital refueling-as-a-service subscriptions capture recurring revenue from satellite operators. Price differentiation centers on payload mass efficiency and FAA launch licensing tier, with Colorado-based ventures least price-sensitive due to NASA anchor funding and Texas operators most sensitive given commercial launch cost exposure. Cost compression in teleoperated robotic tiers is intensifying because autonomous drilling architectures reduce ground-control staffing overhead.
Supply Chain Analysis
Launch vehicle supply rests on United States, France, and New Zealand providers for mission deployment, while autonomous drilling electronics draw from Taiwan semiconductor foundries and Japanese precision sensor manufacturers. Raw material dependencies include radiation-hardened microcontrollers, cryogenic containment alloys, and spectral imaging sensors. Single-source vulnerability concentrates in launch slot allocation through FAA-licensed ranges. Distribution runs through prime contractor integration hubs in Colorado and Texas before mission control handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Commercial Space Launch Competitiveness Act creates a cost-of-compliance moat where Delaware and Colorado incorporation with FAA licensing infrastructure separates viable ventures from capital-constrained aspirants.
For Market Incumbents: Anticipate regulatory fragmentation as Luxembourg and UAE draft competing space resource statutes that erode US-first-mover advantages. Lock in vertical integration into launch slot reservations through FAA streamlined licensing pathways. Secure autonomous drilling certification protocols before mission qualification timelines extend beyond venture capital fund horizons. For New Entrants and Emerging Players: Satellite operators represent the most penetrable channel partner type for service-based revenue models, particularly communications constellation owners in cislunar orbits seeking orbital refueling contracts. White-space concentrates in asteroid prospecting missions where platinum group metal economics rebalance deep-space mission viability. Target the Denver-Boulder corridor for rapid prototyping partnerships with NASA contractor infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor autonomous drilling ventures with FAA licensing completion in Colorado jurisdictions during capital-market tightening for deep-space hardware. Long-term viability hinges on propellant supply contract maturation rather than sample-return demonstration programs. Watch Artemis program funding continuity as the critical inflection signal for lunar infrastructure investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Drilling Certification | FAA mission qualification protocols validate payload mass reduction for deep-space launch economics. |
| Orbital Refueling Service Launch | Satellite operator contracts displace capital expenditure with recurring propellant delivery revenue. |
| Colorado Technology Cluster Expansion | Denver-Boulder corridor proximity to NASA contractors compresses hardware prototyping cycles. |
| Luxembourg Regulatory Arbitrage | National space resource legislation attracts European mission control incorporation from competing jurisdictions. |
| In-Space Manufacturing Integration | Additive manufacturing with regolith feedstocks closes production loops without Earth resupply mass. |
Research Approach
NASA contract award databases, FAA commercial launch licensing records, and ESA technology demonstration filings formed the secondary backbone, cross-referenced with primary interviews involving autonomous systems engineers at Colorado-based ventures, satellite operator procurement leads, and Artemis program contracting officers. Bottom-up mission cost modeling triangulated against top-down venture capital flow analysis across the space resource sector.
Historical trendline analysis of lunar demonstration program expenditures and asteroid prospecting investment flows established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include resource target type, extraction technology maturity tier, application end-use, and customer procurement modality. CAGRs derived from trajectory analysis of launch cost reduction curves and in-situ resource utilization technology maturation timelines, with specific inputs from propellant electrolysis efficiency improvements and autonomous drilling payload mass reduction coefficients.
Caveats apply where Artemis program funding continuity or FAA licensing backlog could materially shift the outlook for lunar infrastructure deployment schedules. Forecasts reflect assumptions about platinum group metal spot price stability and launch vehicle reusability progression. A small set of named triggers—regulatory jurisdiction competition, launch slot availability, and deep-space communication architecture deployment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
China Space Electronics Market
Space
Space Semiconductor Market
Space
Private Space Travel Market
Space
France Space Electronics Market
Space
Space Frame Market
Space
Space Lander and Rover Market
Space
South Korea Space Electronics Market
Space
India Space Electronics Market
Space
Germany Space Electronics Market
Space
Mexico Space Electronics Market
Space
Space Transportation Market
Space
Space Travel Market
Space
Space Mobile Service Market
Space
Rocket Launchpad Market
Space
Space Tourism Market
Space
Orbital Spaceflight Market