
 Droplet Separator Market | 2026-2036
Droplet Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Droplet Separator Market Analysis
Market Overview
Germany is reconfiguring European supply dynamics through specialized manufacturing corridors in North Rhine-Westphalia and Bavaria. GEA Group leverages its century-long process engineering heritage to sustain leadership in thermal separation systems. Sulzer Ltd. anchors Nordic supply reliability through precision manufacturing in Winterthur. Munters Group competes aggressively on energy-efficient designs for humid climate installations.
Technical Definition and Segmentation
A droplet separator is a mechanical device engineered to remove liquid droplets from gas streams through inertial impaction, typically achieving separation efficiencies above 99% for droplets larger than 10 microns in diameter, and serves to protect downstream equipment and ensure environmental compliance in process industries. Coalescing separator technology dominates current installed bases where sub-micron mist elimination proves critical, while centrifugal separator demand accelerates in offshore platforms where footprint constraints and motion tolerance outweigh absolute efficiency requirements. Gravity separator configurations occupy mature positions in water treatment pre-processing where low operating cost supersedes compact design priorities.
Regulatory Environment and Outlook
EPA enforcement of Maximum Achievable Control Technology standards and OSHA Process Safety Management requirements shape North American procurement specifications and inspection frequencies. The EU Green Deal's Industrial Emissions Directive revision tightens allowable particulate and liquid discharge thresholds, forcing upgrade cycles across German and Dutch chemical corridors. Stakeholders must monitor how carbon border adjustment mechanisms alter total cost of ownership calculations for imported versus locally fabricated separation equipment.
Market Dynamics
EPA emissions enforcement under the Clean Air Act is tightening allowable liquid carryover limits in industrial vents, forcing Gulf Coast refineries into accelerated replacement cycles for flare gas recovery systems and compressing supplier lead times across North American process engineering channels.
Growth Catalysts
- Clean Air Act MACT Standards:EPA enforcement of Maximum Achievable Control Technology mandates is compelling Texas and Louisiana petrochemical clusters to upgrade legacy separation equipment, creating replacement demand across downstream processing units.
- Offshore Platform Footprint Constraints:Centrifugal separator configurations are displacing gravity-based systems on floating production facilities where deck space premiums and motion tolerance requirements override absolute efficiency benchmarks.
- EU Green Deal Industrial Emissions Directive:The revised directive tightens particulate and liquid discharge thresholds across German and Dutch chemical corridors, forcing upgrade investments in thermal separation infrastructure.
Market Restraints
- Stainless Steel Input Volatility:Separator fabrication relies heavily on 316L and duplex stainless grades, exposing manufacturers to nickel and molybdenum price swings that compress margin visibility on fixed-price contracts.
- Specialized Welding Labor Scarcity:ASME Section VIII pressure vessel certification requirements limit the pool of qualified fabrication shops, concentrating supply capacity in Gulf Coast and Ruhr industrial zones.
- Coalescing Media Substitution Limits:Polypropylene and fiberglass mesh materials face technical barriers in high-temperature sour gas applications above 120°C, restricting deployment in certain upstream processing environments.
Strategic Opportunities
- Carbon Border Adjustment Mechanism Positioning:European fabricators can capture margin premiums by documenting embedded carbon intensity below imported equipment thresholds, leveraging local renewable energy inputs in North Rhine-Westphalia production corridors.
- Hydrogen Economy Pre-Treatment Demand:Electrolyzer and fuel cell manufacturing facilities require ultra-clean gas streams, opening new specification tiers for sub-micron mist elimination in renewable hydrogen production chains.
- Digital Twin Integration:Separator OEMs bundling predictive maintenance software with hardware sales can capture recurring revenue streams from reliability-conscious operators in Norwegian North Sea assets.
Industry Challenges
- Computational Fluid Dynamics Talent Gap:Separator design optimization requires specialized CFD modeling expertise that remains concentrated among senior engineers at legacy process equipment firms, constraining product development velocity at mid-tier competitors.
- Legacy System Integration Complexity:Brownfield installations in established Gulf Coast refineries must accommodate existing nozzle orientations and foundation footprints, complicating retrofit engineering and extending project timelines.
- Third-Party Certification Backlogs:ASME U-stamp and PED compliance documentation reviews face extended queue times at notified bodies, delaying equipment delivery schedules for time-sensitive turnaround windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Droplet Separator Market |
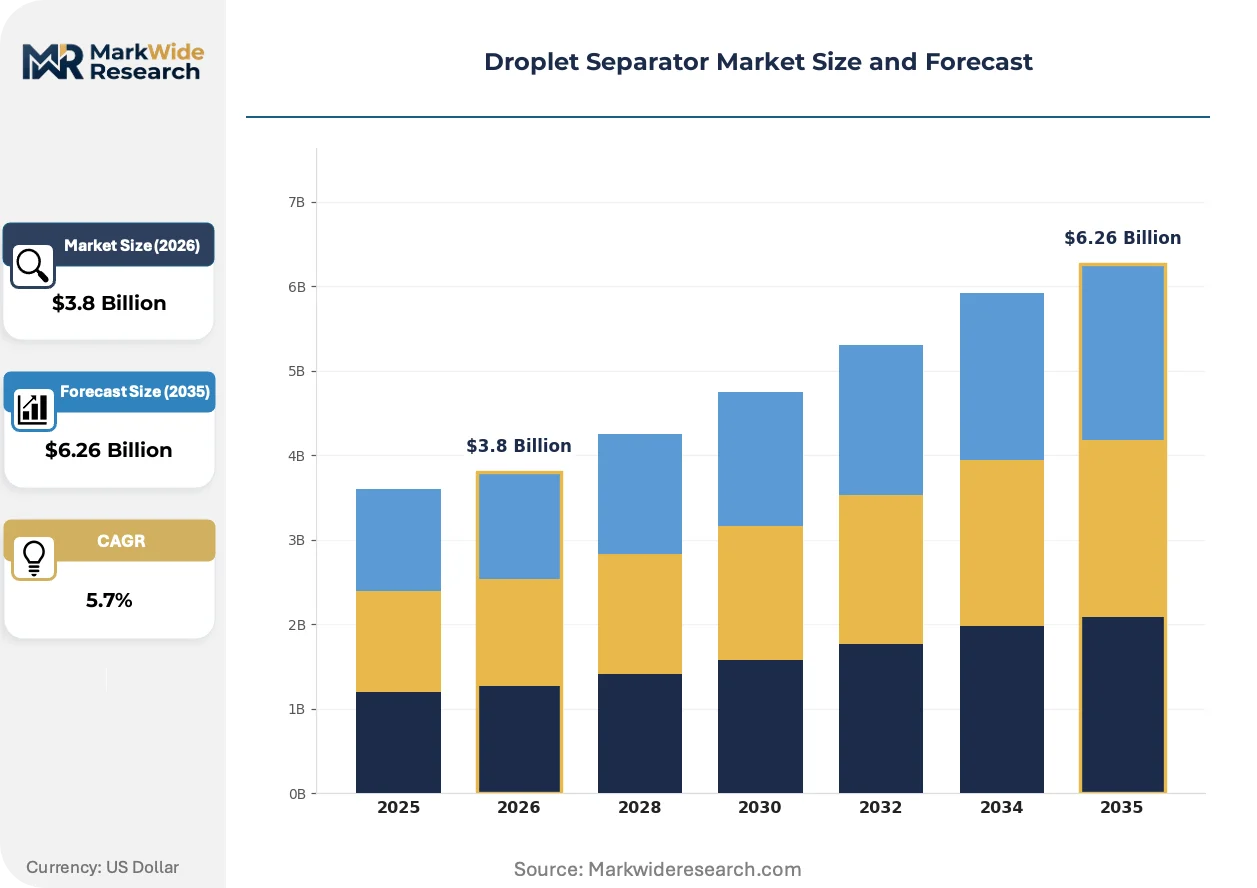
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coalescing Separator, Centrifugal Separator, Gravity Separator, Magnetic Separator Application: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage End User: Refineries, Power Plants, Municipalities, Pharmaceuticals Technology: Filtration, Distillation, Adsorption, Electrostatic |
| Companies Covered | GEA Group, Sulzer Ltd., Munters Group, Kimre Inc., Eaton Corporation, Alfa Laval AB, Parker Hannifin Corporation, SPX Flow, Nederman Holding AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Droplet Separator Market Emerging Trajectories
Sensor-embedded separation hardware is transforming maintenance economics across process industries, enabling condition-based service intervals that compress total cost of ownership calculations and reshape supplier-customer contracting structures.
Computational fluid dynamics simulation is digitizing separator design workflows, allowing GEA Group and Sulzer Ltd. engineering teams to validate vane pack geometries and demister pad configurations virtually before prototype fabrication. Major operators in Norwegian North Sea assets and Texas Gulf Coast refineries are adopting these digital validation protocols to reduce field testing cycles. This capability is digitizing competitive differentiation, compressing the traditional 18-month product development timeline toward 10-month windows for customized pressure vessel designs.
REACH chemical substance restrictions and the EU F-Gas Regulation are eliminating certain fluoropolymer coating options historically used in corrosive gas separation applications, forcing materials substitution toward ceramic and hastelloy alternatives. The industrial consequence is elevated capital cost for chemical processing installations in Rotterdam and Antwerp port zones. German fabricators in Winterthur and Bavaria are responding by qualifying nickel-based superalloy demister constructions for high-chloride service environments previously served by PTFE-lined components.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles, with large integrated operators in Louisiana petrochemical clusters now sourcing spare vane packs and coalescing elements through independent distributors rather than OEM captive channels. This pattern is most visible among supermajor operators with centralized procurement functions, where direct material sourcing from specialty mesh manufacturers in North Rhine-Westphalia bypasses traditional markup structures and compresses OEM service revenue pools.
Droplet Separator Market Segmentation
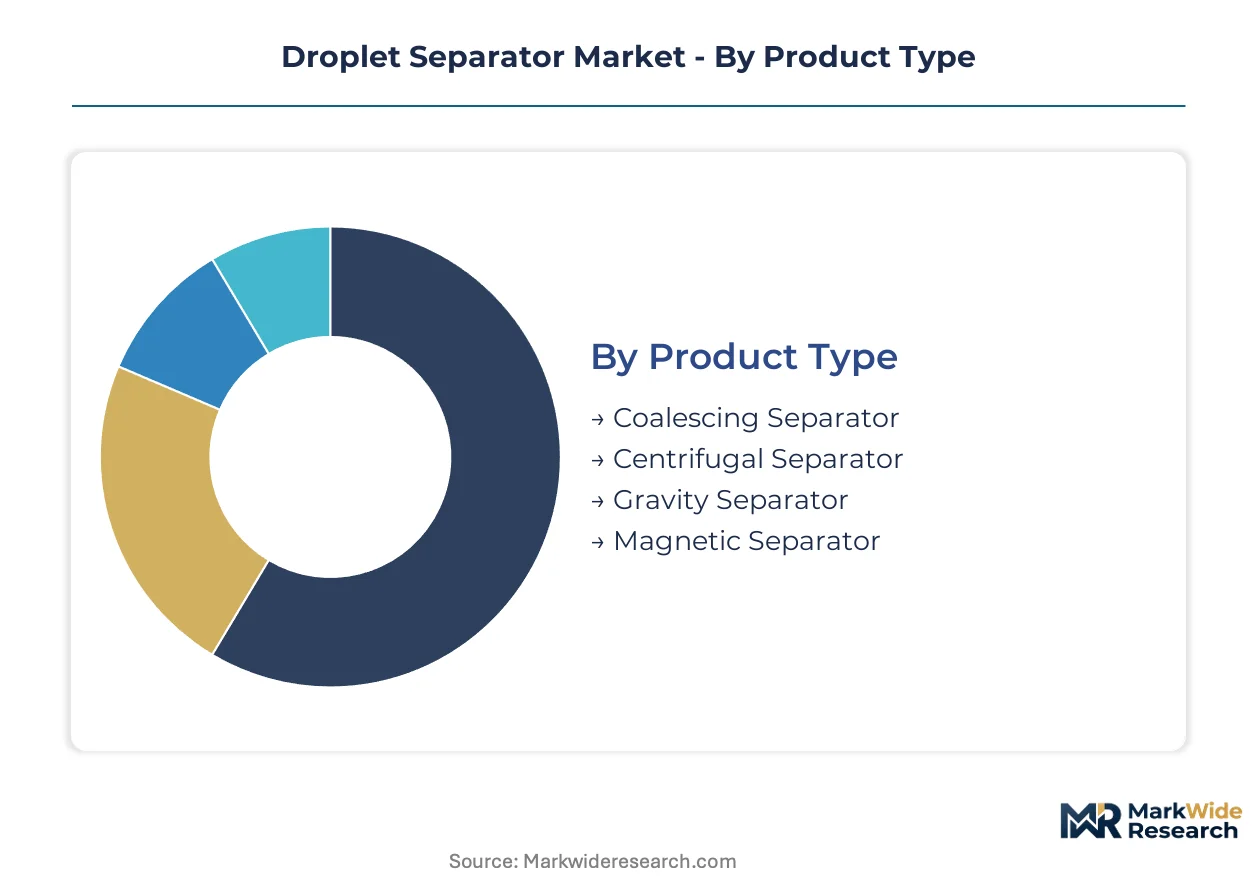
Segmentation in droplet separators reveals distinct procurement rhythms across product architectures and end-use environments. Replacement cycles vary from five-year intervals in refinery flare systems to fifteen-year spans in municipal water pre-treatment, creating asynchronous demand patterns that suppliers must navigate.
Product Type:
Replacement velocity diverges sharply across separator architectures, with offshore platforms driving accelerated centrifugal upgrade schedules while gravity installations persist for decades in water treatment basins.
- Coalescing Separator:Engineered with polypropylene or fiberglass mesh media to capture sub-micron liquid mists through progressive droplet agglomeration. Petrochemical clusters in Texas and Louisiana deploy these for EPA-compliant flare gas recovery where liquid carryover limits are tightening. Sour gas applications above 120°C force material substitution toward hastelloy constructions, elevating capital cost.
- Centrifugal Separator:Deploys rotational inertia to separate denser liquid phases from gas streams without consumable media. Floating production facilities in the Norwegian North Sea favor these configurations where deck space constraints and vessel motion tolerance override absolute efficiency requirements. Digitized predictive maintenance packages are bundling with hardware sales.
- Gravity Separator:Relies on density differential and residence time in large vessel footprints, dominating water treatment pre-processing where low operating cost supersedes compact design. Municipal installations in the US Gulf Coast region exhibit minimal replacement urgency.
- Magnetic Separator:Employs ferromagnetic capture mechanisms for specialized process streams containing magnetic particulate contamination. Niche deployment in pharmaceutical cleanrooms and select chemical processing corridors.
Gravity separators anchor the volume base while centrifugal configurations gain share at the steepest rate.
Application:
Procurement intensity maps directly to regulatory enforcement pressure, with oil and gas processing facing the most aggressive inspection frequencies and chemical processing tracking EU emissions directive revisions.
- Oil & Gas:Upstream production, midstream transport, and downstream refining operations generate sustained demand for high-pressure separation vessels. EPA MACT standards and OSHA Process Safety Management requirements compress replacement cycles across Texas and Louisiana assets. Brownfield retrofit complexity extends project timelines.
- Water Treatment:Municipal and industrial pre-treatment applications favor gravity-based systems with minimal maintenance overhead. Coalescing technology penetrates where effluent quality standards tighten.
- Chemical Processing:German and Dutch chemical corridors face EU Green Deal Industrial Emissions Directive upgrades. REACH restrictions on fluoropolymer coatings force ceramic and nickel-based superalloy substitutions.
- Food & Beverage:Hygienic design specifications and FDA compliance documentation shape procurement. Lower pressure ratings and stainless steel surface finish requirements differentiate this segment.
Oil and gas anchors the volume base while chemical processing gains share at the steepest rate.
End User:
Customer scale determines contracting structure, with supermajor refineries unbundling after-sales service while municipal purchasers retain bundled maintenance agreements.
- Refineries:Integrated downstream operators in the US Gulf Coast region drive the largest individual procurement volumes. Centralized procurement functions increasingly source spare vane packs through independent distributors rather than OEM captive channels.
- Power Plants:Flue gas desulfurization and steam cycle applications require corrosion-resistant constructions. Cycles align with major turnaround schedules.
- Municipalities:Water and wastewater treatment authorities prioritize lifecycle cost over initial capital. Extended decision timelines and public procurement regulations elongate sales cycles.
- Pharmaceuticals:Ultra-clean gas stream requirements for aseptic processing drive specification tiers approaching semiconductor-grade purity. Electrolyzer pre-treatment for renewable hydrogen production is emerging as adjacent demand.
Refineries anchor the volume base while pharmaceuticals gains share at the steepest rate.
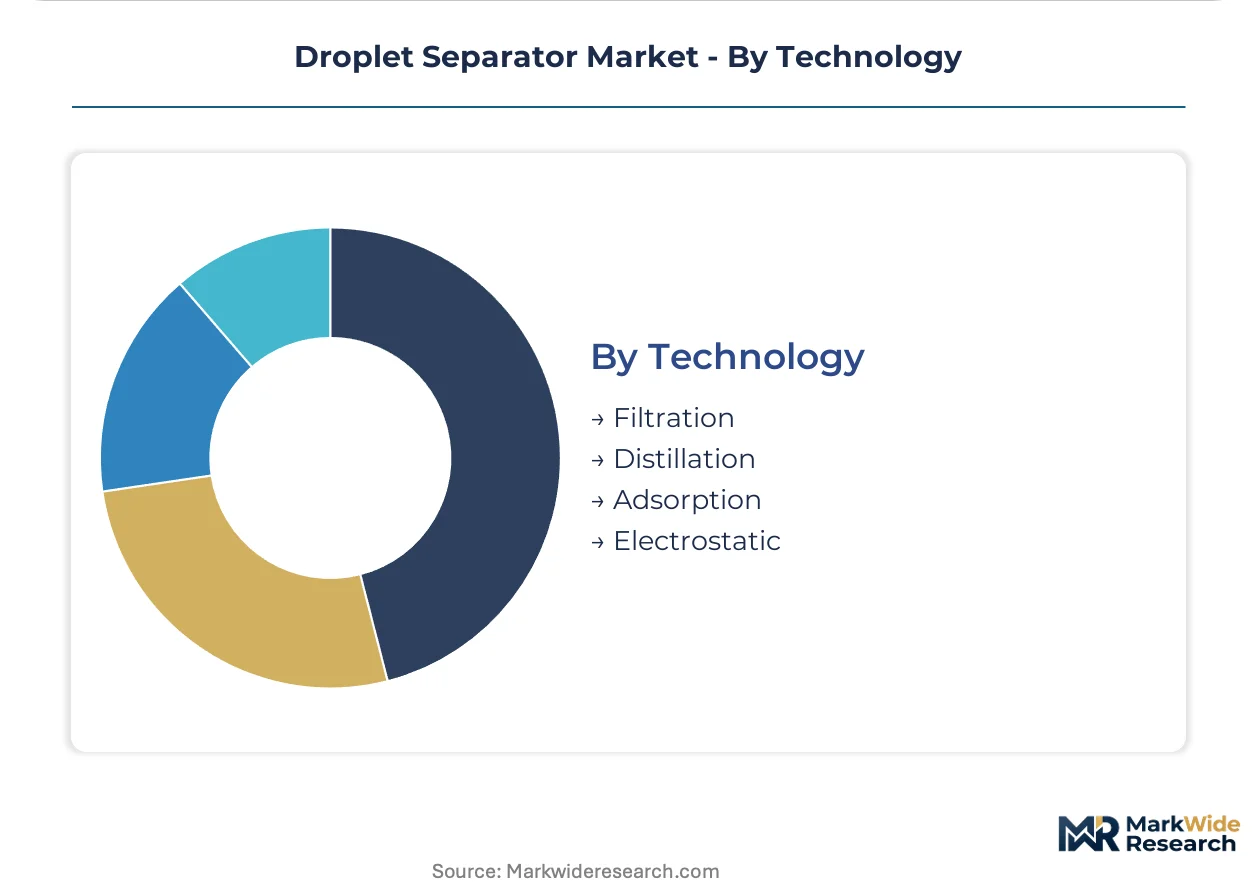
Technology:
Technology selection trades capital efficiency against operating precision, with filtration dominating installed bases and electrostatic methods penetrating specialized high-value niches.
- Filtration:Vane packs, demister pads, and mesh coalescers constitute the broadest installed base across process industries. GEA Group and Sulzer Ltd. compete on CFD-optimized geometry designs.
- Distillation:Thermal separation for close-boiling mixtures where mechanical droplet removal proves insufficient. Energy intensity limits deployment scope.
- Adsorption:Activated carbon and molecular sieve systems for trace contaminant removal downstream of primary separation. Niche positioning in pharmaceutical and food-grade applications.
- Electrostatic:Charged field precipitation for sub-micron aerosols below mechanical capture thresholds. Premium pricing in specialized chemical and electronics manufacturing environments.
Filtration anchors the volume base while electrostatic methods gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of Clean Air Act standards anchors procurement intensity in the United States, while EU emissions directives and offshore platform investments shape demand across European and North Sea markets.
United States
Texas and Louisiana petrochemical clusters drive replacement cycles for flare gas recovery systems. EPA Maximum Achievable Control Technology standards compress supplier lead times across Gulf Coast process engineering channels. Houston-area refineries face accelerated inspection frequencies under tightening liquid carryover limits.
Germany
North Rhine-Westphalia chemical corridors reconfigure European supply dynamics through specialized manufacturing networks. EU Green Deal Industrial Emissions Directive revisions force upgrade investments in thermal separation infrastructure. Bavarian fabricators leverage local renewable energy inputs to document embedded carbon intensity below import thresholds.
Norway
Floating production facilities in the Norwegian North Sea favor centrifugal configurations where deck space premiums override efficiency benchmarks. Predictive maintenance software bundling reshapes supplier contracting structures across offshore assets. Stavanger-based operators digitize condition-based service intervals.
Netherlands
Rotterdam and Antwerp port zones face elevated capital costs from REACH chemical restrictions eliminating fluoropolymer coating options. Industrial Emissions Directive compliance forces ceramic and nickel-based superalloy substitutions in high-chloride service environments. Dutch chemical processors qualify alternative demister constructions.
China
Dual carbon goals and industrial emissions standards tighten discharge thresholds across Yangtze River Delta chemical processing hubs. Domestic fabrication capacity expands for pressure vessels serving refinery and petrochemical complexes. Shanghai-based engineering firms accelerate CFD-optimized separator design adoption.
Droplet Separator Market Vendor Landscape
Capability concentration sits with heritage engineering specialists; scale advantage sits with diversified industrial conglomerates. The vendor base organizes around three strategic archetypes: century-long process engineering houses with thermal separation heritage, precision manufacturing specialists from Nordic supply corridors, and diversified flow control conglomerates with captive distribution networks. Competitive moves center on predictive maintenance software bundling and carbon border adjustment documentation to capture margin premiums.
Within the heritage engineering tier, GEA Group and Sulzer Ltd. occupy positions defined by century-long thermal separation expertise and precision manufacturing legacies respectively. Munters Group exemplifies the energy-efficient design specialist archetype competing aggressively on humid climate installations. These three anchors demonstrate how fabrication heritage and geographic concentration in North Rhine-Westphalia and Winterthur production corridors sustain competitive differentiation against diversified industrial players.
| Leading Market Players |
|---|
| GEA Group |
| Sulzer Ltd. |
| Munters Group |
| Kimre Inc. |
| Eaton Corporation |
| Alfa Laval AB |
| Parker Hannifin Corporation |
| SPX Flow |
| Nederman Holding AB |
| Others |
Supply Flow & Price Mechanics
North Rhine-Westphalia fabrication corridors concentrate ASME-certified pressure vessel capacity, translating localized stainless steel input access into margin premiums for German suppliers serving Dutch chemical processors. Gulf Coast refineries face compressed pricing leverage against this European supply concentration as EPA turnaround windows tighten procurement urgency.
Pricing Analysis
Price spreads between German and Chinese fabricated units widen during nickel and molybdenum volatility cycles. Three-tier pricing structure across premium, standard, and economy levels differentiates by ASME Section VIII certification grade and bundled predictive maintenance software. Cost compression in standard-grade centrifugal configurations is intensifying because independent distributors now source spare vane packs directly from specialty mesh manufacturers. Municipal water treatment authorities exhibit highest price sensitivity; offshore platform operators accept premium positioning for motion-tolerant designs.
Supply Chain Analysis
Tariff exposure between European Union and Chinese steel inputs dominates fabrication cost uncertainty for pressure vessel constructors. Supply concentrates in Germany, Switzerland, and the United States for ASME-certified production. Separator fabrication draws from 316L and duplex stainless grades, polypropylene mesh media, and nickel-based superalloy demister constructions. Single-source vulnerability concentrates in qualified welding labor pools certified for sour gas service. Distribution runs through OEM captive channels and emerging independent aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance software bundling expands recurring revenue faster than hardware sales across Norwegian North Sea assets, repositioning separator OEMs toward service-attach economics.
For Market Incumbents: Insulate margin position by deepening backward integration into specialty mesh manufacturing in North Rhine-Westphalia corridors and accelerating CFD talent acquisition against mid-tier competitors. Carbon border adjustment documentation capabilities defend pricing power against lower-cost Asian imports. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical electrolyzer pre-treatment segments where ultra-clean gas specifications create specification tiers above commodity refinery applications. Hydrogen economy infrastructure buildouts offer penetrable demand with limited incumbent software bundling. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA and EU emissions enforcement tightens replacement cycles independent of underlying industrial output cycles. Target fabrication specialists with ASME U-stamp certification backlogs and documented renewable energy inputs for carbon border positioning. Watch hydrogen economy capital commitment announcements as inflection signal for sub-micron mist elimination demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Bundling | Captures recurring revenue from Norwegian North Sea operators digitizing condition-based service intervals. |
| Carbon Border Adjustment Documentation | Enables German fabricators to leverage local renewable energy inputs for margin premiums against imports. |
| CFD-Optimized Geometry Development | Compresses product development timelines for GEA Group and Sulzer Ltd. engineering teams. |
| Backward Integration into Mesh Manufacturing | Defends service revenue pools against independent distributor bypass in Louisiana petrochemical clusters. |
| Hydrogen Economy Pre-Treatment Qualification | Opens specification tiers for electrolyzer gas cleaning in renewable hydrogen production chains. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers at Gulf Coast refineries, aftermarket service heads at Norwegian offshore operators, procurement leads at Dutch chemical processors, and maintenance directors at German power plants, then refined through customs trade data, SEC filings from diversified industrial conglomerates, EPA enforcement action databases, and EU Industrial Emissions Directive compliance records. Bottom-up unit economics triangulated against top-down sector spending patterns validated market sizing.
Demand-supply balance modeling across the projection horizon segmented by separator architecture, end-use intensity, certification tier, and regional regulatory cluster. CAGRs derived from replacement cycle analysis and enforcement-driven upgrade schedules. Forecast inputs incorporated stainless steel price volatility indices and ASME certification queue times at notified bodies.
Sensitivities concentrate around nickel and molybdenum commodity swings, welding labor availability at Gulf Coast fabrication shops, and carbon border adjustment mechanism implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Automatic Tank Cleaning Systems Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Marine Pump Market