
 Global Diaphragm Pump Market | 2026-2036
Global Diaphragm Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diaphragm Pump Market Foresight
Market Context with Strategic Players
REACH is recalibrating the cost-of-entry calculus for European diaphragm pump suppliers by mandating perfluorinated compound disclosures and material traceability. IDEX Corporation leverages its vertically integrated elastomer manufacturing to preempt compliance bottlenecks across EU member states. Flowserve Corporation anchors its competitive stance through severe-service alloy casting capabilities that exceed emerging corrosion-resistance benchmarks. Graco Inc. differentiates via modular pump architecture that simplifies field retrofitting for regulatory transitions.
Technical Definition and Structural Segments
A diaphragm pump is a positive-displacement device that transfers fluids through the reciprocating action of a flexible membrane, typically constructed from PTFE, EPDM, or thermoplastic elastomers, with flow rates spanning microliters to thousands of gallons per minute depending on drive configuration. The mechanism isolates process fluid from mechanical components, making it indispensable for shear-sensitive, abrasive, or hazardous media in chemical processing and pharmaceutical production. Air-operated technology captures the dominant share of corrosive-fluid installations due to intrinsic spark resistance and stall-free operation under dead-head conditions. Electric motor-driven systems are gaining ground in water treatment utilities seeking energy recovery and precise flow modulation. Pneumatic technology retains primacy in mining dewatering applications where explosive atmospheres preclude electrified alternatives.
Regulatory Frame and Forward-Looking Close
The EPA enforces Clean Water Act effluent limitations that compel US chemical manufacturers to upgrade legacy pumping infrastructure, while EMA and FDA GMP guidelines impose material certification requirements on pharmaceutical producers in Europe and North America. China's MEE administers wastewater discharge standards that accelerate diaphragm pump replacement cycles in coastal manufacturing zones. Stakeholders must weigh material compatibility against evolving per- and polyfluoroalkyl substance restrictions when specifying elastomer formulations for next-generation installations.
Market Dynamics
REACH compliance deadlines and EPA effluent rule enforcement are compressing replacement cycles for legacy pumping infrastructure across chemical processing clusters, forcing asset owners to prioritize material traceability and seal-integrity specifications in procurement decisions.
Growth Catalysts
- REACH perfluorinated compound mandates:European chemical manufacturers must retrofit facilities with pumps featuring certified elastomer formulations, accelerating demand for compliant diaphragm systems in Germany, France, and the Netherlands.
- Air-operated double-diaphragm technology:Intrinsic safety characteristics drive adoption in explosive atmosphere applications across Brazilian mining operations and Saudi petrochemical complexes.
- Water treatment infrastructure:China's MEE wastewater discharge standards compel municipal utilities in coastal manufacturing zones to replace conventional centrifugal pumps with zero-leakage diaphragm alternatives.
Market Restraints
- Specialized elastomer supply concentration:PTFE and perfluoroelastomer feedstock production concentrates among Japanese and German specialty chemical suppliers, exposing pump manufacturers to input cost volatility and allocation constraints.
- Electric drive substitution in clean-fluid applications:Progressive cavity and magnetically driven centrifugal pumps capture share in non-corrosive, low-viscosity transfer duties where diaphragm technology holds no intrinsic advantage.
- Extended REACH certification timelines:Material traceability documentation requirements add 4-8 months to product qualification cycles, delaying revenue recognition for new elastomer formulations.
Strategic Opportunities
- Modular retrofit architectures:Field-convertible pump configurations enable chemical processors to adapt existing assets for evolving regulatory transitions without full replacement capex.
- Pharmaceutical single-use systems:Biologics manufacturers in Switzerland and Ireland demand disposable diaphragm pump components to eliminate cross-contamination risks in multi-product facilities.
- Digital predictive maintenance integration:Vibration and pressure sensor convergence with diaphragm pump mechanics creates aftermarket service revenue streams in US and German industrial clusters.
Industry Challenges
- Per- and polyfluoroalkyl substance skill gaps:Field service technicians lack training in PFAS-free elastomer handling and failure-mode diagnosis, complicating warranty support for next-generation installations.
- Legacy system integration complexity:Chemical plants in the US Gulf Coast and German Ruhr region operate 1980s-era distributed control systems that resist seamless interface with smart pump diagnostics.
- Multi-jurisdiction certification stacking:Pump suppliers targeting pharmaceutical exports must simultaneously satisfy FDA, EMA, and PMDA material certification requirements with non-overlapping documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diaphragm Pump Market |
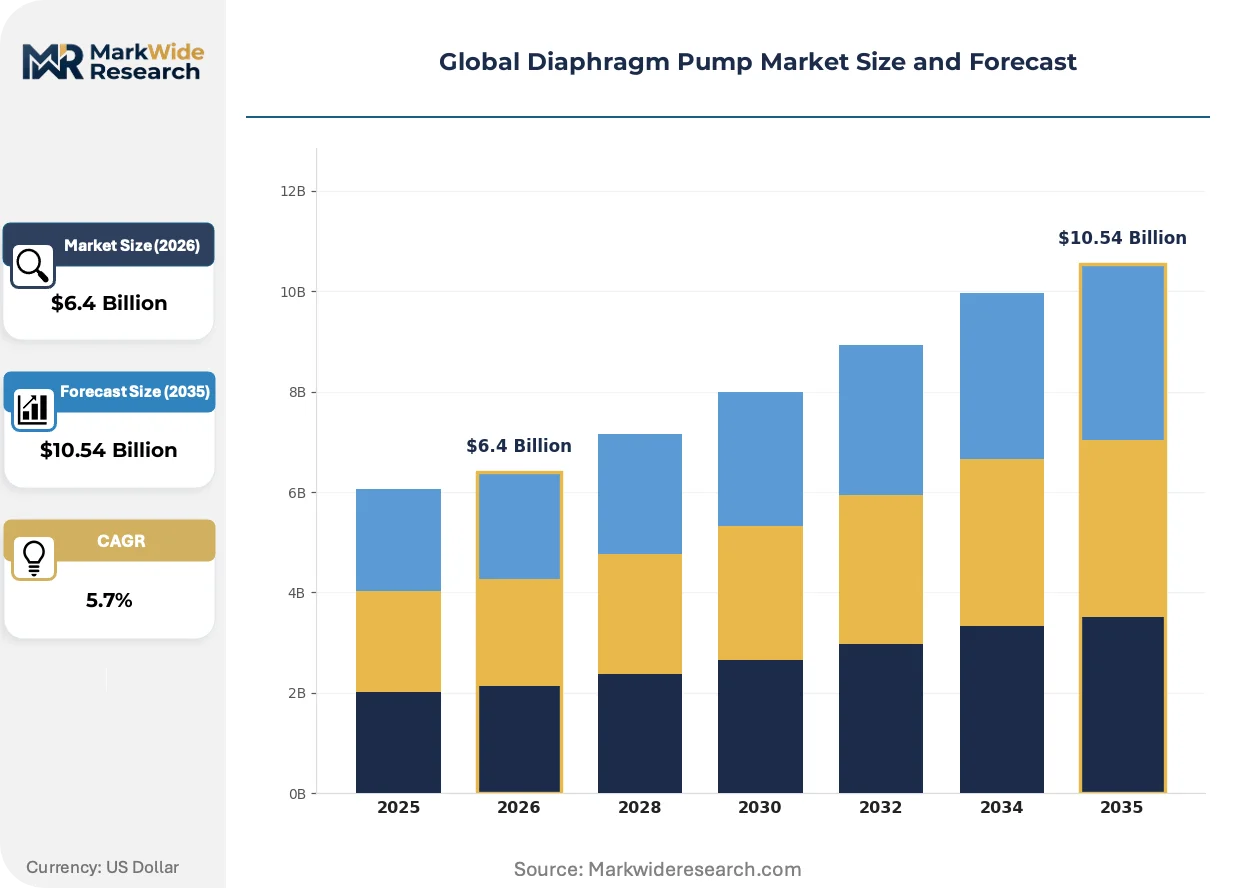
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Operated, Electric, Hydraulic, Manual Technology: Mechanical Diaphragm, Solenoid, Pneumatic, Motor Driven Application: Water Treatment, Chemical Processing, Food & Beverage, Pharmaceuticals, Mining End User Industry: Chemical Manufacturers, Food Processors, Pharmaceutical Producers, Mining Firms, Water Utilities |
| Companies Covered | IDEX Corporation, Flowserve Corporation, Graco Inc., Grundfos Holding A/S, Ingersoll Rand, Yamada Corporation, Xylem Inc., LEWA GmbH, Dover Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diaphragm Pump Market Shifts & Advancements
Smart diaphragm pump architectures incorporating real-time condition monitoring and predictive analytics are compressing maintenance intervals and reshaping aftermarket service economics across process industries.
Advanced thermoplastic elastomer compounds with embedded fiber reinforcement are rewriting durability benchmarks for abrasive slurry handling. Mining operators in Western Australia and Chilean copper belts specify these materials for tailings transfer applications previously requiring metal pump rebuilds every 90 days. The technology is compressing total cost-of-ownership calculations and displacing conventional rubber-lined alternatives in severe-service procurement evaluations.
EPA Clean Water Act effluent limitation guidelines are mandating zero-discharge standards for chemical manufacturing facilities in Texas and Louisiana. The regulatory pressure forces pump specification teams to prioritize seal-less positive displacement technologies over mechanical seal configurations in hazardous fluid containment duties. US Gulf Coast chemical processors now require third-party verification of pump fugitive emission rates as a standard procurement gate.
Asset-as-a-service contracting models are displacing traditional capital purchase arrangements in European water treatment utilities. Municipal operators in Denmark and the Netherlands prefer fixed-cost-per-cubic-meter agreements that transfer maintenance liability and technology obsolescence risk to pump suppliers. The shift concentrates purchasing authority among national procurement consortia and compresses vendor margins in exchange for decade-long service commitments.
Global Diaphragm Pump Market Segmentation
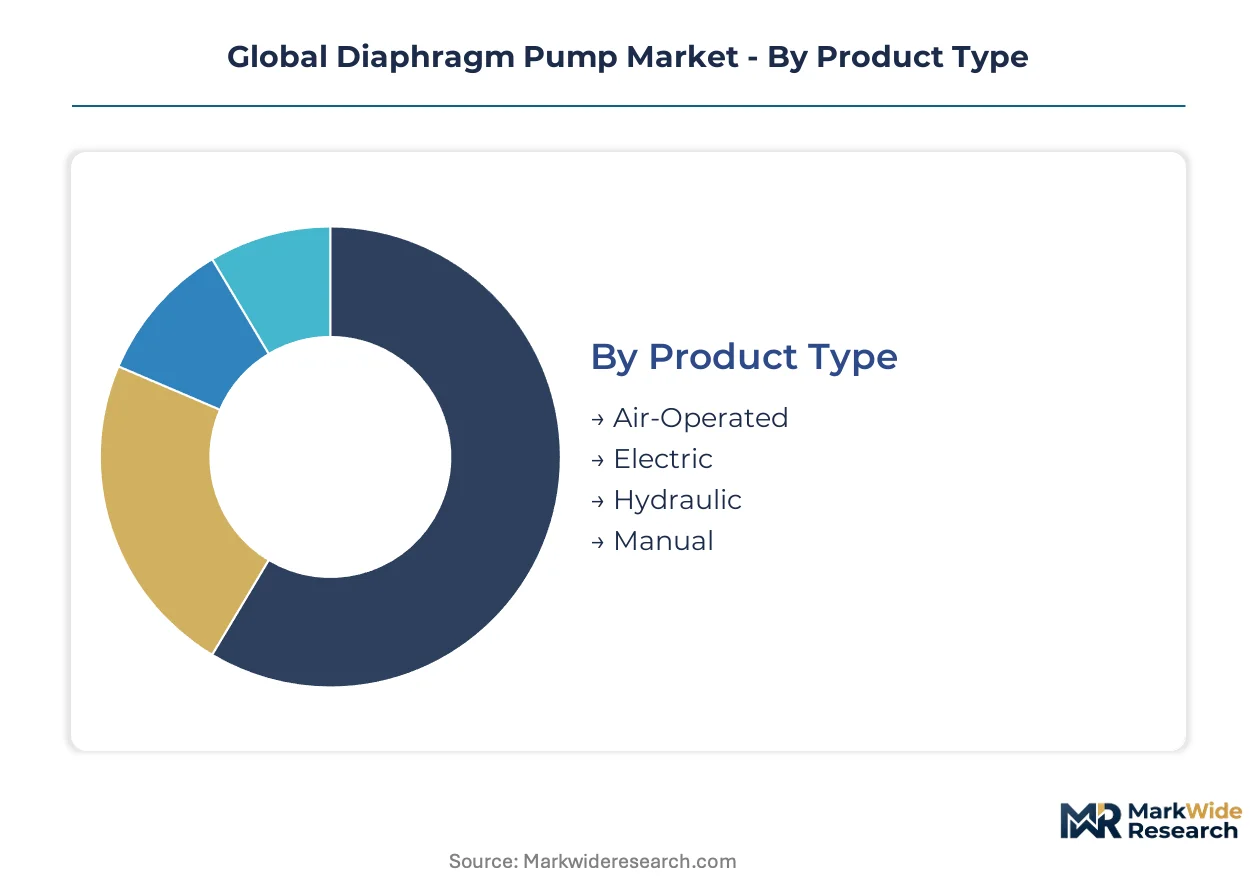
Diaphragm pump procurement hinges on matching drive mechanism to duty cycle, media corrosivity, and regulatory exposure. Buyers prioritize seal integrity certifications in chemical and pharmaceutical applications while weighing energy recovery potential in municipal water systems.
Product Type:
Capital intensity and operating environment dictate product selection across process industries.
- Air-Operated:Compressed-air-driven reciprocating action delivers intrinsic spark resistance and stall-free dead-head operation. Brazilian mining conglomerates and Saudi Aramco petrochemical complexes specify these units for explosive atmosphere zones under strict national safety mandates.
- Electric:Motor-driven configurations enable precise flow modulation and energy recovery in clean-fluid applications. German water utilities in the Ruhr region retrofit aging centrifugal stations with variable-frequency electric diaphragm pumps to meet ECHA discharge standards.
- Hydraulic:Fluid-powered actuation generates high-pressure output for slurry transfer in remote mining locations lacking compressed air infrastructure.
- Manual:Hand-operated mechanisms serve laboratory sampling and emergency bypass duties in pharmaceutical cleanrooms.
Air-operated units lead on scale across hazardous fluid installations; electric systems lead on momentum in energy-conscious municipal infrastructure.
Technology:
Actuation method determines maintenance intervals, pulsation characteristics, and compatibility with legacy control architectures.
- Mechanical Diaphragm:Crankshaft-driven flexing membrane delivers consistent displacement for abrasive tailings in Chilean copper extraction.
- Solenoid:Electromagnetic pulse actuation enables microliter-precision dosing in Swiss biologics manufacturing.
- Pneumatic:Compressed air reciprocation dominates South Korean semiconductor chemical delivery systems requiring zero contamination risk.
- Motor Driven:Direct-coupled electric motors anchor US Gulf Coast chemical processor upgrades under EPA effluent enforcement.
Pneumatic technology captures the broadest installed base; motor-driven configurations are climbing fastest in regulated water treatment sectors.
Application:
Media characteristics and containment requirements segment demand across process intensity tiers.
- Water Treatment:Zero-leakage positive displacement meets China's MEE coastal discharge mandates in Shanghai and Shenzhen municipal plants.
- Chemical Processing:Corrosive acid and caustic transfer in BASF Ludwigshafen and Dow Texas Operations demands PTFE-lined configurations.
- Food & Beverage:Hygienic elastomer formulations satisfy FDA dairy pasteurization line requirements in Wisconsin.
- Pharmaceuticals:Single-use disposable diaphragm assemblies eliminate cross-contamination in Irish multi-product biologics facilities.
- Mining:Abrasive slurry handling in Western Australian iron ore operations specifies fiber-reinforced thermoplastic diaphragms.
Chemical processing commands the largest equipment spend; pharmaceutical applications show the steepest specification escalation.
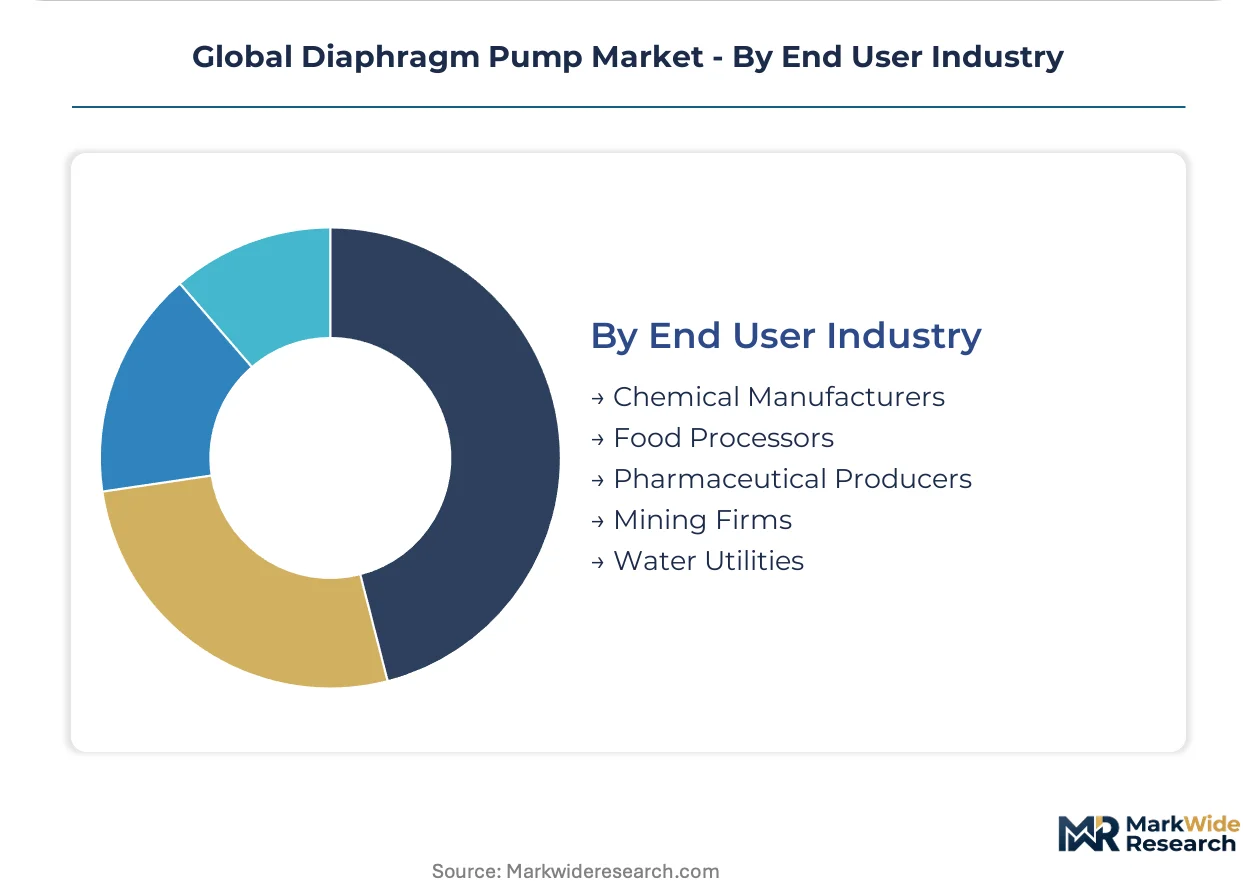
End User Industry:
Procurement authority concentrates among asset-intensive operators with captive maintenance capabilities.
- Chemical Manufacturers:Integrated producers in Germany's Chemical Triangle and US Gulf Coast drive specification standardization for REACH and EPA compliance.
- Food Processors:Dairy cooperatives in the Netherlands and Wisconsin prioritize clean-in-place compatibility and 3A sanitary certification.
- Pharmaceutical Producers:Swiss and Irish biologics specialists demand disposable pump path technologies for multi-product flexibility.
- Mining Firms:Copper and iron ore operators in Chile and Australia specify severe-service diaphragm materials for tailings management.
- Water Utilities:Danish and Dutch municipal consortia negotiate asset-as-a-service contracts transferring obsolescence risk to suppliers.
Chemical manufacturers anchor volume procurement; water utilities are gaining share fastest through service-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diaphragm pump manufacturing originated in German industrial engineering traditions during the early twentieth century, with precision metalworking clusters in the Ruhr region establishing foundational casting and machining capabilities that persist in today's severe-service alloy production.
United States
Gulf Coast chemical processors in Texas and Louisiana drive replacement demand as EPA Clean Water Act enforcement tightens fugitive emission standards. The EPA mandates third-party verification of pump seal integrity for hazardous fluid containment. Houston-area petrochemical complexes now specify zero-leakage positive displacement systems for acid and caustic transfer duties.
Germany
Chemical manufacturers in Ludwigshafen and Leverkusen retrofit facilities to meet REACH perfluorinated compound disclosure requirements. ECHA material traceability mandates compress procurement cycles for certified elastomer formulations. The Chemical Triangle spanning North Rhine-Westphalia and Hesse anchors European demand for PTFE-lined process pumps.
China
Coastal municipal utilities in Shanghai and Shenzhen replace conventional centrifugal infrastructure under MEE wastewater discharge standards. The Ministry of Ecology and Environment enforces zero-discharge thresholds in manufacturing zones along the Yangtze River Delta. Zhejiang and Jiangsu province water treatment plants specify air-operated double-diaphragm units for abrasive slurry handling.
Brazil
Mining conglomerates in Minas Gerais and Pará specify spark-resistant pneumatic pumps for explosive atmosphere zones in iron ore and copper extraction. ANVISA safety mandates govern equipment certification for underground operations. The Carajás mineral province drives demand for severe-service diaphragm materials in tailings transfer applications.
Saudi Arabia
Petrochemical complexes in Jubail and Yanbu procure air-operated systems for hydrocarbon processing under strict national safety regulations. SFDA material certification requirements apply to pharmaceutical-grade pump installations in Riyadh manufacturing zones. The Eastern Province industrial corridor concentrates demand for corrosion-resistant fluid transfer equipment.
Global Diaphragm Pump Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive elastomer manufacturing capabilities. Tier-one positions concentrate among pump specialists with vertically integrated material science operations and severe-service alloy casting facilities. Three archetypes dominate: integrated industrial conglomerates with multi-product fluid handling portfolios; mid-scale specialists focused on modular architectures and field retrofit solutions; and regional fabricators serving price-sensitive mining and water utility sectors. Capacity expansion in thermoplastic elastomer compounding and strategic partnerships for predictive maintenance software integration represent the dominant competitive moves.
Among diversified industrial conglomerates, IDEX Corporation and Flowserve Corporation exemplify the integrated archetype through captive supply of certified elastomer formulations and severe-service casting capabilities. Graco Inc. occupies a position within the modular-specialist tier, with field-convertible pump architectures that reduce regulatory transition costs for chemical processors. Yamada Corporation and LEWA GmbH represent precision-engineering traditions from Japanese and German manufacturing clusters respectively, anchoring premium-tier positioning in pharmaceutical and semiconductor process applications.
| Leading Market Players |
|---|
| IDEX Corporation |
| Flowserve Corporation |
| Graco Inc. |
| Grundfos Holding A/S |
| Ingersoll Rand |
| Yamada Corporation |
| Xylem Inc. |
| LEWA GmbH |
| Dover Corporation |
| Others |
Supply & Pricing Matrix
Specialized elastomer compounding expertise concentrates in German and Japanese industrial corridors, where labor-cost differentials between Ruhr Valley precision engineers and Osaka specialty chemical technicians widen pricing-tier spreads across certified REACH-compliant pumps versus standard-duty alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs diaphragm pump procurement, with certification grade and after-sales service bundling as the primary price differentiation drivers. Cost compression in economy-tier pneumatic units is intensifying because Brazilian and Saudi mining buyers prioritize asset availability over brand premium. Water utilities in Denmark and the Netherlands exhibit lowest price sensitivity due to decade-long asset-as-a-service contracting, while regional fabricators serving Chilean tailings operations face acute margin pressure.
Supply Chain Analysis
PTFE and perfluoroelastomer feedstock supply rests on Japanese and German specialty chemical producers, with secondary sourcing from South Korean fluoropolymer compounders. Raw material dependencies center on fluorspar concentrates, specialty resin formulations, and fiber-reinforced thermoplastic substrates. Single-source vulnerability in medical-grade elastomer certification creates exposure for pharmaceutical pump suppliers. Distribution runs through national industrial distributors in process industries and direct OEM relationships in water utility consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diaphragm pump market reads as a late-cycle quality story, with REACH and EPA regulatory escalation forcing asset owners toward premium-specification pumps with traceable elastomer provenance and predictive maintenance integration.
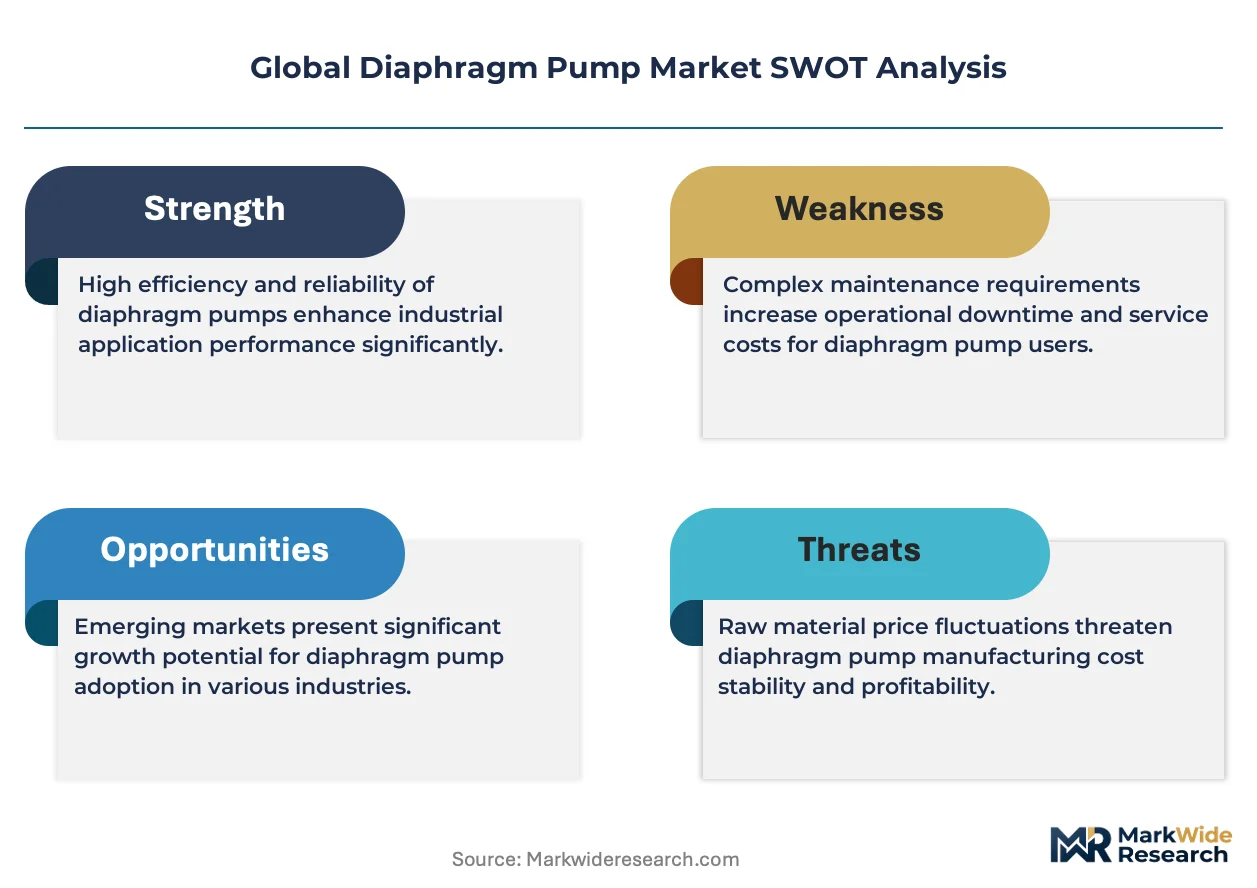
For Market Incumbents: Anchor competitive position through captive control of certified elastomer formulation capacity and severe-service alloy casting facilities. Magnetically driven centrifugal pumps threaten share in clean-fluid water treatment applications, necessitating defensive certification investment in FDA and EMA material documentation. Channel control through exclusive distribution partnerships with German and US Gulf Coast chemical processors protects pricing power. For New Entrants and Emerging Players: Municipal water utilities in China's Yangtze River Delta represent an underserved buyer archetype with compressed procurement cycles under MEE zero-discharge mandates. Modular retrofit architectures for legacy centrifugal stations offer the most penetrable entry path, with go-to-market positioning around field-convertible configurations that eliminate full replacement capex. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale modular specialists with pharmaceutical single-use capabilities but limited geographic footprint. Long-term viability over the analysis window favors targets with predictive maintenance software integration and thermoplastic elastomer compounding assets. Watch for inflection in PFAS-free elastomer qualification timelines as the signal for margin recovery in premium-tier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive PTFE formulation capacity preempts REACH certification bottlenecks for IDEX and Flowserve. |
| Predictive Maintenance Platform Integration | Vibration sensor convergence with pump mechanics creates recurring revenue streams in German industrial clusters. |
| Pharmaceutical Single-Use System Expansion | Disposable diaphragm assemblies address cross-contamination risks in Irish and Swiss biologics facilities. |
| Modular Retrofit Architecture Development | Field-convertible pumps reduce regulatory transition costs for BASF and Dow chemical processors. |
| Asset-as-a-Service Contracting Model | Fixed-cost-per-cubic-meter agreements transfer obsolescence risk to suppliers in Danish water utilities. |
Research Methodology
Bottom-up chemical processing and water utility modeling reconciled against top-down elastomer supplier and pump manufacturer tracking forms the analytical core. Primary interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and distribution channel partners combined with secondary validation from ECHA REACH filings, EPA enforcement databases, customs trade data, and SEC 10-K disclosures. Triangulation between demand-side asset replacement schedules and supply-side capacity announcements ensures cross-verification.
Input-output matrices map drive mechanism selection to duty cycle intensity, media corrosivity tiers, and regulatory exposure levels across the projection horizon. Segmentation dimensions include product type, actuation technology, application severity, and end-user industry procurement authority. CAGRs derive from installed base depreciation curves, replacement cycle compression under evolving effluent rules, and penetration rates of electric drive systems in municipal infrastructure. Forecast inputs incorporate MEE wastewater discharge enforcement timelines and ECHA perfluorinated compound restriction phases.
Inputs from ECHA certification databases and EPA enforcement records were available through the study window; gaps in real-time pharmaceutical single-use adoption rates introduce uncertainty bands in biologics segment projections. Forecasts reflect documented assumptions regarding regulatory implementation pacing and elastomer supply allocation. Supply concentration in Japanese fluorspar processing and REACH documentation delays represent specific revision triggers. A small set of regulatory enforcement intensity indicators and PFAS-free material qualification milestones warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Plate Heat Exchanger Market