
 Asia Pacific Oil and Gas CAPEX Market | 2026-2036
Asia Pacific Oil and Gas CAPEX Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Oil and Gas CAPEX Market Outlook
Australian LNG producers is repositioning their brownfield expansion portfolios toward carbon-neutral liquefaction trains. Petronas leverages integrated upstream-downstream operations across Malaysia's deepwater blocks to sustain project returns. CNOOC anchors its spending profile in the South China Sea, where tieback developments reduce per-barrel development costs. Shell plc differentiates through floating LNG expertise, competing for pre-salt and ultra-deepwater contracts across Southeast Asian waters.
Asia Pacific Oil and Gas CAPEX encompasses capital deployed across exploration, development, production, and infrastructure assets spanning onshore fields, offshore platforms, subsea systems, pipelines, refineries, and LNG liquefaction trains, with typical project lifecycles extending 15-30 years and requiring sustained investment in drilling rigs, wellhead equipment, and processing facilities to extract, transport, and transform hydrocarbons into marketable fuels and feedstocks. Upstream spending dominates the value pool given the region's maturing basins and frontier exploration requirements, while midstream transportation infrastructure captures growing capital allocation as cross-border pipeline networks and LNG export terminals expand capacity to serve Northeast Asian demand centers. Downstream refining investments face structural pressure from electrification trends, though petrochemical integration projects in China and India sustain select greenfield refinery complexes.
China's MEE enforces methane intensity standards that elevate compliance costs for conventional field operators, while Australia's NOPSEMA imposes stringent offshore safety and environmental management requirements that extend project sanction timelines. Indonesia's SKK Migas coordinates production sharing contract terms that directly shape contractor capital commitment schedules and cost recovery mechanisms. Stakeholders must monitor regulatory divergence across these frameworks when allocating capital across national jurisdictions with diverging decarbonization timelines and local content mandates.
Market Dynamics
China's dual carbon goals are compressing investment timelines for conventional extraction assets while redirecting capital toward integrated carbon capture systems across the Asia Pacific upstream portfolio.
Growth Catalysts
- Deepwater frontier basins:Indonesia's eastern frontier blocks and Australia's northwest shelf sustain exploration drilling commitments through improved seismic imaging and subsea tieback economics.
- MEE methane intensity standards:China's enforcement of fugitive emissions protocols is accelerating facility upgrade cycles and leak detection technology deployment across Sichuan and Tarim basin operations.
- Northeast Asian LNG demand:Contracting appetite from Japanese power utilities and Korean city gas distributors underpins liquefaction train expansion commitments in Australia and Malaysia.
Market Restraints
- Steel and alloy input volatility:Specialized sour service grades and corrosion-resistant alloys for subsea manifolds face price swings that destabilize project sanction economics.
- NOPSEMA approval timelines:Australia's offshore safety regulator extends environmental plan assessments by 8-14 months, compressing contractor cash flow cycles.
- Electrification substitution:Grid-scale battery storage and renewable hydrogen pilots in Japan and South Korea erode long-term gas-fired power demand visibility.
Strategic Opportunities
- Carbon capture integration:Australia's Carbon Capture Use and Storage Development Fund creates offtake certainty for gas processing facilities with integrated sequestration.
- Digital twin convergence:Real-time reservoir simulation combined with predictive maintenance analytics reduces unplanned downtime in mature Malaysian and Thai fields.
- Vietnam's Block B gas development:Untapped pre-salt structures and pipeline connectivity to power-hungry southern industrial zones attract first-mover upstream commitments.
Industry Challenges
- Subsea engineering talent scarcity:Deepwater riser design and flow assurance expertise concentrates among aging specialist cohorts in Perth and Kuala Lumpur.
- SKK Migas local content enforcement:Indonesia's production sharing contractor mandates for domestic fabrication and engineering services extend procurement lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Oil and Gas CAPEX Market |
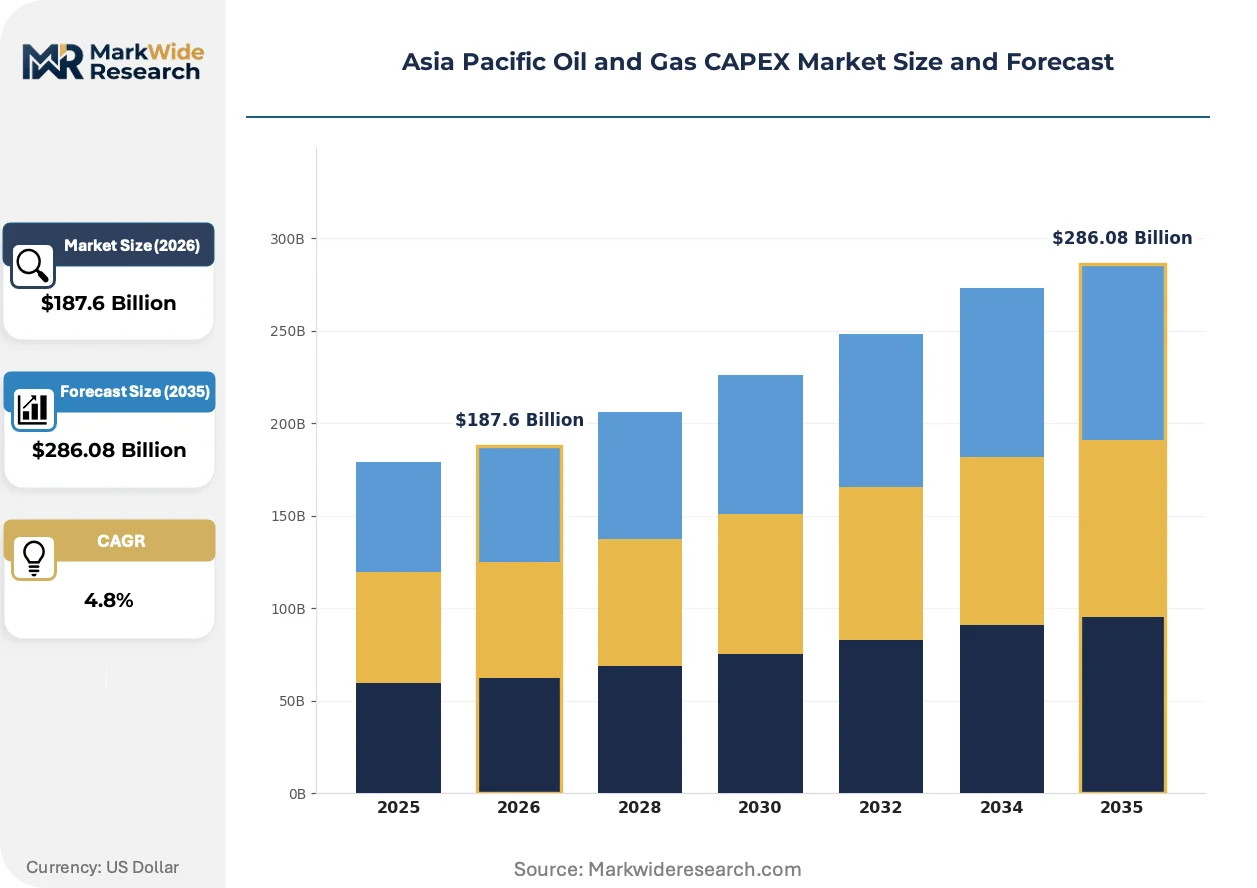
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $286.08 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Upstream, Midstream, Downstream, Service Application: Exploration, Production, Refining, Transportation Technology: Conventional, Unconventional, Renewable, Hybrid End User: Oil Companies, Gas Distributors, Engineering Firms, Others |
| Companies Covered | Petronas, Exxon Mobil Corporation, China National Petroleum Corporation (CNPC), Chevron Corporation, Shell plc, China National Offshore Oil Corporation (CNOOC), Oil and Natural Gas Corporation (ONGC), BP plc, Sinopec, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Oil and Gas CAPEX Market Strategic Shifts
Capital allocation across Asia Pacific upstream portfolios is pivoting from greenfield megaprojects toward modular brownfield extensions and emissions-abated production systems.
Subsea processing technology is decentralizing field development economics by enabling seabed separation and boosting at remote wellheads, eliminating topside platform requirements. Australian and Malaysian operators are deploying these systems at 15-20% faster sanction cycles than conventional platform tiebacks. This compression is reshaping contractor competition around subsea equipment packages rather than integrated EPC awards.
China's MEE methane intensity regulations now mandate quarterly leak detection surveys and flare minimization protocols for all production blocks above 50,000 barrels per day. Conventional operators face retrofit obligations for pneumatic device replacement and vapor recovery unit installation. Sichuan basin tight gas projects are responding with integrated methane monitoring networks that feed real-time emissions data to provincial environmental bureaus.
Long-term offtake contracting is fragmenting as Japanese and Korean utilities shift procurement toward shorter-duration SPAs and spot-indexed cargoes. This compression disrupts the 20-25 year financing structures that underpinned Australian LNG train developments. Queensland and Western Australian projects are responding with tolling arrangements and portfolio marketing structures that decouple upstream equity from liquefaction capacity commitments.
Asia Pacific Oil and Gas CAPEX Market Segmentation
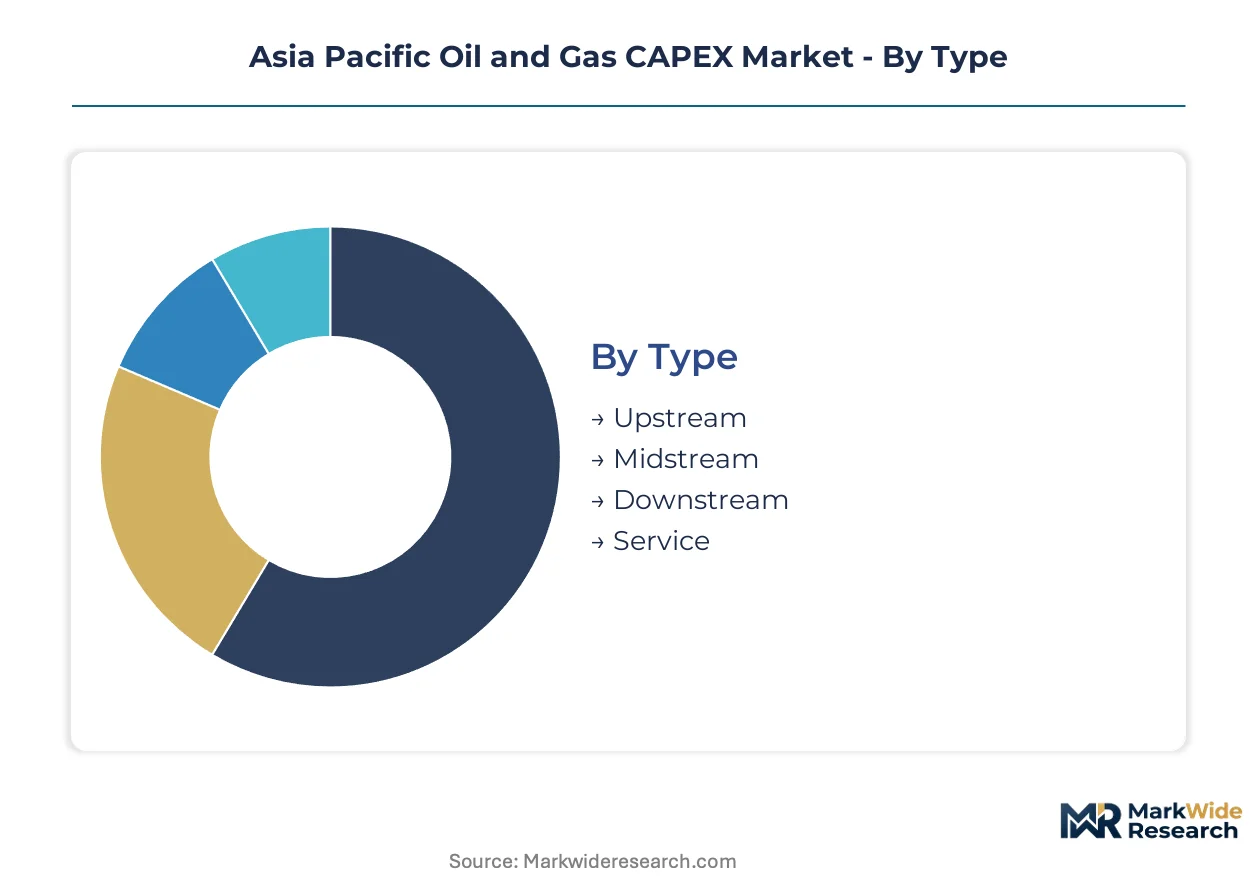
Capital deployment patterns across Asia Pacific oil and gas infrastructure diverge sharply by asset class and operational phase. Segment-specific investment timelines, regulatory exposure, and technology requirements shape contractor selection and project financing structures throughout the region.
Type:
Upstream assets command the dominant technology specification axis, with subsea tieback systems and enhanced recovery platforms defining competitive differentiation.
- Upstream:Exploration drilling, field development, and production facilities absorb the majority of regional CAPEX, driven by deepwater commitments in Indonesia's frontier basins and Australia's northwest shelf. Brownfield extensions in Malaysia's mature fields sustain equipment replacement cycles.
- Midstream:Cross-border pipeline networks and LNG export terminals capture growing allocation as Northeast Asian demand centers require expanded receiving capacity. Subsea manifolds and floating production systems dominate contractor order books.
- Downstream:Refinery upgrades and petrochemical integration projects concentrate in China and India, where electrification pressure is offset by feedstock demand from chemical complexes.
- Service:Contract drilling, maintenance, and specialized engineering support round out capital deployment, with rig fleet renewals accelerating in Australian and Malaysian waters.
Mature deployment sits with Upstream. Newer deployment is concentrated in Midstream.
Application:
Cost tier differentiation separates high-risk frontier exploration from lower-risk production optimization programs.
- Exploration:Seismic acquisition and wildcat drilling in Indonesia's eastern frontier and Australia's deepwater blocks require specialized rigs and extended well test equipment. MEE methane protocols in China's Sichuan basin add environmental compliance layers to tight gas appraisal.
- Production:Sustained field development spending targets Malaysia's deepwater tiebacks and Thailand's mature basin extensions. Digital twin integration is compressing unplanned downtime across these assets.
- Refining:Capacity additions face structural pressure from electrification trends, though integrated petrochemical complexes in China sustain select greenfield commitments.
- Transportation:Pipeline connectivity investments link remote Australian gas fields to coastal liquefaction terminals, while cross-border infrastructure expands across Southeast Asian archipelagos.
Exploration carries the steepest expansion trajectory as frontier basins attract first-mover commitments. Production maintains the largest installed base.
Technology:
Application maturity separates proven extraction methods from emerging low-carbon systems still scaling to commercial viability.
- Conventional:Platform-based offshore development and onshore field extraction remain the workhorse technology across Australian LNG and Malaysian deepwater blocks. Established supply chains and predictable sanction timelines sustain contractor preference.
- Unconventional:Coal seam gas in Queensland and tight gas in China's Sichuan basin require hydraulic fracturing fleets and horizontal drilling programs. Water management and methane containment add cost layers.
- Renewable:Offshore wind-to-hydrogen pilots and solar-powered facility electrification are entering early deployment phases, primarily in Australian and Japanese waters.
- Hybrid:Integrated carbon capture systems and electrified production platforms represent the convergence pathway, with Australia's CCUS Development Fund creating offtake certainty for gas processing retrofits.
Conventional technology anchors current deployment. Hybrid systems are gaining share fastest as dual carbon goals reshape investment criteria.
End User:
Customer type determines procurement scale and contracting duration, from integrated majors to specialized engineering contractors.
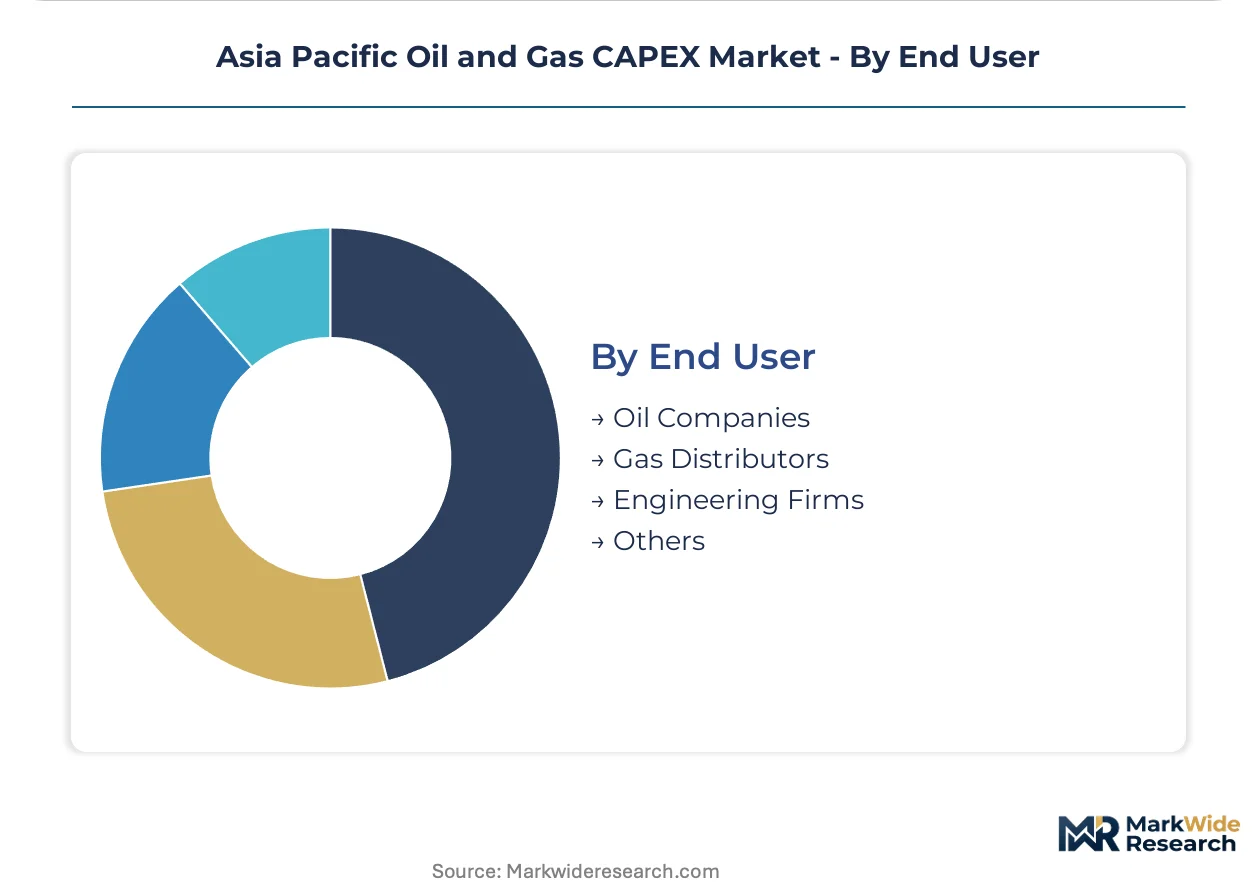
- Oil Companies:National oil companies across China, Malaysia, and Indonesia direct the largest capital commitments, with Petronas and CNOOC anchoring deepwater development portfolios. Their integrated upstream-downstream operations sustain project returns through market cycles.
- Gas Distributors:Japanese power utilities and Korean city gas distributors are shortening offtake contract durations, compressing the financing structures that underpin Australian LNG train expansions.
- Engineering Firms:Subsea equipment specialists and modular fabrication contractors compete for brownfield extension packages, with subsea processing technology decentralizing field development economics.
- Others:Financial investors and infrastructure funds are entering midstream transportation assets through tolling arrangements that decouple equity from liquefaction capacity.
Oil Companies dominate mature deployment. Gas Distributors are driving newer procurement patterns through contract restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal seam gas reserves in Queensland's Surat Basin and deepwater hydrocarbon structures beneath the South China Sea anchor Asia Pacific's upstream investment geography. National oil companies from Kuala Lumpur to Beijing direct capital deployment across these basins.
Australia
Northeast Asian LNG offtake contracts from Japanese utilities and Korean city gas distributors sustain liquefaction train expansions on the northwest shelf. TGA environmental assessments and NOPSEMA safety protocols extend project sanction timelines. Perth-based engineering clusters concentrate subsea riser design expertise for deepwater tieback developments.
China
Tight gas appraisal in the Sichuan basin and ultra-deep drilling in the Tarim basin absorb upstream capital despite dual carbon compression. MEE methane intensity standards mandate quarterly leak detection surveys and flare minimization protocols for blocks above 50,000 barrels per day. Beijing-Tianjin-Hebei industrial corridors host carbon capture integration engineering for gas processing retrofits.
Indonesia
Frontier exploration commitments in eastern frontier blocks and pre-salt structures attract seismic acquisition spending from contractors. SKK Migas production sharing contracts impose local content mandates for domestic fabrication and engineering services. Jakarta-based procurement coordination extends lead times for subsea manifold deliveries.
Malaysia
Deepwater tieback economics across Peninsular Malaysia and Sarawak sustain Petronas-anchored field development portfolios. Integrated upstream-downstream operations capture margin through market cycles. Kuala Lumpur engineering clusters concentrate flow assurance expertise for subsea processing technology deployment.
Vietnam
Untapped pre-salt structures in Block B and pipeline connectivity to southern industrial zones attract first-mover upstream commitments. Cross-border gas infrastructure expansion links remote fields to power-hungry manufacturing corridors. Ho Chi Minh City-based logistics clusters support offshore platform fabrication and marine contracting.
Asia Pacific Oil and Gas CAPEX Market Competitive Environment
Global majors compete with regional champions across integrated portfolio breadth and deepwater execution capability. The vendor base separates into scale-driven integrated operators, national oil companies with captive upstream-downstream control, and specialized subsea engineering contractors. Three archetypes dominate: vertically integrated majors with floating LNG expertise, state-backed champions with basin-specific operational dominance, and modular fabrication specialists competing for brownfield extension packages. Capacity expansion through liquefaction train additions and strategic partnerships for carbon capture integration represent the dominant competitive moves.
Among Asia Pacific-based national champions, Petronas anchors Malaysian deepwater development through integrated block operations. Shell plc occupies a position exemplifying floating LNG technology leadership across Southeast Asian pre-salt and ultra-deepwater contracts. CNOOC represents the state-backed archetype with South China Sea tieback developments that reduce per-barrel extraction economics.
| Leading Market Players |
|---|
| Petronas |
| Exxon Mobil Corporation |
| China National Petroleum Corporation (CNPC) |
| Chevron Corporation |
| Shell plc |
| China National Offshore Oil Corporation (CNOOC) |
| Oil and Natural Gas Corporation (ONGC) |
| BP plc |
| Sinopec |
| Others |
Value Chain & Pricing Dynamics
China's MEE methane intensity standards gate qualified supply access and premium-tier pricing for carbon-abated production systems across Asia Pacific upstream portfolios. Contractors meeting these protocols command contract premiums while non-compliant vendors face exclusion from national oil company procurement rosters.
Pricing Analysis
Project-based long-term offtake contracting dominates, with bundled engineering-procurement-construction warranties separating integrated service packages from unbundled equipment-only supply. Price differentiation rests on certification tier (ISO 14001 environmental management, API Q1 quality standards) and volume scale commitments. Pricing pressure stems from steel and alloy input volatility destabilizing project sanction economics. Exploration contractors exhibit highest price sensitivity due to frontier basin risk profiles, while integrated majors demonstrate lowest sensitivity through captive financing capacity.
Supply Chain Analysis
API certification and MEE environmental compliance qualifications restrict subsea manifold and drilling rig supplier pools to pre-approved vendor lists. Manufacturing concentrates in Singapore, South Korea, and China for subsea processing equipment and specialized alloy components. Raw material dependencies center on nickel-based superalloys, high-strength steel plate, and subsea umbilical thermoplastics. Single-source vulnerability concentrates in deepwater riser design expertise anchored in Perth and Kuala Lumpur engineering clusters. Distribution runs through national oil company procurement coordination centers with SKK Migas, Petronas, and CNOOC gatekeeping contractor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's MEE methane regulations erect barrier-to-entry moats favoring incumbent operators with established environmental management systems.
For Market Incumbents: Lock in subsea engineering talent scarcity through specialized training partnerships with Perth and Kuala Lumpur technical institutes before demographic retirement waves erode capability pools. Secure backward integration into corrosion-resistant alloy supply through long-term offtake agreements with Korean and Japanese steel mills. Defend against modular fabrication specialists by accelerating digital twin deployment across Malaysian and Thai brownfield assets. For New Entrants and Emerging Players: Subsea processing technology convergence offers entry wedge into brownfield extension markets where incumbent integrated EPC contractors face sanction cycle disadvantages. Target Australia's northwest shelf tieback developments where Petronas and Shell plc floating LNG expertise creates subcontractor opportunity gaps. Pursue SKK Migas local content compliance certification to access Indonesia's eastern frontier block procurement channels. For Investors and Strategic Acquirers: First-mover carbon capture integration commitments under Australia's CCUS Development Fund signal leading indicator that emissions-abated production assets will command financing preference over conventional extraction. Long-term viability centers on hybrid technology portfolios spanning upstream gas processing with integrated sequestration. Acquisition focus should target subsea equipment specialists with MEE-certified manufacturing capabilities and established CNOOC or Petronas contractor relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Australia's CCUS Development Fund creates offtake certainty for gas processing retrofits with sequestration. |
| Subsea Processing Deployment | Seabed separation systems compress sanction cycles 15-20% faster than conventional platform tiebacks. |
| Digital Twin Convergence | Real-time reservoir simulation reduces unplanned downtime across mature Malaysian and Thai production fields. |
| Local Content Compliance | SKK Migas domestic fabrication mandates extend procurement lead times for Indonesia frontier block development. |
| Methane Monitoring Networks | Sichuan basin tight gas projects feed real-time emissions data to provincial MEE environmental bureaus. |
Study Parameters
Document review covered SKK Migas production sharing contract terms, NOPSEMA environmental plan assessments, MEE methane intensity protocols, and IEA Asia Pacific energy investment databases, complemented by interviews with upstream project development executives, subsea engineering directors, national oil company procurement managers, and EPC contract specialists. Secondary validation drew from customs trade data, SEC 10-K filings of listed operators, and project sanction announcement tracking. Bottom-up field development cost modeling and top-down regional CAPEX aggregation provided triangulation.
Historical project sanction timelines were cross-referenced against executive panel input on forward commitment intentions. Segmentation modeling spanned asset type, operational phase, technology maturity, and end-user procurement structure across the projection horizon. CAGRs derived from weighted average of disclosed capital guidance and contractor order book trajectories. Forecast inputs incorporated dual carbon policy compression effects and Northeast Asian LNG contracting duration shifts.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to China's dual carbon implementation timeline and unforeseen geopolitical disruptions to South China Sea operations. Forecasts reflect assumptions around sustained Northeast Asian gas demand and stable production sharing contract terms. A model refresh is warranted upon material change in MEE enforcement intensity or Australian carbon pricing mechanism expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market