
 Double Suction Pump Market | 2026-2036
Double Suction Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Double Suction Pump Market Intelligence
EPA efficiency standards for clean water infrastructure is hardening the cost-of-entry calculus for new entrants in the North American double suction pump landscape. Xylem Inc. leverages its vertically integrated manufacturing footprint to sustain pricing discipline across municipal bids. Sulzer Ltd. anchors its position through specialized metallurgy expertise in corrosive fluid handling. Flowserve Corporation competes on aftermarket service density rather than upfront equipment cost.
A double suction pump draws fluid through two opposing inlets into a single volute casing, typically achieving flow rates from 500 to over 100,000 gallons per minute with balanced axial thrust eliminating the need for heavy thrust bearings. Horizontal configurations dominate heavy industrial installations where floor-mounted stability and maintenance access matter most, while submersible variants capture growth in flood-prone water treatment facilities and deep-well extraction. Oil & Gas procurement favors API-compliant horizontal units for pipeline booster duty, whereas municipal water treatment gravitates toward vertical split-case designs for compact station footprints.
ISO 5199 chemical pump standards, API 610 for petroleum applications, and the EU Ecodesign Directive collectively shape product certification requirements and cross-border market access for manufacturers. China's GB standards for pump efficiency and India's BIS certification create additional compliance layers for suppliers targeting Asia-Pacific procurement. Stakeholders must monitor how regional efficiency benchmarks diverge and whether localized testing protocols fragment the addressable market for standardized product platforms.
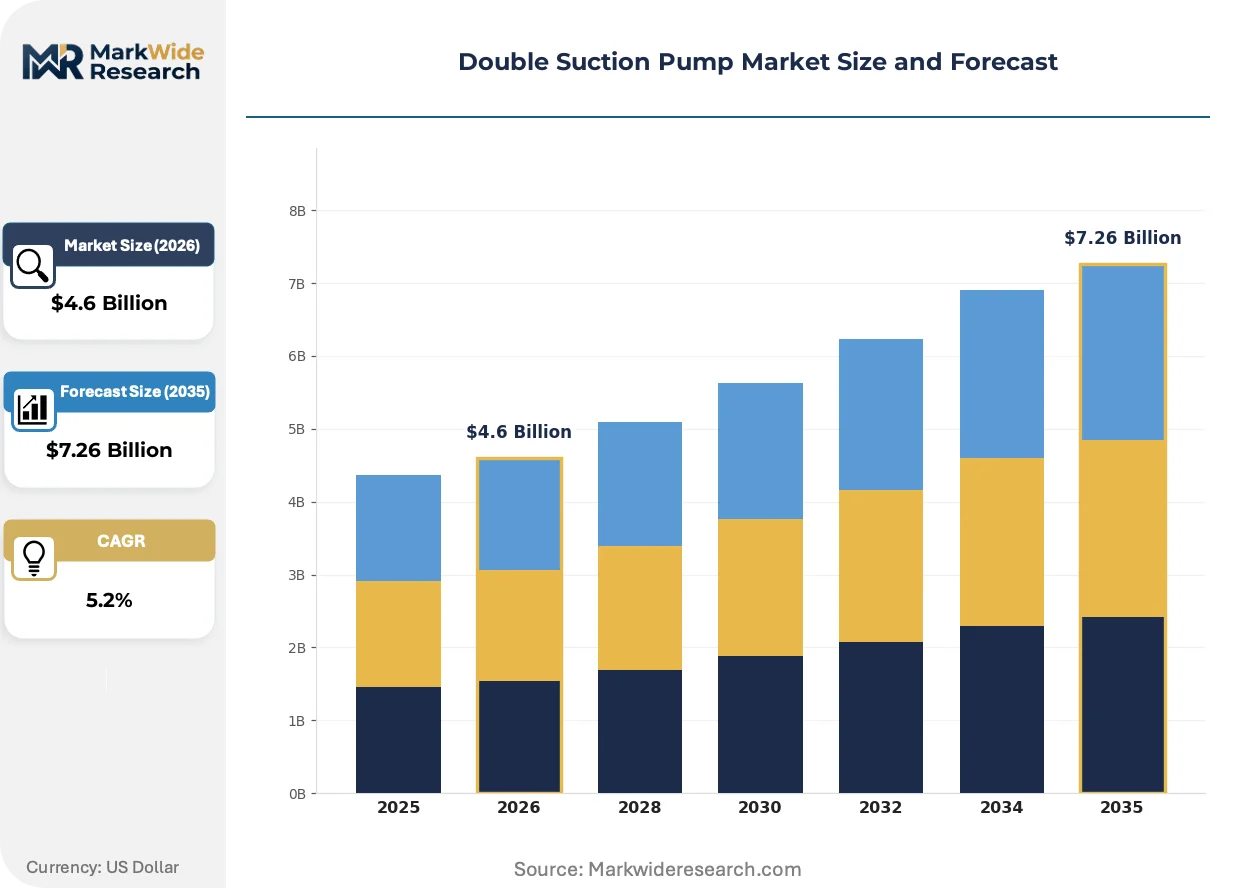
Market Dynamics
The double suction pump market is experiencing fundamental restructuring as municipal water infrastructure upgrades collide with tightening energy efficiency mandates, forcing manufacturers to redesign core hydraulics while maintaining backward compatibility with installed base specifications.
Growth Catalysts
- EPA efficiency standards:The US Environmental Protection Agency's clean water infrastructure rules are accelerating replacement cycles for aging municipal pumping stations, creating immediate equipment refresh demand across state water authorities.
- China's industrial corridor expansion:Thermal power and chemical processing capacity growth in cities along the Yangtze River Delta is driving procurement of high-flow horizontal split-case units for cooling water and process applications.
- EU Ecodesign Directive:Minimum efficiency requirements for water pumps are compelling end-users to specify premium-efficiency models, expanding the addressable market for optimized impeller designs and variable-speed configurations.
Market Restraints
- Specialized casting supply concentration:Foundry capacity for large-diameter duplex stainless steel casings concentrates in Germany and Japan, creating procurement bottlenecks during demand surges.
- API 610 compliance costs:Petroleum sector certification requirements for horizontal pumps impose extensive testing protocols that extend lead times and elevate engineering overhead for mid-size manufacturers.
- Magnetic drive substitution:Sealless pump technology is capturing share in chemical processing applications where emissions containment takes priority over flow rate maximization.
Strategic Opportunities
- India's BIS efficiency certification:New mandatory pump performance labeling is creating first-mover advantage for suppliers with pre-tested product platforms ready for rapid market entry.
- Digital twin integration:Convergence of computational fluid dynamics with IoT sensor networks enables predictive maintenance offerings that transform equipment vendors into service partners.
- Flood-resilient water treatment:Submersible double suction configurations are penetrating municipal installations in coastal cities facing sea-level rise adaptation requirements.
Industry Challenges
- Turbomachinery engineering talent scarcity:Experienced hydraulic designers capable of optimizing double-volute geometries are retiring faster than universities produce replacements, compressing R&D throughput.
- Multi-standard certification complexity:Simultaneous pursuit of ISO 5199, API 610, and EU Ecodesign compliance requires parallel testing programs that strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Suction Pump Market |
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Submersible, Multistage Industry Vertical: Oil & Gas, Water Treatment, Power Generation, Chemical Processing End User: Manufacturing, Municipalities, Agriculture, Mining Application: Irrigation, Firefighting, Industrial Processes, HVAC |
| Companies Covered | Xylem Inc., Sulzer Ltd., Flowserve Corporation, ITT Inc., KSB SE & Co. KGaA, Torishima Pump Mfg. Co. Ltd., Hunan Credo Pump Co. Ltd., Goulds Pumps, Buffalo Pumps Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Suction Pump Market Strategic Shifts & Innovations
Computational fluid dynamics and additive manufacturing are converging to reshape impeller design methodologies, while regulatory pressure on lifecycle energy consumption is elevating total cost of ownership over upfront capital expenditure in buyer evaluations.
Additive manufacturing is integrating conformal cooling channels into impeller cores that were previously impossible to machine, enabling municipal water utilities in the Netherlands and Singapore to specify pumps with 8-12% hydraulic efficiency gains over conventional cast designs. Equipment manufacturers with captive metal printing capability are compressing prototype-to-production cycles from months to weeks.
The EU Ecodesign Directive's extended product scope now captures pumps above 150 kW, forcing oil and gas terminal operators across Rotterdam, Antwerp, and Hamburg to pre-emptively upgrade pipeline booster stations before mandatory compliance deadlines. This regulatory compression is accelerating the retirement of fixed-speed installations in favor of variable-frequency drive packages.
Buyers are unbundling aftermarket service contracts from initial equipment procurement, with Dutch and German water utilities now separately tendering 10-year maintenance agreements after competitive equipment awards. This disintermediation is pressuring traditional full-service vendors to defend margin through spare parts exclusivity rather than bundled pricing.
Double Suction Pump Market Segmentation
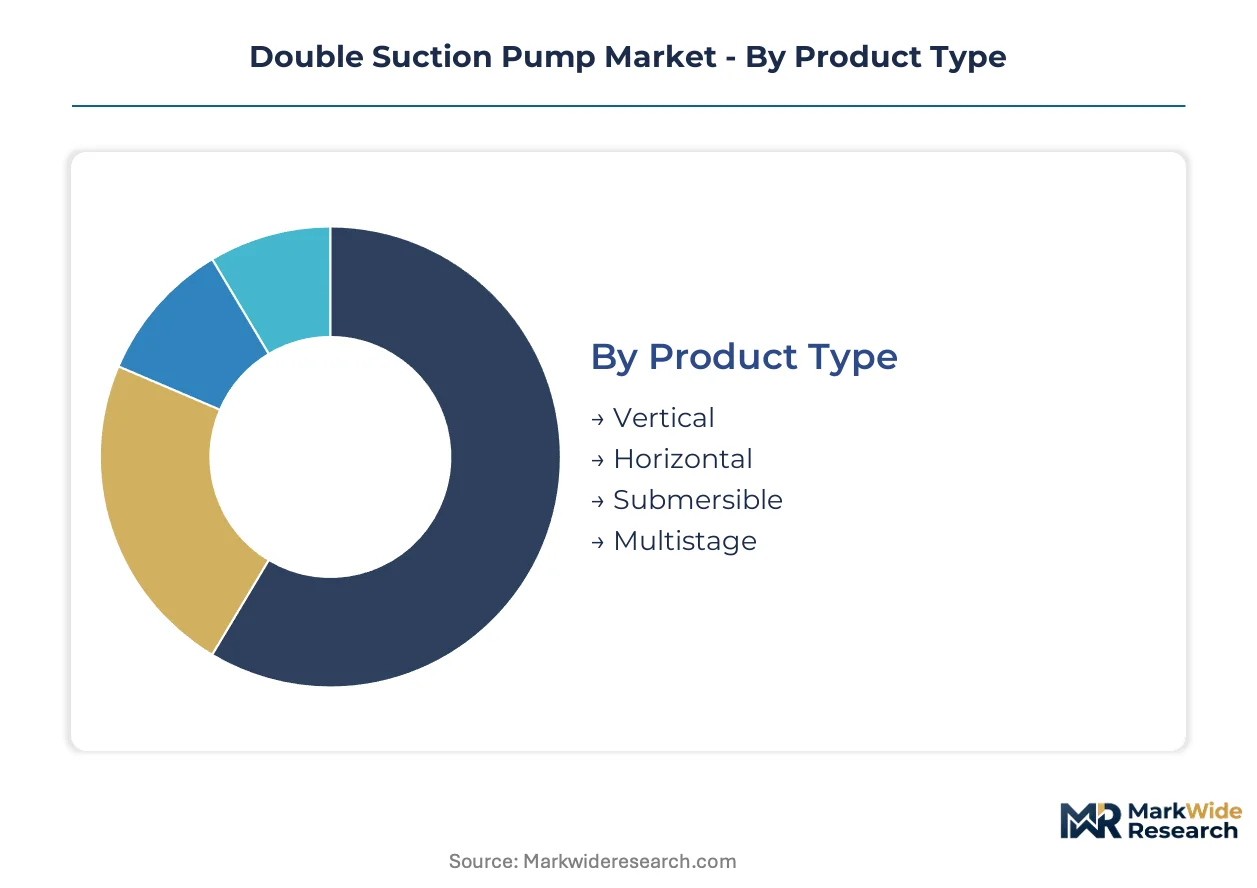
Double suction pump procurement patterns diverge sharply across installation geometry, regulatory environment, and duty cycle requirements. Specification engineers weight hydraulic efficiency against footprint constraints differently in municipal water stations versus offshore oil terminals. Understanding these segment boundaries clarifies where manufacturers must maintain dual certification portfolios versus single-standard specialization.
Product Type:
Impeller orientation and mounting configuration dictate maintenance accessibility, axial thrust balance, and station civil works requirements.
- Horizontal:Floor-mounted split-case designs dominate heavy industrial installations where bearing accessibility and volute inspection drive lifecycle economics. API 610 procurement specifications across Rotterdam, Houston, and Singapore terminals mandate this configuration for pipeline booster duty above 75 kW.
- Vertical:Space-constrained water treatment facilities in Dutch and German municipalities specify vertical turbine arrangements to minimize station footprint. Compact motor mounting above the volute eliminates underground pump pits in flood-prone coastal installations.
- Submersible:Motor-integrated wet-pit designs penetrate deep-well extraction and stormwater management applications where dry-pump accessibility is impractical.
- Multistage:Stacked impeller configurations address high-head, moderate-flow requirements in boiler feed and pressure-boosting circuits.
Mature deployment sits with horizontal configurations across established petroleum infrastructure. Newer deployment is concentrated in submersible variants for climate-adaptation water projects.
Industry Vertical:
Fluid characteristics and regulatory exposure separate capital-intensive process industries from public infrastructure procurement.
- Water Treatment:Municipal and industrial effluent handling drives the largest equipment volumes. EPA clean water infrastructure rules across US state authorities are accelerating replacement cycles for aging split-case stations.
- Oil & Gas:Pipeline transmission and terminal loading specify API-compliant metallurgy for sour service and high-pressure hydrocarbon duty.
- Power Generation:Thermal plant cooling water circuits require high-flow, low-head designs with corrosion-resistant coatings for continuous operation.
- Chemical Processing:ISO 5199 compliance for aggressive fluids competes against magnetic drive substitution in emissions-critical applications.
Procurement sophistication clusters in oil and gas vertical specifications. Fastest volume expansion is occurring in water treatment verticals driven by infrastructure refresh mandates.
End User:
Capital availability and technical staffing depth determine whether buyers prioritize upfront equipment cost or lifecycle service contracts.
- Municipalities:Public water authorities in Netherlands and Singapore tender separately for equipment and 10-year maintenance, disintermediating traditional full-service vendors. Bidding transparency favors pre-tested efficiency platforms.
- Manufacturing:Process industries balance production continuity against energy cost exposure, driving variable-frequency drive adoption in new installations.
- Agriculture:Irrigation districts prioritize capital efficiency over hydraulic optimization, accepting lower efficiency ratings for reduced first cost.
- Mining:Remote site operations demand ruggedized designs with extended mean time between overhauls where technical support infrastructure is sparse.
Service bundling persists most strongly in manufacturing end-user procurement. Unbundled equipment-only purchasing is expanding fastest in municipal tendering.
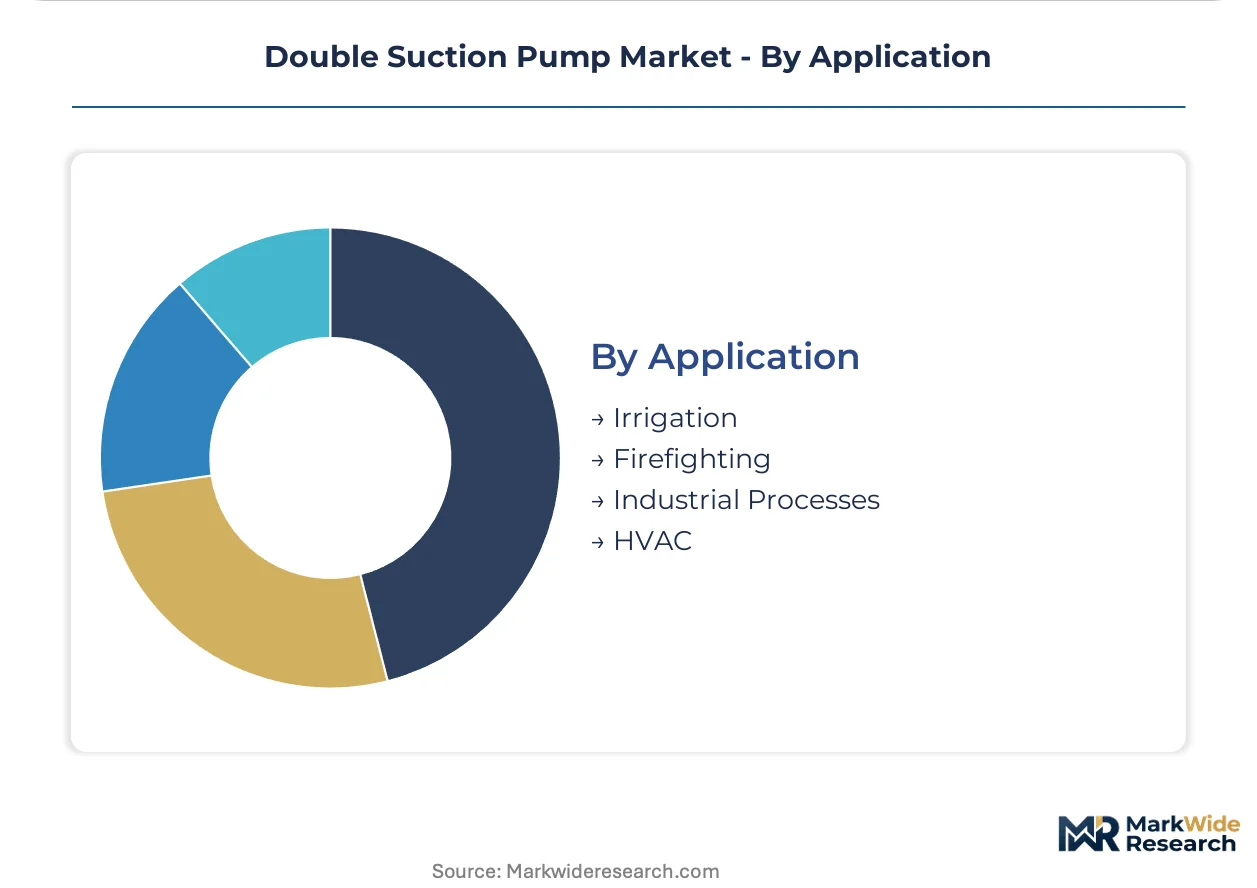
Application:
Duty cycle intermittency and consequence of failure define specification stringency across operating scenarios.
- Industrial Processes:Continuous-duty cooling water and process circulation specify premium efficiency tiers with redundant standby configurations. EU Ecodesign Directive compliance above 150 kW is forcing pre-emptive upgrades in Rotterdam and Hamburg terminals.
- HVAC:Building services applications prioritize acoustic performance and part-load efficiency over peak hydraulic performance.
- Irrigation:Seasonal operation accepts lower efficiency ratings where utilization hours fail to justify premium impeller investment.
- Firefighting:Standby-duty specifications emphasize reliability verification and rapid start capability over operating efficiency metrics.
Specification intensity concentrates in industrial process applications with continuous duty cycles. Steepest efficiency upgrade pressure is appearing in HVAC applications as building energy codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate double suction pump procurement for thermal power and chemical processing infrastructure. State-backed water treatment modernization across multiple jurisdictions is reshaping equipment demand patterns. Municipal efficiency mandates in coastal cities are accelerating submersible configuration adoption.
United States
EPA clean water infrastructure rules are accelerating replacement cycles for aging municipal pumping stations. State water authorities in California and Texas are tendering high-capacity split-case units for distribution network upgrades. Houston's petrochemical corridor specifies API-compliant horizontal pumps for pipeline booster duty.
China
GB standards for pump efficiency are tightening procurement specifications across industrial corridor cities. MIIT enforcement of dual carbon goals is forcing thermal power operators to pre-emptively upgrade cooling water circuits. Shanghai and Ningbo port terminals are expanding high-flow horizontal split-case installations for seawater intake systems.
Germany
EU Ecodesign Directive minimum efficiency requirements are compelling municipal utilities to specify premium-efficiency models. REACH compliance costs for specialized metallurgy are elevating engineering overhead for corrosion-resistant designs. Ruhr industrial basin water treatment facilities are standardizing vertical split-case configurations for compact station footprints.
India
BIS mandatory pump performance labeling is creating first-mover advantage for pre-tested product platforms. CEA guidelines for thermal power plant efficiency are driving cooling water pump upgrades across state electricity boards. Gujarat and Maharashtra industrial zones are procuring high-capacity units for chemical processing and desalination infrastructure.
Netherlands
Rotterdam and Amsterdam water utilities are unbundling aftermarket service contracts from initial equipment procurement. Dutch flood-resilience programs are penetrating submersible double suction configurations for coastal adaptation requirements. Randstad municipal tenders favor pre-tested efficiency platforms with transparent bidding structures.
Double Suction Pump Market Key Industry Players
German and Swiss producers anchor one tier; Japanese and Chinese specialists hold adjacent positions in corrosion-resistant and cost-optimized segments respectively. The vendor base stratifies across full-service multinationals with captive foundry capacity, mid-size regional fabricators with ISO certification depth, and emerging Asian manufacturers competing on lead-time compression. Strategic differentiation concentrates on aftermarket service density, metallurgy expertise, and digital twin integration. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers seek to secure large-diameter duplex stainless steel casting supply.
Among diversified industrial technology groups, Xylem Inc. and Sulzer Ltd. exemplify the vertically integrated archetype with in-house control over precision casting and global service networks. Flowserve Corporation occupies a position emphasizing aftermarket service partnerships over upfront equipment positioning. KSB SE & Co. KGaA represents the European engineering heritage tier with deep certification portfolios spanning API, ISO, and EU Ecodesign requirements. Chinese specialists including Hunan Credo Pump Co. Ltd. anchor the cost-optimized segment with rapid prototyping capability and domestic GB standard compliance.
| Leading Market Players |
|---|
| Xylem Inc. |
| Sulzer Ltd. |
| Flowserve Corporation |
| ITT Inc. |
| KSB SE & Co. KGaA |
| Torishima Pump Mfg. Co. Ltd. |
| Hunan Credo Pump Co. Ltd. |
| Goulds Pumps |
| Buffalo Pumps Inc. |
| Others |
Cost & Logistics Intelligence
Additive manufacturing adoption in impeller production is compressing prototype cycles and redrawing cost curves while simultaneously concentrating advanced production capability among manufacturers with captive metal printing capacity in Germany and Japan. This technological shift tightens supply-side control over premium-efficiency designs and amplifies pricing power for certified producers against conventional foundry-dependent competitors.
Pricing Analysis
Lead-time premiums dominate transaction economics, with spot inventory from distributors commanding discounts against engineered-to-order units with extended delivery schedules. Three-tier pricing structure across premium, standard, and economy levels separates API-certified horizontal split-case pumps from municipal-grade vertical configurations and basic irrigation-duty units. Cost compression in the economy tier is intensifying because Chinese manufacturers are compressing margins through rapid GB-standard prototyping. Agricultural irrigation districts exhibit highest price sensitivity, while Rotterdam and Singapore municipal utilities prioritize lifecycle efficiency over first cost.
Supply Chain Analysis
Single-source vulnerability sits with large-diameter duplex stainless steel casting capacity concentrated in Germany, Japan, and select Chinese foundries serving the Yangtze River Delta. Raw material dependencies center on nickel-alloy feedstock, specialized sand binders for precision casting, and rare-earth elements for high-efficiency motor integration. Tariff exposure on European-sourced specialty metallurgy creates procurement risk for North American OEMs assembling API-compliant units. Distribution runs through authorized service networks for aftermarket parts, with direct-to-utility contracting dominating new equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with foundry ownership and captive additive manufacturing capability determining who captures margin in premium-efficiency segments. Control over large-diameter duplex stainless steel supply represents the decisive upstream lever.
For Market Incumbents: Deepen backward integration into specialty foundry capacity or secure exclusive offtake agreements with German and Japanese casting houses before demand surges tighten supply further. Magnetic drive substitution in chemical processing threatens double suction share in corrosive applications, requiring defensive certification investment in ISO 5199 compliance depth. Prioritize digital twin integration to transform equipment sales into decade-long service partnerships that lock out competitors. For New Entrants and Emerging Players: Launch via unbundled equipment-only tendering to Dutch and Singapore municipal utilities that have separated maintenance contracts from initial procurement. India's BIS mandatory pump performance labeling creates immediate white-space opportunity for pre-tested product platforms ready for rapid market entry. Target flood-resilient submersible configurations in coastal adaptation projects where incumbents lack specialized wet-pit design expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial technology groups seeking hydraulics capability, with IPO viability limited by foundry capital intensity. Mid-size regional fabricators with ISO 5199 and API 610 certification depth represent the most defensible acquisition targets against margin compression. Watch for inflection when EU Ecodesign Directive enforcement above 150 kW triggers pre-emptive replacement cycles across Rotterdam, Antwerp, and Hamburg terminal operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive supply of duplex stainless steel castings insulates margin from German and Japanese supply bottlenecks. |
| Digital Twin Platform Development | Predictive maintenance offerings transform Xylem and Sulzer from vendors into decade-long utility partners. |
| BIS Pre-Certification Investment | First-mover positioning in India's mandatory pump performance labeling captures state electricity board procurement. |
| Submersible Configuration Expansion | Flood-resilient designs penetrate Dutch coastal adaptation programs where dry-pump stations face obsolescence. |
| API 610 Compliance Depth | Petroleum sector certification barriers protect premium pricing in Houston and Singapore pipeline booster markets. |
Research Approach
Multi-period observation of municipal tender awards, foundry capacity utilization, and efficiency regulation enforcement anchored the trend analysis, supplemented by interviews with plant engineers at thermal power operators, procurement leads at Dutch water utilities, aftermarket service heads at major OEMs, and hydraulic designers at specialized engineering consultancies. Secondary validation drew from EPA clean water infrastructure filings, EU Ecodesign Directive implementation reports, China MIIT dual carbon policy documents, and India BIS pump performance labeling guidelines. Bottom-up equipment procurement tracking triangulated against top-down market sizing across the analysis window.
Segment-weighting applied product type, industry vertical, end-user category, and regional regulatory cluster as primary dimensions across the modeling period. CAGRs derived from installed base replacement cycles, infrastructure investment pipelines, and efficiency mandate compliance deadlines. Industry-specific inputs included cooling water demand from China's thermal power expansion and submersible adoption rates in Dutch flood-resilience programs.
The model assumes a particular technology adoption path for additive manufacturing in impeller production; alternative pathways with slower metal printing penetration would preserve conventional foundry economics and alter competitive positioning. Forecasts reflect assumptions regarding EPA enforcement continuity, EU Ecodesign Directive scope expansion, and China MIIT dual carbon goal adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Double Diaphragm Pump Market