
 Asia-Pacific Cryogenic Pump Market | 2026-2036
Asia-Pacific Cryogenic Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cryogenic Pump Market Outlook
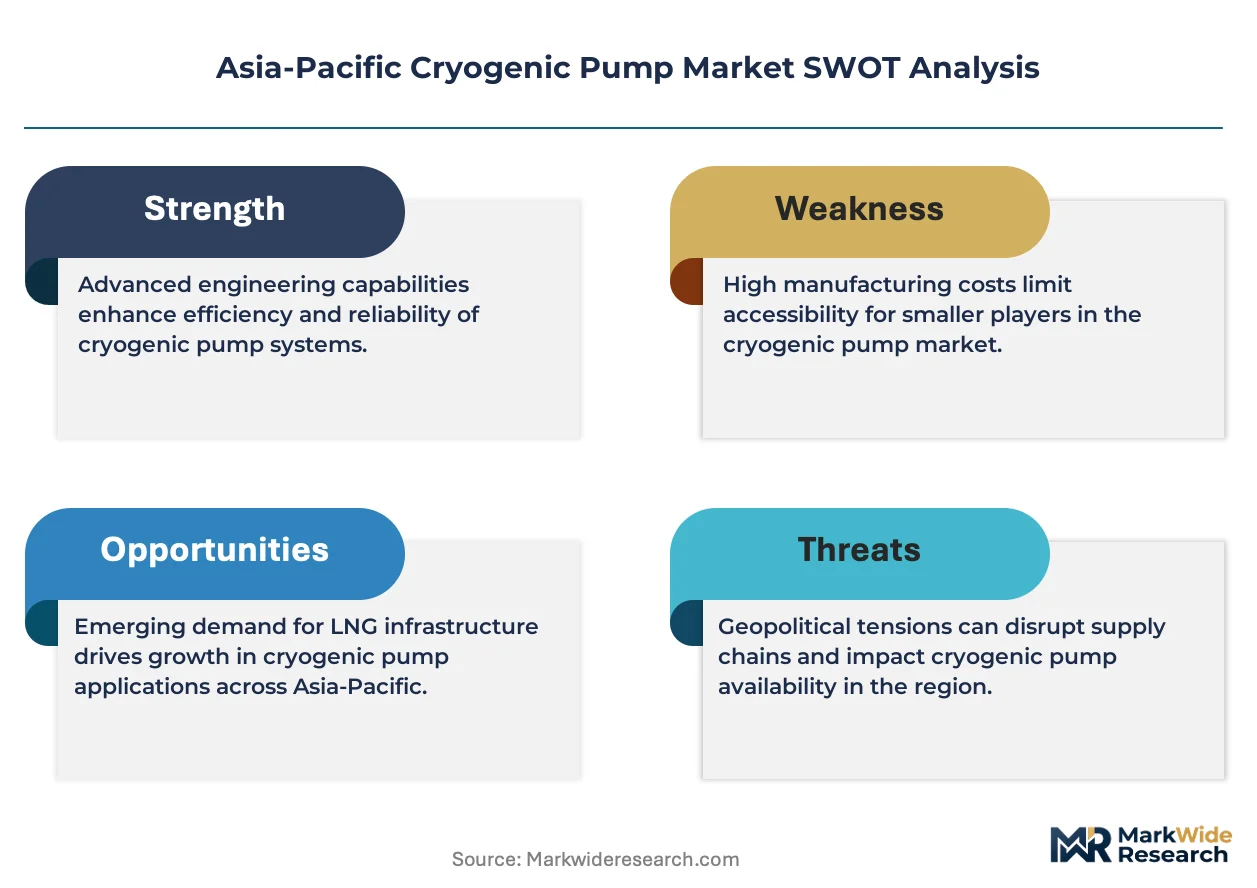
Asset-light leasing and project finance arrangements for LNG terminal infrastructure is fragmenting the competitive landscape for cryogenic pump procurement. Ebara Corporation leverages its domestic manufacturing footprint in Japan to anchor long-term service contracts with regional gas utilities. Flowserve Corporation competes through specialized centrifugal designs for sub-zero hydrocarbon transfer. Beijing Long March Tianmin Hi-Tech Co Ltd dominates indigenous supply to China's expanding LNG receiving terminals.
Asia-Pacific cryogenic pumps are hermetically sealed mechanical devices engineered to transport liquefied gases below minus 150 degrees Celsius, utilizing specialized seal geometries and vacuum-jacketed housings to prevent thermal leakage. These units serve critical functions in LNG regasification, liquid hydrogen distribution, and industrial gas separation processes where maintaining cryogenic temperatures prevents vaporization losses. Submersible pumps lead product type demand due to their immersion-compatible design for LNG storage tanks, while positive displacement pumps capture specialized applications in aerospace propellant loading where precise flow control matters. Centrifugal pumps sustain the broadest end-user footprint across oil and gas and chemical processing installations. Stationary installations anchor the market by value, though portable units are gaining traction in modular LNG and hydrogen fueling deployments.
China's SAMR enforces GB standards for pressure equipment safety that directly shape cryogenic pump certification requirements for domestic deployment. Japan's METI and South Korea's MFDS coordinate hydrogen equipment codes that dictate material specifications and testing protocols for sub-zero service. Australia's TGA and national pressure equipment safety frameworks impose additional compliance layers for offshore LNG and industrial gas projects. Stakeholders must monitor how diverging national hydrogen infrastructure codes will reshape interoperability requirements and supplier qualification pathways across the region.
Market Dynamics
LNG receiving terminal buildouts across coastal China, Japan, and South Korea are compressing procurement cycles and forcing pump suppliers to absorb longer warranty obligations tied to project finance structures.
Growth Catalysts
- Japan's METI hydrogen roadmap:The national framework mandates liquid hydrogen distribution infrastructure by 2040, directly pulling demand for submersible cryogenic pumps in Osaka-Kobe industrial corridors.
- China's dual carbon goals:SAMR-enforced GB standards for pressure equipment safety are accelerating replacement cycles for aging LNG terminal pumps in Yangtze River Delta petrochemical clusters.
- Submersible pump immersion compatibility:This design architecture eliminates vaporization losses in full-containment LNG storage tanks, making it the default specification for newbuild terminals.
Market Restraints
- Nickel-based superalloy supply concentration:Vacuum-jacketed housing fabrication depends on specialty steel mills concentrated in Japan and Germany, exposing procurement to input cost volatility and lead time extension.
- Australia's TGA pressure equipment codes:Offshore LNG projects face additional compliance layers that extend qualification timelines for cryogenic pump suppliers by six to twelve months.
- Positive displacement pump substitution:Aerospace propellant loading applications are migrating toward centrifugal alternatives where flow precision requirements permit, compressing addressable market for reciprocating designs.
Strategic Opportunities
- Modular hydrogen fueling deployments:Portable cryogenic pump units are capturing traction in South Korea's coastal hydrogen bunkering stations where fixed infrastructure economics fail.
- China's indigenous certification pathway:Beijing's SAMR is streamlining domestic type-approval for cryogenic fluid handling equipment, creating preferential access for local suppliers in LNG terminal expansions.
- Digital twin integration with predictive maintenance:Convergence of IoT sensor arrays and vacuum-jacketed housing diagnostics is enabling outcome-based service contracts that unbundle hardware from lifecycle support.
Industry Challenges
- Cryogenic seal geometry engineering talent:The specialized skill set for hermetic sealing design below minus 150 degrees Celsius concentrates in Japan's Osaka-Kobe corridor and Germany, creating recruitment bottlenecks for expanding Chinese manufacturers.
- Legacy SCADA integration complexity:New-generation variable-speed cryogenic pumps face protocol mismatches with existing terminal automation systems in Japan's established LNG infrastructure, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cryogenic Pump Market |
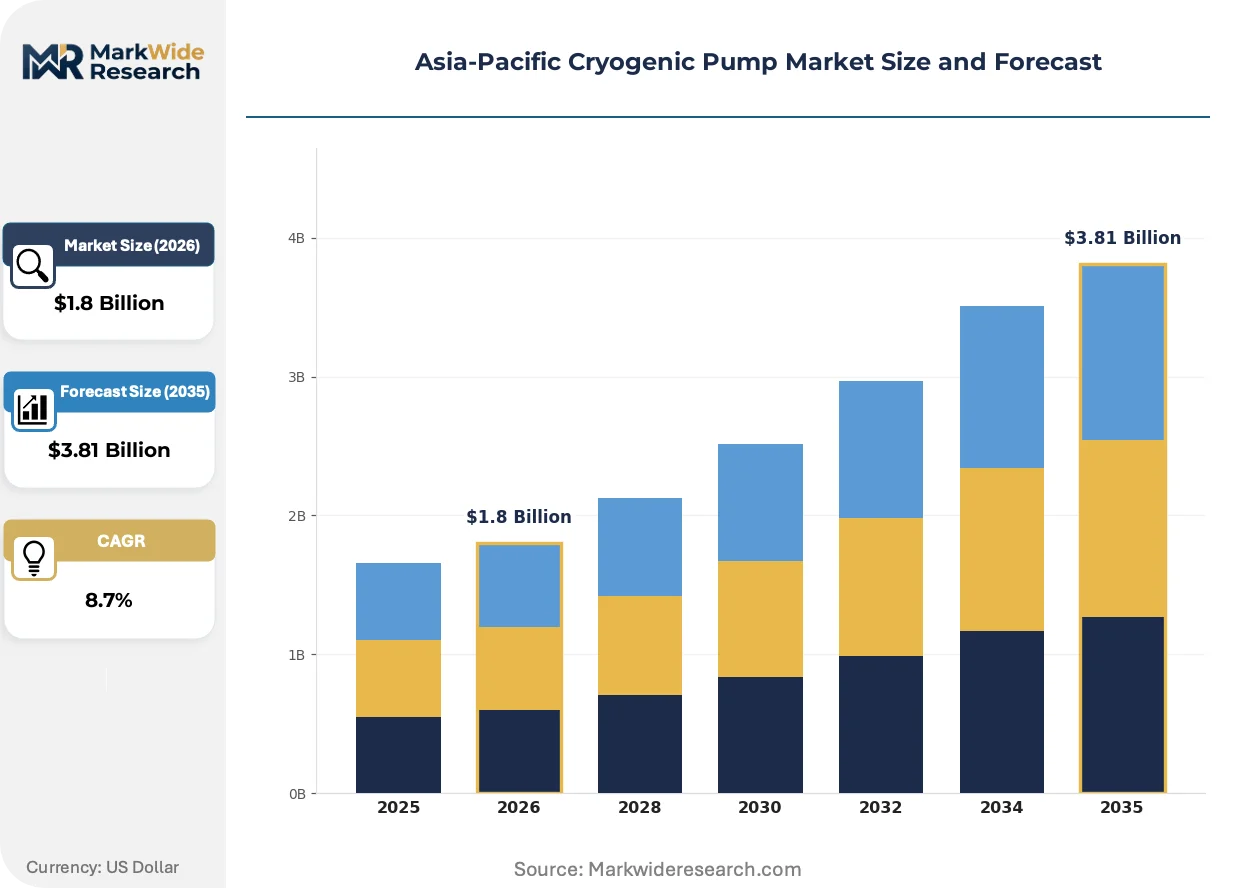
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Positive Displacement Pumps, Reciprocating Pumps End User: Industrial, Aerospace, Oil & Gas, Chemical Processing Installation: Onshore, Offshore, Stationary, Portable Service Type: Installation Services, Maintenance Services, Repair Services, Consulting Services |
| Companies Covered | Fives Group, Flowserve Corporation, Ebara Corporation, Weir Group PLC, Beijing Long March Tianmin Hi-Tech Co Ltd, Nikkiso Co Ltd, KSB SE & Co KGaA, Cryostar SAS, SHI Cryogenics Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cryogenic Pump Market Strategic Shifts
Active magnet bearing technology and vacuum insulation advances are compressing maintenance intervals and enabling predictive service models that restructure supplier-customer relationships across LNG and hydrogen value chains.
Magnetically levitated cryogenic pumps eliminate mechanical seal wear and extend mean time between overhaul by operating without fluid lubrication contact. Japanese LNG terminal operators in Chubu and Kansai regions are piloting these units for base-load regasification duty. This architecture is hybridizing maintenance economics by collapsing the traditional separation between capital equipment procurement and long-term service agreements.
China's SAMR is tightening GB 150 pressure vessel standards to incorporate hydrogen embrittlement testing protocols for sub-zero service materials. The industrial consequence forces pump manufacturers to requalify existing nickel-alloy casting suppliers or vertically integrate into specialty metallurgy. LNG receiving terminal projects in Fujian and Guangdong provinces are experiencing six-month certification delays as fabricators adapt welding procedures.
Terminal operators are unbundling aftermarket service from original equipment procurement, soliciting third-party maintenance providers for vacuum-jacketed housing refurbishment. This behavior shift disrupts the traditional captive service model anchored by Japanese manufacturers. South Korea's KOGAS and Chinese provincial gas distributors are most visible in this transition, running parallel procurement tracks for hardware and fifteen-year maintenance contracts.
Asia-Pacific Cryogenic Pump Market Segmentation
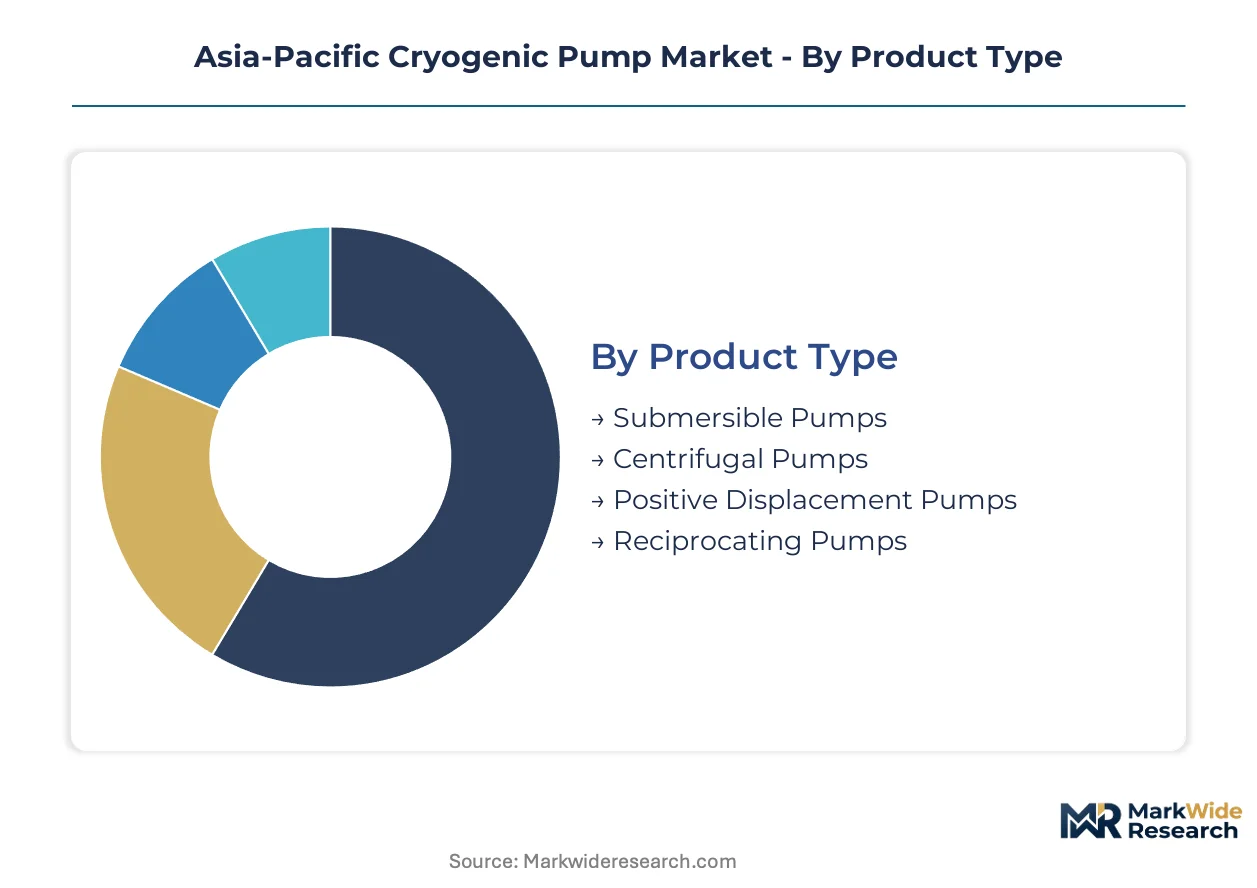
Cryogenic pump procurement in Asia-Pacific fragments across four structural dimensions that determine warranty obligations, service revenue capture, and supplier qualification pathways. Each category reshapes how Ebara, Flowserve, and Beijing Long March Tianmin structure their regional commercial strategies.
Product Type:
After-sales-service intensity varies sharply by pump architecture, with submersible units demanding immersive maintenance protocols and centrifugal designs requiring precision balancing over decade-long lifecycles.
- Submersible Pumps:These immersion-compatible units eliminate vaporization losses in full-containment LNG storage tanks through hermetic seal geometries and vacuum-jacketed housings. Demand concentrates in China's Yangtze River Delta petrochemical clusters where newbuild LNG terminals specify submersible architecture as default. Japan's Osaka-Kobe industrial corridor pulls specialized variants for liquid hydrogen distribution under METI's roadmap.
- Centrifugal Pumps:Specialized designs for sub-zero hydrocarbon transfer sustain the broadest end-user footprint across oil and gas installations. South Korea's KOGAS and Chinese provincial gas distributors compress procurement cycles for these units, forcing suppliers to absorb extended warranty obligations tied to project finance structures.
- Positive Displacement Pumps:Aerospace propellant loading applications in Japan's space facilities utilize these for precise flow control where centrifugal alternatives fail.
- Reciprocating Pumps:Niche deployment in high-pressure hydrogen fueling stations across South Korea's coastal bunkering infrastructure.
By volume, centrifugal pumps lead. By growth pace, submersible pumps are ahead.
End User:
Cost tier differentiation separates capital-intensive LNG terminal operators from research-driven aerospace procurement with diverging technical specifications and contract structures.
- Oil & Gas:LNG regasification terminals across coastal China, Japan, and South Korea anchor absolute demand volume. These facilities specify pumps for minus 150 degrees Celsius service with fifteen-year maintenance contracts unbundled from hardware procurement.
- Industrial:Liquid hydrogen distribution networks and industrial gas separation processes in Japan's Chubu and Kansai regions deploy magnetically levitated units for base-load duty.
- Chemical Processing:China's Fujian and Guangdong provinces experience certification delays as fabricators adapt welding procedures to tightened GB 150 standards.
- Aerospace:Propellant loading applications in Japan's space facilities migrate toward centrifugal alternatives where flow precision requirements permit.
Oil and gas commands the largest capital deployment. Aerospace presents the steepest expansion trajectory as hydrogen infrastructure scales.
Installation:
Customer type segmentation separates integrated terminal operators from modular deployment specialists with contrasting procurement authority and lifecycle management approaches.
- Stationary:Permanent installations anchor market value through LNG receiving terminals and industrial gas facilities. Australia's TGA pressure equipment codes extend qualification timelines for offshore suppliers by six to twelve months.
- Portable:Modular units capture traction in South Korea's coastal hydrogen bunkering stations where fixed infrastructure economics fail.
- Onshore:China's expanding LNG receiving terminals in Fujian and Guangdong drive indigenous certification pathway development through SAMR.
- Offshore:Australia's offshore LNG projects face additional compliance layers that fragment supplier qualification pathways.
Stationary installations dominate current revenue. Portable configurations are expanding most quickly in hydrogen fueling applications.
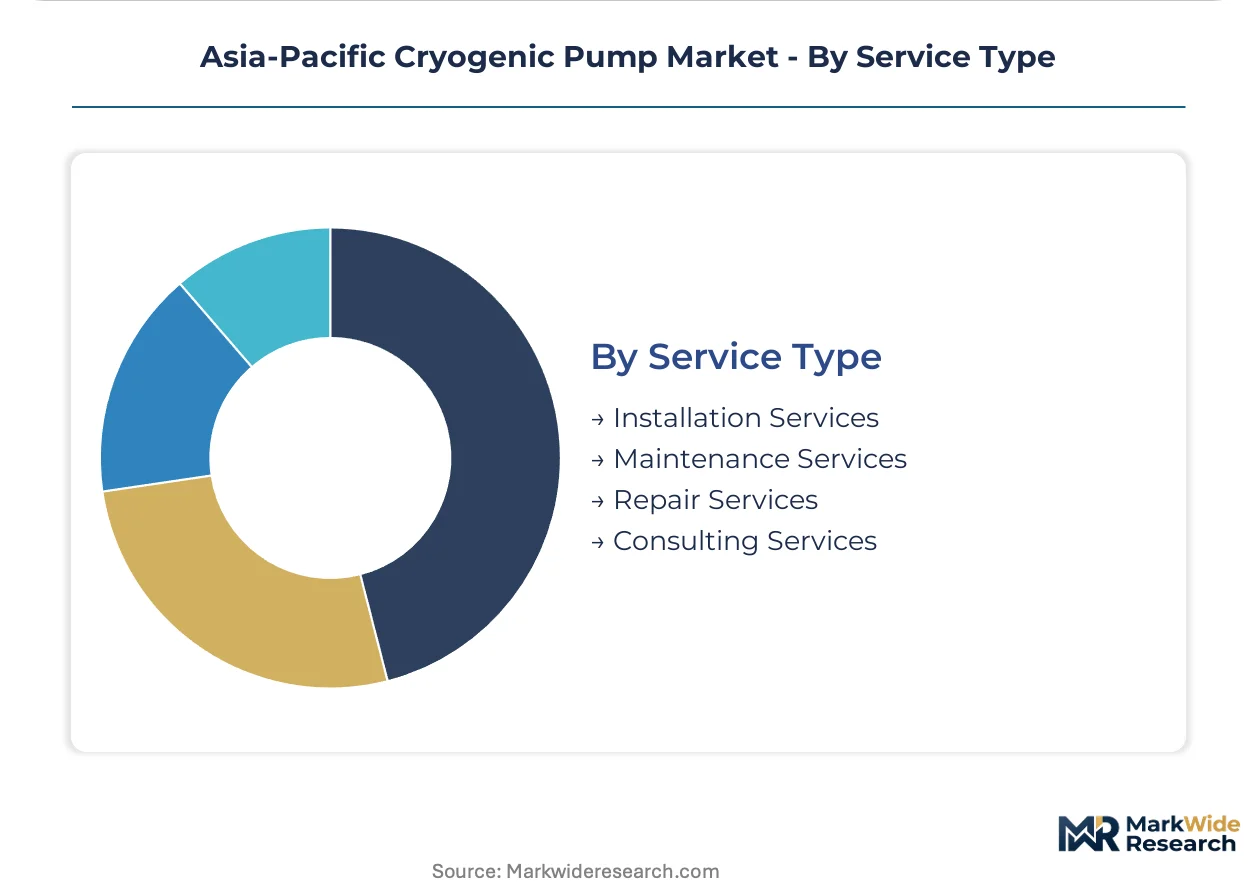
Service Type:
Supply concentration for specialized engineering talent concentrates maintenance and repair revenue in Japan's Osaka-Kobe corridor and Germany, creating geographic bottlenecks for Chinese manufacturers.
- Maintenance Services:Terminal operators unbundle aftermarket service from original equipment procurement, soliciting third-party providers for vacuum-jacketed housing refurbishment. This behavior shift disrupts the traditional captive service model anchored by Japanese manufacturers.
- Installation Services:LNG terminal buildouts compress procurement cycles and force pump suppliers to absorb longer warranty obligations tied to project finance structures across China, Japan, and South Korea.
- Repair Services:Digital twin integration with predictive maintenance enables outcome-based contracts that restructure supplier-customer relationships.
- Consulting Services:Protocol mismatch remediation for legacy SCADA integration in Japan's established LNG infrastructure forces costly middleware development.
Maintenance services generate the highest recurring revenue. Installation services are climbing the fastest as terminal buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI hydrogen roadmap and China's dual carbon goals are redirecting procurement priorities across the region. SAMR-enforced GB standards and South Korea's MFDS hydrogen equipment codes are tightening certification requirements. Industrial clusters in coastal provinces and metropolitan corridors concentrate deployment activity.
China
Yangtze River Delta petrochemical clusters anchor demand for high-capacity centrifugal units in LNG receiving terminals. SAMR's GB 150 pressure vessel standards are forcing six-month certification delays as fabricators adapt welding procedures. Fujian and Guangdong provinces drive indigenous certification pathway development through streamlined domestic type-approval.
Japan
Osaka-Kobe industrial corridors pull specialized submersible variants for liquid hydrogen distribution under METI's 2040 infrastructure mandate. JIS standards coordinate with METI codes to dictate material specifications for sub-zero service. Chubu and Kansai region LNG terminal operators pilot magnetically levitated units for base-load regasification duty.
South Korea
KOGAS and provincial gas distributors compress procurement cycles for centrifugal pumps with extended warranty obligations. MFDS hydrogen equipment codes shape testing protocols for coastal hydrogen bunkering stations. Busan-Ulsan industrial zones deploy portable cryogenic pump units where fixed infrastructure economics fail.
Australia
Offshore LNG projects face TGA pressure equipment codes that extend supplier qualification timelines by six to twelve months. Western Australia and Queensland anchor absolute demand volume for stationary installations in coastal terminal buildouts. Additional compliance layers fragment procurement pathways for vacuum-jacketed housing fabricators.
India
CEA grid integration requirements and BIS pressure equipment standards are beginning to shape cryogenic pump specifications for emerging LNG infrastructure. Gujarat and Maharashtra coastal zones concentrate early terminal development activity. PLI scheme incentives for clean energy equipment are redirecting capital toward hydrogen-ready fluid handling systems.
Asia-Pacific Cryogenic Pump Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: integrated multinational pump manufacturers with full lifecycle service capabilities, regional specialists leveraging domestic certification pathways, and emerging local fabricators capturing modular deployment opportunities. Strategic moves center on unbundling aftermarket service from hardware procurement and absorbing longer warranty obligations tied to project finance structures.
Among Japan-based manufacturers, Ebara Corporation exemplifies the integrated service archetype through domestic manufacturing footprints anchoring long-term utility contracts. Flowserve Corporation represents the multinational engineering tier competing through specialized centrifugal designs. Beijing Long March Tianmin Hi-Tech Co Ltd occupies the indigenous supplier position, capturing preferential access through SAMR-streamlined certification pathways in China's terminal expansions.
| Leading Market Players |
|---|
| Fives Group |
| Flowserve Corporation |
| Ebara Corporation |
| Weir Group PLC |
| Beijing Long March Tianmin Hi-Tech Co Ltd |
| Nikkiso Co Ltd |
| KSB SE & Co KGaA |
| Cryostar SAS |
| SHI Cryogenics Group |
| Others |
Value Chain & Pricing Dynamics
Osaka-Kobe industrial corridors concentrate specialty nickel-alloy casting capacity for vacuum-jacketed housings, feeding pricing power to Japanese fabricators serving LNG terminal operators across coastal China and South Korea. Extended warranty obligations tied to project finance structures compress margins for centrifugal pump suppliers while concentrating aftermarket service revenue with incumbent service providers.
Pricing Analysis
Certification level under SAMR GB standards and JIS codes creates the primary spread between premium and standard tiers. Project-based contract structures dominate LNG terminal procurement, with price differentiation hinging on after-sales service bundling and fifteen-year maintenance commitments. Cost compression in standard-tier centrifugal units is intensifying as Chinese provincial gas distributors unbundle hardware from lifecycle support. Research-driven aerospace procurement exhibits lowest price sensitivity due to flow precision requirements, while modular hydrogen fueling deployments show highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Extended payment terms from KOGAS and Chinese provincial distributors are restructuring supplier-financing arrangements across the region. Vacuum-jacketed housing fabrication draws from specialty steel mills concentrated in Japan and Germany, with hermetic seal geometries resting on precision machining capabilities in Osaka-Kobe and Chubu regions. Single-source vulnerability in nickel-based superalloy supply exposes procurement to input cost volatility. Distribution runs through EPC contractors and terminal operators with unbundled hardware and service procurement tracks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic pump procurement is shifting toward outcome-based service contracts that expand recurring revenue faster than hardware sales. Digital twin integration with predictive maintenance enables suppliers to capture fifteen-year lifecycle value unbundled from original equipment transactions.
For Market Incumbents: Harden captive service positions by integrating IoT sensor arrays into vacuum-jacketed housing diagnostics before third-party maintenance providers capture vacuum-jacketed refurbishment revenue. Accelerate certification investment under tightened GB 150 hydrogen embrittlement testing protocols to defend against indigenous Chinese suppliers leveraging SAMR-streamlined pathways. Vertical integration into specialty nickel-alloy casting mitigates supply concentration risk from Japanese and German steel mills.
For New Entrants and Emerging Players: Pursue modular portable configurations for South Korea's coastal hydrogen bunkering stations where fixed infrastructure economics fail and incumbent service networks remain underdeveloped. Target liquid hydrogen distribution applications under Japan's METI roadmap where magnetically levitated architectures reset competitive benchmarks. Lead with digital-native predictive maintenance platforms that bypass legacy SCADA integration complexity plaguing established LNG terminals.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with magnet bearing integration capabilities and unbundled service contract expertise. Five-to-ten year viability hinges on hydrogen infrastructure scaling faster than LNG terminal saturation. Acquisition target archetype: regional specialists with SAMR certification pathways and established utility relationships. The signal to watch is MFDS hydrogen equipment code convergence with METI standards reshaping interoperability requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Metallurgy | Captive nickel-alloy supply secures GB 150 certification timelines for Chinese terminal expansions. |
| Digital Twin Platform Development | IoT-enabled predictive maintenance restructures supplier-customer relationships across KOGAS infrastructure. |
| Modular Portable Unit Launch | Busan-Ulsan hydrogen bunkering stations bypass fixed infrastructure economics with flexible deployment. |
| Long-term Service Contract Unbundling | Fifteen-year maintenance agreements separate hardware procurement from lifecycle revenue capture. |
| Joint Venture with Indigenous Certifier | SAMR-streamlined pathways accelerate market access for Fujian and Guangdong terminal projects. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with LNG terminal procurement directors, aftermarket service heads, and EPC project managers; and secondary validation through customs trade data, SAMR certification filings, and METI hydrogen infrastructure disclosures. Bottom-up triangulation across product type, end user, and installation segmentation converged with top-down regional demand aggregation. Plant engineers at Yangtze River Delta petrochemical clusters and maintenance directors at Chubu regasification facilities provided operational deployment perspectives.
Forecast inputs span submersible, centrifugal, positive displacement, and reciprocating pump architectures across oil and gas, industrial, chemical processing, and aerospace end uses. Stationary and portable installation modes, onshore and offshore deployment contexts, and maintenance, installation, repair, and consulting service types shaped segmentation granularity. CAGRs were derived from supply-side capacity buildouts and demand-side infrastructure commitments across the analysis window. Hydrogen roadmap milestones and GB standard evolution provided industry-specific trajectory anchors.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by emerging Chinese fabricators or accelerated magnet bearing adoption by Japanese multinationals would shift outcomes. Macroeconomic deviation in project finance availability, regulatory divergence in hydrogen equipment codes, or technological breakthrough in seal geometry materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Oil and Gas Actuators Market