
 Rotary Pump Market | 2026-2036
Rotary Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Pump Market Intelligence
A capital-intensity divergence between integrated manufacturers and assembly-focused competitors is unwinding competitive stability in rotary pump supply. Flowserve Corporation leverages captive foundry capacity and precision machining networks to sustain margin control across high-pressure gear and screw pump lines. KSB SE & Co. KGaA anchors its position through deep backward integration into motor and seal technologies, while IDEX Corporation specializes in sanitary vane pump configurations for food-grade and pharmaceutical duty cycles.
A rotary pump transfers fluid through the mechanical rotation of one or more internal elements—gears, vanes, screws, or lobes—within a closely toleranced casing, typically achieving discharge pressures from 50 to 5,000 psi depending on configuration and material grade. Its primary industrial purpose is to deliver precise, pulse-free volumetric flow across viscous, abrasive, or shear-sensitive media in continuous-process environments. Screw pumps command the largest installed base in oil & gas pipeline and marine bunkering applications, where their axial-flow geometry handles multi-phase crude without cavitation damage. Gear pumps dominate compact hydraulic power units and precision metering skids, though margin pools are shifting toward custom alloy configurations for chemical processing duty. Vane pumps retain strength in mobile agricultural equipment and legacy machine tool coolant circuits, a segment showing slower replacement velocity as end-users defer capital spend.
EPA emissions rules and OSHA process safety mandates in the United States compel rotary pump operators to specify mechanical seal upgrades and leak detection instrumentation, directly inflating replacement part attach rates. The EU F-Gas Regulation and REACH chemical restrictions shape European demand toward hermetically sealed screw and diaphragm pump architectures with fluoropolymer-compatible elastomers. Stakeholders must weigh the pace of electric actuator substitution against hydraulic technology's residual installed base when allocating R&D budgets and field service capacity across the forecast horizon.
Market Dynamics
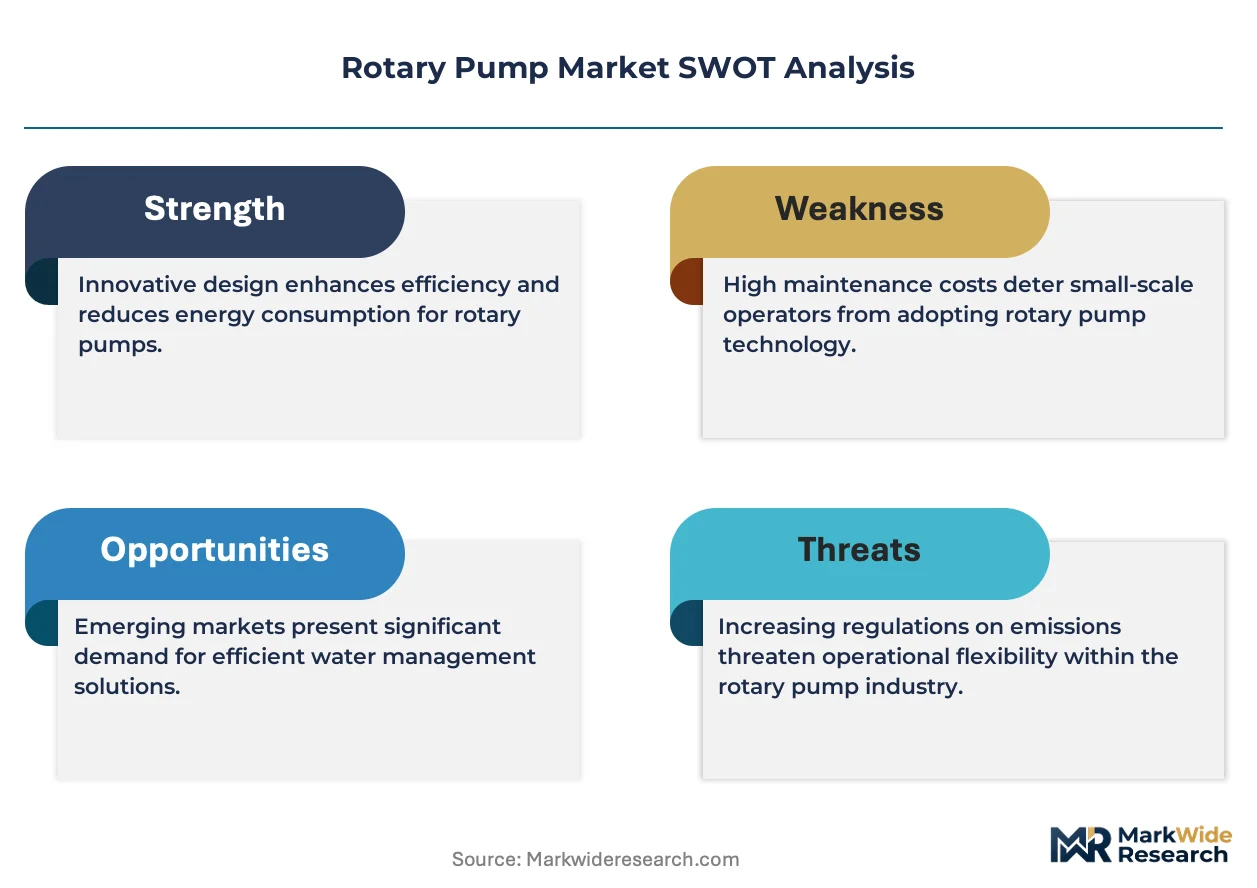
EPA effluent standards and the EU F-Gas Regulation are forcing a wholesale replacement cycle across installed rotary pump bases, converting regulatory pressure into immediate capital expenditure mandates for sealed, low-emission architectures.
Growth Catalysts
- Membrane Filtration Expansion:Water treatment facilities across Germany and the United States are procuring rotary pumps for sludge handling and reverse osmosis pre-treatment, driven by tightening municipal discharge requirements.
- REACH Chemical Restrictions:The European regulation is accelerating demand for fluoropolymer-compatible elastomers in hermetically sealed screw pump designs for solvent transfer applications.
- Industrial Corridor Modernization:Chemical processors in Germany's Rhine-Ruhr region are upgrading fluid transfer infrastructure, creating concentrated demand for high-pressure gear and lobe pump configurations.
Market Restraints
- Specialized Alloy Input Volatility:Nickel and cobalt price swings directly compress margins on corrosion-resistant pump castings specified for sulfuric acid duty cycles.
- Precision Machining Concentration:Germany and Japan dominate multi-axis CNC capacity for tight-tolerance screw rotor production, creating geographic supply vulnerability.
- Electric Actuator Substitution:Linear motor-driven positive displacement pumps are displacing hydraulic rotary units in precision metering applications below 500 psi.
Strategic Opportunities
- Hydrogen Infrastructure White Space:Liquid hydrogen transfer stations in the United States require cryogenic-compatible screw pump architectures that incumbent suppliers have yet to certify.
- IRA Clean Manufacturing Credits:The US Inflation Reduction Act is subsidizing domestic production of energy-efficient fluid handling equipment for industrial process applications.
- Digital Twin Convergence:Integration of vibration sensors with predictive maintenance software is enabling premium service attach rates for high-value pump installations.
Industry Challenges
- Precision Grinding Skill Scarcity:Screw rotor profile grinding demands journeyman-level expertise that German and Swiss technical institutes are producing at insufficient rates.
- API 676 Certification Timelines:Third-party validation for centrifugal and rotary pump packages in oil & gas service extends lead times by 14-22 weeks, constraining order conversion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Pump Market |
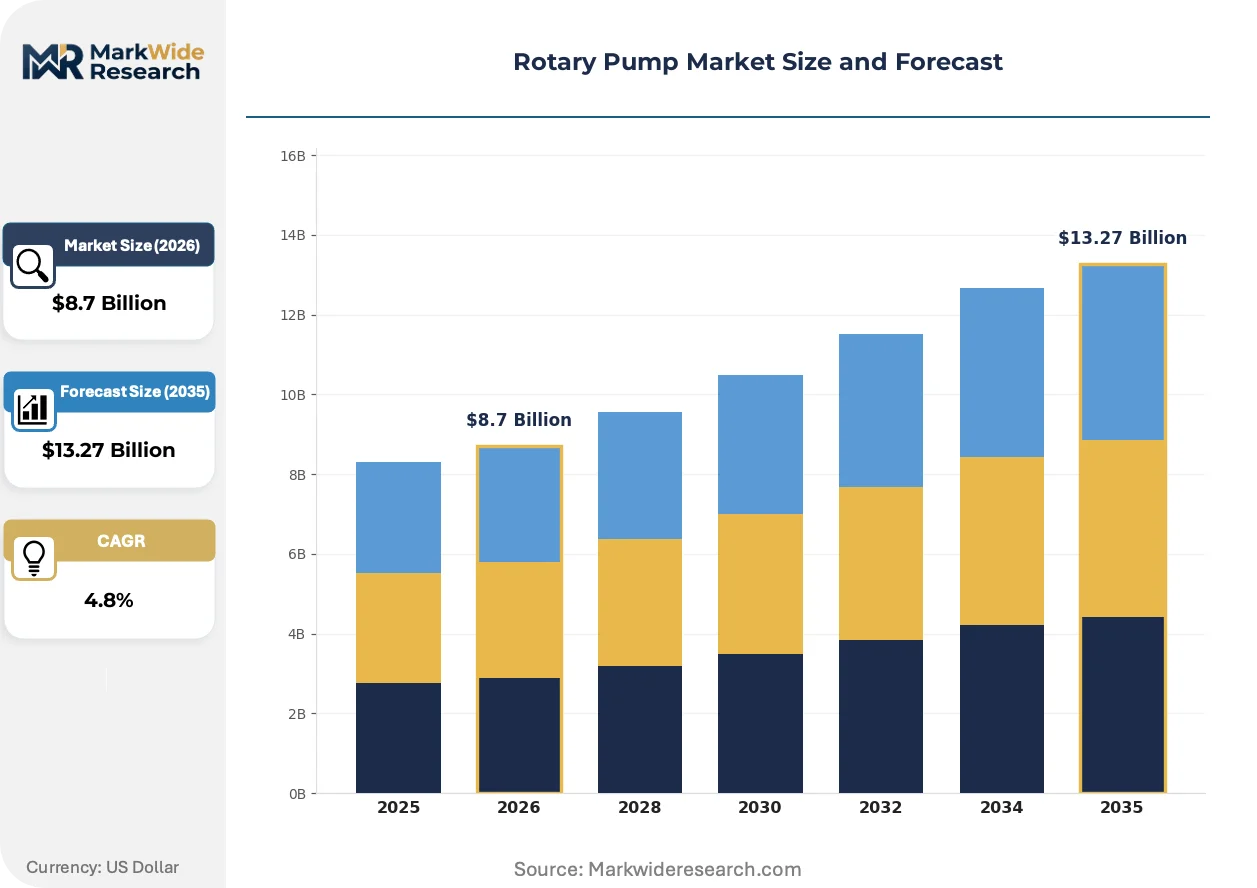
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Vane Pumps, Screw Pumps, Diaphragm Pumps End User: Oil & Gas, Chemical Processing, Water Treatment, Food & Beverage Technology: Electric, Hydraulic, Pneumatic, Manual Application: Industrial, Agricultural, Marine, Pharmaceutical |
| Companies Covered | Xylem Inc., Flowserve Corporation, KSB SE & Co. KGaA, Atlas Copco AB, SPX Flow, IDEX Corporation, Dover Corporation, Colfax Corporation, Pentair Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Pump Market Strategic Shifts & Innovations
Digital instrumentation and materials science are converging to redefine rotary pump value propositions, shifting competitive differentiation from mechanical reliability toward data-enabled uptime guarantees and chemical compatibility breadth.
Ceramic-coated screw rotors are fragmenting traditional metallurgical specifications in abrasive slurry service. Mining operators in Western Australia and Chile are specifying silicon carbide surface treatments for phosphate and copper concentrate transfer, bypassing conventional hardened steel wear rates. This materials shift is fragmenting supplier tiering, as captive coating capacity becomes a disqualifying capability for large-project bids.
The EU F-Gas Regulation is mandating hermetic sealing architectures for all refrigerant and process gas handling equipment by 2030. Pump OEMs are redesigning screw and diaphragm casings to eliminate shaft penetrations, prioritizing magnetic drive and canned motor integrations. Chemical processors in Belgium and the Netherlands are pre-emptively specifying these configurations to avoid mid-decade retrofit penalties.
Service contract unbundling is disrupting traditional bundled maintenance arrangements in North American food processing. End-users are separating predictive monitoring subscriptions from parts-and-labor coverage, selecting specialized vibration analytics vendors over OEM service divisions. This procurement pattern is most pronounced in Wisconsin and California dairy processing cooperatives, where internal maintenance teams now specify third-party sensor packages.
Rotary Pump Market Segmentation
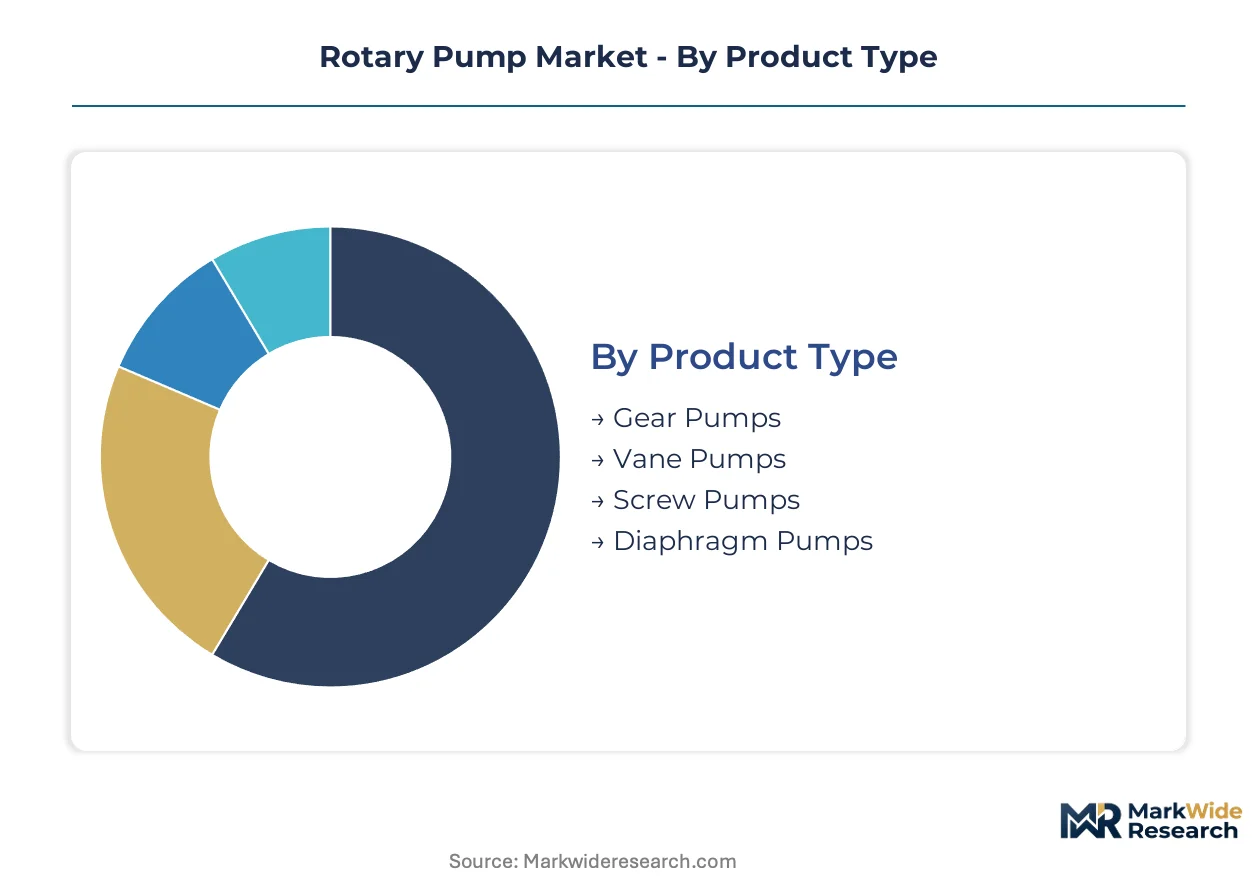
Rotary pump procurement patterns diverge sharply across product architectures and end-use environments, with regulatory compliance thresholds and fluid compatibility requirements dictating specification choices. Understanding these segment boundaries enables suppliers to align R&D investments with the highest-attach-rate upgrade cycles.
Product Type:
EPA effluent standards and the EU F-Gas Regulation impose divergent sealing and emission requirements across rotary pump architectures, fragmenting compliance pathways by mechanical design.
- Gear Pumps:Compact positive displacement units with interlocking cogs achieve precise volumetric metering in hydraulic power packs and chemical injection skids. Demand concentrates in Germany's Rhine-Ruhr chemical corridor, where REACH-mandated fluoropolymer seal upgrades are accelerating replacement velocity.
- Screw Pumps:Axial-flow geometries handle multi-phase crude and high-viscosity bitumen without cavitation damage in pipeline and marine bunkering service. Oil & gas operators in the United States Gulf Coast are specifying these for heavy crude transfer under stricter EPA leak detection mandates.
- Vane Pumps:Sliding vanes in eccentric housings deliver pulse-free flow for mobile agricultural equipment and legacy machine tool coolant circuits.
- Diaphragm Pumps:Hermetically sealed reciprocating membranes isolate process fluid from mechanical drive components in pharmaceutical and hazardous chemical duty.
Established volume favors gear pumps in general industrial service; emerging adoption favors screw pumps in emission-controlled hydrocarbon handling.
End User:
Process safety thresholds and fluid contamination risks create tiered pricing structures across customer verticals, with pharmaceutical and food-grade specifications commanding premium engineering margins.
- Oil & Gas:Pipeline operators and refinery complexes specify API 676-certified rotary packages for custody transfer and process injection. United States onshore shale producers are retrofitting wellpad chemical injection skids with sealed screw architectures to satisfy EPA methane monitoring rules.
- Chemical Processing:Sulfuric acid, caustic soda, and solvent transfer operations demand corrosion-resistant alloys and fluoropolymer elastomers. Belgian and Dutch processors are pre-emptively specifying hermetic screw pump configurations to avoid EU F-Gas Regulation retrofit penalties.
- Water Treatment:Municipal and industrial facilities deploy rotary pumps for sludge thickening, membrane filtration feed, and reverse osmosis pre-treatment.
- Food & Beverage:Sanitary vane and lobe pump configurations with 3A certification and electropolished surfaces handle dairy, beverage, and viscous food product transfer.
Maintenance contract values are highest in chemical processing; steepest expansion trajectory appears in water treatment infrastructure.
Technology:
Actuation source selection reflects a tension between hydraulic power density and electric precision, with pneumatic systems retaining niche positions in explosive atmospheres.
- Electric:Variable-frequency drive integration enables precise flow modulation and energy recovery in continuous-process environments. German automotive suppliers are specifying servo-driven gear pumps for precision coating and adhesive metering applications.
- Hydraulic:High power-to-weight ratios sustain dominance in mobile equipment and high-pressure industrial presses. United States construction equipment manufacturers specify these for implement control circuits.
- Pneumatic:Intrinsically safe operation without electrical ignition risk suits solvent handling and grain processing facilities.
- Manual:Hand-cranked rotary pumps serve emergency backup and remote field applications without power infrastructure.
Installed base concentration favors hydraulic actuation; specification momentum favors electric drive integration.
Application:
Environmental exposure conditions and uptime criticality differentiate specification requirements across deployment contexts, from abrasive mining slurries to sterile pharmaceutical cleanrooms.
- Industrial:Continuous-process manufacturing in steel, pulp and paper, and general machinery production specifies rotary pumps for coolant circulation, lubrication, and hydraulic power. United States steel mills are upgrading legacy vane pump circuits under OSHA process safety management mandates.
- Agricultural:Tractor-mounted and irrigation system pumps handle fertilizers, pesticides, and viscous crop inputs. Midwest United States grain cooperatives specify these for liquid handling during planting and harvest windows.
- Marine:Engine room lubrication, fuel transfer, and bilge handling systems require compact, vibration-resistant rotary architectures.
- Pharmaceutical:Aseptic processing and active pharmaceutical ingredient transfer demand validated cleanability and batch traceability.
Replacement parts revenue concentrates in industrial maintenance; qualification barriers are steepest in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's precision-machining corridor while cost-sensitive procurement dominates India's expanding industrial base. This asymmetry fragments supplier tiering across geographies.
United States
Shale producers in the Permian Basin and Gulf Coast refineries drive demand for sealed screw pump architectures under EPA methane monitoring mandates. The Inflation Reduction Act subsidizes domestic production of energy-efficient fluid handling equipment. Houston-area chemical processors are retrofitting wellpad injection skids to satisfy stricter leak detection rules.
Germany
Rhine-Ruhr chemical clusters and Bavarian automotive suppliers anchor European demand for high-pressure gear and precision metering pumps. REACH chemical restrictions accelerate fluoropolymer seal upgrades across installed bases. Stuttgart-based coating specialists are certifying ceramic-treated rotors for abrasive slurry applications.
China
Petrochemical expansion in the Yangtze River Delta and Shandong Peninsula sustains volume demand for multi-phase crude transfer systems. National dual carbon goals pressure state-owned refiners toward lower-emission pump architectures. Ningbo-Zhoushan port authorities are specifying marine bunkering pumps for heavy fuel oil handling.
India
Gujarat's chemical parks and Maharashtra's pharmaceutical corridors drive procurement of sanitary lobe and vane pump configurations. PLI scheme incentives support domestic manufacturing of precision fluid handling components. Mumbai-Pune industrial belt processors are modernizing solvent transfer infrastructure under tightening environmental compliance.
Japan
Kansai region machinery builders and Chubu automotive suppliers specify compact hydraulic gear pumps for precision coating applications. METI energy efficiency standards accelerate variable-frequency drive integration. Nagoya-area machine tool manufacturers are upgrading legacy coolant circuits under revised industrial emissions guidelines.
Rotary Pump Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated manufacturers with captive foundry and precision machining networks control premium segments, while assembly-focused competitors compete on delivery speed and customization flexibility. Three archetypes dominate: vertically integrated full-liners, specialized niche players, and regional fabrication houses. Capacity expansion in ceramic coating capabilities and strategic partnerships for predictive maintenance software represent the dominant competitive moves.
Among diversified industrial conglomerates, Xylem Inc. and Flowserve Corporation exemplify scale-driven archetypes with broad geographic presence, while KSB SE & Co. KGaA represents the European integrated manufacturer model with deep backward integration into motor and seal technologies. IDEX Corporation occupies a specialist position within sanitary pump configurations for regulated process industries.
| Leading Market Players |
|---|
| Xylem Inc. |
| Flowserve Corporation |
| KSB SE & Co. KGaA |
| Atlas Copco AB |
| SPX Flow |
| IDEX Corporation |
| Dover Corporation |
| Colfax Corporation |
| Pentair Ltd. |
| Others |
Cost & Logistics Intelligence
Fourteen-to-twenty-two-week API 676 certification timelines for oil and gas service packages concentrate pricing power with German and Japanese suppliers possessing captive multi-axis CNC capacity, while buyers facing EPA methane mandates absorb premium configured-to-order pricing for sealed screw architectures.
Pricing Analysis
The customization-premium spread separates standard catalog gear pumps from fluoropolymer-sealed, corrosion-alloy configurations for sulfuric acid duty cycles. Three-tier pricing structure across premium certified, standard industrial, and economy replacement tiers reflects REACH compliance grade and after-sales bundling intensity. Cost compression in economy-tier vane pumps is intensifying because Midwest agricultural equipment manufacturers defer capital spend. Chemical processors in Belgium and the Netherlands exhibit lowest price sensitivity due to EU F-Gas retrofit avoidance penalties.
Supply Chain Analysis
Strait of Malacca transit vulnerability for nickel and cobalt concentrates from Indonesian and Philippine mining operations feeds into corrosion-resistant pump casting supply chains centered on German foundry networks. Raw material dependencies span nickel-cobalt superalloys, silicon carbide ceramic feedstocks, and precision-grade bearing steels from Swedish and Austrian mills. Single-source vulnerability concentrates in Swiss and German screw rotor profile grinding capacity. Distribution runs through OEM-direct project contracting for large installations and authorized distributor networks for aftermarket replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as hydrogen infrastructure buildouts and water treatment membrane filtration adoption create first-mover certification advantages for cryogenic-compatible and hermetically sealed architectures.
For Market Incumbents: Shield installed base revenue by certifying ceramic-coated rotor capabilities for abrasive mining slurry applications before Australian and Chilean operators consolidate supplier tiers. Deepen backward integration into fluoropolymer elastomer compounding to capture REACH-mandated seal upgrade cycles and defend margin position against specialized niche competitors.
For New Entrants and Emerging Players: Lead with liquid hydrogen transfer station certification gaps in United States Gulf Coast infrastructure, where incumbent suppliers lack cryogenic screw pump validations. Target predictive maintenance software integration partnerships with Wisconsin and California dairy processing cooperatives unbundling OEM service contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA and EU emission mandates convert installed base replacement into recurring capital expenditure cycles. Acquisition focus should center on mid-tier specialists with captive ceramic coating capacity and hermetic sealing engineering depth. Monitor API 676 certification backlog durations as inflection indicator for order conversion velocity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | Captive silicon carbide surface treatment capability disqualifies competitors for Australian phosphate mining bids. |
| Hermetic Sealing Architecture Development | Magnetic drive and canned motor integrations satisfy EU F-Gas Regulation mandates for Belgian chemical processors. |
| Predictive Maintenance Platform Partnership | Vibration sensor integration with third-party analytics vendors captures unbundled service contracts in North American food processing. |
| Backward Integration into Seal Technologies | In-house fluoropolymer elastomer production secures margin control during REACH-driven upgrade cycles. |
| Cryogenic Certification Investment | Liquid hydrogen transfer validation opens white-space demand from United States Gulf Coast infrastructure developers. |
Research Approach
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this rotary pump market assessment. Primary field engagement combined with secondary validation against customs trade data, SEC 10-K filings, American Chemistry Council reports, and oil and gas operator capex disclosures. Bottom-up triangulation across product architecture demand and top-down cross-check against end-use industry capital expenditure patterns ensured methodological rigor.
Sensitivity analysis across nickel and cobalt price volatility bands, API 676 certification timeline scenarios, and electric actuator substitution rates shaped the forecast framework. Segmentation dimensions modeled include pump architecture type, actuation technology, end-use vertical, and regional regulatory compliance cluster. CAGRs were derived from installed base replacement velocity analysis and greenfield infrastructure penetration curves, with hydrogen infrastructure buildout assumptions and water treatment membrane filtration expansion rates serving as key industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity and EU F-Gas Regulation adherence timelines would require recalibration. Practitioners should keep alternative scenarios live as electric actuator substitution thresholds and precision machining skill scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Air Compressor Controller Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market