
 Fine Bubble Diffusers Market | 2026-2036
Fine Bubble Diffusers Market Size, Share, and Industry Trends Forecast 2026-2036
Fine Bubble Diffusers Market Insights
Aftermarket membrane replacement revenue is narrowing the margin gap with original equipment sales as utilities extend capital cycles. Xylem Inc. leverages its installed base across North American municipal plants to secure recurring service contracts. Sulzer anchors European demand through specialized ceramic diffuser manufacturing in Switzerland. Environmental Dynamics International competes on membrane material science, offering extended-lifetime silicone formulations that reduce plant downtime.
Fine bubble diffusers are gas-liquid contact devices that produce bubbles typically 1-3 mm in diameter through porous ceramic, membrane, or perforated metal media, maximizing oxygen transfer efficiency in aeration basins through high surface-area-to-volume ratios. Membrane diffusers now lead product type share due to elastomer advances, while ceramic segments retain preference in high-temperature industrial process applications where chemical resistance outweighs first-cost sensitivity. Wastewater treatment dominates application demand as biological nutrient removal standards tighten, though aquaculture installations represent the fastest-growing application as recirculating aquaculture systems scale in Northern Europe and Southeast Asia.
The EPA enforces effluent limitations through NPDES permits that directly mandate minimum dissolved oxygen levels, compelling municipal upgrades to fine bubble aeration. Germany's KBA and France's ANSM do not regulate this sector, but the EU Urban Wastewater Treatment Directive shapes product specifications across member states, while China's MEE implements increasingly stringent surface water quality standards. Japan's METI promotes energy-efficient aeration through industrial equipment standards that favor high-standard oxygen transfer efficiency ratings. Stakeholders must monitor how evolving energy-efficiency mandates in major wastewater markets reshape total-cost-of-ownership calculations against upfront capital expenditure preferences.
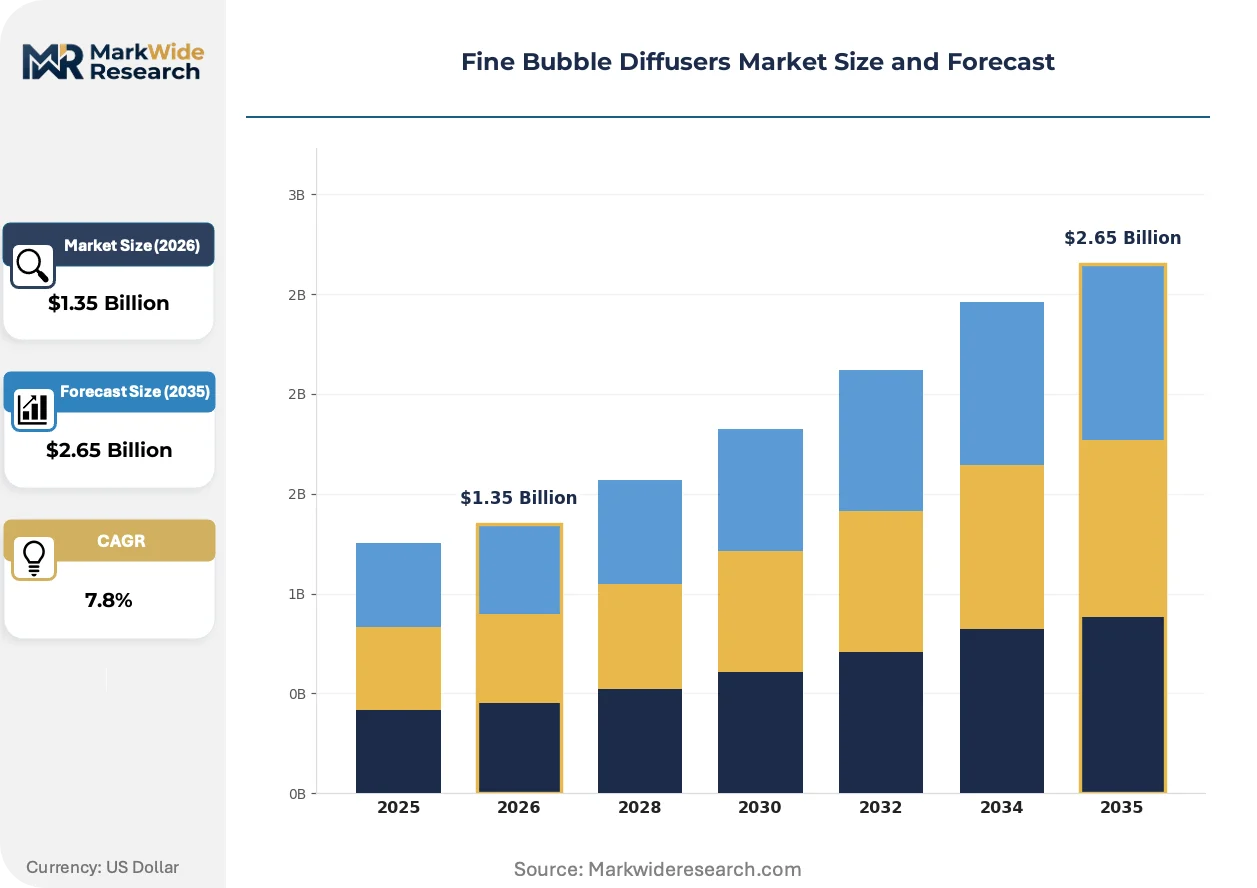
Market Dynamics
Municipal utilities face capital renewal cycles where membrane degradation in existing fine bubble diffuser installations forces technology refresh decisions against tightening dissolved oxygen mandates from environmental regulators.
Growth Catalysts
- EPA NPDES permit enforcement:Municipal wastewater facilities across the United States must upgrade aeration infrastructure to meet dissolved oxygen minimums, accelerating diffuser replacement schedules.
- China urbanization pressure:Rapid city expansion strains existing water treatment capacity in tier-2 and tier-3 municipalities, requiring new aeration basin construction with fine bubble systems.
- Elastomer membrane advances:Silicone and EPDM formulations now deliver 8-10 year service lifetimes, reducing total cost of ownership calculations for utility procurement committees.
Market Restraints
- Ceramic raw material concentration:High-purity alumina supply concentrates in Guizhou province, creating price volatility for ceramic diffuser manufacturers dependent on Chinese feedstock.
- Capital budget compression:Municipal utilities defer aeration upgrades when interest rate environments raise municipal bond financing costs for infrastructure projects.
- Surface aerator substitution:Mechanical surface aerators retain preference in shallow basin designs and temporary installations where fine bubble oxygen transfer advantages diminish.
Strategic Opportunities
- Recirculating aquaculture systems:Northern European salmon farming operations and Southeast Asian shrimp producers adopt fine bubble aeration for dissolved oxygen control in closed-loop tanks.
- EU Green Deal funding:Energy-efficiency renovation grants for municipal infrastructure favor high-standard oxygen transfer equipment, creating procurement preference for premium diffuser systems.
- Membrane-sensor convergence:Integration of dissolved oxygen probes with smart diffuser arrays enables real-time aeration optimization, opening premium service contract revenue streams.
Industry Challenges
- Field installation skill scarcity:Proper membrane sealing and grid leveling requires trained technicians, and contractor capacity bottlenecks delay project completion timelines.
- Legacy basin retrofit complexity:Existing concrete basin geometries and fixed piping infrastructure constrain diffuser grid redesign options, forcing customized engineering solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fine Bubble Diffusers Market |
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Membrane, Stainless Steel, Plastic Application: Aquaculture, Wastewater Treatment, Water Treatment, Industrial Processes End User: Aquatic Farms, Municipalities, Factories, Research Institutions Installation Type: Fixed, Portable, Modular, Submersible |
| Companies Covered | Jäger Umwelt-Technik, Environmental Dynamics International, Xylem Inc., Refractron Technologies, Aquaconsult Anlagenbau, Sulzer, Aqua-Aerobic Systems, OTT Group, SSI Aeration Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fine Bubble Diffusers Market Trends and Innovations
Material science advances and regulatory energy-efficiency mandates are converging to reshape product specifications and procurement criteria across municipal and industrial aeration applications.
Ceramic-polymer composite membranes are hybridizing traditional porous ceramic durability with elastomer flexibility, enabling deployment in high-temperature industrial process water where pure membranes fail. Food and beverage processors in Germany and Japan adopt these hybrid systems for brewery and dairy wastewater treatment. The technology is compressing the historical trade-off between ceramic longevity and membrane oxygen transfer efficiency.
The EU Urban Wastewater Treatment Directive's energy-efficiency amendments require member states to benchmark aeration power consumption against oxygen transfer performance. Germany's KBA and France's ANSM do not directly regulate this sector, but national implementation of the directive shapes municipal tender specifications. Equipment vendors now certify SOTE (Standard Oxygen Transfer Efficiency) ratings under ISO 15443 to compete for public procurement contracts.
Service unbundling from equipment sales is restructuring vendor-customer relationships as utilities favor performance-based membrane replacement contracts over capital purchases. Xylem and Sulzer restructure field service organizations to capture recurring revenue from installed base maintenance. This pattern concentrates in North American municipal accounts where stretched capital budgets favor operational expenditure treatment of diffuser lifecycle costs.
Fine Bubble Diffusers Market Segmentation
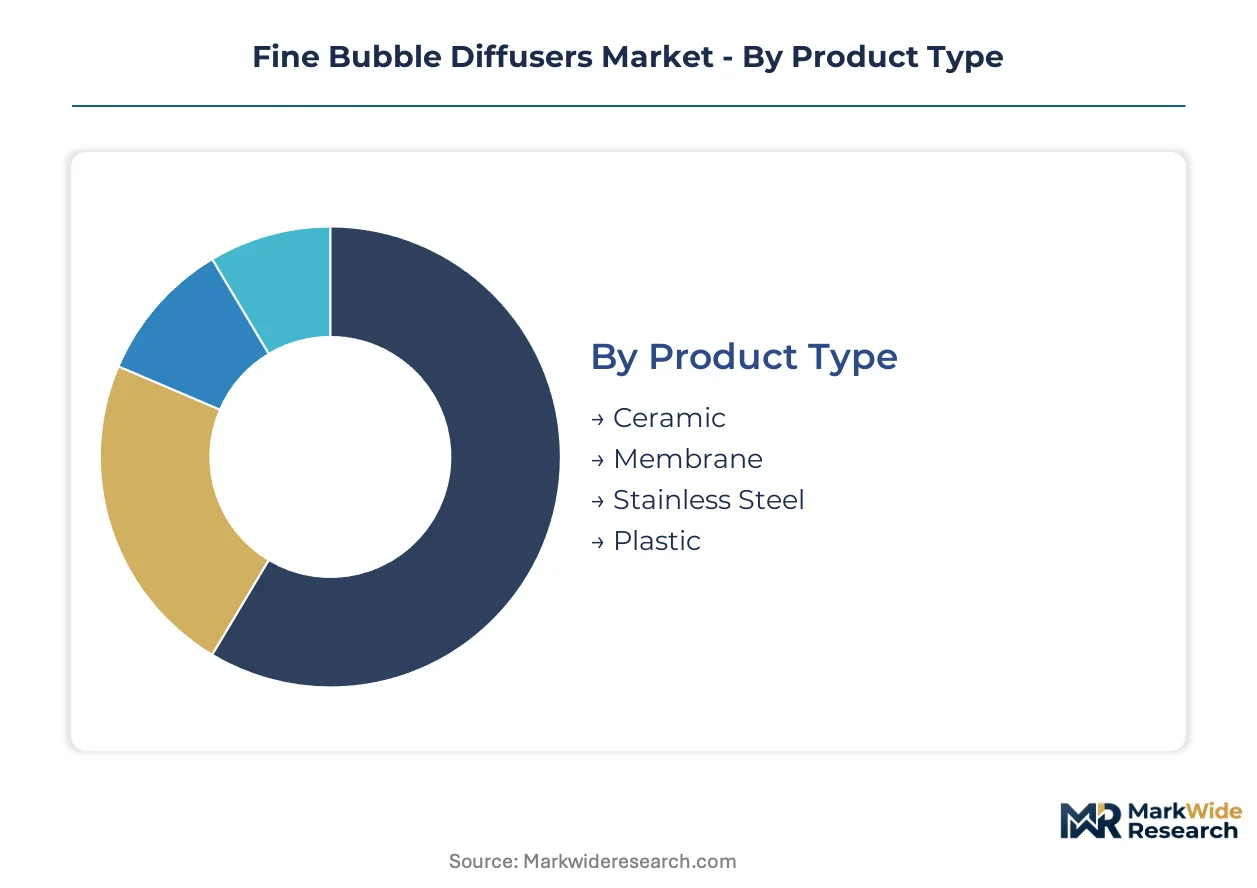
Segmentation in fine bubble diffusers reveals how oxygen transfer technology adapts across divergent operating environments. Product material selection, application context, and installation constraints each create distinct procurement criteria that vendors must address separately.
Product Type:
Mature ceramic formats coexist with emerging membrane technologies, creating a bifurcated supply base serving different durability and efficiency priorities.
- Membrane:Elastomer membranes—EPDM and silicone formulations—deliver superior oxygen transfer efficiency through precise bubble size control. Municipal wastewater plants in Germany and Japan specify these for energy-efficient aeration basins where EPA NPDES and METI standards mandate high SOTE ratings.
- Ceramic:Sintered alumina or silica carbide structures withstand aggressive chemical environments and elevated temperatures. Industrial process water treatment in chemical manufacturing clusters favors ceramic for longevity where membrane degradation would accelerate.
- Stainless Steel:Perforated metal diffusers serve temporary installations and food-grade applications requiring corrosion resistance without ceramic brittleness.
- Plastic:Injection-molded polymer formats address cost-sensitive aquaculture operations in Southeast Asia where capital constraints outweigh efficiency optimization.
Membrane handles the majority of throughput; ceramic is the fastest mover on share in industrial process applications.
Application:
Volume concentration clusters where regulatory enforcement is strictest, while emerging use cases expand the addressable market periphery.
- Wastewater Treatment:Biological nutrient removal in municipal facilities drives baseline demand. China's MEE surface water standards and EU Urban Wastewater Treatment Directive compel aeration upgrades across tier-2 cities and member states respectively.
- Aquaculture:Recirculating aquaculture systems in Norwegian salmon operations and Vietnamese shrimp farming represent the steepest expansion trajectory. Dissolved oxygen precision in closed-loop tanks favors fine bubble over mechanical aeration.
- Water Treatment:Potable water ozonation and reservoir destratification employ diffusers for chemical dosing and mixing, though volumes trail wastewater applications.
- Industrial Processes:Brewery and dairy wastewater in Germany, plus semiconductor fabrication rinse water in Japan, require specialized ceramic-polymer hybrid systems.
Wastewater treatment absorbs the dominant share of installed capacity; aquaculture is climbing the fastest as protein demand intensifies land-based farming.
End User:
Customer type determines procurement rhythm—capital cycles versus operational expenditure treatment shapes vendor engagement models.
- Municipalities:Public utilities operate on 15-20 year capital renewal cycles with stringent tender requirements. ISO 15443 SOTE certification and EU Green Deal funding eligibility filter supplier selection.
- Aquatic Farms:Private operators in Northern Europe and Southeast Asia prioritize rapid deployment and modular scalability over lifetime optimization.
- Factories:Industrial end users balance chemical resistance needs against production uptime, often specifying ceramic for high-temperature process streams.
- Research Institutions:Universities and government labs drive pilot-scale innovation but represent minimal commercial volume.
Municipalities command the largest committed budgets; aquatic farms are expanding most quickly as aquaculture industrializes.
Installation Type:
Basin geometry and operational flexibility requirements segment deployment approaches across greenfield and retrofit contexts.
- Fixed:Permanent grid installations dominate municipal wastewater infrastructure. Concrete basin retrofits in legacy US plants constrain design flexibility and demand customized engineering.
- Modular:Pre-assembled drop-in systems reduce field installation labor for contractor-constrained markets. European municipal tenders increasingly specify modular formats to accelerate project timelines.
- Portable:Temporary aeration for lagoon maintenance and emergency response serves utility maintenance departments with intermittent deployment needs.
- Submersible:Integrated blower-diffuser units target shallow basin applications where fixed grid depth is impractical.
Fixed installations retain the bulk of existing infrastructure; modular formats are gaining share fastest as utilities seek to compress project delivery schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: European utilities prioritize energy-efficient membrane systems for existing basin retrofits, while Chinese municipalities favor ceramic diffusers for new greenfield construction in rapidly urbanizing tier-2 cities.
United States
EPA NPDES permit enforcement drives municipal aeration upgrades across the Midwest and Southeast. The Clean Water Act mandates dissolved oxygen minimums that compel diffuser replacement in aging infrastructure. Chicago and Atlanta metropolitan utilities deploy membrane systems to meet combined sewer overflow consent decrees.
Germany
EU Urban Wastewater Treatment Directive implementation prioritizes Standard Oxygen Transfer Efficiency certification for public tenders. Bavarian and North Rhine-Westphalian municipalities specify silicone membrane formats to satisfy energy-efficiency benchmarking requirements. Industrial clusters around Munich adopt ceramic-polymer hybrids for brewery wastewater treatment.
China
MEE surface water quality standards tighten effluent requirements for municipal plants in tier-2 and tier-3 cities. Urbanization pressure in the Yangtze River Delta and Pearl River Delta strains existing treatment capacity. Guizhou province alumina supply concentration shapes ceramic diffuser pricing volatility for domestic manufacturers.
Japan
METI industrial equipment standards favor high-SOTE aeration systems through energy-efficiency promotion programs. Kanto and Kansai region municipalities specify premium membrane diffusers for dissolved oxygen precision. Semiconductor fabrication clusters in Kyushu deploy specialized ceramic systems for high-temperature rinse water treatment.
Netherlands
Randstad region water boards pioneer modular diffuser installations to accelerate project delivery timelines. EU Green Deal funding eligibility filters municipal procurement toward certified energy-efficient systems. Aquaculture innovation clusters in Zeeland adopt fine bubble aeration for recirculating salmon farming operations.
Fine Bubble Diffusers Market Competitive Landscape
Capability concentration sits with specialized membrane material scientists; scale advantage sits with diversified water technology conglomerates. The vendor base organizes into three tiers: integrated multinationals with full-service portfolios, regional specialists with ceramic or membrane expertise, and modular system fabricators serving contractor-constrained markets. Dominant competitive moves include service unbundling from equipment sales and geographic expansion through distribution partnerships rather than direct manufacturing investment.
Within the membrane-specialist tier, Environmental Dynamics International and SSI Aeration Inc. occupy positions emphasizing elastomer formulation durability. Among European-integrated conglomerates, Xylem Inc. and Sulzer exemplify the service-contract revenue model, leveraging installed base relationships to secure recurring maintenance agreements. Jäger Umwelt-Technik represents the regional German specialist archetype, while Aquaconsult Anlagenbau anchors the Austrian-German alpine market cluster.
| Leading Market Players |
|---|
| Jäger Umwelt-Technik |
| Environmental Dynamics International |
| Xylem Inc. |
| Refractron Technologies |
| Aquaconsult Anlagenbau |
| Sulzer |
| Aqua-Aerobic Systems |
| OTT Group |
| SSI Aeration Inc. |
| Others |
Pricing and Supply Chain Analysis
Guizhou province alumina concentration anchors ceramic diffuser input costs, shifting margin pools toward membrane specialists with elastomer formulation mastery and service-contract bundling capabilities. Municipal procurement committees now weight total cost of ownership more heavily than first-cost bids, compressing pricing power for undifferentiated ceramic suppliers while rewarding membrane vendors with lifecycle optimization tools.
Pricing Analysis
Long-term performance-based service contracts dominate municipal procurement, displacing transactional equipment sales as utilities stretch capital cycles. Three-tier pricing structure across premium SOTE-certified systems, standard membrane formats, and economy plastic diffusers separates procurement tiers by certification grade and after-sales bundling. Cost compression in ceramic segments intensifies because Guizhou feedstock volatility erodes margin buffers. Aquaculture operators in Southeast Asia exhibit highest price sensitivity, while German municipalities under EU Green Deal funding show lowest sensitivity due to grant eligibility requirements.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Sulzer's Swiss ceramic foundries and Xylem's membrane fabrication facilities in Mexico and China. High-purity alumina draws from Guizhou, silicone elastomer formulations from Germany and Japan, and EPDM compounds from US Gulf Coast petrochemical clusters. Single-source vulnerability runs through Guizhou alumina concentration, where environmental compliance shutdowns ripple through ceramic diffuser pricing. Distribution runs through municipal utility procurement departments, industrial EPC contractors, and aquaculture system integrators serving distinct end-use specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-sensor convergence is creating platform-economics dynamics where dissolved oxygen probe integration transforms standalone diffuser sales into recurring optimization service platforms, redefining vendor lock-in mechanisms across municipal accounts.
For Market Incumbents: Harden installed base relationships through predictive membrane replacement algorithms and ISO 15443 certification investments that raise tender barriers against low-cost ceramic imports. Surface aerator substitution in shallow basins and modular system fabricators represent immediate competitive threats; backward integration into silicone formulation production secures supply continuity and margin defense against Guizhou alumina volatility. For New Entrants and Emerging Players: Pursue recirculating aquaculture system deployments in Vietnam and Indonesia, where capital constraints favor rapid-deployment modular formats over premium efficiency optimization. Aquaculture presents the most penetrable segment due to industrializing protein demand and limited incumbent service infrastructure; partner with regional system integrators to bypass direct municipal tender complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane material science specialists as formulation R&D yields scale economies, making mid-tier elastomer innovators attractive acquisition targets before platform consolidation accelerates. Five-to-ten year viability favors vendors with smart-diffuser data platform capabilities; monitor EU Green Deal funding disbursement velocity as inflection indicator for municipal upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Sensor Integration | Real-time aeration optimization creates recurring service revenue streams beyond equipment sales. |
| Ceramic-Polymer Hybrid Development | Brewery and dairy processors in Germany adopt systems bridging membrane efficiency with ceramic durability. |
| Modular System Fabrication | Pre-assembled drop-in formats compress project timelines for contractor-constrained European municipal markets. |
| Backward Integration into Elastomer Production | In-house silicone formulation control insulates margins from petrochemical feedstock volatility. |
| EU Green Deal Certification Investment | ISO 15443 SOTE compliance filters supplier eligibility for energy-efficiency renovation grants. |
Research Methodology
Cross-validation between municipal utility procurement directors and membrane material scientists anchors the qualitative findings, with secondary validation through EPA NPDES permit databases, EU Urban Wastewater Treatment Directive implementation reports, and METI industrial equipment standard filings. Plant engineers at tier-2 Chinese municipalities, aftermarket service heads at North American water utilities, EPC contractors specializing in basin retrofits, and aquaculture system designers in Northern Europe provided primary perspective. Bottom-up triangulation across installed base estimates and top-down validation through regulatory mandate timelines shaped segment-level projections.
Calibration against historical replacement cycle data and regulatory enforcement intensity indices refined the analytical framework across the projection horizon. Segmentation dimensions modeled include product material type, application context, end-user procurement rhythm, and installation format flexibility. CAGRs emerged from elasticity analysis of capital expenditure sensitivity to municipal bond financing conditions and energy-efficiency mandate stringency. Oxygen transfer efficiency certification penetration rates and aquaculture land-based farming capacity expansion trajectories served as industry-specific forecast inputs.
Sensitivities concentrate around Chinese environmental policy enforcement consistency affecting alumina supply, EU Green Deal funding allocation velocity, and interest rate environments impacting municipal infrastructure financing. Forecasts reflect documented assumptions regarding regulatory mandate implementation timelines and technology substitution thresholds. Quarterly review of NPDES permit issuance rates, MEE surface water standard revision announcements, and METI energy-efficiency equipment subsidy disbursements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Membrane Pump Market