
 Asia Pacific Safety Drives and Motors Market | 2026-2036
Asia Pacific Safety Drives and Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Safety Drives and Motors Market Outlook
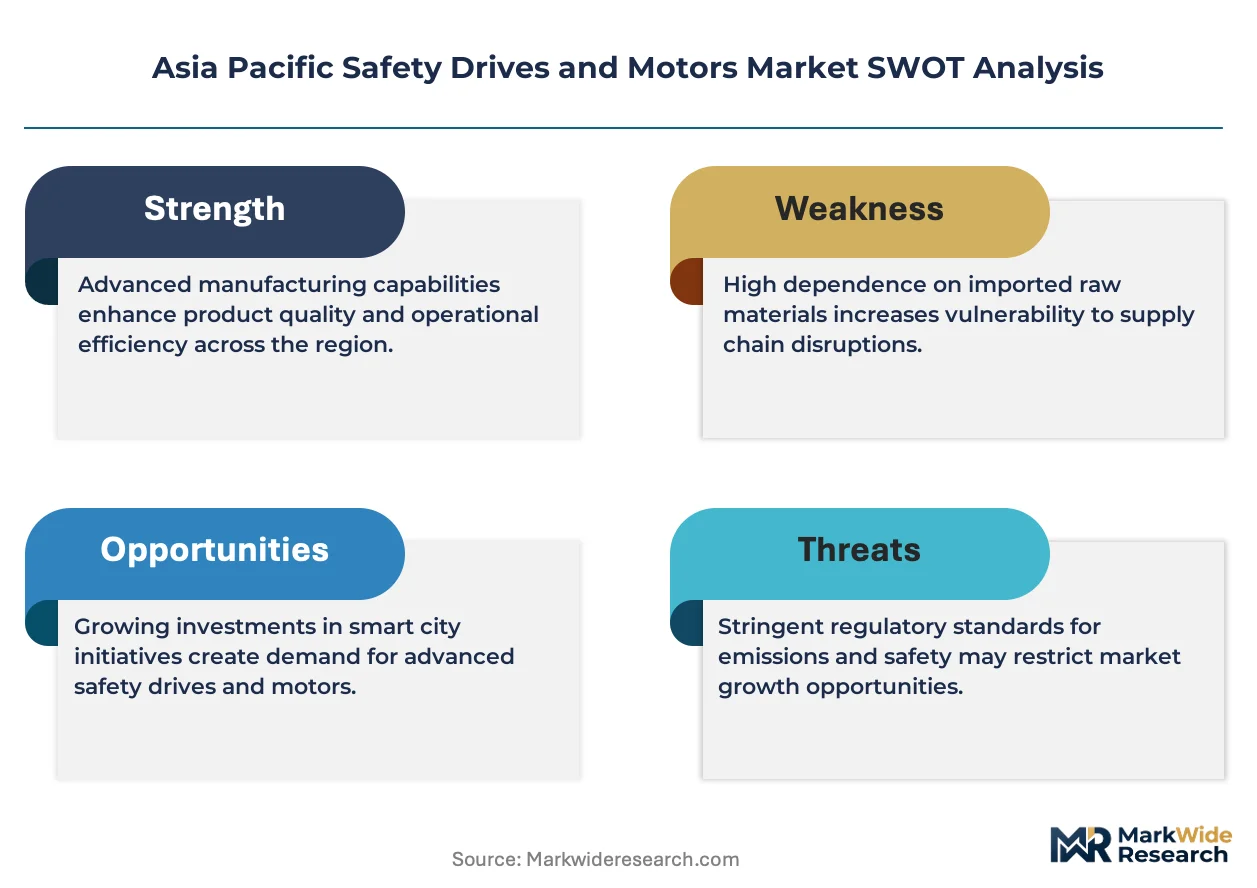
Integrated safety architectures is fragmenting legacy standalone safety relay configurations across Asia Pacific industrial automation. Siemens AG leverages its TIA Portal ecosystem to anchor safety drive deployments in German-affiliated manufacturing plants across China. ABB Limited competes through its ACS880 machinery drive line with built-in safe torque-off functionality. Pilz GmbH & Co. KG specializes in configurable safety controllers that extend compatibility with third-party servo platforms.
Asia Pacific safety drives and motors comprise electromechanical motion systems engineered with dual-channel encoder feedback, SIL 3 / PLe certified shutdown circuits, and STO (Safe Torque Off) response times under one millisecond to prevent hazardous machine states. These systems serve primary industrial purpose in protecting personnel during automated manufacturing, robotic collaborative workspaces, and high-speed material handling operations. Servo drives command premium positioning in precision robotics applications where closed-loop feedback maintains tight tolerances. Variable frequency drive technology dominates process control installations across chemical and food processing plants due to energy recovery capabilities. Motion control applications absorb the largest volume share as automotive and electronics manufacturers retrofit stamping and assembly lines with safety-rated axes.
China's MIIT mandates GB standard compliance for industrial safety equipment entering domestic smart factory programs. Japan's METI promotes JIS B 9700 alignment with international machinery safety conventions through its Robot Revolution Initiative. Australia's TGA-equivalent electrical safety regulators enforce AS 4024 compliance for imported automation components. Stakeholders must monitor divergence between China's GB standards and IEC harmonization timelines when configuring regional product portfolios.
Market Dynamics
Integrated safety architectures are fragmenting legacy standalone safety relay configurations as manufacturers across Asia Pacific consolidate control and safety functions into single hardware platforms. This structural shift is compressing supplier margins in discrete safety components while elevating system-level competition.
Growth Catalysts
- MIIT Smart Factory Mandates:China's Ministry of Industry and Information Technology directives require GB-compliant safety equipment in domestic automation programs, concentrating procurement toward certified motion systems in the Yangtze River Delta.
- Automotive Electrification:Battery gigafactories across Thailand and Indonesia require SIL 3-certified servo axes for electrode coating and cell assembly operations at speeds exceeding 200 meters per minute.
- Collaborative Robotics Deployment:STO-capable servo drives enable human-robot interaction without physical guarding, expanding adoption in electronics contract manufacturing facilities across Vietnam and Malaysia.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price fluctuations from Chinese processing concentration inflate permanent magnet servo motor costs unpredictably.
- Dual-Channel Encoder Supply Concentration:Heidenhain and Renishaw dominate high-resolution optical encoder supply, creating single-source vulnerability for PLe-certified feedback loops.
- GB-IEC Harmonization Gaps:Divergent certification timelines between China's national standards and IEC 62061 create product configuration complexity for regional portfolios.
Strategic Opportunities
- India's PLI Manufacturing Incentive:Production-linked incentive schemes for automotive and electronics sectors create first-mover advantage for safety drive vendors establishing local assembly.
- Safe Motion Over EtherCAT:Convergence of FSoE (Functional Safety over EtherCAT) with AI-powered predictive maintenance opens premium service revenue streams.
- Australian Mining Automation:AS 4024 compliance requirements in Western Australian iron ore operations drive replacement demand for legacy contactor-based safety systems.
Industry Challenges
- Functional Safety Engineering Shortage:Certified TÜV Rheinland machinery safety engineers remain scarce across Southeast Asian system integrator channels, extending commissioning timelines.
- Legacy Drive Retrofit Complexity:Integrating STO-capable replacements into 1990s-era PLC architectures requires custom safety relay bridging, inflating project engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Safety Drives and Motors Market |
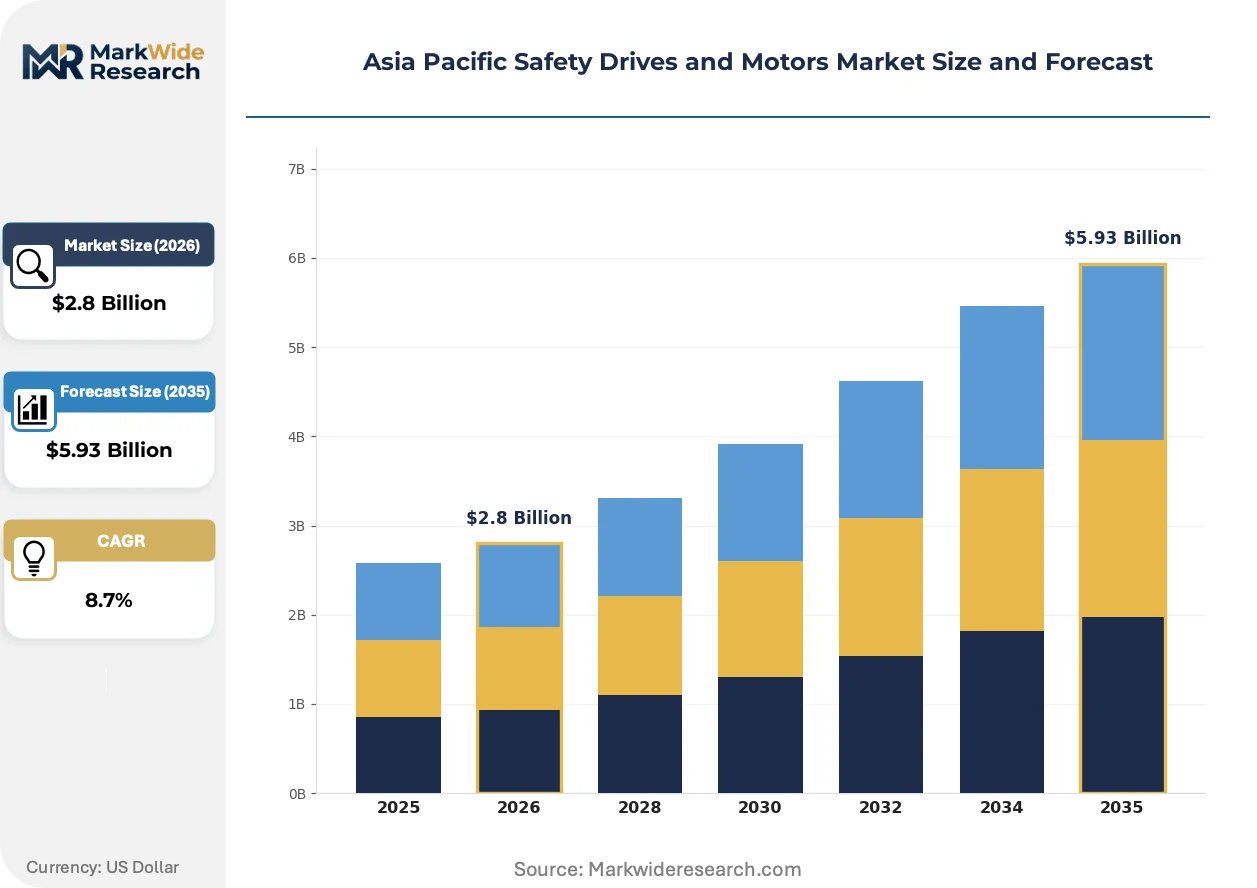
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servo Drives, AC Drives, DC Drives, Integrated Drives End User: Manufacturing, Automotive, Aerospace, Robotics Technology: Variable Frequency Drive, Digital Servo Drive, Closed Loop Drive, Soft Starter Application: Motion Control, Process Control, Material Handling, Positioning |
| Companies Covered | Rockwell Automation, Inc., ABB Limited, Siemens AG, Pilz GmbH & Co. KG, SIGMATEK GmbH & Co KG, Beckhoff Automation GmbH & Co. KG, B&R Industrial Automation GmbH, Kollmorgen, Hoerbiger India Precision Technology Private Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Safety Drives and Motors Market Strategic Shifts
Single-chip safety processors are collapsing the cost barrier between standard and safety-rated motion control, enabling tier-two manufacturers to compete on certified architectures without dedicated safety PLC hardware.
Safe torque off functionality embedded in silicon rather than external safety modules is collapsing the traditional premium commanded by discrete safety configurations. Mid-tier servo vendors in South Korea and Taiwan now ship STO-capable drives at standard drive price points, pressuring established European suppliers to unbundle their safety offerings. This compression is accelerating replacement cycles in cost-sensitive packaging machinery across ASEAN food processing plants.
Japan's METI Robot Revolution Initiative mandates JIS B 9700 alignment with ISO 10218 collaborative robot safety standards by 2026, forcing domestic servo manufacturers to recertify product lines for force-limiting control modes. Automotive suppliers in Toyota City and Nagoya industrial corridors are pre-emptively upgrading stamping line servos to comply, creating concentrated demand spikes ahead of enforcement deadlines. This regulatory compression is favoring vendors with existing IEC 61800-5-2 safety motion certification.
Electronics manufacturers in China's Pearl River Delta are unbundling safety drive procurement from long-term automation vendor contracts, shifting toward direct specification of certified components in capital expenditure tenders. This disintermediation fragments incumbent system integrator relationships and elevates component brand recognition in purchasing decisions. The pattern is most pronounced in smartphone assembly equipment refresh cycles, where OEMs now mandate specific SIL ratings rather than delegating safety architecture to machine builders.
Asia Pacific Safety Drives and Motors Market Segmentation
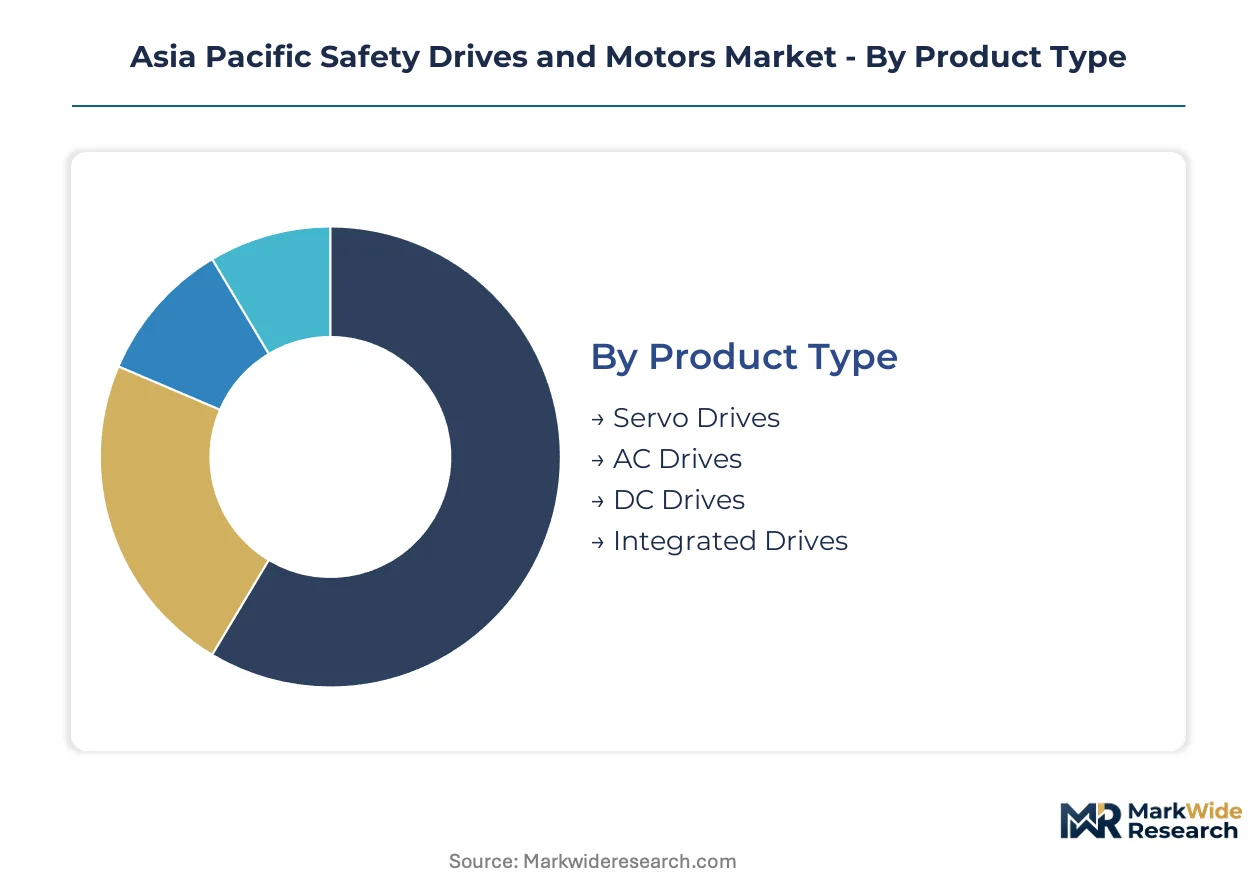
Segmentation in the Asia Pacific safety drives and motors market reveals distinct procurement cycles across product architectures and end-use sectors. Cycle times vary from 18-month refresh intervals in electronics manufacturing to 7-10 year replacement horizons in heavy process industries, shaping inventory and certification strategies for suppliers.
Product Type:
Cycle times diverge sharply across drive architectures, with integrated platforms turning over fastest as smart factory retrofits accelerate, while DC drive replacements lag in legacy industrial infrastructure.
- Servo Drives:Precision motion systems with SIL 3-certified safe torque-off circuits and sub-millisecond response times dominate battery electrode coating lines in Thailand and Indonesia. Demand concentrates in automotive electrification facilities where 200+ meter-per-minute production speeds mandate closed-loop safety feedback.
- AC Drives:Variable frequency platforms with energy recovery capabilities anchor process control installations across chemical and food processing plants. China's Yangtze River Delta industrial cluster absorbs the largest procurement volumes as MIIT smart factory mandates enforce GB-compliant safety equipment.
- DC Drives:Legacy architectures persist in metals processing and crane applications where high-torque startup requirements resist AC conversion economics.
- Integrated Drives:Single-platform solutions collapsing control and safety functions command premium positioning in greenfield collaborative robotics deployments across Vietnam and Malaysia.
AC drives dominate installed base across Asia Pacific process industries. Integrated drives represent where expansion concentrates as manufacturers consolidate panel architectures.
End User:
Cost tier stratification separates premium-specification aerospace and robotics procurement from price-sensitive manufacturing automation, with automotive occupying the intermediate value band.
- Manufacturing:General industrial automation spans packaging machinery, textile production, and assembly operations with mixed safety integrity requirements. Electronics contract manufacturers in Malaysia and Vietnam drive mid-tier servo volume as they retrofit for collaborative robot compatibility.
- Automotive:Stamping and welding line retrofits in Toyota City and Nagoya corridors generate concentrated demand spikes ahead of METI's JIS B 9700 enforcement deadlines. Battery gigafactory construction across Southeast Asia absorbs SIL 3-certified axes for cell assembly.
- Aerospace:Precision positioning systems with PLe-certified feedback loops serve airframe assembly and component machining in tier-one supplier facilities.
- Robotics:Force-limiting control modes and STO-capable drives enable human-robot interaction without physical guarding in smartphone assembly equipment refresh cycles.
Manufacturing commands the broadest installed base. Robotics is climbing the fastest as collaborative automation penetrates electronics assembly.
Technology:
Volume concentration favors variable frequency platforms in process industries, while digital servo architectures capture margin in precision motion applications.
- Variable Frequency Drive:Energy-efficient motor control with regenerative braking dominates pump, fan, and compressor applications across chemical processing and HVAC systems. China's Pearl River Delta food and beverage plants specify these platforms for GB standard compliance.
- Digital Servo Drive:High-resolution encoder feedback with real-time Ethernet connectivity serves multi-axis robotics and semiconductor manufacturing equipment. South Korean and Taiwanese vendors now ship STO-capable variants at standard drive price points.
- Closed Loop Drive:Dual-channel feedback architectures with external safety module compatibility persist in legacy machine tool retrofits requiring PLe certification.
- Soft Starter:Reduced-voltage starting for high-inertia loads minimizes mechanical stress in conveyor and pump applications with lower safety integrity requirements.
Variable frequency drive technology anchors process industry installations. Digital servo drive platforms are gaining share fastest as single-chip safety processors collapse cost barriers.
Application:
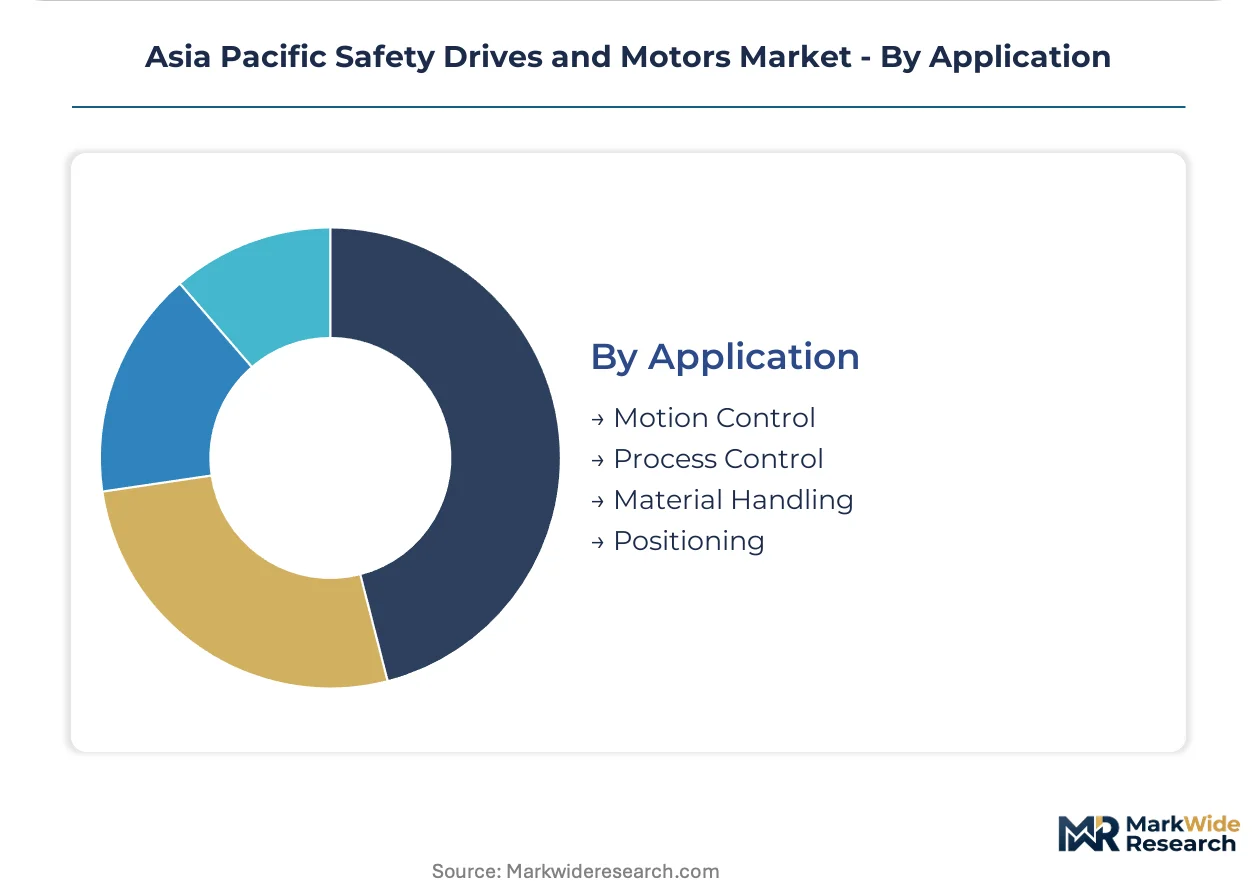
Application scope determines safety integrity level requirements, with motion control demanding the highest certification grades and material handling occupying the broadest volume tier.
- Motion Control:Multi-axis coordinated positioning with IEC 61800-5-2 safety motion certification serves precision robotics and CNC machining centers. Australian iron ore operations in Western Australia specify AS 4024-compliant systems for autonomous haulage retrofits.
- Process Control:Continuous regulation of flow, temperature, and pressure dominates chemical, pharmaceutical, and food processing installations with SIL 2 typically sufficient.
- Material Handling:Conveyor, crane, and automated storage systems span the widest end-use footprint with variable safety requirements from standard drives to SIL 3-certified servo axes.
- Positioning:Precision linear and rotary positioning with force feedback enables collaborative robot applications in electronics assembly without hard guarding.
Material handling commands the widest installed base penetration. Motion control is expanding most quickly as automotive and battery manufacturing automate precision operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-resolution encoders and safety-certified processors shapes procurement patterns across Asia Pacific, with regional manufacturers balancing foreign component sourcing against domestic assembly expansion to capture value within national industrial programs.
China
Battery gigafactory construction in the Yangtze River Delta absorbs SIL 3-certified servo axes for electrode coating lines operating above 200 meters per minute. MIIT smart factory mandates enforce GB standard compliance for automation equipment entering domestic programs. Shenzhen and Dongguan electronics manufacturers are disintermediating long-term vendor contracts to specify certified safety components directly in capital expenditure tenders.
Japan
Automotive stamping line retrofits in Toyota City and Nagoya corridors generate concentrated demand ahead of METI's JIS B 9700 enforcement deadline. The Robot Revolution Initiative mandates ISO 10218 alignment for collaborative robot safety standards by 2026. Domestic servo manufacturers are recertifying product lines for force-limiting control modes to maintain position in home-market automotive supply chains.
South Korea
Mid-tier servo vendors now ship STO-capable drives at standard drive price points, pressuring established European suppliers on cost-sensitive packaging machinery. The country's national industrial technology regulator promotes IEC 61800-5-2 adoption in smart manufacturing zones. Busan-Ulsan industrial corridors concentrate electronics contract manufacturing facilities retrofitting for collaborative robot compatibility.
Thailand
Battery cell assembly operations for regional electric vehicle supply chains require certified motion systems with sub-millisecond safe torque-off response. The Board of Investment incentives for advanced manufacturing attract safety drive vendors establishing local assembly presence. Eastern Economic Corridor industrial estates concentrate automotive electrification facilities specifying PLe-certified feedback architectures.
Australia
Western Australian iron ore operations drive replacement demand for legacy contactor-based safety systems under AS 4024 compliance requirements. Autonomous haulage retrofits specify motion control platforms with IEC 61800-5-2 safety motion certification. Perth-based mining equipment integrators face extended commissioning timelines due to certified functional safety engineer scarcity.
Asia Pacific Safety Drives and Motors Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform providers while fragmenting at the component tier as single-chip safety processors collapse traditional hardware barriers. German and Swiss automation conglomerates anchor premium positioning through bundled control-safety ecosystems. Mid-tier Asian fabricators compete on cost-optimized STO-capable architectures. Dominant competitive moves include unbundling safety offerings from legacy premium pricing and establishing localized assembly to capture production-linked incentive schemes.
Among European-headquartered automation conglomerates, Siemens AG and ABB Limited exemplify the integrated platform archetype, leveraging control ecosystem lock-in across German-affiliated manufacturing plants. Pilz GmbH & Co. KG occupies a specialist position within the configurable safety controller segment, extending compatibility across third-party servo platforms. These three entities represent distinct strategic postures: ecosystem bundling, machinery-optimized drive lines, and safety-centric interoperability architectures.
| Leading Market Players |
|---|
| Rockwell Automation, Inc. |
| ABB Limited |
| Siemens AG |
| Pilz GmbH & Co. KG |
| SIGMATEK GmbH & Co KG |
| Beckhoff Automation GmbH & Co. KG |
| B&R Industrial Automation GmbH |
| Kollmorgen |
| Hoerbiger India Precision Technology Private Ltd |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion and Shanghai-Ningbo freight differentials compress margins for European safety drive imports while amplifying price premiums on SIL 3-certified servo systems. This logistics friction concentrates procurement power among domestic Chinese assemblers who can bypass transoceanic cost layers, forcing incumbent suppliers to unbundle safety functionality from legacy premium positioning.
Pricing Analysis
Next-generation STO-embedded silicon architectures trade at 15-20% discount to external safety module configurations, while prior-generation relay-based systems face accelerated obsolescence discounts. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61800-5-2 certified integrated platforms from SIL 2 discrete configurations and uncertified standard drives. Cost compression in mid-tier servo segments intensifies because South Korean and Taiwanese vendors now ship STO-capable units at standard drive price points. Electronics contract manufacturers in Vietnam and Malaysia exhibit highest price sensitivity, while Australian mining operators show lowest due to AS 4024 compliance mandates and autonomous haulage uptime requirements.
Supply Chain Analysis
Neodymium and dysprosium processing draws from Chinese rare earth refining concentration, while high-resolution optical encoder manufacturing rests on German and British supplier dominance. Permanent magnet servo motors hinge on Chinese feedstock for rare earth elements, and safety-certified processors sources from Taiwanese foundry capacity. Single-source vulnerability in dual-channel encoder supply creates structural risk for PLe-certified feedback loop availability. Distribution runs through German-affiliated system integrators in China, direct OEM procurement channels in Japan, and mining equipment specialists in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific safety drives and motors market sits in early-cycle expansion as collaborative robotics penetration in electronics assembly accelerates retrofit demand beyond traditional automotive and process industry boundaries.
For Market Incumbents: Pre-empt margin erosion from silicon-embedded STO commoditization by accelerating unbundling of safety software licenses from hardware premiums. Establish captive assembly in Thailand's Eastern Economic Corridor to capture Board of Investment incentives and defend against South Korean cost-positioned entrants. Prioritize TÜV Rheinland certification pipeline investment to address certified functional safety engineer scarcity extending commissioning timelines. For New Entrants and Emerging Players: India's automotive and electronics PLI schemes represent the most penetrable geographic underpenetration for safety drive vendors establishing local assembly presence. Target mid-tier packaging machinery in ASEAN food processing plants where STO-capable drives at standard price points displace legacy relay configurations. Pursue direct specification relationships with Pearl River Delta smartphone OEMs who now unbundle safety component procurement from long-term automation vendor contracts. For Investors and Strategic Acquirers: Configurable safety controller specialists with third-party servo compatibility command premium positioning as integrated architectures fragment legacy standalone relay markets. Single-chip safety processor developers enabling tier-two manufacturers to compete on certified architectures without dedicated safety PLC hardware represent the most attractive acquisition target archetype. Monitor FSoE adoption rates in South Korean smart manufacturing zones as inflection indicator for premium service revenue potential from AI-powered predictive maintenance convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Establishment | Captures India's PLI schemes and Thailand's Board of Investment incentives for advanced manufacturing. |
| Single-Chip Safety Processor Development | Collapses cost barrier between standard and safety-rated motion control for tier-two manufacturers. |
| FSoE Platform Integration | Opens predictive maintenance service revenue as EtherCAT safety convergence accelerates in Korean zones. |
| TÜV Certification Pipeline Investment | Addresses functional safety engineer scarcity extending commissioning timelines across Southeast Asia. |
| Direct OEM Procurement Channel | Exploits Pearl River Delta electronics manufacturers unbundling safety drive specification from integrators. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at battery gigafactories, procurement leads at automotive Tier 1 suppliers, aftermarket service heads at mining equipment integrators, and safety system architects at collaborative robot OEMs. Secondary validation drew from MIIT smart factory program disclosures, METI Robot Revolution Initiative documentation, AS 4024 compliance registries, SEC filings of listed automation conglomerates, and customs trade data for encoder and servo drive imports. Bottom-up unit economics triangulated against top-down industrial automation capex forecasts to anchor volume and value estimates.
Calibration against historical adoption curves for IEC 61800-5-2 certification and JIS B 9700 alignment timelines shaped trajectory assumptions across the projection horizon. Segmentation modeling incorporated drive architecture type, safety integrity level tier, end-use sector intensity, and regional regulatory cluster divergence. CAGRs were derived from installed base replacement cycles varying from 18-month electronics refresh intervals to 7-10 year heavy process industry horizons, cross-referenced against MIIT and METI enforcement deadline impacts.
The forecast holds incumbent behavior within observed patterns; aggressive unbundling moves by European ecosystem vendors or accelerated rare earth magnet price volatility would shift outcomes beyond modeled ranges. Cross-checking against TÜV Rheinland certification database growth rates and FSoE node deployment statistics in Korean manufacturing zones is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Global Sliding Vane Air Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
China AC Motor Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Global Induction Motors Market