
 West Africa Oil and Gas Midstream Market | 2026-2036
West Africa Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Oil and Gas Midstream Market Analytics
Pipeline corridors linking Niger Delta production to coastal export terminals is fragmenting as new entrants challenge incumbent throughput arrangements. Chevron Corporation leverages its Escravos-Lagos infrastructure to sustain captive export capacity. TotalEnergies SE anchors West African LNG offtake through its Greater Tortue development. Royal Dutch Shell PLC navigates divestment of onshore pipelines while competing for deepwater trunk line contracts.
The West Africa oil and gas midstream sector encompasses transportation, storage, and processing infrastructure operating between upstream extraction points and downstream refineries, typically handling crude at 0.5-2.0 million barrels per day throughput rates and managing natural gas through compression stations at 1,000-5,000 psi. Its primary commercial purpose is to aggregate, condition, and deliver hydrocarbons to export markets and domestic refineries with minimal loss and defined custody transfer specifications. Pipeline infrastructure dominates capital allocation across the technology dimension, while LNG terminal capacity represents the fastest-growing segment as Mauritania-Senegal basin discoveries seek export outlets. Storage facilities command disproportionate margin pools due to tankage scarcity in the Lagos-Abidjan coastal band and associated blending revenue opportunities.
Nigeria's Department of Petroleum Resources enforces pipeline integrity standards that mandate pressure testing and corrosion monitoring, effectively raising compliance costs for older trunk line operators. Ghana's Petroleum Commission regulates terminal construction permits, shaping investment timelines for Tema and Takoradi expansion projects. Côte d'Ivoire's national hydrocarbon code, administered by Petroci's regulatory arm, governs storage licensing and third-party access terms. Stakeholders must weigh stranded asset risk against the region's proven undeveloped reserves when committing to multi-decade infrastructure contracts.
Market Dynamics
Floating storage and regasification technology is fragmenting traditional throughput arrangements across Niger Delta-to-coastal corridors, forcing incumbent pipeline operators to renegotiate offtake terms with new storage entrants.
Growth Catalysts
- FSRU deployment:Floating regasification units are unlocking stranded gas discoveries in Mauritania-Senegal basins without requiring onshore terminal construction.
- Nigeria's DPR integrity mandates:Pressure testing and corrosion monitoring requirements are accelerating replacement of aging Escravos-Lagos trunk segments.
- LNG export terminal expansion:Greater Tortue development is anchoring new offtake agreements for deepwater gas aggregation.
Market Restraints
- Scarce tankage in Lagos-Abidjan band:Coastal storage capacity constraints limit blending revenue capture for product arbitrage traders.
- Legacy pipeline metallurgy:Pre-1990 carbon steel infrastructure suffers accelerated corrosion rates in Niger Delta swamp conditions.
- Domestic refining underutilization:Nigerian refineries operate below nameplate capacity, forcing continued crude export dependence.
Strategic Opportunities
- Port Harcor coastal terminal upgrades:Rehabilitation of Warri and Calabar facilities offers third-party access revenue streams.
- Compression station automation:Integration of SCADA systems with drone-based leak detection reduces unplanned shutdown intervals.
- Ghana Petroleum Commission permitting:Streamlined Tema and Takoradi construction approvals are compressing project development timelines.
Industry Challenges
- Weld integrity certification:API 1104 compliance timelines for in-service pipelines extend maintenance windows and defer throughput gains.
- Specialized inspection labor:Magnetic flux leakage and ultrasonic testing expertise concentrates with aging technician cohorts in Lagos-Port Harcourt corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Oil and Gas Midstream Market |
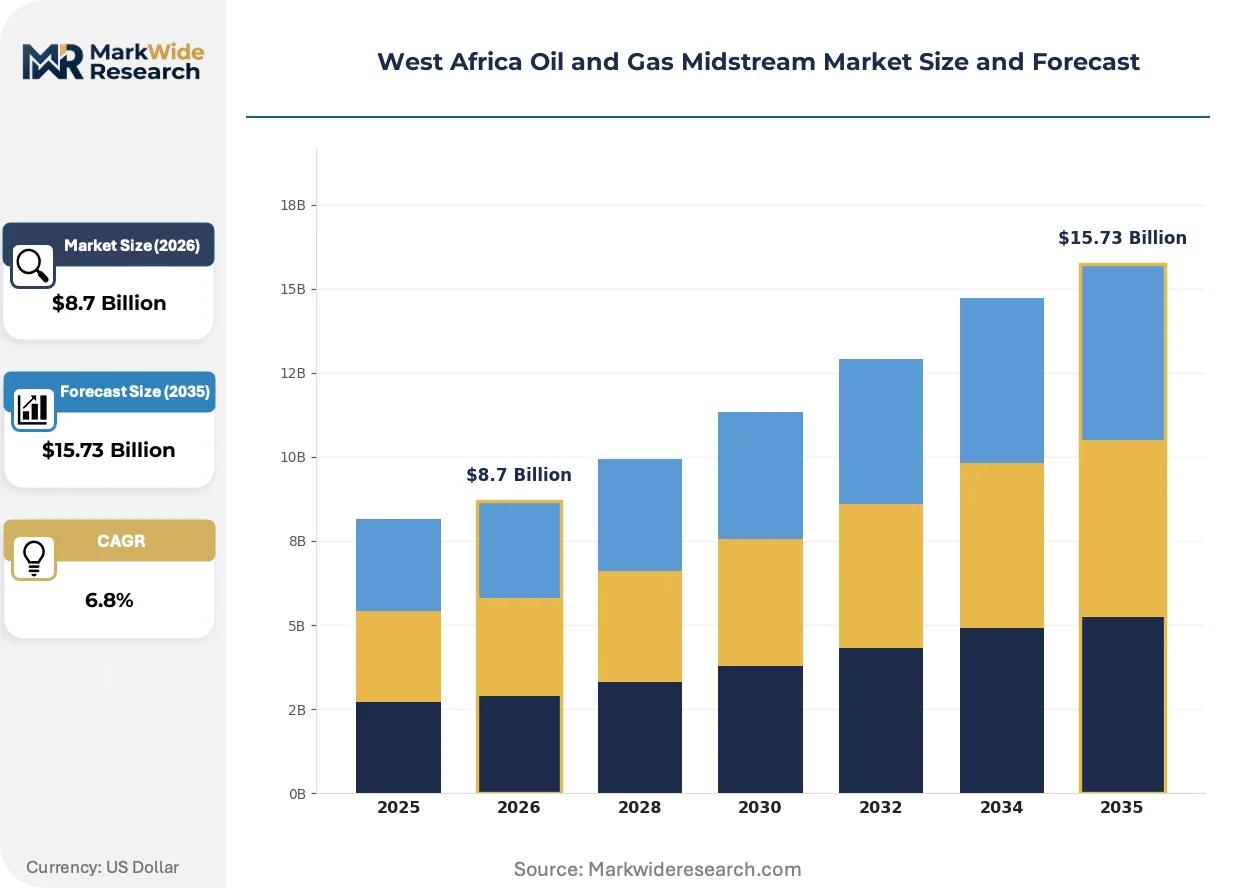
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Trading, Processing Technology: Pipeline, Terminal, LNG, Depot End User: Exploration Companies, Refiners, Distributors, Marketers Infrastructure: Refineries, Terminals, Piping Networks, Storage Facilities |
| Companies Covered | Chevron Corporation, PetroChina, Nigerian National Petroleum Corporation, Valero Energy, TotalEnergies SE, Royal Dutch Shell PLC, Societe Nationale d'Operations Petrolieres de la Cote d'Ivoire (Petroci), Imperial Oil, Eni SpA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Oil and Gas Midstream Market Evolving Landscape
Digital infrastructure is compressing custody transfer verification cycles while regulatory pressure on methane intensity forces sensor deployment across compression and storage nodes. These shifts are reconfiguring capital allocation between hardware replacement and data architecture.
Drone-based pipeline surveillance combined with fiber-optic leak detection is digitizing integrity management for Escravos-Lagos and trans-Niger lines. Midstream operators in the Niger Delta are deploying these systems to satisfy DPR monitoring mandates while reducing helicopter patrol costs. The technology is digitizing how pressure anomalies translate into maintenance dispatch decisions, compressing response windows from days to hours.
Nigeria's Department of Petroleum Resources is tightening pipeline integrity standards through mandatory pressure testing protocols and corrosion monitoring schedules. These rules elevate compliance costs for trunk line operators with pre-2000 vintage infrastructure. Older system owners are responding by segmenting networks into priority replacement corridors versus monitored-deferral segments.
Buyers are unbundling storage and throughput contracts that previously locked in multi-year commitments with single operators. Trading houses in the Lagos-Abidjan corridor now procure tankage and pipeline capacity separately, optimizing arbitrage timing. This pattern is most visible among Nigerian product importers seeking blending flexibility ahead of regional specification changes.
West Africa Oil and Gas Midstream Market Segmentation
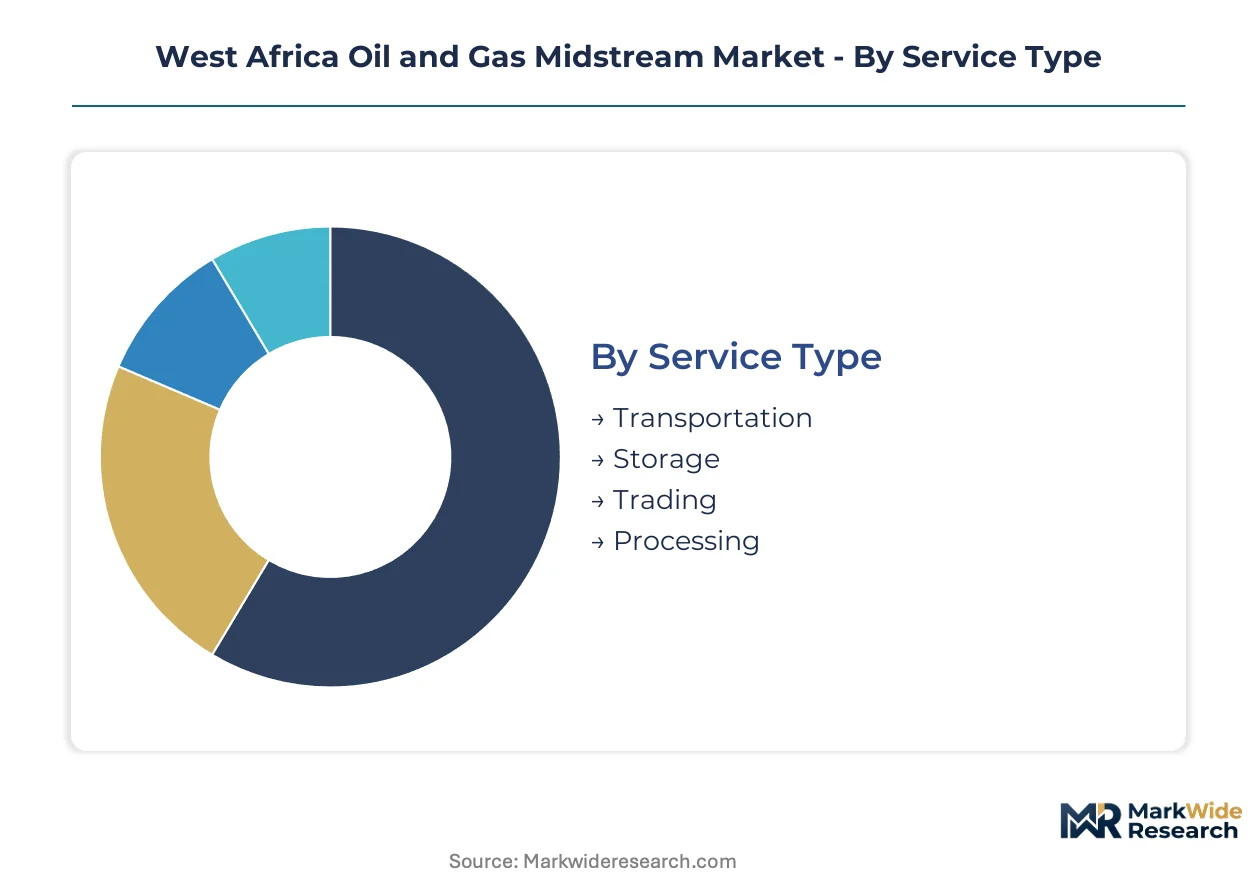
Midstream service differentiation in West Africa hinges on maintenance intensity and operational continuity requirements. Equipment reliability contracts and emergency response capabilities separate premium providers from commodity competitors across pipeline and terminal operations.
Service Type:
After-sales service intensity varies sharply across these operational categories, with transportation infrastructure demanding continuous surveillance and storage assets requiring periodic refurbishment cycles.
- Transportation:Pipeline and marine logistics services move crude and products between production fields, coastal terminals, and import facilities. Nigerian trunk line operators in the Escravos-Lagos corridor absorb the highest maintenance burden due to DPR-mandated integrity testing and swamp corrosion conditions.
- Storage:Tankage and underground cavern facilities provide buffer capacity for cargo scheduling and blending operations. Demand concentrates in the Lagos-Abidjan coastal band where tankage scarcity creates arbitrage opportunities for product specification management.
- Trading:Commercial intermediation and offtake arrangement services connect production to end markets. Ghana Petroleum Commission licensing requirements shape contract structures for Tema and Takoradi terminal access.
- Processing:Conditioning, blending, and treatment services prepare hydrocarbons for custody transfer. Compression station automation in Niger Delta fields reduces unplanned shutdown intervals.
By volume, Transportation leads. By growth pace, Storage is ahead.
Technology:
Capital deployment intensity distinguishes these infrastructure modalities, with LNG terminals requiring front-loaded investment and pipelines spreading expenditure across decades of integrity maintenance.
- Pipeline:Steel trunk lines and gathering systems operate at 1,000-5,000 psi compression ratings across Niger Delta production corridors. Replacement demand accelerates for pre-1990 carbon steel segments failing DPR corrosion monitoring standards.
- Terminal:Coastal loading and discharge facilities handle vessel traffic at export and import points. Warri and Calabar rehabilitation projects in Nigeria's Port Harcourt corridor offer third-party access revenue streams.
- LNG:Liquefaction trains and regasification infrastructure anchor deepwater gas development. Floating regasification units unlock Mauritania-Senegal basin discoveries without onshore construction timelines.
- Depot:Product distribution terminals and inland storage facilities serve retail and commercial fuel markets. Lagos-Abidjan corridor constraints limit blending flexibility for Nigerian product importers.
By installed base, Pipeline dominates. By expansion trajectory, LNG climbs fastest.
End User:
Contract sophistication and creditworthiness profiles segment these customer categories, with international exploration companies commanding standardized terms and local distributors negotiating flexible delivery schedules.
- Exploration Companies:Upstream producers require gathering systems and export capacity for field development. Deepwater trunk line contracts in Nigeria attract competition between incumbent operators and new entrants.
- Refiners:Processing facilities need feedstock delivery and product offtake infrastructure. Nigerian refineries operating below nameplate capacity force continued crude export dependence.
- Distributors:Wholesale product marketers procure storage and throughput capacity separately. Unbundled contracting patterns optimize arbitrage timing ahead of regional specification changes.
- Marketers:Retail-facing entities manage last-mile logistics and depot access. Côte d'Ivoire's Petroci regulatory arm governs storage licensing terms for third-party access.
By contract value, Exploration Companies lead. By volume growth, Distributors pull ahead.
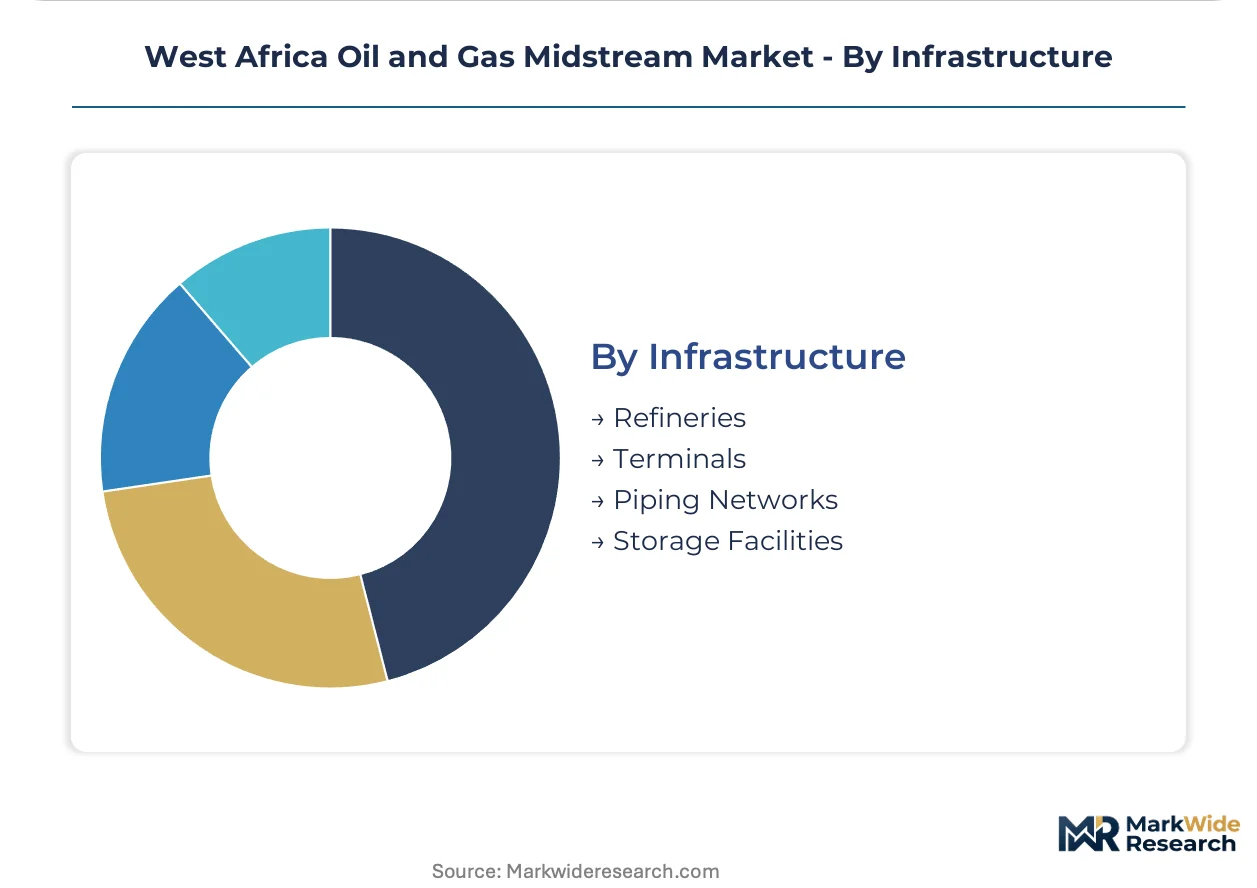
Infrastructure:
Asset life cycles and replacement economics shape investment priorities across these physical categories, with piping networks demanding sustained maintenance spend and greenfield terminals offering greenfield margin structures.
- Refineries:Downstream processing complexes convert crude to refined products. Domestic underutilization in Nigeria sustains regional crude export flows.
- Terminals:Marine and coastal handling facilities manage vessel loading and cargo storage. Ghana's Tema and Takoradi expansion projects compress development timelines through streamlined permitting.
- Piping Networks:Interconnected pipeline systems aggregate production to export points. API 1104 weld integrity certification extends maintenance windows for in-service lines.
- Storage Facilities:Tank farms and caverns provide inventory buffer and blending capability. Coastal scarcity in the Lagos-Abidjan band commands disproportionate margin pools.
By capital employed, Piping Networks lead. By margin expansion, Storage Facilities gain fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's Department of Petroleum Resources pipeline integrity mandates are accelerating infrastructure replacement across coastal corridors. Ghana's Petroleum Commission streamlined permitting compresses project timelines at Tema and Takoradi. Côte d'Ivoire's national hydrocarbon code revisions govern third-party storage access terms.
Nigeria
Lagos-Port Harcourt corridor demand concentrates around Escravos-Lagos trunk line rehabilitation and Warri terminal upgrades. The Department of Petroleum Resources enforces pressure testing and corrosion monitoring standards that raise compliance costs for pre-2000 vintage infrastructure. Port Harcourt coastal terminals absorb the bulk of sector investment as Nigerian National Petroleum Corporation expands offtake arrangements.
Ghana
Tema and Takoradi expansion projects drive demand for marine loading facilities and product storage capacity. The Petroleum Commission regulates terminal construction permits, shaping investment timelines for coastal infrastructure. Accra-Tema industrial zone anchors LNG import terminal development as floating regasification technology unlocks gas supply.
Côte d'Ivoire
Abidjan storage scarcity creates arbitrage opportunities for product specification management and blending operations. Petroci's regulatory arm administers storage licensing and third-party access terms under the national hydrocarbon code. San Pedro coastal terminal development attracts investment for regional cargo handling capacity.
Mauritania-Senegal Basin
Deepwater gas discoveries seek export outlets through floating storage and regasification unit deployment. Greater Tortue development anchors LNG offtake agreements for regional gas aggregation. Nouakchott-Dakar coastal corridor positions for breakbulk terminal investment as basin production scales.
Cameroon
Kribi deepwater port infrastructure supports regional crude export diversification from traditional Niger Delta routes. National hydrocarbon regulatory frameworks govern pipeline corridor development to coastal terminals. Douala-Yaoundé industrial corridor concentrates demand for product storage and distribution depot capacity.
West Africa Oil and Gas Midstream Market Competitive Landscape
On the supply side, the industry is consolidating around integrated majors with captive infrastructure and specialized national oil companies with regulatory proximity. International exploration companies compete for deepwater trunk line contracts against incumbent pipeline operators. Two strategic archetypes dominate: vertically integrated majors leveraging legacy Escravos-Lagos networks, and state-affiliated entities capturing domestic terminal access. Competitive moves concentrate on portfolio divestment of onshore exposure and FSRU partnership structures for basin-agnostic gas monetization.
Among integrated majors, Chevron Corporation and TotalEnergies SE exemplify infrastructure-led competitive positioning. Chevron anchors West African midstream presence through Escravos-Lagos corridor control. TotalEnergies occupies a position at the LNG export terminal expansion frontier via Greater Tortue development. Royal Dutch Shell PLC represents the divestment archetype, navigating onshore pipeline exit while competing for deepwater trunk line awards.
| Leading Market Players |
|---|
| Chevron Corporation |
| PetroChina |
| Nigerian National Petroleum Corporation |
| Valero Energy |
| TotalEnergies SE |
| Royal Dutch Shell PLC |
| Societe Nationale d'Operations Petrolieres de la Cote d'Ivoire (Petroci) |
| Imperial Oil |
| Eni SpA |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoint exposure through Nigeria's DPR integrity mandates determines both compression station pricing spreads and supply chain shape across the Escravos-Lagos corridor. Pre-2000 vintage infrastructure owners face tiered compliance costs that segment pricing power between rehabilitated trunk lines and monitored-deferral segments.
Pricing Analysis
Certification level under API 1104 weld integrity standards creates the primary spread between premium and standard pipeline access tiers. Contract-based long-term offtake agreements dominate, with price differentiation driven by corrosion monitoring compliance status and compression automation integration. Cost compression in standard-tier throughput is intensifying because FSRU deployment offers basin-agnostic alternatives to fixed infrastructure. Nigerian product importers in the Lagos-Abidjan band show highest price sensitivity due to unbundled storage and throughput procurement patterns.
Supply Chain Analysis
Specialized inspection labor concentration in the Lagos-Port Harcourt corridor anchors fabrication and maintenance capacity for compression station components. Raw material dependencies center on high-grade carbon steel for trunk line replacement, SCADA control systems for automation retrofit, and specialized welding consumables for swamp-condition integrity. Single-source vulnerability concentrates with aging magnetic flux leakage and ultrasonic testing technician cohorts. Distribution runs through coastal terminal operators with third-party access licensing under Ghana Petroleum Commission and Petroci regulatory frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by floating regasification technology unlocking stranded Mauritania-Senegal basin reserves. Infrastructure replacement cycles and LNG export terminal expansion create overlapping investment windows.
For Market Incumbents: Harden Escravos-Lagos corridor control through backward integration into drone-based surveillance and fiber-optic leak detection systems. Segment pre-2000 vintage networks into priority replacement corridors versus monitored-deferral segments to manage DPR compliance cost exposure. Capture FSRU partnership structures to defend against basin-agnostic gas monetization entrants.
For New Entrants and Emerging Players: Ghana's Tema-Takoradi terminal expansion offers white-space access through streamlined Petroleum Commission permitting timelines. Mauritania-Senegal basin floating regasification deployment presents second-mover LNG aggregation opportunities without onshore construction timelines. Target third-party storage licensing under Côte d'Ivoire's Petroci regulatory framework for Abidjan blending arbitrage positioning.
For Investors and Strategic Acquirers: The market sits at an infrastructure replacement phase that favors specialized national oil companies with regulatory proximity over pure-play international operators. Long-term viability across the analysis window hinges on portfolio exposure to deepwater trunk line contracts versus stranded onshore pipeline assets. Monitor DPR enforcement intensity on pre-1990 carbon steel integrity as inflection signal for accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| FSRU Partnership Structuring | Floating regasification units unlock Mauritania-Senegal basin discoveries without onshore terminal construction timelines. |
| Pipeline Integrity Automation | SCADA integration with drone surveillance compresses DPR-mandated maintenance dispatch windows from days to hours. |
| Third-Party Terminal Access Licensing | Petroci and Ghana Petroleum Commission frameworks create revenue streams from Warri and Calabar facility rehabilitation. |
| Compression Station Retrofit | Automation reduces unplanned shutdown intervals across Niger Delta production corridors. |
| Coastal Storage Capacity Expansion | Tankage scarcity in the Lagos-Abidjan band commands disproportionate blending margin pools. |
Research Methodology
A standing panel of pipeline integrity engineers, terminal operations managers, EPC contractors, and regulatory compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from Nigerian Department of Petroleum Resources enforcement records, Ghana Petroleum Commission permitting databases, customs and trade data for equipment imports, and SEC filings from integrated majors with West African midstream exposure. Bottom-up project pipeline assessment triangulated against top-down regional infrastructure investment tracking.
Scenario-bracketing around DPR enforcement intensity and FSRU deployment pace shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include service type, technology modality, end user contract sophistication, and infrastructure asset life cycle position. CAGRs derived from capacity utilization trajectories and replacement investment schedules. Industry-specific forecast inputs incorporated floating regasification unit deployment timelines and trunk line integrity testing compliance rates.
Practitioners should monitor DPR penalty enforcement patterns and FSRU charter rate movements for early signals of infrastructure investment inflection. Quarterly review of pipeline replacement contract awards and LNG terminal construction permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
North America Shale Market