
 Centrifugal Water Pump Market | 2026-2036
Centrifugal Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Water Pump Market Intelligence
Aftermarket service revenue from maintenance and digital monitoring solutions is reshaping competitive positioning among pump manufacturers. Grundfos Holding A/S leverages its extensive service network to capture this value stream. Xylem Inc. competes through its portfolio of smart water technologies and integrated analytics platforms. KSB SE & Co. KGaA differentiates with specialized engineering support for complex industrial and mining applications, securing long-term service contracts.
A centrifugal water pump converts rotational energy from a motor into kinetic energy in a fluid, utilizing a spinning impeller to accelerate water. The design of the volute casing then converts this velocity into higher pressure for transfer through a piping system. End-suction pumps dominate the market in volume due to their versatility in commercial buildings and HVAC systems. The multi-stage pump category, however, represents a significant margin pool, especially in high-pressure municipal water supply and industrial boiler feed applications.
Energy efficiency mandates, such as the EU's Ecodesign Directive and standards set by the US Department of Energy, dictate minimum performance levels for motors and hydraulic systems. Concurrently, regulations from bodies like the US EPA on water quality and China's MEE on industrial discharge influence material choices to prevent contamination and ensure durability. Future success depends on manufacturers' ability to integrate IoT connectivity for predictive maintenance without substantially increasing total cost of ownership.
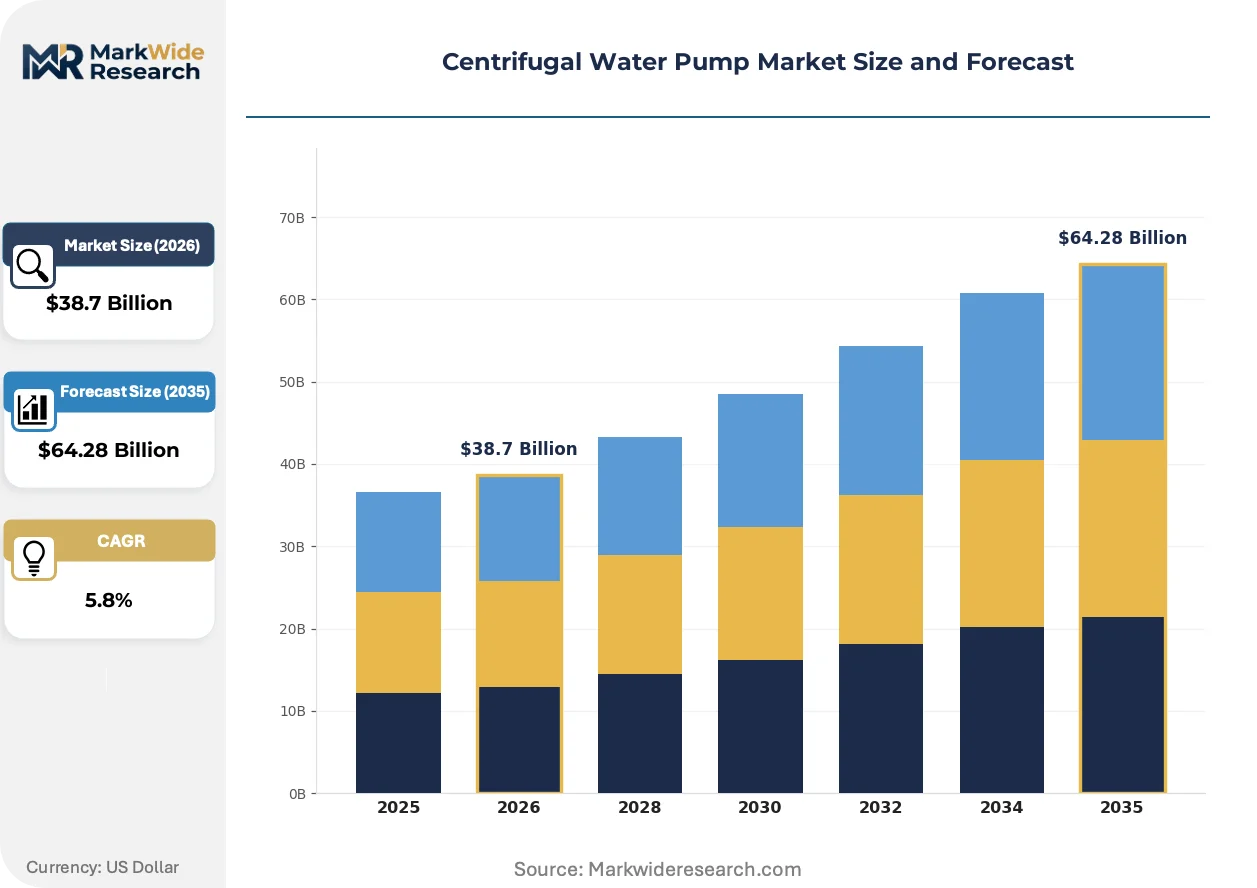
Market Dynamics
The convergence of energy efficiency mandates and digital service models is the central force defining the market. Regulations like the EU's Ecodesign Directive compel hardware innovation while IoT creates new revenue streams from aftermarket services.
Growth Catalysts
- Government Infrastructure Investment:National programs in India funding water and wastewater treatment create large-scale demand for pumps in municipal and agricultural applications.
- Agricultural Modernization:A global shift to efficient irrigation systems requires reliable high-pressure water transfer, boosting demand for multi-stage centrifugal pumps.
- Ecodesign Mandates:The EU's Ecodesign Directive and US DOE standards compel the adoption of higher-efficiency pump systems, accelerating equipment replacement cycles.
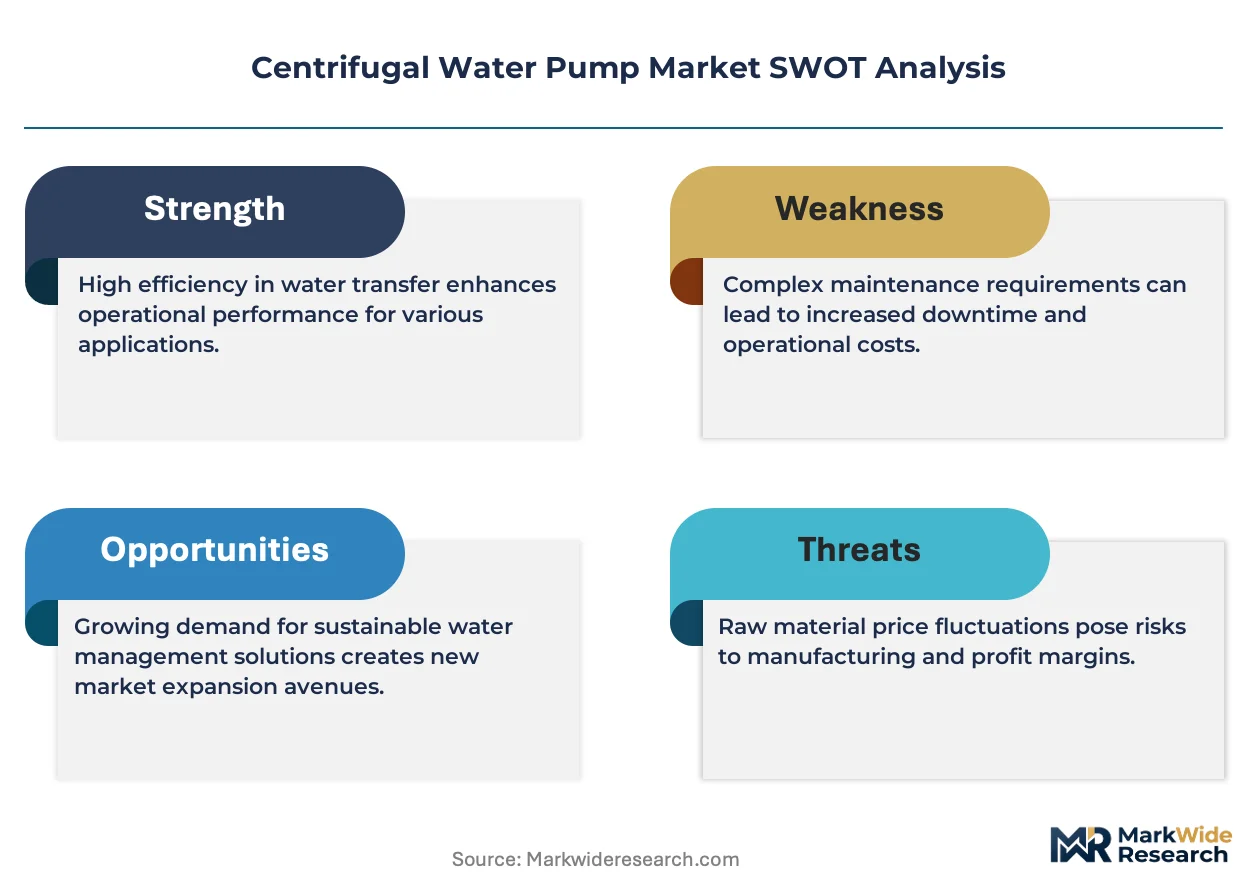
Market Restraints
- High Initial Cost:The upfront capital for pumps with variable frequency drives deters adoption among cost-sensitive buyers, despite long-term operational savings.
- Material Cost Volatility:Price fluctuations in stainless steel and cast iron directly impact manufacturer margins and create pricing instability for end-users.
- Substitution in Niche Applications:Positive displacement pumps offer a competitive alternative in specific low-flow, high-pressure industrial processes, limiting the centrifugal pump's scope.
Strategic Opportunities
- Water Reuse and Desalination:Growing water scarcity drives investment in treatment plants, creating demand for specialized corrosion-resistant, high-pressure multi-stage pumps.
- Digital Twin Integration:Offering digital twin services for pump systems enables predictive maintenance, creating new high-margin revenue streams beyond hardware sales.
- Infrastructure in Africa:Underpenetrated markets in Sub-Saharan Africa represent a significant growth opportunity as municipal water and sanitation networks are developed.
Industry Challenges
- System Integration Complexity:Integrating new smart pumps with existing legacy SCADA systems and building automation platforms presents significant technical hurdles and interoperability challenges.
- Workforce Skill Gaps:A shortage of technicians skilled in both mechanical pump systems and digital analytics hinders the deployment and maintenance of smart water solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Water Pump Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: End-Suction, Split-Case, Vertical Multistage, Submersible, Self-Priming Technology: Single-Stage, Multi-Stage, Magnetic Drive, Air-Operated, Seal-Less Application: Municipal Water Supply, Irrigation Systems, Commercial Buildings, Mining, HVAC End User: Water Treatment Plants, Agricultural Operations, Real Estate Developers, Mineral Processing Plants, Cold Chain Facilities |
| Companies Covered | Grundfos Holding A/S, Flowserve Corporation, Xylem Inc., KSB SE & Co. KGaA, Sulzer Ltd, Wilo SE, ITT Inc., Ebara Corporation, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Water Pump Market Strategic Shifts & Innovations
The digitalization of mechanical assets is transforming operational models and value propositions in the centrifugal water pump sector. This shift moves the focus from standalone component sales toward integrated, data-driven system performance and lifecycle management.
Digital twin technology creates a dynamic virtual model of a physical pump or an entire water network. Large municipal utilities and industrial facilities are adopting this for advanced asset management and operational planning. The technology is virtualizing the pump's lifecycle, enabling performance simulation and predictive failure analysis without requiring physical system downtime.
Standards from the US Department of Energy dictate minimum pump efficiency levels across numerous centrifugal pump categories. This regulation forces manufacturers to invest in improved hydraulic design and more efficient motor technologies to remain compliant. The high-volume end-suction pump segment is most affected, leading to the phase-out of older, less efficient models from the market.
A notable behavioral shift involves end-users moving from one-time capital purchases to performance-based service contracts. This model disrupts traditional distribution channels, favoring manufacturers who can provide comprehensive lifecycle management and guaranteed uptime. The trend is most prominent in European industrial and municipal water sectors where operational expenditure predictability is highly valued.
Centrifugal Water Pump Market Segmentation
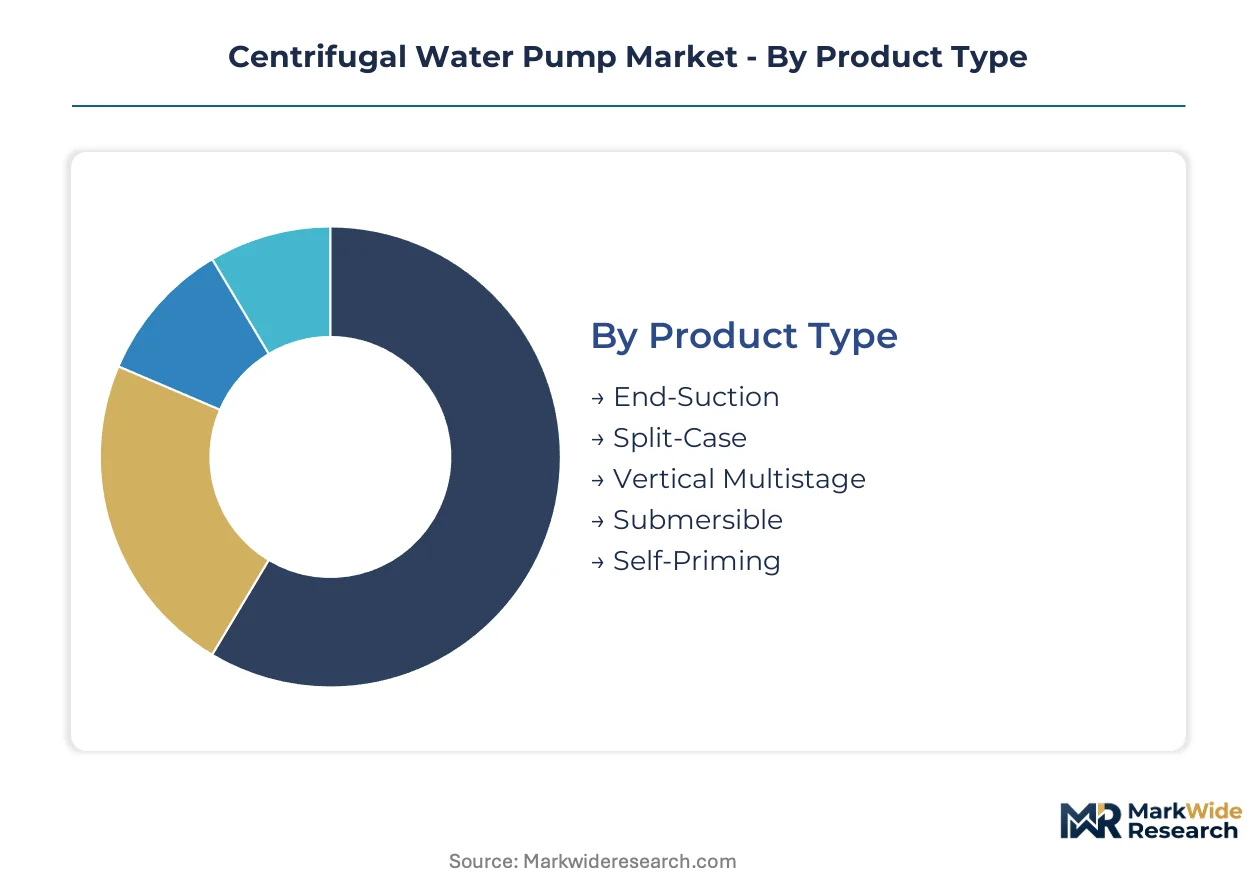
The centrifugal water pump market segmentation highlights the diverse operational requirements and technological preferences across various industries. Understanding these distinct segments allows manufacturers to tailor product development and service offerings to specific customer needs, optimizing market penetration and value capture.
Product Type:
The product type dimension delineates pump designs based on their hydraulic configuration and operational characteristics, impacting their suitability for different pressure and flow demands.
- End-Suction:These pumps feature a single impeller with an inlet on one side and an outlet at the top, offering cost-effectiveness and versatility for commercial buildings and HVAC systems. Demand concentrates in urban development projects, driven by new construction and facility upgrades.
- Vertical Multistage:Employing multiple impellers in series, these pumps generate high pressure, making them ideal for municipal water supply and industrial boiler feed applications. Their demand is increasing in India due to significant government investment in water infrastructure.
- Split-Case:The casing is split horizontally, allowing easy access to internal components for maintenance, commonly used in large-volume liquid transfer for industrial and municipal applications.
- Submersible:Designed to operate fully immersed in the fluid, these pumps are essential for well pumping, sewage handling, and dewatering in construction, offering efficiency by eliminating priming issues.
- Self-Priming:Equipped with a built-in reservoir that allows them to re-prime automatically after initial setup, these pumps find use in agricultural irrigation and construction sites where suction lift is required.
End-Suction pumps hold installed capacity. Vertical Multistage pumps are rotating up the share rankings.
Technology:
Technological distinctions define the core mechanical and operational principles governing centrifugal pump performance and efficiency in various fluid handling tasks.
- Multi-Stage:These pumps incorporate several impellers on a common shaft, enabling them to generate high discharge pressures suitable for municipal water distribution and high-rise building water supply. Demand is strong in agricultural modernization programs requiring efficient irrigation systems.
- Single-Stage:Featuring one impeller, these pumps are simpler in design and cost-effective, typically used for moderate flow and pressure applications in commercial and light industrial settings. Their versatility makes them a staple in HVAC systems across Europe.
- Magnetic Drive:Utilizing magnetic coupling to transmit power without a direct shaft seal, these pumps eliminate leakage and are preferred for hazardous, corrosive, or high-purity fluids in chemical processing.
- Air-Operated:These pumps use compressed air to drive a diaphragm, providing reliable operation in situations where electricity is unavailable or flammable liquids are present, often found in mining and construction.
- Seal-Less:Designed without traditional mechanical seals, these pumps prevent leakage and are ideal for sensitive or aggressive media in pharmaceutical manufacturing and specialized industrial applications.
Innovations in Multi-Stage technology are driving efficiency gains, while Single-Stage maintains its fundamental utility.
Application:
Market applications segment demand based on the specific end-use environment and the functional purpose of the centrifugal water pump within that context.
- Municipal Water Supply:Pumps are critical for extracting, treating, and distributing potable water to urban and rural populations, supporting public health and economic development. Government infrastructure investment in India creates substantial demand in this sector.
- Irrigation Systems:Centrifugal pumps facilitate the transfer of water from sources to agricultural fields, supporting crop growth and food security. The global shift towards efficient irrigation systems boosts demand for reliable high-pressure pumps.
- Commercial Buildings:Pumps manage water circulation for heating, ventilation, air conditioning (HVAC), and domestic water services within offices, hotels, and retail complexes. Energy efficiency mandates in the EU compel the adoption of higher-efficiency systems.
- Mining:Heavy-duty pumps are essential for dewatering mines, slurry transport, and process water circulation in mineral processing operations, requiring robust designs to handle abrasive fluids.
- HVAC:Dedicated pumps circulate chilled or hot water through cooling and heating systems in various structures, contributing to climate control and occupant comfort.
Municipal Water Supply continues to expand with infrastructure projects, and Irrigation Systems is experiencing renewed investment.
End User:
End-user categories group buyers by their operational needs and the organizational structure that procures and manages centrifugal water pump assets.
- Water Treatment Plants:These facilities utilize pumps for various stages of water purification, including intake, chemical dosing, filtration, and effluent discharge. Investment in water reuse and desalination drives demand for specialized pumps.
- Agricultural Operations:Farms and agribusinesses deploy pumps for irrigation, livestock watering, and drainage, supporting modern farming practices and yield optimization. Modernization programs in agriculture are accelerating pump adoption.
- Real Estate Developers:Responsible for constructing residential and commercial properties, these entities procure pumps for building services, including water supply, drainage, and HVAC systems.
- Mineral Processing Plants:These industrial sites use pumps for handling slurries, chemical solutions, and process water in the extraction and refinement of raw materials.
- Cold Chain Facilities:Pumps support refrigeration systems and water circulation for cooling in temperature-controlled warehouses and logistics hubs, crucial for preserving perishable goods.
Demand from Water Treatment Plants remains foundational, as Agricultural Operations show accelerated purchasing activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for centrifugal water pumps varies significantly across geographies. Industrial applications in mature economies prioritize long-term operational efficiency and digital integration. Developing markets often exhibit higher price sensitivity, focusing on initial capital expenditure for basic water infrastructure needs.
United States
Demand for centrifugal water pumps in the United States stems from commercial building HVAC systems and municipal water treatment upgrades. US Department of Energy standards dictate minimum efficiency levels for these systems. Major infrastructure projects in cities like Los Angeles and New York drive significant pump procurement.
Germany
Germany's demand for high-efficiency centrifugal water pumps is driven by stringent environmental regulations and industrial process optimization. The EU's Ecodesign Directive compels manufacturers to innovate in motor and hydraulic design. Industrial clusters in Bavaria and North Rhine-Westphalia integrate advanced pump systems for manufacturing.
India
India's centrifugal water pump market experiences substantial demand from expanding municipal water supply networks and agricultural modernization. Government investment in water and wastewater treatment infrastructure, such as the Jal Jeevan Mission, creates large-scale procurement. Agricultural regions like Maharashtra and Punjab adopt efficient irrigation systems, boosting pump sales.
China
China's market for centrifugal water pumps is influenced by rapid urbanization and industrial development, particularly in water and wastewater management. Regulations from China's MEE on industrial discharge drive demand for durable, efficient pumps. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta require pumps for process water and building services.
Japan
Japanese demand for centrifugal water pumps focuses on precision industrial applications and resilient urban infrastructure. Strict JIS standards ensure high quality and energy efficiency in pump systems. Major metropolitan areas like Tokyo and Osaka invest in advanced water management and climate control technologies.
Centrifugal Water Pump Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the centrifugal water pump market. The market exhibits a tiered structure, encompassing global industrial conglomerates, specialized regional manufacturers, and local assembly operations. Strategic archetypes include innovation-driven solution providers focusing on efficiency and cost-optimized volume producers serving basic infrastructure needs. Competitive moves center on portfolio diversification into digital services and strategic partnerships for IoT integration and expanded geographic reach.
Within the innovation-driven solution provider archetype, companies like Grundfos Holding A/S and Xylem Inc. operate. Grundfos Holding A/S, a Danish entity, exemplifies comprehensive lifecycle management through its extensive service network and digital offerings. Xylem Inc., a US-based corporation, represents the integration of smart water technologies and advanced analytics platforms for water management. KSB SE & Co. KGaA, a German industrial group, occupies a position focused on specialized engineering support for complex industrial and mining applications, securing long-term service contracts. These entities collectively anchor the premium segment, emphasizing digital capabilities, energy efficiency, and long-term operational value for end-users.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Flowserve Corporation |
| Xylem Inc. |
| KSB SE & Co. KGaA |
| Sulzer Ltd |
| Wilo SE |
| ITT Inc. |
| Ebara Corporation |
| Baker Hughes |
| Others |
Cost & Logistics Intelligence
Price volatility in stainless steel and cast iron directly impacts manufacturer margins in centrifugal water pumps. This material cost instability creates pricing instability for end-users, affecting project budgeting.
Pricing Analysis
Aftermarket service revenue from maintenance and digital monitoring solutions drives lifetime value for pump manufacturers. The market uses a hybrid pricing model, combining one-time capital purchases with performance-based service contracts, especially in European industrial and municipal sectors. Price differentiation stems from energy efficiency compliance and specialized engineering support for complex applications. High initial costs for advanced systems create pricing pressure, deterring cost-sensitive buyers, while municipal and industrial end-users value operational expenditure predictability.
Supply Chain Analysis
Sourcing of critical raw materials like stainless steel and cast iron forms the upstream feedstock for centrifugal pump manufacturing. Global supply of these materials concentrates in countries such as China and India, with specialized component production centered in Germany and Japan. The supply chain relies heavily on consistent availability of electric motors and precisely engineered impellers. Commodity price volatility represents a significant structural risk impacting manufacturer margins, while distribution predominantly runs through established channels and manufacturer service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifugal water pump market experiences a buyer-power shift as large municipal utilities and industrial facilities increasingly demand performance-based service contracts. This consolidates purchasing decisions around manufacturers offering comprehensive lifecycle management and guaranteed uptime.
For Market Incumbents: Pre-empt competitive threats from digital-first solution providers by accelerating IoT connectivity integration for predictive maintenance. Leverage existing extensive service networks to deliver comprehensive lifecycle management, securing long-term service contracts. Invest in R&D for advanced hydraulic designs and motor technologies to maintain compliance with energy efficiency mandates. This defends against margin pressure from commoditized hardware and addresses workforce skill gaps. For New Entrants and Emerging Players: Underpenetrated markets in Sub-Saharan Africa represent a significant growth opportunity as municipal water and sanitation networks develop. Target specialized corrosion-resistant, high-pressure multi-stage pumps for growing water reuse and desalination projects. A focused go-to-market angle involves offering modular, scalable solutions with integrated digital twin services to address system integration complexity. This allows new players to capture high-margin revenue streams beyond hardware sales. For Investors and Strategic Acquirers: Capital is best deployed toward innovation-driven solution providers with established digital capabilities and extensive service networks. Long-term viability hinges on companies integrating IoT connectivity for predictive maintenance and offering comprehensive lifecycle management. Acquisition targets should possess strong smart water technologies and a proven ability to secure long-term service contracts. The signal to watch is a sustained increase in performance-based service contract adoption across European and North American municipal sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Enables advanced asset management and predictive failure analysis for large municipal utilities. |
| High-Efficiency Hydraulic Design | Meets stringent US Department of Energy and EU Ecodesign Directive efficiency mandates. |
| Corrosion-Resistant Material Innovation | Supports demand for specialized pumps in water reuse and desalination treatment plants. |
| Aftermarket Service Network Expansion | Captures high-margin revenue streams from maintenance and digital monitoring solutions. |
| Sub-Saharan Africa Market Entry | Addresses demand from developing municipal water and sanitation networks in Africa. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform market dynamics and segmentation. Primary interviews included plant engineers, maintenance directors, procurement leads, and municipal water authorities. This was triangulated with secondary research from US Department of Energy reports, EU Ecodesign Directive documents, and industry association publications. A bottom-up and top-down approach validated all data points.
Market sizing and projections were calibrated through a multi-stage analytical framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand elasticity. Compound annual growth rates were derived from historical trend analysis, regulatory impact assessments, and future investment projections. Key inputs included government infrastructure spending commitments and evolving energy efficiency mandate updates.
Practitioners should monitor geopolitical shifts affecting commodity prices and major government infrastructure program changes for early signals of forecast revision. Forecasts reflect assumptions documented at the time of publication, acknowledging inherent market uncertainties. Cross-checking against World Bank infrastructure spending reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Electric Oil Pump Market