
 Electric Vehicle Battery Coolant Market | 2026-2036
Electric Vehicle Battery Coolant Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Coolant Market Foresight
The EU Green Deal's automotive decarbonization mandate is consolidating demand for low-conductivity, biodegradable coolant chemistries across European EV supply chains. BASF SE leverages its Ludwigshafen integrated production complex to supply glycol-based formulations directly to German OEM thermal programs. TotalEnergies anchors its position through backward integration into bio-sourced alcohol feedstocks for water-glycol blends. Shell Group dominates marine and aviation-adjacent coolant testing protocols that now transfer to automotive battery applications.
Electric vehicle battery coolant comprises dielectric or semi-dielectric fluid formulations—typically water-glycol mixtures, dielectric oils, or engineered fluorinated compounds—engineered to maintain cell temperatures between 15°C and 35°C during charge and discharge cycles. These fluids prevent thermal runaway propagation, minimize cell-to-cell temperature variation below 5°C, and preserve pack longevity across 8-15 year service lives. Water-glycol products occupy the largest volume share due to cost scalability and compatibility with existing automotive cooling infrastructure, while cold plate installations are capturing margin pools as 800V architectures demand localized, high-heat-flux dissipation. Fleet operators represent the fastest-growing end user segment as logistics electrification creates concentrated, high-volume procurement contracts with specified thermal performance guarantees.
FDA oversight of fluorinated compound environmental persistence intersects with EPA SNAP program restrictions on high-GWP refrigerant and coolant chemistries, pushing formulators toward hydrofluoroether and hydrofluoroolefin alternatives. China's SAMR enforces GB standards for battery pack thermal propagation resistance that directly specify coolant ignition suppression properties and maximum conductivity thresholds. REACH registration requirements in Europe mandate full toxicological disclosure for novel coolant additives above one tonne annual volume. Stakeholders must monitor how NHTSA's evolving battery safety rulemaking incorporates thermal management system performance into federal motor vehicle safety standards.
Market Dynamics
Passenger EV manufacturers are accelerating procurement of advanced thermal management fluids as 800V architectures and fast-charging protocols intensify heat flux densities beyond the dissipation capacity of legacy cooling infrastructure.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on high-GWP fluorinated compounds are forcing formulators toward hydrofluoroether alternatives, expanding addressable market for next-generation dielectric fluids.
- Fleet electrification:Logistics operators are consolidating procurement through specified thermal performance guarantees, creating concentrated high-volume contracts that validate coolant reliability at scale.
- China's NMPA battery safety protocols:Mandatory thermal propagation resistance standards specify coolant ignition suppression properties, embedding advanced formulations into OEM supply chains.
Market Restraints
- Bio-sourced alcohol feedstock volatility:TotalEnergies and competitors face input cost instability as agricultural commodity prices fluctuate, compressing margin on water-glycol blends.
- REACH registration burden:Full toxicological disclosure mandates for novel additives above one tonne annual volume create structural barriers for mid-tier formulators entering European markets.
- Dielectric oil substitution threat:Engineered fluorinated compounds risk displacement by hydrofluoroolefin alternatives as EPA SNAP program restrictions tighten.
Strategic Opportunities
- Marine-adjacent testing protocols:Shell Group's dominance in aviation and marine coolant certification creates transferable credibility for automotive battery applications requiring extreme thermal stress validation.
- Cold plate architecture convergence:Localized high-heat-flux dissipation systems are capturing margin pools as 800V platforms proliferate, rewarding suppliers with precision manufacturing capabilities.
- India's PLI scheme:Production-linked incentives for domestic EV manufacturing are creating first-mover advantages for coolant suppliers establishing localized blending capacity.
Industry Challenges
- Cell-to-cell temperature uniformity:Maintaining variation below 5°C across 8-15 year service lives requires predictive modeling capabilities that outpace current talent pipelines in thermal engineering.
- NHTSA rulemaking uncertainty:Evolving federal motor vehicle safety standards for battery thermal management systems create compliance timeline risk for OEMs finalizing platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Coolant Market |
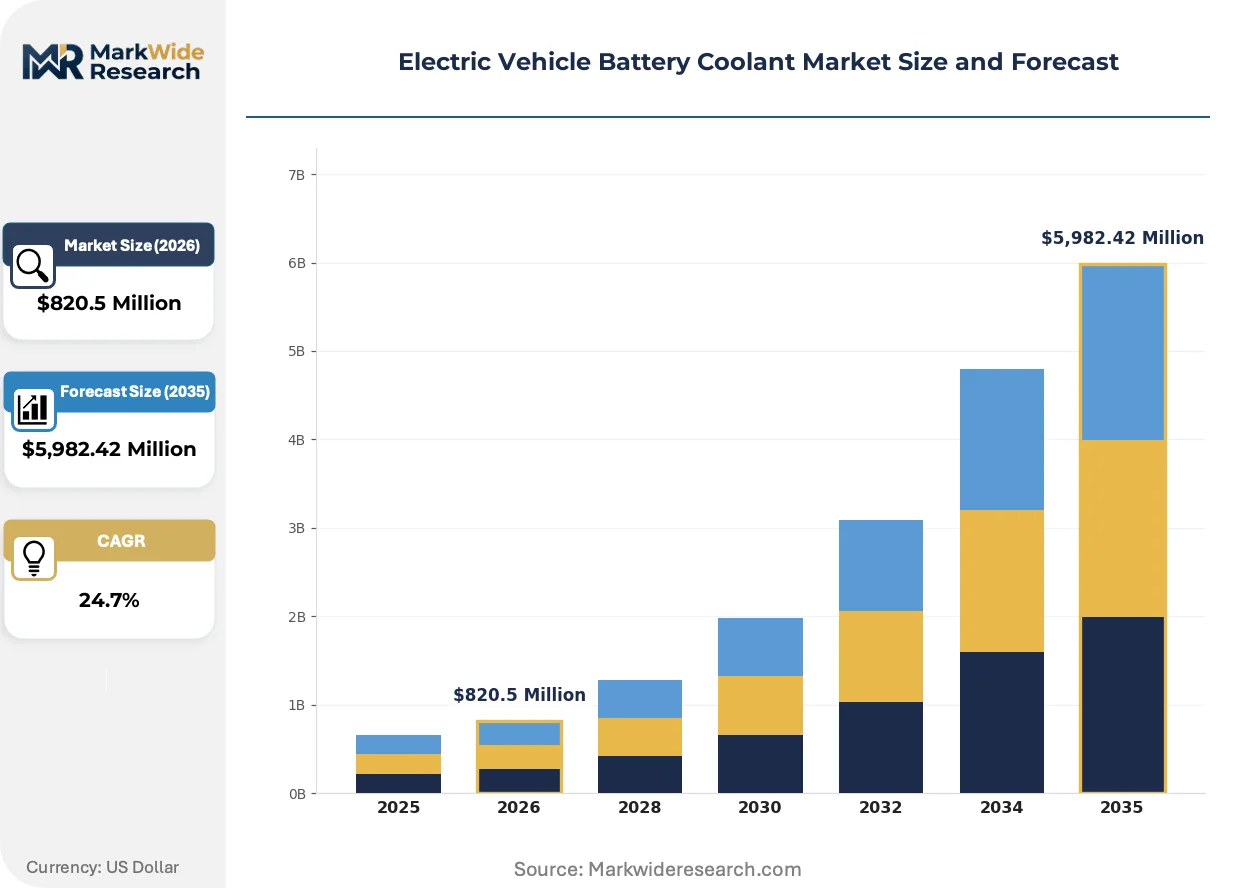
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $5,982.42 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
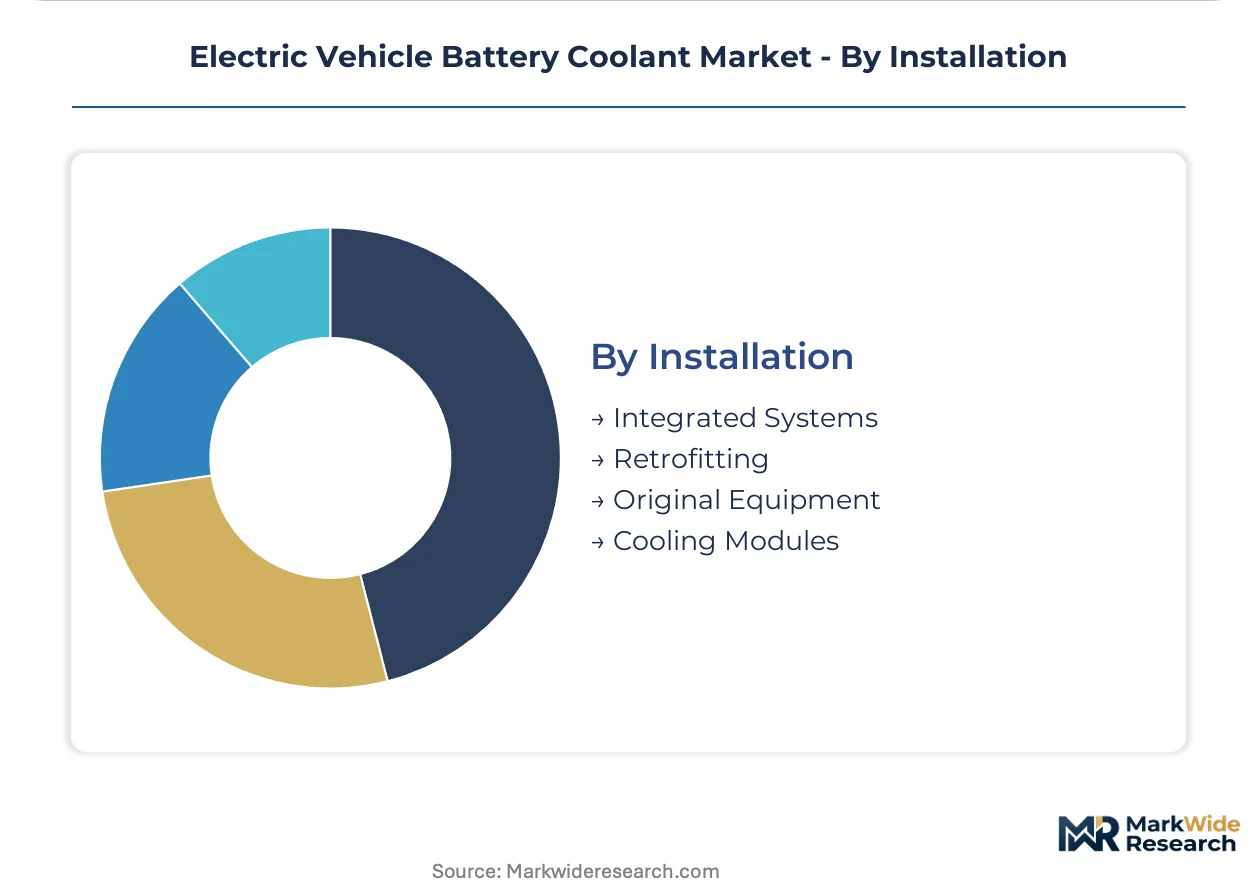
| Segmentation | Product Type: Water-Glycol, Air-Cooled, Radiator Type, Cold Plate Use Case: Temperature Regulation, Heat Dissipation, Performance Optimization, System Stability End User: OEMs, Aftermarket Suppliers, Fleet Operators, Research Institutions Installation: Integrated Systems, Retrofitting, Original Equipment, Cooling Modules |
| Companies Covered | Shell Group, TotalEnergies, BASF SE, Dow Inc., Castrol Limited, Valvoline Inc., GS Caltexa, 3M Company, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Coolant Market Shifts & Advancements
Formulation chemistry and system architecture are converging as thermal management becomes a competitive differentiator in EV platform design, with dielectric performance and biodegradability emerging as dual optimization targets.
Immersion cooling systems using engineered dielectric fluids are modularizing battery pack design by eliminating cold plate plumbing complexity. Premium passenger EV programs are adopting these systems for 800V architectures. This technology is modularizing thermal management from a centralized subsystem into cell-level distributed control, compressing supplier tiers and rewarding integrated formulator-system designers.
REACH registration requirements in Europe are mandating full toxicological disclosure for novel coolant additives above one tonne annual volume. Formulators are pre-emptively screening candidate molecules through ECHA compliance pathways to avoid commercialization delays. Specialty additive suppliers are consolidating around Ludwigshafen and Rotterdam clusters to access shared testing infrastructure.
Logistics fleet operators are unbundling coolant procurement from vehicle purchase contracts, establishing direct relationships with formulators for thermal performance guarantees. Third-party service networks are displacing OEM captive supply for aftermarket coolant replacement. This pattern is most visible in Germany's automotive corridor around Stuttgart and Wolfsburg, where fleet concentration enables volume-based contract structures.
Electric Vehicle Battery Coolant Market Segmentation
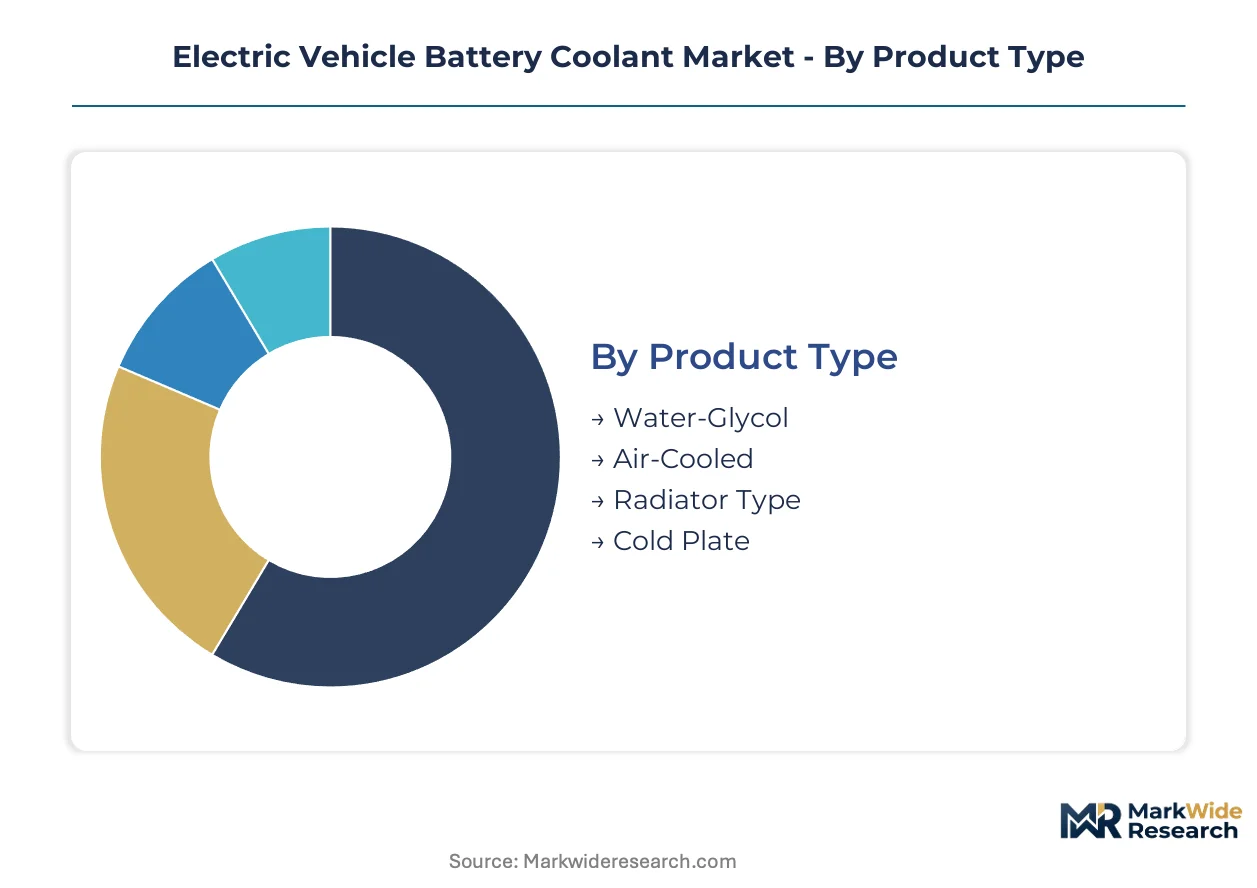
Thermal management procurement decisions split across four distinct axes: fluid chemistry, functional application, customer type, and system integration method. Each axis carries different margin profiles, certification requirements, and supplier qualification barriers that reshape competitive positioning.
Product Type:
Cost scalability and infrastructure compatibility drive buyer selection between established water-glycol formulations and emerging direct-contact architectures.
- Water-Glycol:Ethylene or propylene glycol mixtures dominate volume due to compatibility with existing automotive cooling loops and mature supply chains. German OEMs around Stuttgart specify these formulations for 400V platforms where heat flux densities remain moderate.
- Cold Plate:Aluminum or copper microchannel plates enable localized high-heat-flux dissipation for 800V architectures and fast-charging protocols. China's NMPA battery safety protocols are accelerating adoption as thermal propagation resistance requirements tighten.
- Air-Cooled:Passive convection systems serve cost-sensitive two-wheeler and low-range urban vehicle segments in India under PLI scheme production.
- Radiator Type:Extended surface heat exchangers persist in hybrid thermal management configurations where battery cooling integrates with cabin HVAC loops.
Water-glycol leads on scale; cold plate leads on momentum.
Use Case:
Functional priority determines formulation specification—dielectric requirements, conductivity thresholds, and biodegradability targets vary sharply by thermal objective.
- Temperature Regulation:Maintaining cell temperatures between 15°C and 35°C across charge-discharge cycles. Fleet operators in Germany's logistics corridors negotiate performance guarantees tied to narrow-band thermal control.
- Heat Dissipation:Removing heat flux densities exceeding 500 W/m² from 800V fast-charging events. Immersion cooling systems using engineered dielectric fluids are expanding fastest here.
- Performance Optimization:Minimizing cell-to-cell temperature variation below 5°C to preserve pack longevity across 8-15 year service lives.
- System Stability:Preventing thermal runaway propagation through ignition suppression properties mandated by China's SAMR GB standards.
Heat dissipation commands premium pricing; temperature regulation anchors contract volumes.
End User:
Procurement authority is shifting from OEM captive supply toward direct formulator relationships as fleet operators unbundle coolant from vehicle purchase contracts.
- Fleet Operators:Logistics electrification creates concentrated high-volume procurement with specified thermal performance guarantees. Third-party service networks in Germany's automotive corridor are displacing OEM aftermarket supply.
- OEMs:Passenger EV manufacturers specify coolant chemistry during platform architecture finalization, embedding formulations into 8-15 year supply agreements.
- Aftermarket Suppliers:Independent distributors serve replacement demand as battery packs age out of warranty coverage.
- Research Institutions:National laboratories and university programs validate novel formulations under extreme thermal stress protocols adapted from aviation and marine applications.
Fleet operators are expanding most quickly; OEMs retain specification authority.
Installation:
Integration method determines supplier tier structure and margin capture—modular approaches compress value chains while integrated systems extend OEM control.
- Integrated Systems:Coolant circuits designed concurrently with battery pack architecture, common in premium passenger EV programs from German manufacturers.
- Cooling Modules:Pre-assembled thermal management subsystems supplied to battery pack integrators, reducing OEM engineering burden.
- Original Equipment:Factory-fill formulations specified by vehicle manufacturers and validated through REACH registration pathways for European markets.
- Retrofitting:Post-manufacture installation of enhanced cooling capacity for commercial vehicles upgrading to fast-charge capability.
Integrated systems capture highest margins; cooling modules scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water-glycol coolant chemistry first achieved automotive scale in Germany's Rhine industrial corridor during the 1980s thermal management programs. German chemical engineering established the formulation protocols now governing global EV battery cooling specifications. Today's regional distribution reflects this technical lineage while incorporating new production centers in Asia and North America.
China
Domestic EV production exceeding eight million units annually generates concentrated coolant demand across Jiangsu and Zhejiang provinces. SAMR enforces GB standards for thermal propagation resistance that specify maximum coolant conductivity thresholds and ignition suppression properties. The Yangtze River Delta cluster around Shanghai hosts blending facilities supplying CATL and BYD thermal programs directly.
Germany
Stuttgart and Wolfsburg anchor European formulation capacity with integrated supply chains reaching premium passenger EV programs. The EU F-Gas Regulation tightens restrictions on high-GWP fluorinated compounds, accelerating hydrofluoroether adoption among local formulators. BASF SE's Ludwigshafen complex maintains direct pipeline connections to OEM thermal engineering centers across Baden-Württemberg.
United States
EPA SNAP program restrictions on high-GWP chemistries push domestic formulators toward alternative dielectric fluids for 800V architectures. NHTSA's evolving battery safety rulemaking incorporates thermal management performance into federal motor vehicle safety standards. Michigan's automotive corridor concentrates coolant validation laboratories serving Detroit-based OEM platform development.
South Korea
Domestic battery cell production from LG Energy Solution and Samsung SDI creates captive coolant demand with stringent conductivity specifications. MFDS oversight intersects with industrial chemical registration requirements for novel additive packages. The Seoul Capital Area hosts formulation R&D facilities co-located with battery pack engineering centers.
India
PLI scheme production-linked incentives for domestic EV manufacturing attract first-mover coolant suppliers establishing localized blending capacity. BIS standards for automotive fluids are converging with thermal management specifications from European OEM joint ventures. Tamil Nadu's Sriperumbudur industrial zone concentrates assembly operations requiring validated coolant supply chains.
Electric Vehicle Battery Coolant Market Competitive Landscape
Capital-heavy integrated chemical producers compete with asset-light specialty blenders for position in EV battery coolant supply chains. The market structure concentrates around three tiers: multinational petrochemical conglomerates with backward integration into feedstocks, mid-scale formulators with regional certification expertise, and niche specialists in dielectric fluid engineering. Strategic differentiation runs through REACH registration completion, OEM thermal program validation, and fleet operator performance guarantee contracts. Capacity expansion and geographic licensing agreements constitute the dominant competitive moves.
Among European-integrated chemical conglomerates, BASF SE and TotalEnergies exemplify archetypes with upstream control over alcohol feedstocks and glycol production. Shell Group occupies a position transferable from marine and aviation coolant certification protocols into automotive battery applications. These three anchors represent distinct strategic postures: integrated manufacturing scale, bio-sourced feedstock specialization, and extreme-environment validation credibility.
| Leading Market Players |
|---|
| Shell Group |
| TotalEnergies |
| BASF SE |
| Dow Inc. |
| Castrol Limited |
| Valvoline Inc. |
| GS Caltexa |
| 3M Company |
| Exxon Mobil Corporation |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating hydrofluoroether alternatives for high-GWP fluorinated compounds, compressing margins on legacy dielectric oils while rewarding REACH-registered formulators with OEM thermal program validation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Premium tiers command OEM thermal program validation and REACH registration completion, while fleet operators in Germany's logistics corridors negotiate standard-tier contracts tied to performance guarantees. Pricing pressure stems from bio-sourced alcohol feedstock volatility compressing water-glycol blend margins. Aftermarket suppliers exhibit highest price sensitivity due to unbundled procurement from vehicle purchase contracts.
Supply Chain Analysis
India's PLI scheme and China's domestic content requirements for EV manufacturing are reshaping sourcing patterns away from European-centric formulation capacity. Supply concentrates in Germany, China, and the United States, with feedstocks drawing from Ludwigshafen glycol production, Yangtze River Delta blending facilities, and Michigan validation laboratories. Raw material dependencies rest on ethylene and propylene glycol feedstocks, bio-sourced alcohol precursors, and engineered fluorinated compound intermediates. Single-source vulnerability runs through BASF SE's integrated Ludwigshafen complex for European OEM supply. Distribution feeds from formulator direct sales to OEM thermal engineering centers and third-party fleet service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle Battery Coolant Market represents a late-cycle quality story as logistics electrification shifts procurement authority toward fleet operators demanding 8-15 year thermal performance guarantees.
For Market Incumbents: Extend backward integration into bio-sourced alcohol feedstocks to insulate margin from agricultural commodity volatility threatening water-glycol blend profitability. Deepen OEM thermal program validation through cold plate architecture partnerships for 800V platforms, while defending against hydrofluoroolefin substitution risks from EPA SNAP program restrictions by accelerating hydrofluoroether formulation portfolios. For New Entrants and Emerging Players: Begin with India's PLI scheme production-linked incentive corridors, where domestic EV manufacturing growth outpaces established coolant supply infrastructure. Target Tamil Nadu's Sriperumbudur industrial zone for localized blending capacity, leveraging BIS standards convergence with European OEM joint venture specifications. Pursue direct fleet operator relationships unbundling procurement from OEM captive supply as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale formulators with regional certification expertise because REACH registration burdens and OEM validation timelines create structural barriers to organic scale. Target 5-10 year holding periods aligned with 800V architecture proliferation and immersion cooling modularization. Watch NHTSA battery safety rulemaking incorporating thermal management performance into federal motor vehicle safety standards as the inflection signal for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Sourced Feedstocks | TotalEnergies anchors margin stability through captive agricultural alcohol supply chains. |
| REACH Registration Completion | ECHA compliance pathways validate novel additives for European OEM thermal programs. |
| Cold Plate Manufacturing Scale-Up | Localized high-heat-flux dissipation captures 800V architecture margin pools. |
| Fleet Operator Direct Contracting | Third-party service networks in Stuttgart-Wolfsburg corridors displace OEM aftermarket supply. |
| Immersion Cooling System Integration | Engineered dielectric fluids modularize thermal management from centralized to cell-level control. |
Research Methodology
Direct dialogue with OEM thermal engineering directors, fleet procurement managers, formulator R&D leads, and aftermarket distributor operations grounded the qualitative foundation. Secondary validation drew from EPA SNAP program filings, ECHA REACH registration databases, SAMR GB standards documentation, and SEC 10-K disclosures from integrated chemical producers. Bottom-up segment sizing triangulated against top-down OEM platform production forecasts.
Segment-level outputs across fluid chemistry, functional application, customer type, and system integration method fed into the analytical framework over the projection horizon. CAGRs derived from regression against 800V architecture adoption curves, fast-charging protocol penetration, and fleet electrification contract volumes. Modeled inputs included thermal propagation resistance specifications, conductivity threshold compliance costs, and cold plate content-per-vehicle trajectories.
Caveats apply where NHTSA rulemaking timeline acceleration, EU F-Gas Regulation enforcement stringency, or bio-sourced feedstock price spikes could materially shift the outlook. A small set of regulatory triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
North America LFP Battery Pack Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Traction Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Germany Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Solar DC Coupled Battery Market