
 Chemical Metering Pumps Market | 2026-2036
Chemical Metering Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Metering Pumps Market Analytics
Water treatment is pivoting toward higher-precision chemical dosing as municipalities confront stricter discharge limits and emerging contaminant rules. IDEX Corporation leverages its diversified fluidics portfolio across municipal and industrial accounts. Grundfos Holding A/S anchors its position through digital integration and energy-efficient pump architectures. ProMinent GmbH specializes in complete metering systems with controller-linked dosing skids that reduce operator intervention.
Chemical metering pumps are positive-displacement devices engineered to deliver precise, repeatable flow rates of corrosive, viscous, or hazardous fluids across variable pressure conditions, typically achieving accuracy within one percent of setpoint through diaphragm, plunger, or peristaltic mechanisms. Diaphragm pumps dominate installed base due to seal-less containment of aggressive chemistries, while peristaltic configurations gain traction in pharmaceutical applications where cross-contamination risks demand disposable fluid paths. Electromechanical technology leads value generation through programmable stroke control and SCADA connectivity, whereas pneumatic systems retain share in explosive atmospheres where electrical spark hazards constrain design.
The EPA enforces maximum contaminant levels under the Safe Drinking Water Act that mandate precise chloramination and coagulant dosing, while REACH and the EU Drinking Water Directive impose substance authorization and quality parameter thresholds that shape pump material specifications across European supply chains. China's MEE administers wastewater discharge permits with real-time monitoring requirements that accelerate electromechanical pump replacements. Stakeholders must weigh capital intensity against total cost of ownership as regulatory telemetry mandates expand and chemical compatibility standards tighten for next-generation fluoropolymer and ceramic component designs.
Market Dynamics
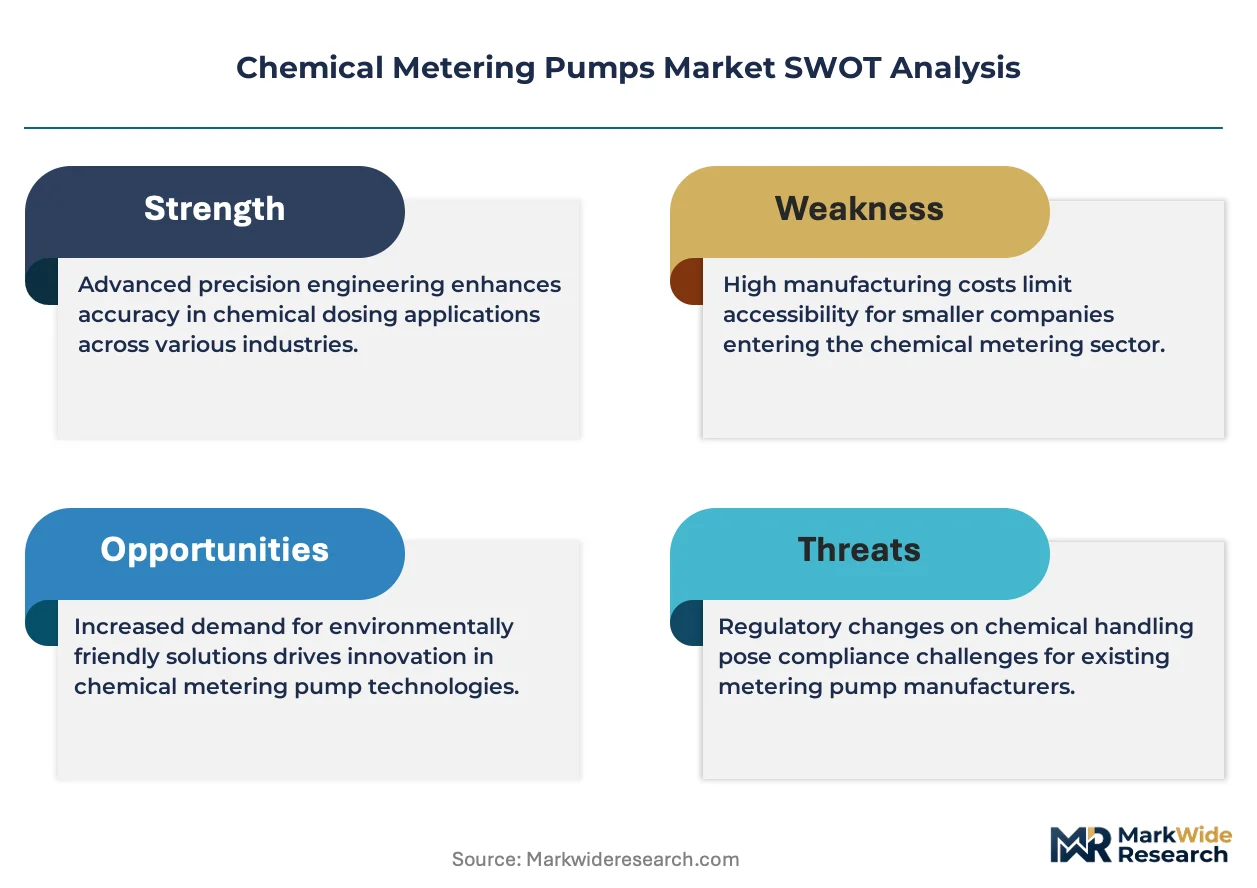
The chemical metering pumps sector faces intensifying pressure from real-time telemetry mandates that are retrofitting legacy infrastructure with networked dosing systems. Electromechanical pumps with embedded sensors now dominate procurement specifications as water utilities seek predictive maintenance capabilities.
Growth Catalysts
- REACH substance authorization:European chemical compliance protocols force material upgrades across pump supply chains, accelerating replacement cycles for non-compliant installed bases.
- Pharmaceutical sterile processing:Peristaltic pump configurations with disposable fluid paths capture share in biologics manufacturing where cross-contamination risks command zero-tolerance protocols.
- China's MEE wastewater permits:Real-time discharge monitoring requirements in chemical processing clusters drive electromechanical pump conversions across Shandong and Jiangsu provinces.
Market Restraints
- Fluoropolymer supply concentration:PTFE and PFA diaphragm materials depend on concentrated Japanese and Chinese resin suppliers, exposing pump manufacturers to input cost volatility.
- Pneumatic system lock-in:Explosive atmosphere installations under ATEX directives retain compressed-air architectures despite electromechanical efficiency advantages, constraining technology migration.
- Extended ceramic sintering cycles:Advanced alumina and silicon carbide component production faces 12-16 week lead times, throttling pump assembly throughput during demand surges.
Strategic Opportunities
- India's PLI scheme for precision engineering:Domestic manufacturing incentives for fluid control equipment attract component localization investments serving South Asian chemical processing corridors.
- SCADA-integrated dosing skids:Convergence of programmable pump controllers with centralized plant management systems opens bundled service revenue streams.
- Brine treatment for lithium extraction:Electrochemical resource recovery operations in Chile and Argentina deploy corrosion-resistant diaphragm pumps for saturated salt solution handling.
Industry Challenges
- Mechatronics technician scarcity:Servicing stroke-adjustable electromechanical pumps requires cross-trained personnel combining mechanical seal expertise with PLC diagnostics.
- Legacy analog system integration:Retrofitting 4-20mA signal pumps into digital Modbus/TCP architectures demands custom protocol gateways that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Metering Pumps Market |
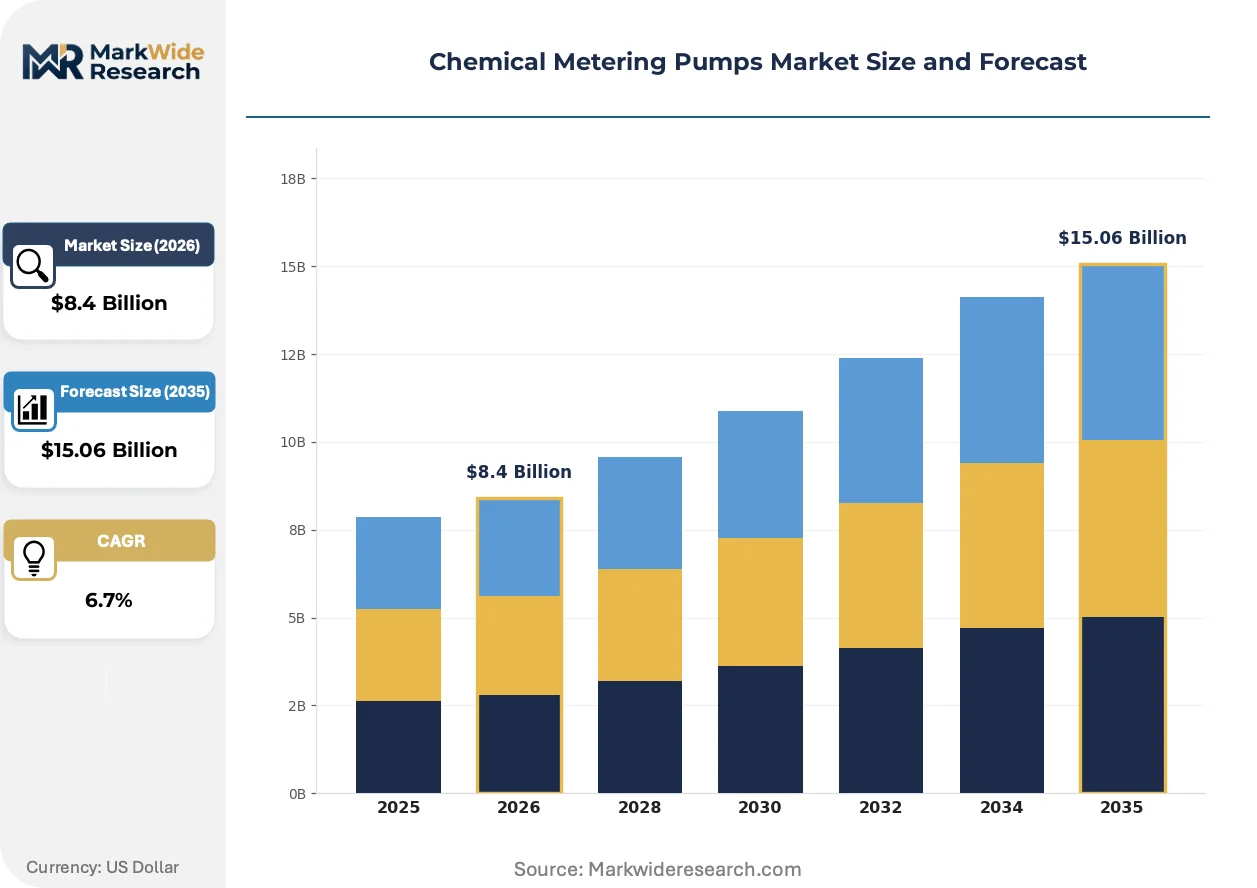
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Gear Pumps, Peristaltic Pumps, Plunger Pumps Application: Water Treatment, Oil & Gas, Pharmaceuticals, Food Processing End User: Chemical Manufacturers, Water Utilities, Pharmaceutical Companies, Food & Beverage Producers Technology: Electromechanical, Pneumatic, Hydraulic, Manual |
| Companies Covered | Ingersoll Rand, Inc., IDEX Corporation, ProMinent GmbH, Grundfos Holding A/S, Dover Corporation, Lewa GmbH, Seko S.P.A., SPX FLOW Inc., Milton Roy Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Metering Pumps Market Evolving Landscape
Connected dosing architectures are compressing the gap between sensor feedback and pump response. Real-time flow verification loops now override mechanical stroke settings without operator intervention.
Edge-computing pump controllers is decentralizing control logic to individual dosing nodes. Municipal water treatment facilities in Germany and the Netherlands deploy these units to eliminate latency from centralized SCADA commands. The architecture reduces chemical overfeed incidents during demand spikes by enabling millisecond-level stroke adjustments.
REACH Annex XIV authorization requirements are tightening material traceability for wetted pump components. European pump OEMs now demand full substance disclosure from fluoropolymer suppliers back to resin batch levels. Diaphragm pump manufacturers serving pharmaceutical applications face the steepest compliance burden as ECHA reviews per- and polyfluoroalkyl substance restrictions.
Specification authority is migrating from maintenance departments to centralized engineering procurement functions. Integrated facility management contractors now issue standardized pump technical requirements across multi-site water utility portfolios. This concentration is most visible in United States municipal systems where regional water authorities consolidate equipment purchasing under shared services agreements.
Chemical Metering Pumps Market Segmentation
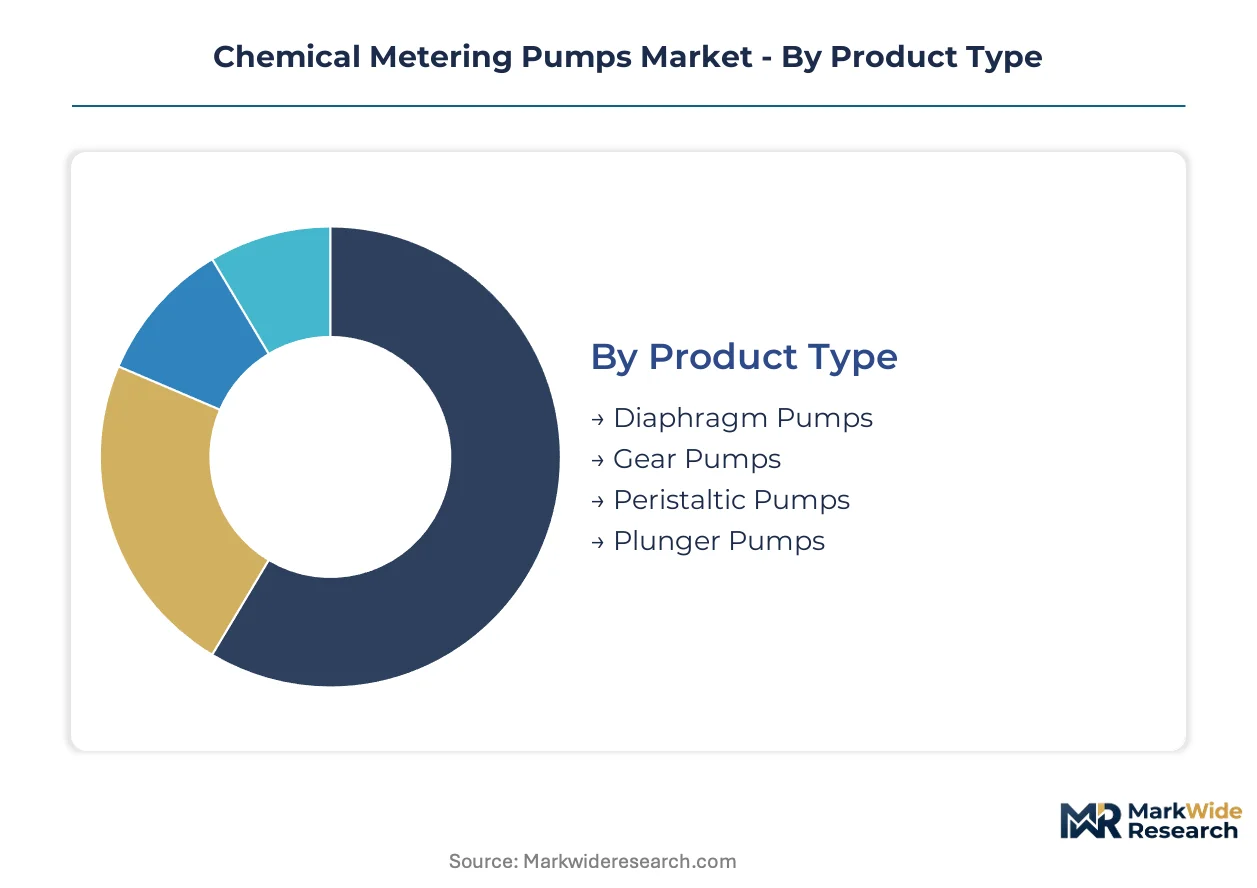
Segmentation in chemical metering pumps reveals distinct upgrade cycles across product architectures and end-use verticals. Replacement timelines vary dramatically between municipal water utilities and pharmaceutical manufacturers, driven by divergent regulatory pressure intensity.
Product Type:
Replacement cycles differ sharply across pump architectures, with seal-less designs commanding shorter upgrade intervals in corrosive chemical service.
- Diaphragm Pumps:Seal-less construction isolates aggressive chemistries through elastomer or PTFE diaphragms that flex against fixed pump heads. Water utilities in Germany and the United States prioritize these configurations for chloramine dosing under EPA and EU Drinking Water Directive mandates, accepting 7-10 year replacement cycles to prevent seal degradation failures.
- Peristaltic Pumps:Roller mechanisms compress disposable tubing to eliminate fluid-path contamination risks entirely. Pharmaceutical manufacturers in Switzerland and Japan specify these for biologics processing where single-use protocols dominate, driving rapid adoption despite higher consumables cost.
- Gear Pumps:Interlocking rotary elements handle viscous polymers and slurries with continuous flow characteristics.
- Plunger Pumps:Reciprocating piston designs achieve highest pressure ratings for oilfield chemical injection.
Volume placements concentrate in Diaphragm Pumps; the faster expansion belongs to Peristaltic Pumps.
Application:
Cost tiers separate mature municipal infrastructure from premium pharmaceutical installations where validation documentation commands price multiples.
- Water Treatment:Municipal and industrial facilities deploy precision dosing for coagulation, disinfection, and pH adjustment across variable raw water quality. China's MEE permit system with real-time monitoring requirements in Shandong and Jiangsu provinces accelerates electromechanical pump conversions, replacing pneumatic legacy systems.
- Pharmaceuticals:Sterile manufacturing demands pumps with full material traceability, surface finish documentation, and CIP/SIP compatibility. European EMA inspections and FDA cGMP enforcement drive specification toward peristaltic and diaphragm architectures with disposable or highly polished fluid paths.
- Oil & Gas:Downhole chemical injection and refinery treatment applications prioritize pressure capability and ATEX certification.
- Food Processing:Sanitary designs with 3A certification handle additives, CIP chemicals, and flavor dosing under FSMA and FSSAI oversight.
Revenue concentration sits with Water Treatment; Pharmaceuticals shows the steepest margin expansion trajectory.
End User:
Customer procurement sophistication varies from centralized engineering standards at multinational chemical producers to decentralized maintenance purchasing at municipal utilities.
- Chemical Manufacturers:Integrated producers operate continuous processes requiring 99.5%+ dosing accuracy for reactor feed and wastewater neutralization. BASF and Dow facilities in Germany and the United States specify smart pumps with embedded flow verification to prevent batch deviations.
- Water Utilities:Regional authorities consolidate purchasing under shared services agreements, standardizing specifications across treatment plants. This concentration shifts specification authority from plant maintenance to centralized procurement functions.
- Pharmaceutical Companies:Validation-heavy procurement demands documented material certifications and change control protocols.
- Food & Beverage Producers:Hygienic design requirements intersect with cost pressure from private-label contract manufacturing.
Contract volume leadership rests with Chemical Manufacturers; Water Utilities demonstrate the fastest procurement centralization.
Technology:
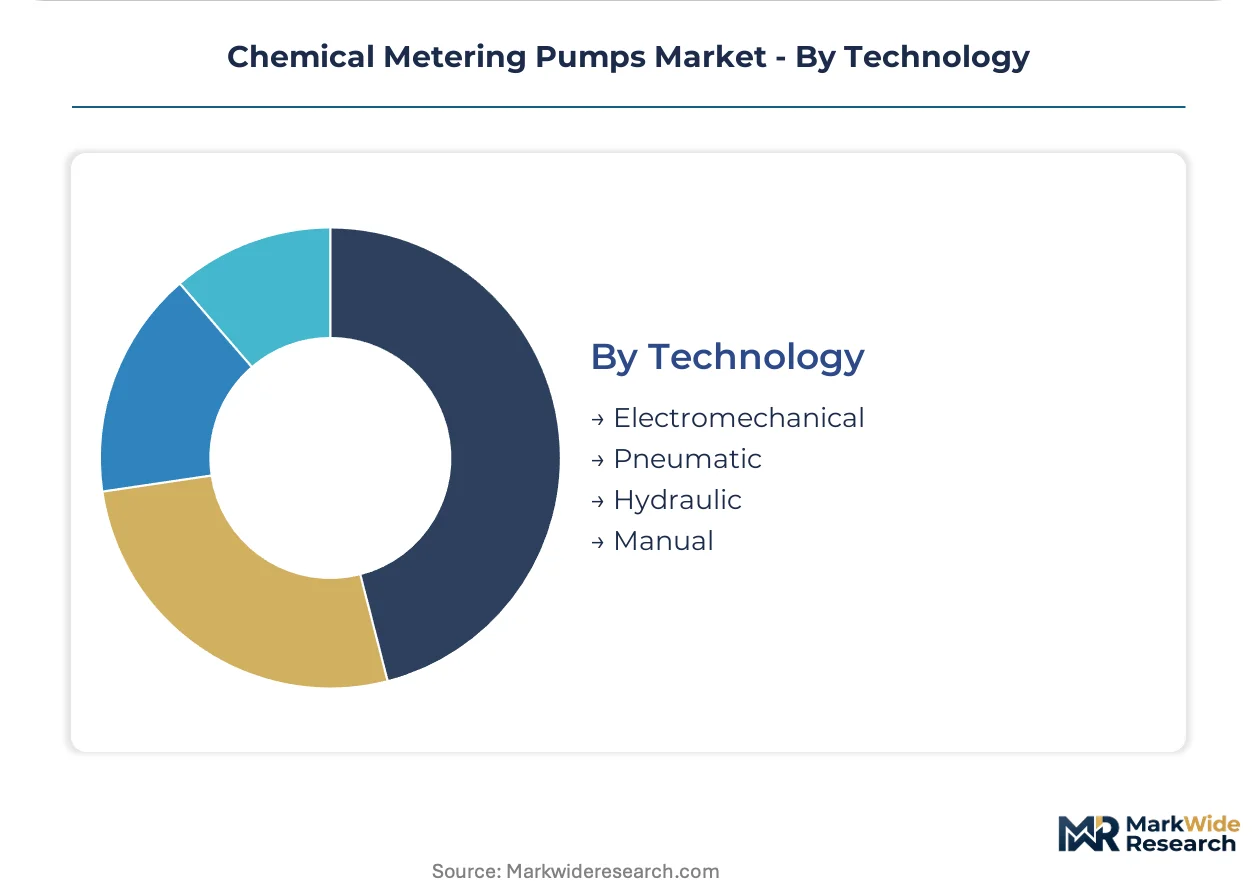
Technology maturity curves separate digitally integrated electromechanical platforms from pneumatic systems locked into explosive atmosphere installations.
- Electromechanical:Servo-controlled stroke adjustment with SCADA connectivity enables predictive maintenance and remote setpoint modification. These systems dominate new municipal procurement in the Netherlands and Denmark where telemetry mandates require networked dosing verification.
- Pneumatic:Compressed-air drive eliminates ignition risks in ATEX Zone 1 environments, preserving share in oilfield and solvent-handling applications despite efficiency disadvantages.
- Hydraulic:Oil-driven actuation delivers smooth flow for shear-sensitive polymers in chemical processing.
- Manual:Hand-adjusted stroke settings persist in isolated applications and backup systems.
Installed base dominance belongs to Electromechanical; Pneumatic retains defensive positioning in hazardous area codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, China, and the United States where precision engineering capabilities intersect with chemical processing demand. Consumption spreads across municipal water utilities and industrial facilities facing tightening discharge regulations. Regional procurement patterns diverge sharply between telemetry-mandated European networks and capacity-expanding Asian chemical corridors.
United States
Municipal water authorities drive electromechanical pump procurement to meet EPA Safe Drinking Water Act contaminant limits. The agency enforces maximum levels for chloramination byproducts that mandate precision dosing infrastructure. Texas and California treatment networks lead replacement cycles as regional authorities consolidate purchasing under shared services agreements.
Germany
REACH substance authorization protocols force material upgrades across pump supply chains, accelerating diaphragm replacement cycles. ECHA reviews of per- and polyfluoroalkyl substances tighten fluoropolymer traceability requirements for pharmaceutical applications. The Rhine-Ruhr chemical processing cluster deploys edge-computing dosing controllers to eliminate latency from centralized SCADA commands.
China
MEE wastewater discharge permits with real-time monitoring requirements accelerate pump conversions across Shandong and Jiangsu provinces. The ministry's enforcement in chemical processing corridors drives electromechanical replacements of pneumatic legacy systems. Yangtze River Delta manufacturing bases expand precision fluidics capacity to serve domestic lithium extraction and semiconductor chemical handling.
India
PLI scheme incentives for precision engineering attract component localization investments serving South Asian chemical processing corridors. The program's domestic manufacturing push targets fluid control equipment for import substitution. Gujarat and Maharashtra industrial zones witness concentrated pump deployment as petrochemical and pharmaceutical facilities scale effluent treatment capacity.
Japan
METI industrial standards shape material specifications for semiconductor and pharmaceutical pump applications where contamination tolerance approaches zero. The ministry's guidance on fluoropolymer purity grades influences diaphragm sourcing across East Asian supply chains. Kyushu and Kansai manufacturing regions maintain specialized ceramic component foundries serving high-purity chemical handling systems.
Chemical Metering Pumps Market Competitive Landscape
Top-tier vendors anchor premium-tier specification authority, while mid-scale specialists occupy regional chemical processing corridors. The vendor base stratifies across diversified fluidics conglomerates, dedicated metering system architects, and precision component fabricators. Three archetypes dominate: integrated pump-and-controller platforms, seal-less containment specialists, and peristaltic disposable-path innovators. Competitive moves concentrate on SCADA-integrated dosing skid bundling and fluoropolymer supply chain backward integration.
Among diversified fluidics conglomerates, IDEX Corporation and Dover Corporation exemplify portfolio breadth across municipal and industrial accounts. Grundfos Holding A/S and ProMinent GmbH represent the dedicated metering system tier, anchoring positions through digital integration and complete dosing skid architectures. German-origin GmbH structures dominate European precision engineering, while US-incorporated entities lead North American municipal procurement consolidation. Specialists in peristaltic and diaphragm configurations occupy defensible niches where material traceability and validation documentation command price premiums.
| Leading Market Players |
|---|
| Ingersoll Rand, Inc. |
| IDEX Corporation |
| ProMinent GmbH |
| Grundfos Holding A/S |
| Dover Corporation |
| Lewa GmbH |
| Seko S.P.A. |
| SPX FLOW Inc. |
| Milton Roy Company |
| Others |
Value Network & Pricing Analysis
Fluoropolymer resin price indices from Japanese and Chinese suppliers cascade through diaphragm pump manufacturing into three-tier pricing structures across premium, standard, and economy levels. REACH substance authorization requirements in Europe and EPA enforcement in the United States concentrate specification authority with buyers who absorb material cost pass-throughs for compliant architectures.
Pricing Analysis
Margin tightening in mid-tier electromechanical pumps reflects fluoropolymer input cost volatility and extended ceramic sintering lead times. Pricing stratifies across premium, standard, and economy tiers based on certification grade—FDA/EMA validation documentation commands multiples—and volume scale from consolidated municipal procurement. Cost-down pressure on pneumatic legacy systems accelerates as utilities convert to networked electromechanical architectures. Chemical manufacturers exhibit lowest price sensitivity due to batch deviation risks; municipal water utilities drive hardest bargaining through shared services agreements.
Supply Chain Analysis
Container freight rate volatility from Asia to Europe and North America amplifies landed cost differentials for precision-machined pump heads and ceramic components. Manufacturing concentrates in Germany, China, and the United States where precision engineering capabilities intersect with chemical processing demand. Raw material dependencies center on Japanese PTFE/PFA resins, Chinese alumina ceramics, and German servo motors. Single-source vulnerability in fluoropolymer diaphragm supply exposes assemblers to input rationing during demand surges. Distribution runs through authorized distributor networks for aftermarket parts and direct OEM relationships for original equipment in municipal tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical metering pumps market operates as a cost-of-compliance arena where REACH Annex XIV substance authorization and EPA Safe Drinking Water Act enforcement erect capital-intensive barriers that favor incumbents with validated material traceability systems.
For Market Incumbents: Anchor specification authority through backward integration into fluoropolymer diaphragm supply and captive ceramic component foundries. IDEX Corporation and Grundfos Holding A/S demonstrate defensive positioning via SCADA-integrated dosing skid bundling that raises switching costs for municipal utilities. Threat substitution from peristaltic disposable-path architectures in biologics manufacturing demands counter-investment in single-use compatible diaphragm materials. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized precision engineering corridor where domestic component localization lags demand from Gujarat and Maharashtra chemical processing zones. The most penetrable segment sits in mid-tier electromechanical pumps for China's Shandong and Jiangsu wastewater treatment upgrades. Go-to-market leverage rests on protocol gateway solutions that bridge legacy 4-20mA analog systems into digital Modbus/TCP architectures without full infrastructure replacement. For Investors and Strategic Acquirers: The window for entry favors specialists in edge-computing pump controllers and peristaltic disposable-path platforms serving pharmaceutical sterile processing. Long-term viability hinges on regulatory telemetry mandate expansion across European and North American water utilities. Acquisition target archetype: mid-scale German-origin GmbH structures with REACH-validated material certifications and existing dosing skid integration capabilities. Signal to watch: ECHA per- and polyfluoroalkyl substance restriction rulings that would force replacement cycles in installed pharmaceutical bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Supply | Captive PTFE/PFA resin sourcing insulates margin from Japanese supplier concentration and REACH traceability mandates. |
| SCADA-Integrated Dosing Skid Bundling | Combined pump-controller-platform offerings lock in municipal utilities through predictive maintenance telemetry contracts. |
| Edge-Computing Controller Development | Millisecond-level stroke adjustment capabilities eliminate chemical overfeed incidents during demand spikes in Dutch and German facilities. |
| Peristaltic Disposable-Path Platform Expansion | Single-use tubing architectures capture biologics manufacturing share where FDA cGMP and EMA inspections enforce zero cross-contamination tolerance. |
| India PLI Scheme Manufacturing Localization | Domestic precision engineering capacity serves South Asian chemical corridor demand while reducing import duty exposure. |
Research Methodology
Independent corroboration across maintenance directors at water utilities, procurement leads at chemical manufacturers, plant engineers in pharmaceutical facilities, and aftermarket service heads at pump distributors underwrites the qualitative findings. Secondary validation draws from EPA enforcement databases, ECHA substance authorization registries, China's MEE discharge permit records, and customs trade data for fluoropolymer resin flows. Bottom-up unit economics triangulate against top-down market sizing from installed base replacement cycle analysis.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift toward higher-value electromechanical platforms. Segmentation dimensions include pump architecture, end-use vertical, technology type, and regional regulatory cluster. CAGRs derive from replacement timeline modeling tied to REACH authorization phases and EPA maximum contaminant level enforcement schedules. Forecast inputs incorporate real-time telemetry mandate adoption curves and ceramic component lead time elasticity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA per- and polyfluoroalkyl substance restrictions and fluoropolymer supply rationing events. Outputs reflect documented assumptions on regulatory enforcement intensity and material substitution feasibility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Air Compressor Controller Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market