
 APAC Centrifugal Pumps Market | 2026-2036
APAC Centrifugal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Centrifugal Pumps Market Outlook
India's Bureau of Energy Efficiency star-rating mandate is repositioning procurement standards across the region. EBARA Corporation leverages its submersible pump specialization to anchor contracts in Japan's municipal sector. Kirloskar Brothers Limited dominates India's agricultural irrigation segment with localized manufacturing scale. Grundfos sustains technology leadership through magnetic drive integration for chemical processing applications.
Centrifugal pumps convert rotational kinetic energy into hydrodynamic energy to move fluids through volute or diffuser casings, with impeller diameters and motor speeds determining head capacity and flow rate. These machines serve water distribution networks, industrial process loops, and energy extraction systems where continuous fluid transfer at variable pressures remains essential. Single-stage designs occupy the largest volume share in agricultural irrigation across India and Southeast Asia, while magnetic drive technology captures premium positioning in chemical and oil & gas end uses where leak containment governs specification. Multi-stage configurations lead power generation applications across China and Japan due to high-pressure boiler feed requirements.
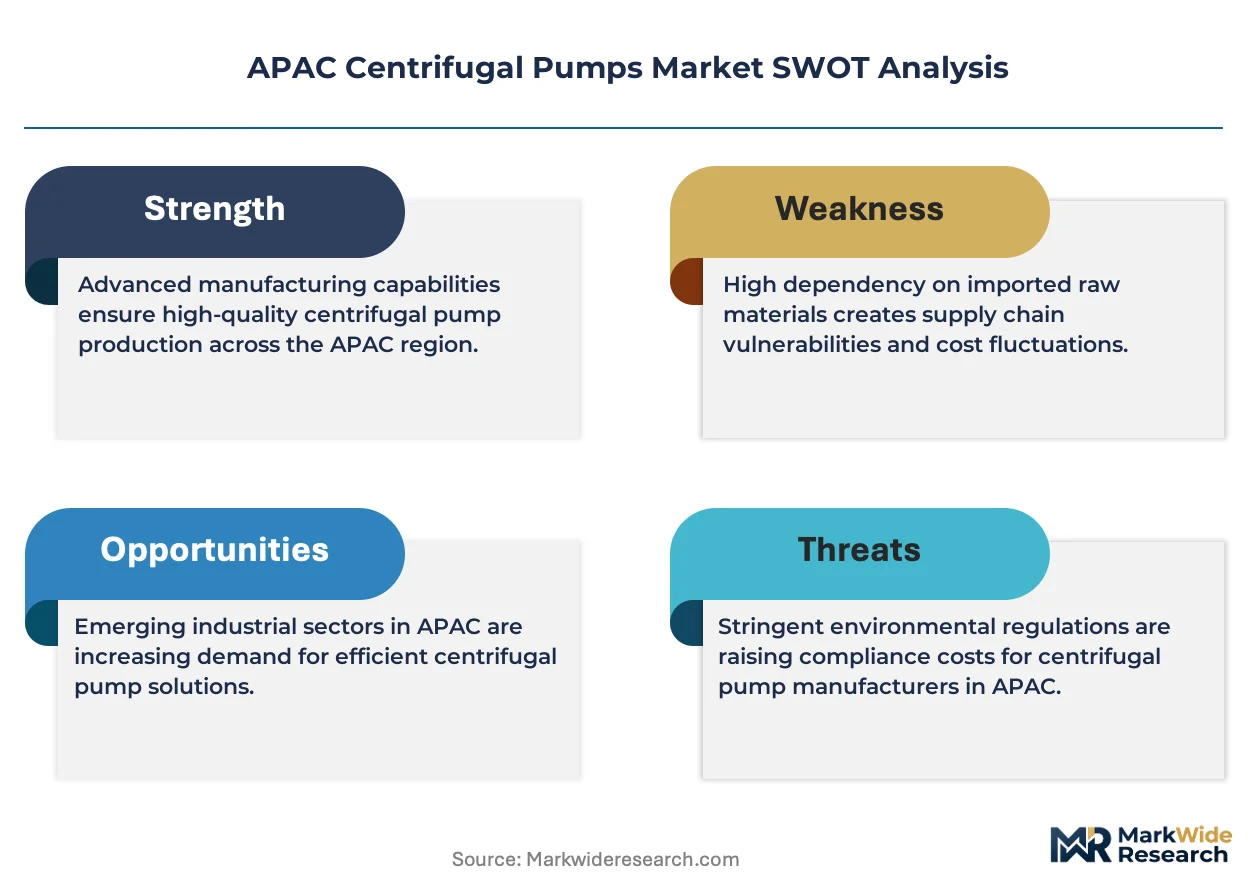
China's Ministry of Ecology and Environment enforces discharge standards that compel wastewater treatment plant upgrades, directly expanding demand for submersible and vertical pump configurations. Japan's METI energy efficiency benchmarks shape product development timelines for electric motor-driven systems sold across East Asian markets. India's BIS certification requirements for pump performance testing create compliance barriers for unverified imports. Stakeholders must monitor how carbon border adjustments and local content rules in Southeast Asian procurement reshape supplier qualification criteria across the forecast horizon.
Market Dynamics
China's municipal water infrastructure renewal programs are compressing procurement cycles while India's BEE star-rating mandate forces simultaneous technology upgrades across supplier bases. These dual pressures are restructuring competitive positioning around energy efficiency certification and localized manufacturing compliance.
Growth Catalysts
- India's BEE Star-Rating Mandate:The Bureau of Energy Efficiency's mandatory performance labeling for agricultural and industrial pumps is accelerating replacement demand. Domestic manufacturers are retooling production lines to meet minimum efficiency thresholds.
- China's Wastewater Treatment Expansion:The Ministry of Ecology and Environment's discharge standard enforcement is compelling municipal utilities to upgrade pumping infrastructure. Submersible and vertical pump configurations are capturing specification share in plant retrofit contracts.
- Magnetic Drive Technology:Leak-proof pump designs are displacing conventional sealed units in chemical processing and oil & gas applications. End users specify these systems where containment failure carries environmental or safety liability.
Market Restraints
- Cast Iron and Specialty Steel Input Volatility:Foundry-grade material costs fluctuate with regional scrap metal availability and energy pricing. Pump OEMs face margin compression when long-term municipal contracts lock in fixed pricing.
- Japan-Centered Precision Component Supply:High-efficiency motor stators and magnetic drive assemblies concentrate among Japanese component specialists. Geopolitical friction or logistics disruption propagates through East Asian pump assembly networks.
- Technical Limitation in High-Temperature Applications:Standard elastomer seals degrade above 150°C, restricting centrifugal pump deployment in certain process industries. Ceramic and metal-sealed alternatives carry 3-4x cost premiums that deter adoption.
Strategic Opportunities
- Vietnam's Industrial Water Infrastructure Gap:Foreign direct investment in electronics manufacturing is outpacing municipal treatment capacity. Industrial park developers are procuring packaged pumping stations with integrated control systems.
- Smart Pump-Digital Twin Convergence:Vibration sensors and edge computing modules are enabling predictive maintenance contracts. Equipment suppliers can capture recurring revenue streams beyond hardware margins.
- Indonesia's PLN Grid Electrification Incentives:State utility subsidies for rural pump electrification are opening agricultural mechanization demand. Solar-powered surface pump systems qualify for preferential financing.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:India's BIS testing requirements, China's GB standards, and Japan's JIS specifications create parallel compliance tracks. Product development timelines extend 8-12 months for regional portfolio coverage.
- Legacy Control System Integration:Municipal utilities operate SCADA networks with 15-20 year replacement cycles. New pump installations require protocol adapters or complete control architecture overhauls.
- Skilled Field Service Technician Scarcity:Magnetic drive and variable frequency drive maintenance demands electro-mechanical cross-training. Rural service coverage gaps limit aftermarket contract penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Centrifugal Pumps Market |
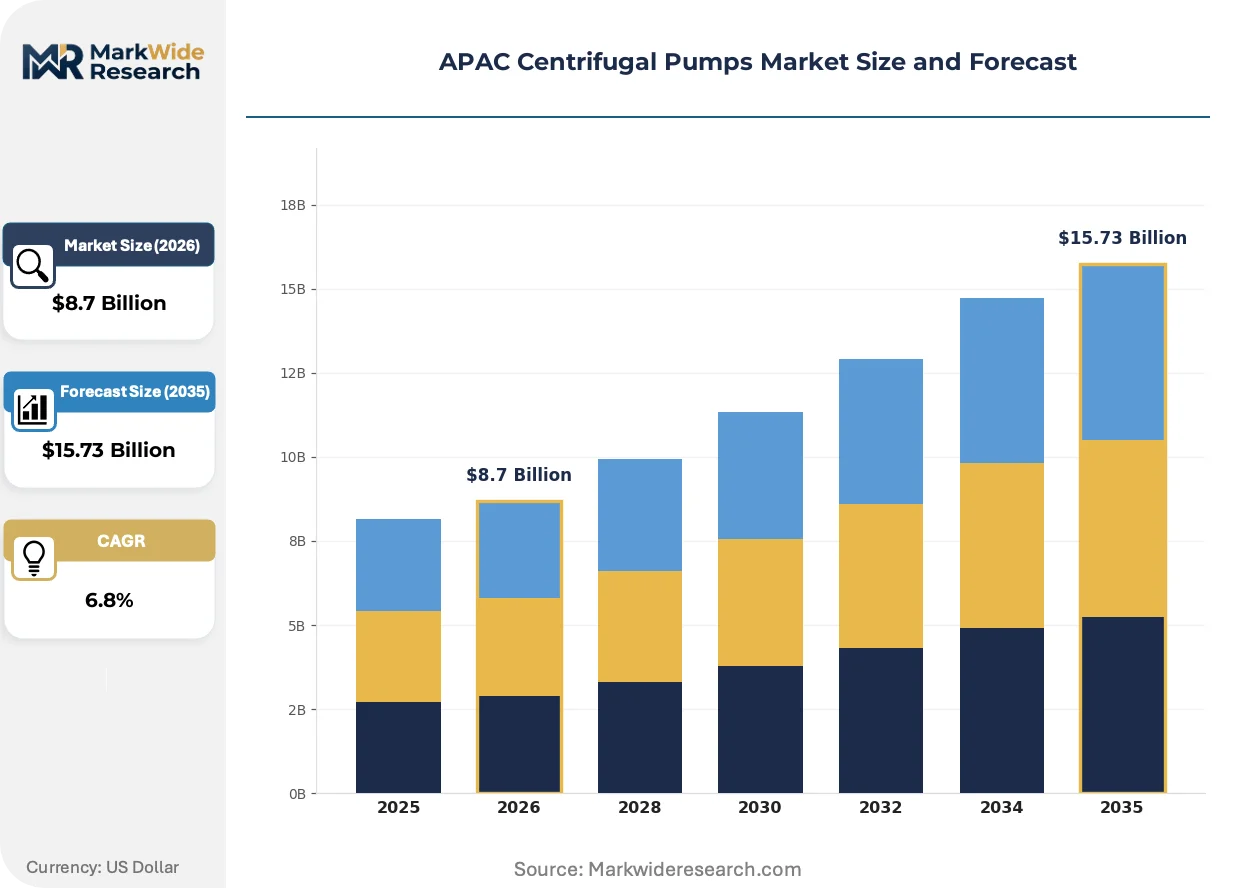
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Multi-stage, Submersible, Vertical Application: Agricultural Irrigation, Water Supply, Wastewater Treatment, Industrial Processing End User: Oil & Gas, Chemical, Power Generation, Municipal Technology: Magnetic Drive, Electric, Hydraulic, Pneumatic |
| Companies Covered | EBARA Corporation, Xylem, Sulzer Ltd, Wilo SE, KSB SE & Co, Flowserve Corporation, Grundfos, Kirloskar Brothers Limited, The Weir Group PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Centrifugal Pumps Market Strategic Shifts
Electrification of pump motor systems is intersecting with digital monitoring layers to reconfigure how fluid transfer assets are specified, operated, and maintained across municipal and industrial contexts.
Permanent magnet synchronous motors are electrifying medium-head pump applications previously dominated by induction motor designs. Municipal water utilities in China and Japan are specifying these systems for 20-30% energy consumption reduction. The technology is compressing total cost of ownership calculations and shortening payback period justifications in public procurement.
Japan's METI energy efficiency benchmarks are cascading through East Asian supply chains as de facto regional standards. Pump manufacturers align product development roadmaps to these thresholds to maintain cross-border market access. Electric motor-driven systems sold across China, South Korea, and Taiwan now carry efficiency ratings traceable to METI methodology.
Lifecycle service contracts are displacing transactional equipment sales in municipal sector procurement. Water utilities in Australia and Singapore are bundling pump supply with 10-year maintenance and energy performance guarantees. This model concentrates vendor selection criteria on service network density rather than unit price alone.
APAC Centrifugal Pumps Market Segmentation
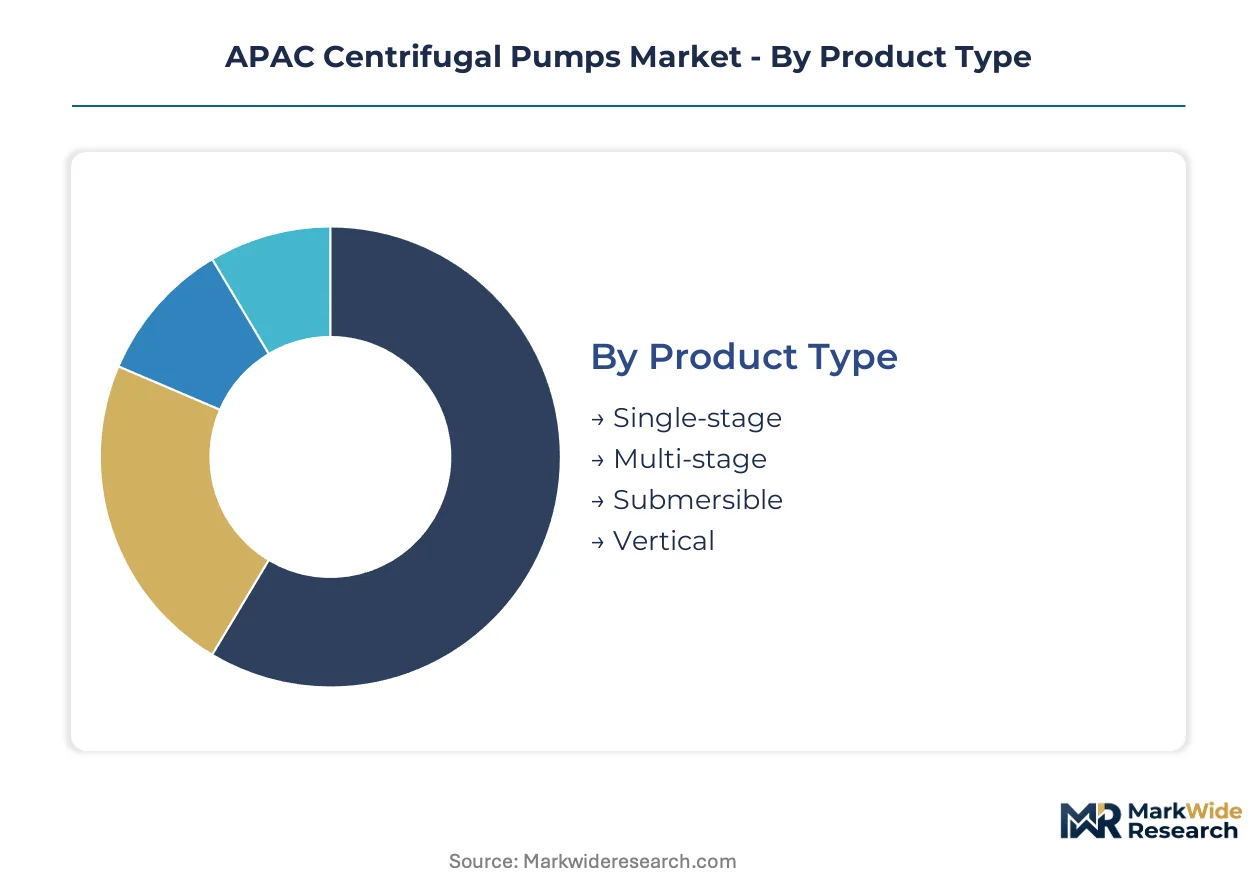
Centrifugal pump specification in APAC diverges sharply across pressure requirements, fluid characteristics, and duty cycles. Procurement patterns cluster around agricultural mechanization in India, municipal infrastructure renewal in China, and chemical containment protocols in Japan and South Korea.
Product Type:
Buyers differentiate primarily by head pressure requirements and installation constraints rather than initial capital outlay.
- Single-stage:One impeller generates moderate discharge pressure for low-lift applications. India's BEE star-rating mandate is accelerating replacement of inefficient induction-motor units in Bihar and Uttar Pradesh agricultural districts.
- Multi-stage:Series-arranged impellers achieve high-pressure output for boiler feed and reverse osmosis systems. China's power generation sector specifies these configurations for ultra-supercritical thermal plant installations under MEE discharge compliance timelines.
- Submersible:Motor and pump integrated for borewell and sump deployment. Groundwater extraction regulations in Maharashtra and Gujarat restrict permissible depths.
- Vertical:Shaft-extended design for limited footprint installations. Wastewater treatment plants in Vietnam's industrial parks favor these for tank immersion duties.
Single-stage leads volumes today; multi-stage is gaining share fastest.
Application:
End-use concentration determines specification complexity and aftermarket service intensity.
- Agricultural Irrigation:Surface water lift and pressurized distribution systems. India's Kisan Credit Card scheme subsidizes pump electrification in rain-fed districts.
- Water Supply:Municipal distribution network pressure maintenance. China's Ministry of Water Resources pipeline replacement programs specify variable frequency drive compatibility.
- Wastewater Treatment:Sludge transfer and tertiary filtration pumping. Indonesia's national sanitation targets are expanding biological treatment plant construction in Java.
- Industrial Processing:Continuous circulation in manufacturing process loops. Thailand's Board of Investment incentives for food processing clusters are driving specification demand.
Agricultural irrigation dominates installed base; wastewater treatment is expanding most quickly.
End User:
Procurement authority structures split between centralized utilities and decentralized industrial operators.
- Oil & Gas:Hydrocarbon transfer and produced water reinjection systems. Australia's offshore platform maintenance schedules concentrate demand in Western Australia.
- Chemical:Corrosive fluid handling with leak containment requirements. Japan's Chemical Substances Control Law shapes seal material specifications.
- Power Generation:Cooling water circulation and condensate extraction. China's dual carbon goals are retrofitting coal plant pumping systems for efficiency compliance.
- Municipal:Water authority procurement with lifecycle cost evaluation. Singapore's PUB mandates 25-year design life for all new pump installations.
Municipal end users lead volumes today; chemical sector is climbing the fastest.
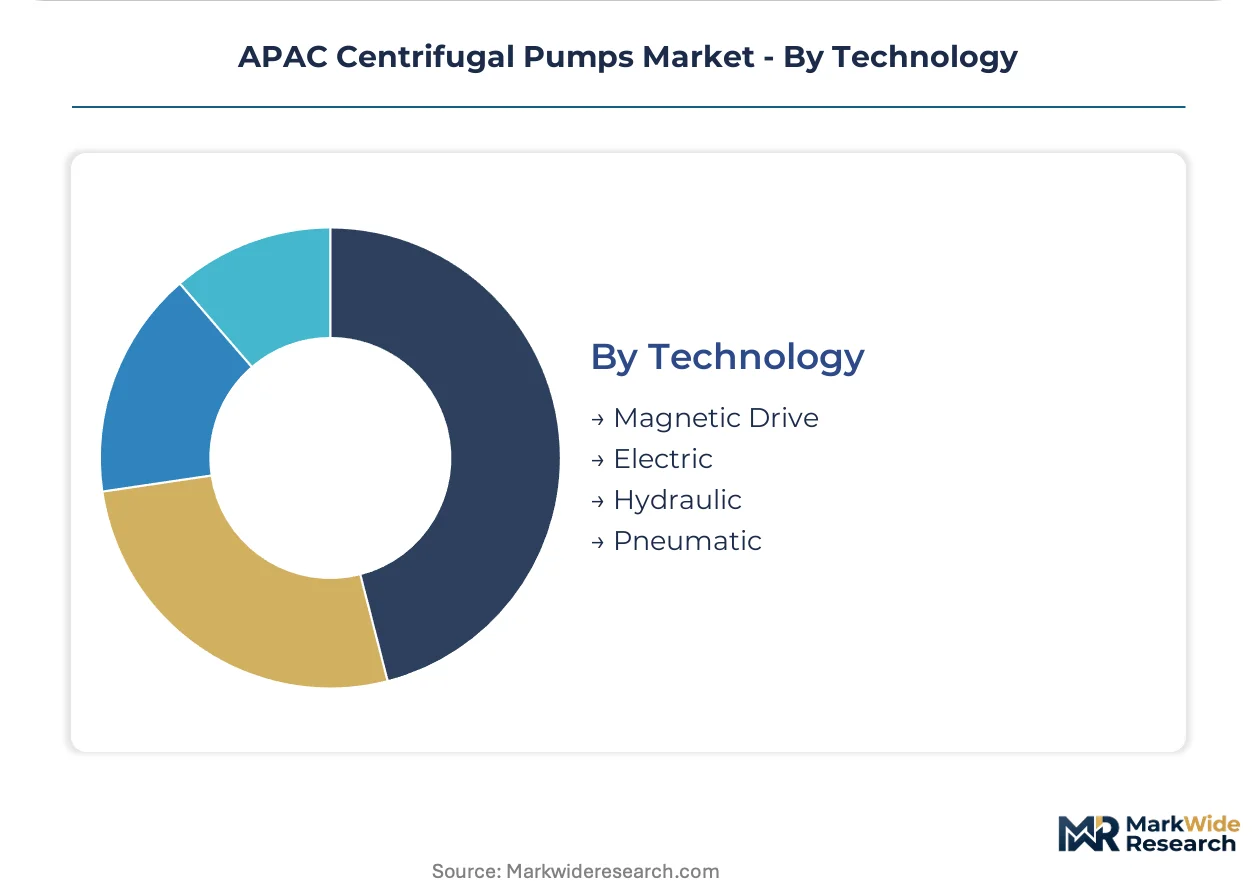
Technology:
Drive mechanism selection reflects energy cost exposure and maintenance capability constraints.
- Magnetic Drive:Canned motor or magnetic coupling eliminates mechanical seals. Chemical processors in South Korea's Yeosu industrial complex specify these for toxic fluid duties.
- Electric:Grid-connected motor systems with variable frequency control. METI efficiency benchmarks are standardizing motor specifications across East Asian markets.
- Hydraulic:Fluid power actuation for explosion-risk environments. Underground coal operations in Australia's Queensland specify these for dewatering.
- Pneumatic:Compressed air drive for intermittent duty or remote locations. Offshore platforms in Malaysia's Sarawak basin deploy these where electrical spark risk governs.
Electric technology leads volumes today; magnetic drive is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry engineers and pump assembly technicians concentrate in Japan's precision manufacturing belt, China's Yangtze industrial corridor, and India's western engineering clusters. These workforce distributions anchor regional supply capabilities while shaping technology transfer patterns across the broader market.
China
Municipal water infrastructure renewal and wastewater treatment plant upgrades drive procurement volume. The Ministry of Ecology and Environment enforces discharge standards that compel utility upgrades. Shanghai and Guangzhou municipal authorities specify submersible and vertical pump configurations for plant retrofit contracts.
Japan
Precision component manufacturing and magnetic drive technology development anchor the supply base. METI energy efficiency benchmarks cascade through East Asian supply chains as de facto regional standards. Osaka and Nagoya industrial clusters concentrate high-efficiency motor stator and magnetic drive assembly production.
India
Agricultural irrigation mechanization and municipal water distribution expansion create dual demand channels. The Bureau of Energy Efficiency mandates star-rated pump performance labeling that accelerates replacement cycles. Maharashtra and Gujarat groundwater extraction regulations restrict permissible borewell depths while subsidizing efficient pump electrification.
South Korea
Chemical processing containment requirements and power generation efficiency upgrades shape specification demand. The Yeosu industrial complex specifies magnetic drive systems for toxic fluid handling duties. Seoul metropolitan water utilities bundle lifecycle service contracts with equipment procurement.
Vietnam
Electronics manufacturing foreign direct investment outpaces municipal treatment capacity development. Industrial park developers in Bac Ninh and Hai Phong provinces procure packaged pumping stations with integrated control systems. State utility subsidies support rural agricultural pump electrification programs.
APAC Centrifugal Pumps Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers and geographic coverage. The vendor base organizes around three strategic archetypes: Japanese precision component integrators, Indian agricultural irrigation specialists, and European energy efficiency technology providers. Capacity expansion and localized manufacturing compliance constitute the dominant competitive moves as procurement standards tighten across the region.
Among Japanese precision manufacturers, EBARA Corporation anchors municipal submersible pump positioning. Kirloskar Brothers Limited exemplifies Indian agricultural irrigation specialization with localized manufacturing scale. Grundfos occupies the premium energy efficiency technology tier through magnetic drive integration capabilities.
| Leading Market Players |
|---|
| EBARA Corporation |
| Xylem |
| Sulzer Ltd |
| Wilo SE |
| KSB SE & Co |
| Flowserve Corporation |
| Grundfos |
| Kirloskar Brothers Limited |
| The Weir Group PLC |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between BEE star-rated and unlabeled pump systems manifests in both procurement premiums and supplier qualification hierarchies across India and China. Municipal utilities in Shanghai and Guangzhou pay efficiency-linked premiums while agricultural buyers in Bihar face compressed margins on commodity induction-motor units.
Pricing Analysis
Bundled lifecycle service contracts versus unbundled equipment-only sales now define the dominant pricing split across APAC municipal procurement. Three-tier pricing structure across premium magnetic-drive, standard electric-motor, and economy induction-motor levels reflects METI efficiency benchmarks and BIS certification compliance costs. Pricing pressure stems from foundry-grade cast iron and specialty steel input volatility under long-term fixed municipal contracts. Agricultural irrigation buyers in India's rain-fed districts exhibit highest price sensitivity, while chemical processors in South Korea's Yeosu complex accept premium positioning for containment assurance.
Supply Chain Analysis
Regional distribution centers in Osaka, Shanghai, and Mumbai anchor hub-and-spoke warehouse networks serving East and South Asian pump assembly operations. Foundry-grade iron casting capacity concentrates in China's Yangtze corridor, India's western engineering clusters, and Japan's precision manufacturing belt. Magnetic drive assemblies and high-efficiency motor stators draw from Japanese component specialists, creating single-source vulnerability for premium pump configurations. Distribution runs through authorized dealer networks with service capability certification, particularly for submersible and multi-stage configurations requiring specialized installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC centrifugal pumps function as a stable compounder anchored by mandatory efficiency regulations that force continuous replacement cycles across installed bases. India's BEE mandate and China's MEE discharge standards ensure steady equipment refresh demand regardless of macroeconomic volatility.
For Market Incumbents: Cement defensive positioning through backward integration into foundry operations and captive motor stator production. EBARA Corporation's submersible specialization and Grundfos's magnetic drive integration demonstrate how technology anchoring resists price erosion from Chinese OEMs. Incumbents should expand service network density in Vietnam's industrial park corridors to capture lifecycle contract bundling opportunities ahead of regional competitors.
For New Entrants and Emerging Players: Begin with Indonesia's PLN-subsidized rural electrification programs where solar-powered surface pump systems qualify for preferential financing and local content rules remain nascent. Vietnam's electronics manufacturing foreign direct investment outpaces municipal treatment capacity, creating packaged pumping station demand with integrated control specifications. New entrants should pursue joint venture structures with established Japanese component suppliers to bypass METI efficiency benchmark compliance barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification complexity extends product development timelines 8-12 months and fragments regional portfolio coverage. Acquisition targets should demonstrate BIS, GB, and JIS parallel compliance capabilities or proprietary magnetic drive assembly expertise. The signal to watch is carbon border adjustment implementation timelines in Southeast Asian procurement, which will disqualify uncertified imports and concentrate supplier bases around compliant regional manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captures margin from cast iron input volatility while securing BEE compliance capacity. |
| Lifecycle Service Contract Bundling | Singapore's PUB 25-year design life mandates transform vendor selection toward service density. |
| Magnetic Drive Assembly Certification | Japan's Chemical Substances Control Law shapes seal specifications for toxic fluid containment premiums. |
| Regional Distribution Center Expansion | Vietnam's Bac Ninh and Hai Phong industrial parks demand localized spare parts availability. |
| Smart Pump-Digital Twin Integration | Edge computing modules enable predictive maintenance recurring revenue beyond hardware margins. |
Study Parameters
Bottom-up agricultural and municipal demand modeling reconciled against top-down foundry capacity and motor assembly tracking forms the analytical core of this study. Primary interviews with maintenance directors at water utilities, plant engineers in chemical processing clusters, OEM procurement teams specifying boiler feed systems, and aftermarket service heads covering rural irrigation networks combined with secondary validation from BEE star-rating databases, MEE discharge compliance filings, METI efficiency benchmark publications, and customs trade records for pump motor imports.
Historical trendline analysis across single-stage, multi-stage, submersible, and vertical product configurations established baseline penetration patterns before modeling technology transition rates for magnetic drive and permanent magnet synchronous motor adoption. Segmentation dimensions include pressure requirement tier, end-use application, drive mechanism type, and regional regulatory cluster, with CAGRs derived from utility capital expenditure planning cycles and agricultural mechanization subsidy program trajectories. Forecast inputs incorporated groundwater extraction depth restrictions in Maharashtra and Gujarat, plus ultra-supercritical thermal plant commissioning schedules under China's dual carbon goals.
Several conditions sit outside the modeled scope, including geopolitical disruption to Japanese precision component supply, abrupt elimination of India's Kisan Credit Card pump subsidies, and unanticipated ceramic seal material breakthroughs eliminating high-temperature application cost premiums. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Solar Pump Market