
 US Industrial Pump Market | 2026-2036
US Industrial Pump Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Pump Market Intelligence
Digital twin integration is narrowing the performance gap between predictive maintenance platforms and legacy mechanical pump systems. Flowserve Corporation leverages embedded sensor architectures to sustain aftermarket service revenue across downstream oil and gas installations. Xylem anchors its position through vertical integration into cloud-based analytics software for municipal water networks. ITT Goulds Pumps, Inc. competes on foundry-to-finish manufacturing scale in the Great Lakes industrial corridor.
An industrial pump converts mechanical energy into hydraulic force to move fluids through sealed casings, impellers, or displacement chambers at pressures ranging from 50 to 10,000 psi for process continuity in continuous-flow operations. Centrifugal pumps dominate installed base volume across power generation cooling loops, while positive displacement systems command premium pricing in chemical processing where shear-sensitive fluids require controlled volumetric delivery. Smart pump technology is capturing the fastest expansion in water treatment applications, though magnetic drive configurations retain margin advantages in hazardous fluid handling.
EPA enforcement of the Clean Water Act and OSHA process safety management standards shape product certification requirements, with NHTSA and DOT regulations additionally governing pump-mounted transport systems in mobile applications. The Department of Energy's pump efficiency standards under the Energy Policy Act reset minimum performance thresholds for commercial and industrial equipment classes. Stakeholders must weigh capital allocation between connected infrastructure upgrades and compliance-driven replacement cycles as federal efficiency mandates tighten.
Market Dynamics
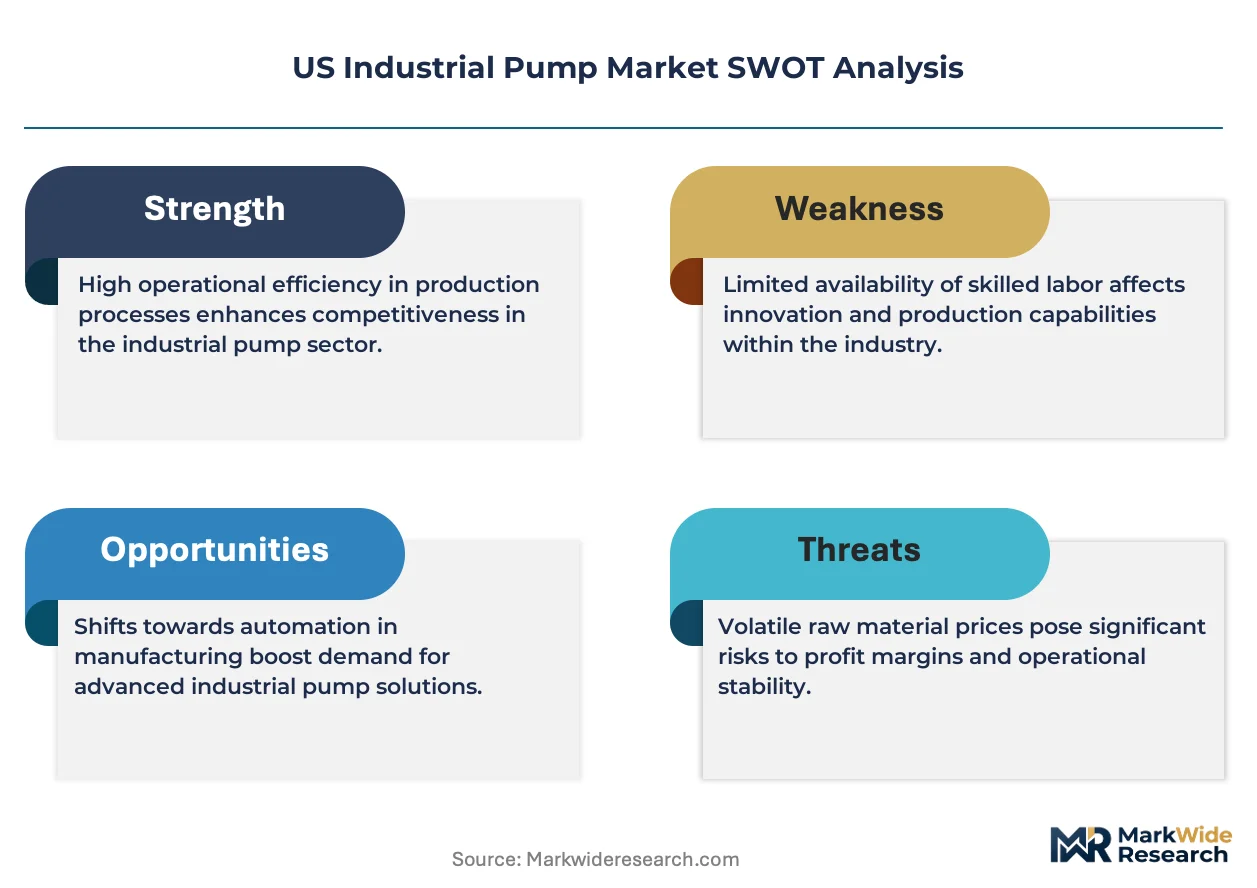
EPA enforcement of the Clean Water Act is compressing replacement cycles across municipal water infrastructure, forcing utilities to prioritize smart pump retrofits over mechanical repairs.
Growth Catalysts
- Clean Water Act mandates:EPA discharge standard tightening accelerates infrastructure replacement in Texas petrochemical corridors and California agricultural districts.
- Smart sensor architectures:Embedded condition monitoring enables predictive maintenance adoption across downstream oil and gas installations.
- Ohio manufacturing belts:Process safety management compliance drives positive displacement pump upgrades in chemical processing facilities.
Market Restraints
- Cast iron foundry concentration:Domestic foundry capacity constraints limit impeller casing production scalability for large-scale orders.
- Copper and rare earth magnet costs:Permanent magnet motor material volatility compresses margins on premium efficiency pump lines.
- Shear-sensitive fluid limitations:Centrifugal pump designs face technical barriers in biopharmaceutical applications requiring controlled volumetric delivery.
Strategic Opportunities
- Magnetic drive configurations:Hazardous fluid handling applications in chemical processing offer margin expansion for sealless pump technologies.
- Cloud-based analytics integration:Municipal water networks present white space for subscription-based performance optimization platforms.
- Department of Energy efficiency standards:Energy Policy Act compliance deadlines create captive replacement demand through 2035.
Industry Challenges
- Digital twin integration complexity:Legacy mechanical pump systems require costly sensor retrofitting to interface with predictive maintenance platforms.
- Foundry-to-finish certification timelines:NHTSA and DOT pump-mounted transport system approvals delay mobile application product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Pump Market |
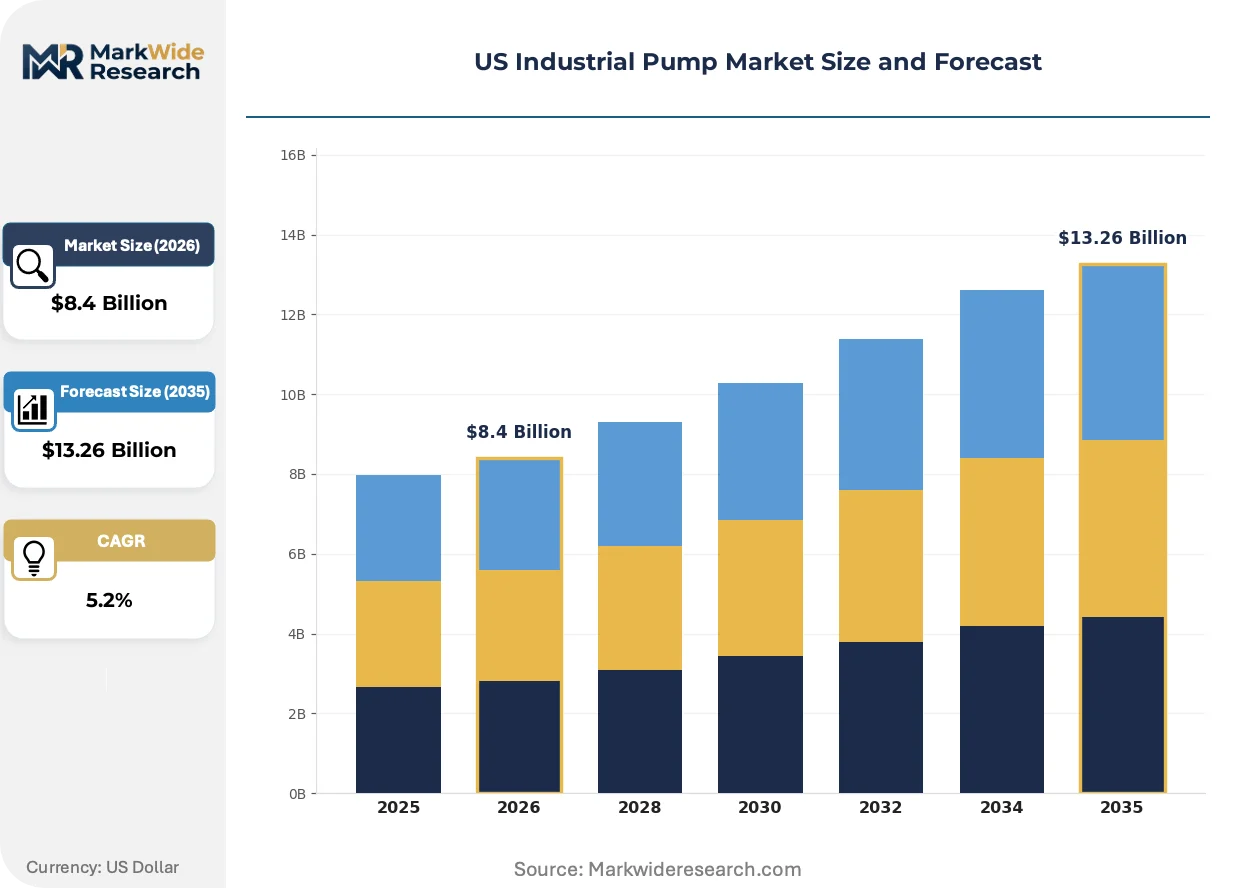
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Centrifugal, Positive Displacement, Diaphragm, Screw Application: Agriculture, Chemical Processing, Water Treatment, Oil & Gas End User: Manufacturing, Power Generation, Food & Beverage, Mining Technology: Smart Pumps, Magnetic Drive, Submersible, Hydraulic |
| Companies Covered | Xylem, ITT Goulds Pumps, Inc., Curtiss-Wright Flow Control Co., Flowserve Corporation, The Gorman-Rupp Co., Baker Hughes Oilfield Operations, LLC, GIW Industries, Inc., Ingersoll Rand, Pentair Flow Technologies, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Pump Market Strategic Shifts & Innovations
Connected infrastructure architectures are restructuring competitive advantage around data monetization rather than unit sales, compressing traditional equipment margin structures.
Magnetic drive sealless pump technology is migrating from niche hazardous chemical applications into broader municipal water treatment installations. Texas and Louisiana refineries pioneered adoption for volatile organic compound containment. The technology is migrating from premium-priced specialty equipment toward standard municipal procurement specifications, compressing price premiums while expanding addressable volume.
OSHA process safety management standards now mandate continuous monitoring for high-pressure pump systems in chemical processing corridors. The regulation forces distributed control system upgrades and embedded sensor retrofitting across legacy installations. Ohio and Gulf Coast petrochemical clusters face the steepest compliance costs, driving consolidation toward integrated pump-and-control package suppliers.
After-sales service unbundling is fragmenting traditional OEM revenue streams across municipal water utilities. Texas and California districts now separately procure spare parts, field service, and predictive analytics from specialized vendors rather than single-source contracts. This pattern is most visible in large metropolitan water authorities with dedicated procurement teams, compressing incumbent aftermarket margins while opening entry points for software-native competitors.
US Industrial Pump Market Segmentation
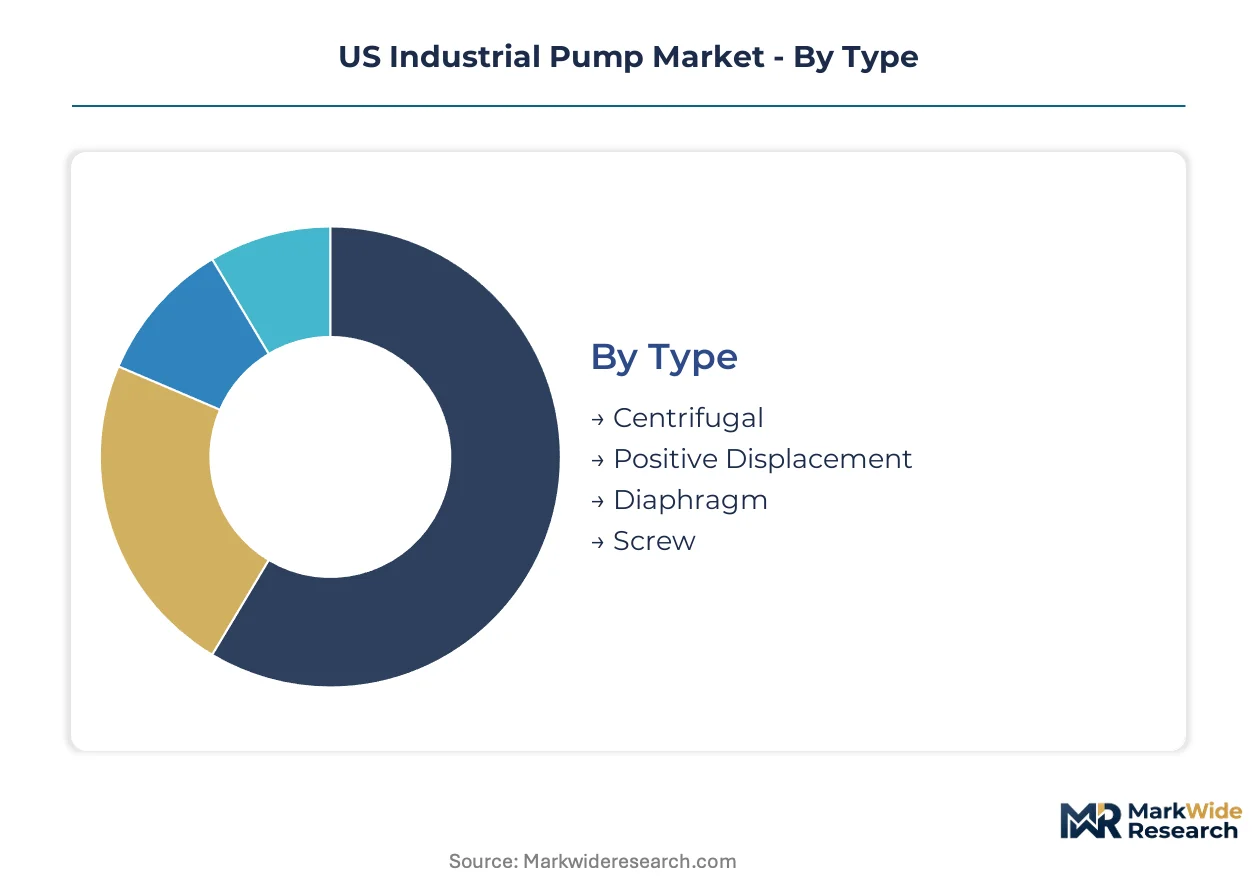
Industrial pump procurement cycles vary dramatically by segment, with municipal water infrastructure turning over every 15-20 years while chemical processing equipment cycles compress to 7-10 years under OSHA pressure. Understanding these replacement rhythms shapes inventory positioning and service revenue forecasting across the value chain.
Type:
Replacement velocity diverges sharply: centrifugal pumps in power generation cooling loops operate 30+ years, while positive displacement systems in chemical processing face 8-year cycles driven by seal degradation and precision drift.
- Centrifugal:Radial flow impeller designs handle high-volume, low-viscosity fluids across Texas power generation corridors. Ohio manufacturing belts sustain demand for ANSI standard process pumps in cooling water recirculation. Installed base dominance masks slower revenue growth as utilities defer replacement.
- Positive Displacement:Controlled volumetric delivery suits shear-sensitive chemical formulations in Gulf Coast petrochemical clusters. Gear, lobe, and piston configurations command 40-60% price premiums over centrifugal equivalents. California agricultural districts specify these for precise fertilizer injection systems.
- Diaphragm:Air-operated double-diaphragm architectures isolate pumped media from mechanical components, serving abrasive slurry handling in Arizona copper mining operations.
- Screw:Progressive cavity and twin-screw variants excel in multiphase oil extraction across Permian Basin unconventional wells.
Centrifugal pumps dominate installed base. Positive displacement is where expansion concentrates.
Application:
Margin structures stratify by fluid hazard classification: benign water treatment applications compress pricing while volatile organic compound handling sustains sealless technology premiums.
- Agriculture:Center-pivot irrigation and precision fertigation systems in California Central Valley districts specify corrosion-resistant stainless steel construction. EPA agricultural runoff regulations tighten nutrient management requirements, accelerating variable-frequency drive adoption.
- Chemical Processing:High-pressure reactor feed and corrosive acid transfer in Texas-Louisiana petrochemical corridors demand Hastelloy and titanium metallurgy. OSHA process safety management mandates continuous monitoring retrofitting across legacy installations.
- Water Treatment:Municipal utilities in Great Lakes states prioritize smart pump retrofits over mechanical repairs under EPA Clean Water Act enforcement. Subscription-based analytics platforms capture recurring revenue streams.
- Oil & Gas:Midstream pipeline booster stations and downstream refinery process units in Oklahoma and Kansas specify API 610 compliance for reliability-critical service.
Water treatment absorbs the steepest technology investment. Chemical processing retains the highest margin capture.
End User:
Capital allocation discipline varies by sector profitability: mining and oil & gas defer maintenance during commodity downturns while food & beverage sustains sanitary upgrade cycles.
- Manufacturing:General industrial process water and coolant circulation across Ohio and Michigan automotive supplier networks. Just-in-time production requirements favor standardized spare parts availability over specialized performance.
- Power Generation:Combined cycle gas turbine plants in Texas and Pennsylvania specify large vertical turbine pumps for cooling tower makeup. DOE efficiency standards drive variable-speed retrofitting.
- Food & Beverage:3-A sanitary standards compliance dominates dairy processing in Wisconsin and brewing operations in Colorado. Clean-in-place protocols favor stainless steel centrifugal designs with polished surfaces.
- Mining:Slurry transport and dewatering in Arizona copper and Nevada gold operations impose severe abrasive wear conditions. High-chrome iron metallurgy extends service intervals in tailings handling.
Manufacturing represents the largest addressable volume. Food & beverage shows the steepest expansion trajectory.
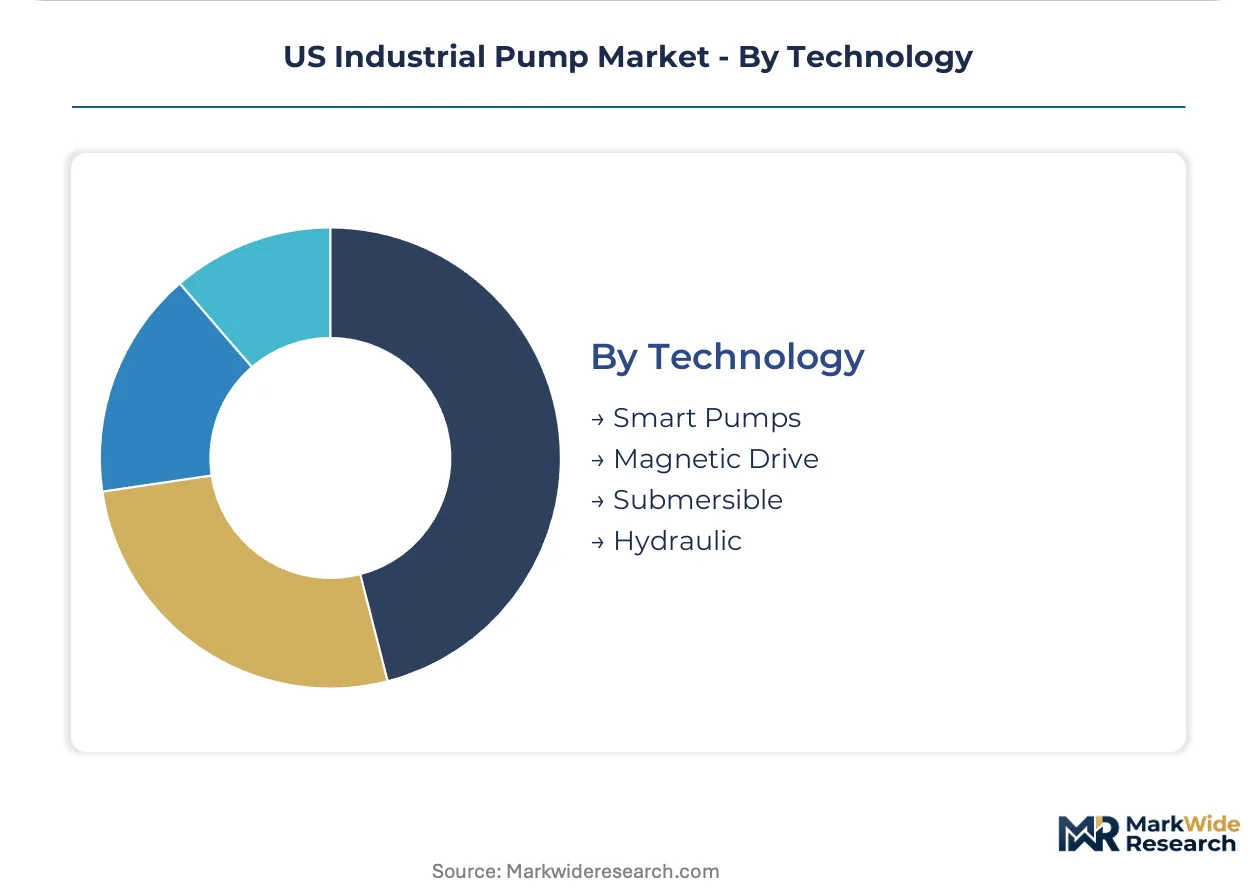
Technology:
Intelligence integration is restructuring competitive advantage: embedded sensor architectures enable predictive maintenance monetization while mechanical simplicity retains cost-driven procurement.
- Smart Pumps:Integrated variable frequency drives, vibration sensors, and cloud connectivity enable condition-based maintenance in Chicago and Atlanta municipal water authorities. Digital twin integration narrows the performance gap against legacy mechanical systems.
- Magnetic Drive:Sealless containment technology eliminates mechanical seal leakage in hazardous chemical handling. Migration from premium specialty equipment toward standard municipal specifications compresses margins while expanding volume.
- Submersible:Immersed motor-pump configurations serve groundwater extraction and wastewater lift stations across Florida aquifer districts.
- Hydraulic:Fluid power actuation provides explosion-proof operation in offshore Gulf of Mexico platforms and underground coal handling.
Magnetic drive anchors hazardous fluid applications. Smart pumps gain share fastest in municipal networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pump manufacturers export precision-engineered positive displacement systems to US chemical processing corridors. This transatlantic trade flow supplies Texas and Louisiana petrochemical clusters with sealless technology for hazardous fluid containment.
Texas
The Permian Basin drives multiphase pump demand for unconventional oil extraction. EPA Clean Water Act enforcement tightens produced water disposal standards across Midland and Odessa operations. Houston anchors downstream refinery process pump procurement for API 610 compliance.
California
Central Valley agricultural districts specify corrosion-resistant centrifugal pumps for precision fertigation systems. State Water Resources Control Board nutrient management regulations accelerate variable-frequency drive adoption. Fresno and Bakersfield clusters concentrate stainless steel pump procurement for center-pivot irrigation.
Ohio
Great Lakes manufacturing belts sustain ANSI standard process pump demand for automotive supplier coolant circulation. OSHA process safety management mandates continuous monitoring retrofitting across legacy chemical installations. Cleveland and Toledo corridors anchor foundry-to-finish pump manufacturing scale.
Louisiana
Gulf Coast petrochemical refineries pioneered magnetic drive sealless pump adoption for volatile organic compound containment. Coast Guard and EPA joint enforcement tightens hazardous fluid handling standards. Baton Rouge and Lake Charles clusters face the steepest compliance-driven replacement cycles.
Pennsylvania
Marcellus Shale midstream operations specify large vertical turbine pumps for pipeline booster stations. Department of Energy efficiency standards drive variable-speed retrofitting across combined cycle gas turbine plants. Pittsburgh and Philadelphia metropolitan utilities prioritize smart pump infrastructure under EPA consent decrees.
US Industrial Pump Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base spans multinational diversified industrials alongside regional foundry operators and application-specific technology developers. Three archetypes dominate: integrated flow control conglomerates, municipal water technology platforms, and oilfield service pump specialists. Capacity expansion and predictive maintenance platform development represent the dominant competitive vectors.
Among integrated flow control conglomerates, Flowserve Corporation and ITT Goulds Pumps, Inc. exemplify scale-driven positioning across downstream oil and gas and Great Lakes industrial corridors respectively. Xylem occupies a position as a municipal water technology platform with cloud-based analytics integration. These three companies represent contrasting strategic postures: foundry-to-finish manufacturing scale, aftermarket service revenue capture, and vertical software integration.
| Leading Market Players |
|---|
| Xylem |
| ITT Goulds Pumps, Inc. |
| Curtiss-Wright Flow Control Co. |
| Flowserve Corporation |
| The Gorman-Rupp Co. |
| Baker Hughes Oilfield Operations, LLC |
| GIW Industries, Inc. |
| Ingersoll Rand |
| Pentair Flow Technologies, LLC |
| Others |
Cost & Logistics Intelligence
German precision engineering concentration in positive displacement pump manufacturing anchors premium pricing tiers across Texas and Louisiana petrochemical corridors. Domestic foundry capacity constraints in Ohio and Michigan compress margins on large centrifugal orders while elevating value capture for integrated manufacturers with captive casting capabilities.
Pricing Analysis
Next-generation smart pump systems command 25-40% premiums over mechanical equivalents, while legacy centrifugal installations face sustained price erosion. Three-tier pricing structure across premium, standard, and economy levels stratifies by metallurgy grade and API certification tier. Pricing pressure stems from copper and rare earth magnet cost volatility in permanent magnet motor configurations. Municipal water utilities exhibit highest price sensitivity through unbundled procurement, whereas chemical processors prioritize sealless technology premiums for hazardous fluid containment.
Supply Chain Analysis
Tariff exposure between China and the United States dominates rare earth magnet and copper winding supply security for premium efficiency motor lines. Domestic production draws from Ohio and Pennsylvania foundry clusters for cast iron casings, German imports for precision positive displacement systems, and Mexican maquiladora operations for standard ANSI process pumps. Single-source vulnerability concentrates in neodymium magnet supply chains. Distribution runs through authorized distributor networks serving municipal utilities and direct OEM channels for petrochemical EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US industrial pump market sits in early-cycle expansion as EPA Clean Water Act enforcement accelerates smart infrastructure replacement timelines. Smart pump penetration in municipal water networks remains below saturation thresholds, creating sustained adoption tailwinds.
For Market Incumbents: Entrench aftermarket service revenue through predictive maintenance platform subscriptions, countering unbundling threats from software-native competitors. Deepen backward integration into cloud analytics software to capture recurring revenue streams from Chicago and Atlanta municipal authorities. Prioritize foundry capacity expansion in Great Lakes corridors to defend scale advantages against import-dependent challengers. For New Entrants and Emerging Players: Establish a beachhead in magnetic drive sealless technology for municipal water treatment applications, where migration from premium specialty toward standard specifications opens volume expansion. Target California agricultural districts with corrosion-resistant stainless steel fertigation systems, exploiting EPA nutrient management regulatory tailwinds. Pursue channel partnerships with irrigation equipment distributors rather than direct utility sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward integrated pump-and-control package suppliers with embedded sensor architectures, as OSHA process safety management mandates force distributed control system upgrades across Ohio and Gulf Coast chemical clusters. Long-term viability hinges on software monetization capability rather than unit manufacturing scale. Watch smart pump retrofit penetration rates in Great Lakes municipal utilities as the inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cloud Analytics | Xylem's software verticalization captures recurring municipal water utility subscription revenue. |
| Foundry Capacity Expansion | ITT Goulds' Great Lakes casting scale defends ANSI process pump cost position against imports. |
| Magnetic Drive Technology Migration | Sealless pump adoption spreads from Texas refineries into standard municipal procurement specifications. |
| Predictive Maintenance Platform Development | Flowserve's embedded sensor architectures sustain aftermarket service revenue across downstream oil and gas. |
| Joint Venture for Rare Earth Magnet Security | Permanent motor material sourcing partnerships hedge against Chinese supply disruption and price volatility. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, municipal utility procurement directors, aftermarket service heads, and OEM technical sales specialists; and secondary validation against SEC 10-K filings, EPA enforcement action databases, Department of Energy efficiency standard dockets, and customs trade records for pump and component imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators anchored volume and value estimates.
Forecast inputs encompassed replacement cycle dynamics across municipal water infrastructure and chemical processing installations, technology penetration curves for smart pump architectures, and regulatory compliance deadline clustering under Clean Water Act and Energy Policy Act mandates. Segmentation dimensions modeled include pump type, application hazard classification, end-user capital allocation discipline, and technology intelligence tier. CAGRs were derived from installed base turnover rates and upgrade elasticity assumptions across the projection horizon.
Stress conditions across rare earth magnet price volatility, foundry capacity utilization thresholds, and EPA enforcement intensity variations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and utility capital budget trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Fuel Feed Pumps Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market