
 Ion Pump Market | 2026-2036
Ion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Ion Pump Market Foresight
The EU F-Gas Regulation is rebalancing procurement criteria across European research facilities and semiconductor fabs toward non-fluorinated vacuum technologies. Pfeiffer Vacuum Technology AG leverages its titanium sublimation pump portfolio to capture replacement cycles in particle accelerator upgrades. ULVAC Inc. anchors supply relationships with Japanese semiconductor equipment OEMs through localized service networks. Edwards Vacuum competes on cryogenic ion pump variants designed for next-generation lithography systems.
An ion pump is a vacuum pump that captures and immobilizes gas molecules through electrical ionization and subsequent burial or chemical binding on reactive surfaces, typically achieving ultimate pressures below 10^-11 mbar using titanium cathodes and strong magnetic fields. The technology serves applications requiring oil-free, vibration-free ultrahigh vacuum environments such as electron microscopy, mass spectrometry, and semiconductor wafer processing. Titanium-based ion pumps command the premium tier due to superior hydrogen pumping speed and extended operational lifespan in continuous-duty research settings. Semiconductor manufacturing applications represent the fastest-expanding segment as extreme ultraviolet lithography tools demand cleaner vacuum conditions than previous nodes. Electron-based ionization technology leads unit shipments though sputtering variants gain traction in aerospace testing chambers where magnetic interference must be minimized.
The EPA regulates fluorinated gas emissions from industrial processes in the United States, creating compliance-driven replacement demand for ion pump systems in federal research laboratories. REACH and RoHS frameworks in Europe restrict hazardous substances in vacuum equipment components, compelling manufacturers to reformulate cathode materials and magnetic assemblies. The EU AI Act and CSRD disclosure rules will soon require documented energy efficiency metrics for vacuum systems deployed in automated manufacturing lines. Stakeholders must evaluate how evolving material compliance standards will alter cathode replacement economics and service revenue models.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale replacement of fluorinated vacuum systems across European semiconductor fabs and research facilities, compressing replacement cycles and rebalancing supplier relationships toward non-fluorinated ion pump architectures.
Growth Catalysts
- Extreme ultraviolet lithography expansion:Taiwan and South Korea foundries are scaling vacuum infrastructure for sub-3nm node production, creating concentrated demand for ultrahigh vacuum systems capable of maintaining pressures below 10^-11 mbar.
- REACH and RoHS compliance mandates:European manufacturers must reformulate cathode materials and magnetic assemblies, accelerating replacement of legacy pump systems that cannot meet hazardous substance restrictions.
- Particle accelerator modernization:Federal research laboratories in the United States face EPA fluorinated gas emission regulations, driving compliance-driven upgrades to titanium sublimation pump portfolios.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and samarium-cobalt magnet production concentrates in China, exposing ion pump manufacturers to input cost volatility and potential supply disruption.
- Technical limitation in hydrogen pumping:Conventional diode ion pumps exhibit degraded pumping speed for hydrogen isotopes, limiting deployment in fusion research and tritium handling applications.
- Substitution threat from cryogenic pumps:Edwards Vacuum and ULVAC Inc. are advancing cryogenic variants for next-generation lithography systems, potentially displacing magnetic ion pumps in cleanest vacuum applications.
Strategic Opportunities
- Indian semiconductor manufacturing incentives:The country's PLI scheme and semiconductor mission are attracting foundry investment, creating vacuum infrastructure demand in a historically underpenetrated geography.
- EU AI Act and CSRD disclosure alignment:Automated manufacturing lines will soon require documented energy efficiency metrics for vacuum systems, favoring suppliers with integrated monitoring capabilities.
- Space simulation chamber convergence:Aerospace testing facilities are combining ion pump technology with vibration-isolation systems, opening hybrid system architectures for satellite qualification programs.
Industry Challenges
- Specialized vacuum technician scarcity:The intersection of ultrahigh vacuum physics, magnetic field engineering, and semiconductor process knowledge creates a narrow talent pipeline that constrains installation and service capacity.
- Legacy system integration complexity:Research facilities operating 1980s-era accelerators and electron microscopes face incompatible flange standards and control interfaces when upgrading to modern ion pump architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ion Pump Market |
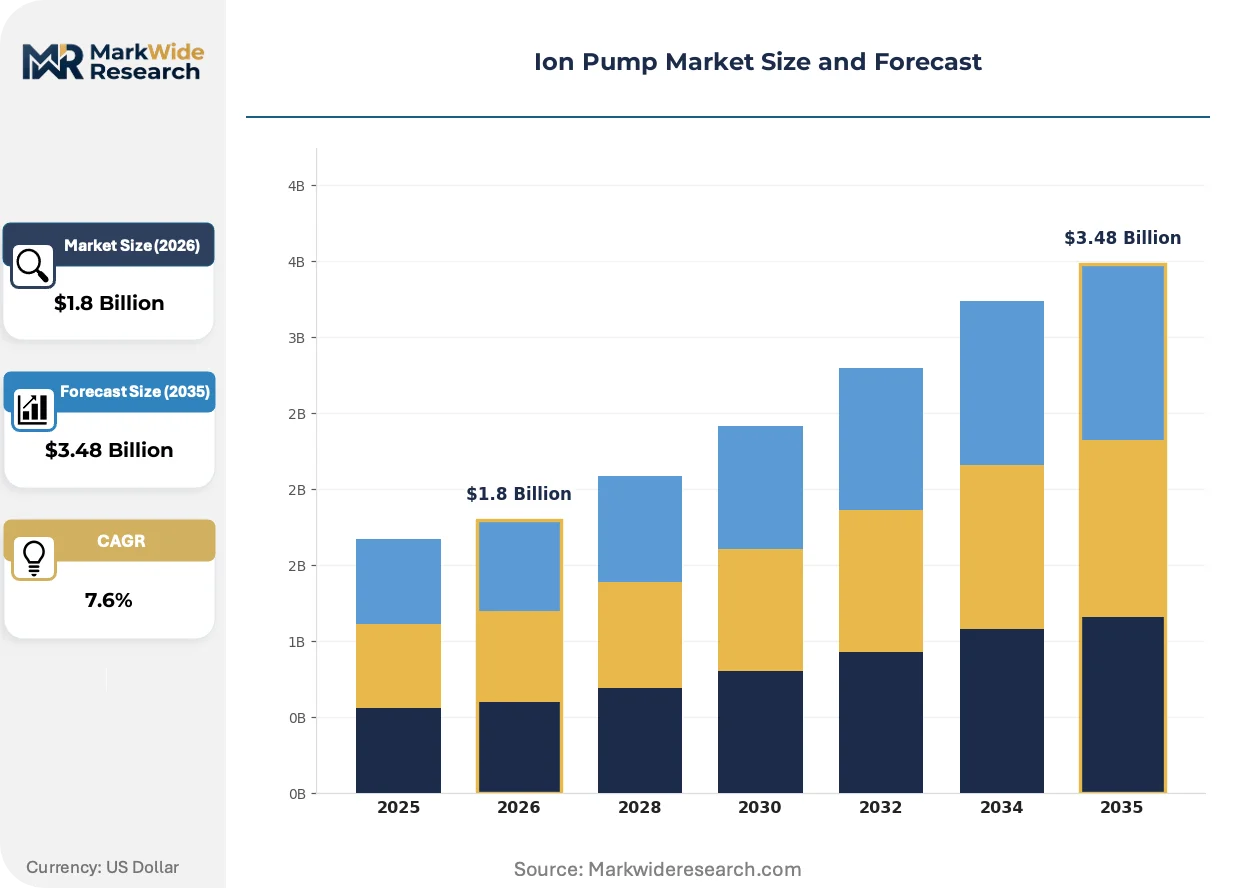
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbo, Scroll, Diaphragm, Titanium Application: Semiconductor Manufacturing, Vacuum Technology, Research Laboratories, Particle Accelerators End User: Healthcare, Aerospace, Industrial, Electronics Technology: Electron, Ionization, Sputtering, Cryogenic |
| Companies Covered | Agilent Technologies, Pfeiffer Vacuum Technology AG, ULVAC Inc., Gamma Vacuum (Atlas Copco Group), Leybold, Edwards Vacuum, Hiden Analytical, Thermionics, KYKY Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ion Pump Market Shifts & Advancements
Active developments across three domains are compressing product lifecycles and reconfiguring competitive positioning: intelligent pump monitoring, regulatory-driven material substitution, and consolidated procurement frameworks among foundry operators.
Smart ion pump controllers with embedded pressure sensing and predictive maintenance algorithms are automating cathode replacement scheduling in continuous-duty research settings. Massachusetts Institute of Technology and CERN facilities are piloting these systems to eliminate unplanned downtime in multi-million dollar experimental campaigns. The technology is automating service revenue models away from scheduled maintenance toward condition-based intervention, compressing supplier-customer interaction cycles.
The EU F-Gas Regulation's phasedown schedule is accelerating titanium cathode adoption as fluorinated greenhouse gas alternatives face elimination from conventional pumping systems. German and French semiconductor fabs must complete infrastructure transitions by 2030, creating a concentrated replacement window. Semiconductor manufacturing applications are most affected, with procurement teams now mandating non-fluorinated vacuum architectures in new equipment specifications.
Foundry operators in Taiwan and South Korea are consolidating vacuum system procurement under single-source framework agreements with integrated service commitments. Equipment OEMs are responding by embedding ion pumps directly into lithography tool platforms rather than selling standalone units. This behavioral shift is most visible in Hsinchu and Pyeongtaek manufacturing clusters, where capital expenditure efficiency priorities override traditional component-level sourcing flexibility.
Ion Pump Market Segmentation
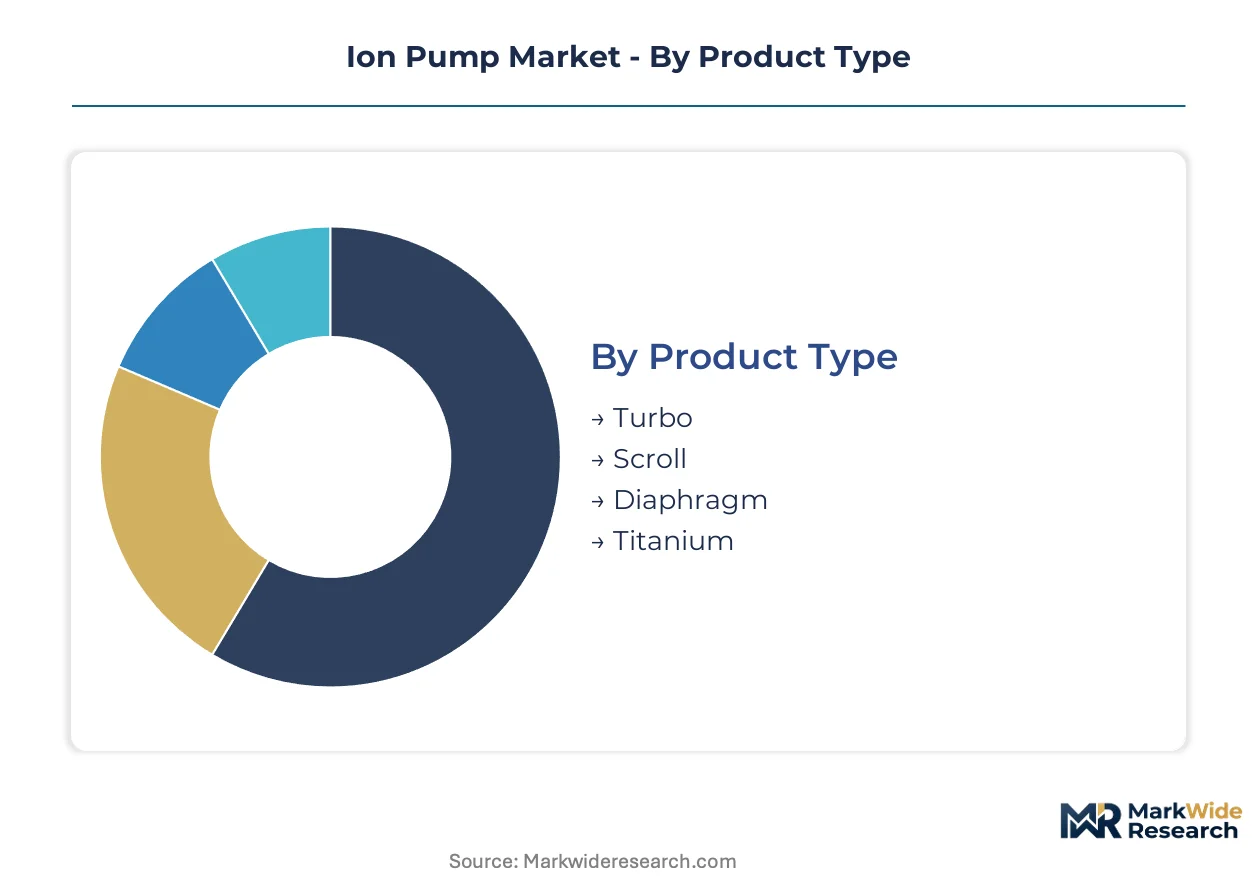
Ion pump procurement patterns diverge sharply across product architectures and end-use environments. Equipment buyers prioritize technical specifications that align with vacuum purity requirements, magnetic interference constraints, and regulatory compliance timelines.
Product Type:
Replacement cycles accelerate as European fabs phase out fluorinated systems under the EU F-Gas Regulation's phasedown schedule.
- Turbo:High-speed molecular drag mechanisms achieve pumping speeds exceeding 1000 L/s for large-volume chambers. Taiwan foundries specify turbo variants for EUV lithography tool backing lines, where contamination tolerance has tightened with each node shrink.
- Titanium:Cathode sublimation surfaces bind reactive gases through chemical gettering, delivering hydrogen pumping speeds unmatched by other architectures. CERN and MIT research facilities specify titanium pumps for continuous-duty particle accelerator operations, where unplanned downtime risks experimental campaign failure.
- Scroll:Orbiting spiral mechanisms provide oil-free roughing without magnetic fields. Semiconductor OEMs embed scroll pumps in metrology tools where electromagnetic interference corrupts sensitive measurements.
- Diaphragm:Flexing membrane designs isolate process gases from lubricants. Industrial coating operations deploy diaphragm pumps for corrosive vapor handling where fluid contamination destroys film quality.
Turbo sits at the top of the volume ranking, with Titanium climbing the fastest.
Application:
Cost tiers separate capital-intensive fab infrastructure from research equipment with discretionary funding cycles.
- Semiconductor Manufacturing:Sub-3nm EUV lithography tools demand base pressures below 10^-11 mbar, requiring multi-stage pump trains with titanium final stages. South Korean foundries in Pyeongtaek concentrate procurement under single-source framework agreements that bundle installation and decade-long service contracts.
- Particle Accelerators:Synchrotron and linear collider vacuum sectors span kilometers of beamline, creating distributed pumping requirements. Federal laboratories face EPA fluorinated gas emission mandates that compress replacement timelines for legacy diffusion pump systems.
- Vacuum Technology:General-purpose coating and deposition equipment serves automotive and architectural glass sectors. Industrial buyers prioritize acquisition cost over ultimate pressure capability, fragmenting supplier relationships.
- Research Laboratories:Electron microscopy and mass spectrometry installations operate intermittently with maintenance windows scheduled around academic calendars. University procurement cycles extend 18-24 months from specification to commissioning.
Semiconductor Manufacturing commands the steepest expansion trajectory, with Particle Accelerators gaining share fastest.
End User:
Customer type determines specification rigor, with certified applications demanding traceable manufacturing documentation.
- Electronics:Foundry operators in Hsinchu and Pyeongtaek specify ion pumps with embedded pressure monitoring and predictive maintenance algorithms. Smart controller integration is becoming mandatory in new equipment specifications.
- Aerospace:Satellite qualification chambers combine ion pumping with active vibration isolation. Testing facilities in the United States and France require pumps certified for thermal vacuum cycling extremes.
- Healthcare:Medical device sterilization and pharmaceutical freeze-drying applications prioritize oil-free operation. FDA validation requirements extend qualification timelines for new pump installations.
- Industrial:Heat treatment and metallurgy sectors tolerate higher base pressures than semiconductor or research applications. Price sensitivity drives procurement toward refurbished equipment and third-party service providers.
Electronics dominates current volume, with Aerospace expanding most quickly.
Technology:
Supply concentration in rare earth magnet production shapes technology selection for magnetic-sensitive environments.
- Electron:Thermionic emission ionizes gas molecules for subsequent burial on cathode surfaces. Standard diode and triode configurations serve electron microscopy installations worldwide.
- Sputtering:Penning discharge variants eliminate thermionic cathodes, reducing power consumption and thermal load. Aerospace testing chambers specify sputtering ion pumps where magnetic field minimization protects sensitive instrumentation.
- Ionization:Radio frequency and microwave excitation methods serve specialized fusion research applications. Hydrogen isotope pumping limitations constrain deployment in tritium handling systems.
- Cryogenic:Condensation on liquid helium-cooled surfaces achieves ultimate pressures rivaling titanium sublimation pumps. Edwards Vacuum and ULVAC Inc. are advancing cryogenic variants for next-generation lithography tools.
Electron leads unit shipments, with Cryogenic gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vacuum technicians cluster in Hsinchu, Dresden, and Silicon Valley, creating narrow talent pipelines that constrain installation capacity across semiconductor manufacturing zones. Their concentration shapes where ion pump suppliers can deploy service networks.
United States
Federal research laboratories in California and Illinois drive demand for titanium sublimation pumps in particle accelerator modernization. The EPA regulates fluorinated gas emissions from industrial processes, compressing replacement timelines for legacy diffusion pump systems. Boston-area research facilities specify smart controllers with predictive maintenance algorithms for electron microscopy installations.
Taiwan
Foundry capital expenditure in Hsinchu anchors concentrated demand for ultrahigh vacuum systems below 10^-11 mbar. The national semiconductor mission channels public investment into vacuum infrastructure scaling. Local procurement teams mandate single-source framework agreements bundling decade-long service contracts for EUV lithography tool platforms.
Germany
Automotive coating operations in Bavaria and Baden-Württemberg deploy oil-free scroll pumps for corrosion-resistant film production. The EU F-Gas Regulation forces wholesale replacement of fluorinated systems by 2030, accelerating titanium cathode adoption. Dresden semiconductor fabs reformulate magnetic assemblies to satisfy REACH substance restrictions.
South Korea
Pyeongtaek foundries scale vacuum infrastructure for sub-3nm node production, creating the fastest-expanding ion pump demand cluster. National industrial policy prioritizes captive supply chain development for semiconductor equipment components. Localized service networks from Japanese OEMs anchor supply relationships in the Seoul Capital Area.
Japan
Electron microscopy manufacturers in Nagoya and Tokyo specify diode and triode configurations for research instrument exports. METI standards guide hazardous substance restrictions in vacuum equipment components. Kyoto-area particle physics facilities pilot intelligent pump monitoring systems to eliminate unplanned experimental downtime.
Ion Pump Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across ion pump architectures. The vendor base spans three tiers: integrated vacuum equipment OEMs embedding pumps directly into lithography platforms, standalone pump specialists serving research facilities, and regional fabricators supplying refurbished industrial units. Two dominant competitive moves are reshaping positioning: foundry-driven procurement consolidation under single-source framework agreements, and technology licensing partnerships for smart controller integration.
Within the integrated equipment tier, Pfeiffer Vacuum Technology AG and ULVAC Inc. exemplify archetypes anchoring supply relationships through localized service networks. Edwards Vacuum occupies a position on the cryogenic variant vector, while Agilent Technologies and Leybold sit within the research instrument bundling segment. KYKY Technology represents the regional fabricator archetype. These five names illustrate how geographic origin and company structure correlate with strategic positioning across semiconductor, research, and industrial end-use segments.
| Leading Market Players |
|---|
| Agilent Technologies |
| Pfeiffer Vacuum Technology AG |
| ULVAC Inc. |
| Gamma Vacuum (Atlas Copco Group) |
| Leybold |
| Edwards Vacuum |
| Hiden Analytical |
| Thermionics |
| KYKY Technology |
| Others |
Supply & Pricing Matrix
Neodymium magnet price indices cascade through ion pump manufacturing into three distinct pricing tiers that separate titanium cathode systems from standard diode configurations and refurbished industrial units. Raw material volatility in rare earth inputs compresses margins at the premium tier while amplifying cost advantages for buyers with decade-long service contracts.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the ion pump market, with foundry operators in Taiwan and South Korea paying premiums for integrated decade-long service commitments while research facilities favor transactional per-unit procurement. Price differentiation hinges on certification grade for EU F-Gas Regulation compliance and geographic proximity to localized service networks. Pricing pressure intensifies as cryogenic pump variants from Edwards Vacuum and ULVAC Inc. encroach on magnetic ion pump territory in EUV lithography applications. Industrial coating operations exhibit highest price sensitivity, tolerating refurbished equipment and third-party service providers rather than OEM premiums.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese neodymium and samarium-cobalt production, with Japanese precision machining and German vacuum engineering completing the value chain. Titanium cathode fabrication draws from aerospace-grade titanium suppliers in the United States and Russia, while magnetic assembly production concentrates in Chinese rare earth processing zones. Single-source vulnerability in magnet supply exposes manufacturers to input cost volatility and potential export restriction scenarios. Distribution runs through semiconductor equipment OEMs embedding pumps directly into lithography platforms rather than standalone component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ion pump market represents a late-cycle quality story where specification premiums widen as EUV lithography nodes demand vacuum purity below 10^-11 mbar. Semiconductor foundries now mandate smart controller integration and predictive maintenance capabilities as baseline procurement criteria.
For Market Incumbents: Acquire specialized vacuum technician training assets to address the talent pipeline constraining installation capacity in Hsinchu, Dresden, and Pyeongtaek. Consolidate service network density around particle accelerator modernization programs in the United States and CERN facilities facing EPA fluorinated gas mandates. Counter cryogenic substitution threats by embedding titanium sublimation pumps directly into next-generation lithography tool platforms through exclusive OEM partnerships. For New Entrants and Emerging Players: Enter via the Indian semiconductor manufacturing corridor where PLI scheme incentives attract foundry investment without entrenched supplier relationships. Target aerospace testing facilities in France and the United States combining ion pumping with vibration-isolation systems for satellite qualification programs. Lead with scroll pump architectures for metrology tools where electromagnetic interference constraints exclude magnetic alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive rare earth magnet sourcing and smart controller software stacks. Long-term viability favors suppliers with demonstrated compliance navigation across REACH, RoHS, and EU AI Act disclosure requirements. Watch for inflection signals in Indian foundry capital expenditure announcements and federal laboratory diffusion pump replacement tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Controller Integration | MIT and CERN pilot predictive maintenance systems eliminating unplanned experimental downtime. |
| Titanium Cathode Capacity Expansion | EU F-Gas Regulation phasedown accelerates non-fluorinated vacuum infrastructure replacement by 2030. |
| Localized Service Network Buildout | Japanese OEMs anchor supply relationships in Seoul Capital Area through captive technician training. |
| Cryogenic Variant Development | Edwards Vacuum advances liquid helium-cooled alternatives for cleanest EUV lithography vacuum conditions. |
| Regulatory Compliance Certification | German fabs reformulate magnetic assemblies to satisfy REACH substance restrictions ahead of deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vacuum equipment OEM procurement directors, semiconductor fab facilities engineers, particle accelerator operations managers, and aftermarket service heads with secondary validation. Trade data from customs records, SEC filings from listed vacuum technology suppliers, EPA emission compliance databases, and EU regulatory implementation timelines anchored volume estimates. Bottom-up pump shipment tallies by product architecture triangulated against top-down foundry capital expenditure allocations across the analysis window.
Segment-weighting approaches distributed value across titanium, turbo, scroll, and diaphragm product types with semiconductor manufacturing, particle accelerator, and research laboratory applications calibrated separately. Electron, sputtering, ionization, and cryogenic technology trajectories modeled distinct replacement cycle dynamics. CAGRs derived from installed base turnover rates and regulatory compliance deadline clustering rather than extrapolated trend lines. Forecast inputs incorporated EU F-Gas Regulation implementation pace and rare earth magnet price volatility assumptions.
The model holds under stable rare earth supply conditions and continued EUV lithography node progression; deviation in Chinese export restriction triggers or fusion research funding shifts would revise trajectory. Forecasts reflect documented assumptions regarding technician training pipeline expansion and foundry procurement consolidation behavior. A small set of triggers warrants ongoing watch: Indian PLI scheme disbursement timing, EPA enforcement intensity on federal laboratory emissions, and cryogenic pump technical advancement in sub-3nm vacuum applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market