
 Global Self Priming Pumps Market | 2026-2036
Global Self Priming Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self Priming Pumps Market Intelligence
EPA effluent limitations under the Clean Water Act are repositioning the cost-of-entry calculus for pump manufacturers serving North American municipal contracts. Xylem Inc. leverages its vertical integration across smart monitoring platforms to sustain premium positioning in specification-driven bids. Gorman-Rupp anchors its competitiveness in cast iron self-priming designs for agricultural drainage, while Grundfos Holding A/S differentiates through high-efficiency permanent magnet motor integration.
Self priming pumps are centrifugal or positive-displacement devices engineered to evacuate air from the suction line and create sufficient vacuum for liquid lift without external priming assistance, typically achieving suction lifts of 25 feet or more depending on impeller design and fluid vapor pressure. Their primary industrial purpose centers on intermittent-duty applications—construction dewatering, emergency flood control, and mobile wastewater bypass—where operator presence cannot guarantee manual priming protocols. Centrifugal pumps occupy the dominant share of product type revenue due to their versatility across clean water and light slurry services, while diaphragm pumps capture niche margin pools in chemical transfer where air-lock immunity proves critical. The water and wastewater industry vertical leads end-use demand structurally, though oil and gas applications in remote wellpad dewatering represent a faster-growing specification segment.
REACH chemical compliance and EU F-Gas Regulation constrain material selection and sealing technologies for pumps sold into European process industries, while India's BIS certification mandates for potable water contact surfaces shape import eligibility for foreign OEMs. The US EPA's Energy Star program for pump systems is tightening test protocols that determine qualification for federal procurement preferences. Stakeholders must monitor how tightening carbon border adjustment mechanisms in Europe and Asia-Pacific will recalibrate total cost-of-ownership calculations for cast iron versus stainless steel wet-end configurations.
Market Dynamics
Self-priming pump OEMs face a structural pivot as EPA effluent rules and EU Green Deal water reuse mandates force wet-end redesigns for hydraulic efficiency, while procurement in India's industrial corridors concentrates demand around smart city sewage infrastructure.
Growth Catalysts
- Smart city sewage mandates:State-level directives in Gujarat and Maharashtra require robust self-priming infrastructure for municipal wastewater networks, pulling specification-grade units into procurement pipelines.
- REACH chemical compliance:European process industries must source pumps with certified sealing technologies and compliant material selections, creating specification premiums for qualified suppliers.
- Remote wellpad dewatering:Oil and gas operators in isolated extraction sites specify portable self-priming units for intermittent-duty applications where manual priming is operationally impractical.
Market Restraints
- Cast iron input volatility:Foundry-grade pig iron and scrap metal price swings compress margin stability for wet-end manufacturers serving cost-sensitive agricultural drainage segments.
- Permanent magnet supply concentration:Rare earth processing capacity clusters in China creates upstream dependency risk for high-efficiency motor integration programs.
- Suction lift physics ceiling:Atmospheric pressure limits practical lift heights to approximately 25 feet for water at standard conditions, constraining application range against submersible alternatives.
Strategic Opportunities
- Carbon border adjustment positioning:European CBAM implementation recalibrates total cost-of-ownership calculations, favoring stainless steel wet-end configurations with embedded emissions transparency.
- Mobile wastewater bypass:Emergency flood control and construction dewatering contractors seek rental fleet expansion with telemetry-enabled self-priming units for real-time performance monitoring.
- BIS certification arbitrage:India's mandatory potable water contact surface standards create import eligibility barriers that domestic assembly partnerships can circumvent for foreign OEMs.
Industry Challenges
- Hydraulic engineer scarcity:Specialized impeller design expertise for variable suction lift conditions commands premium compensation, constraining R&D throughput at mid-cap manufacturers.
- Legacy control system integration:Municipal wastewater plants with SCADA architectures built on proprietary protocols face commissioning friction when retrofitting smart monitoring pump platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self Priming Pumps Market |
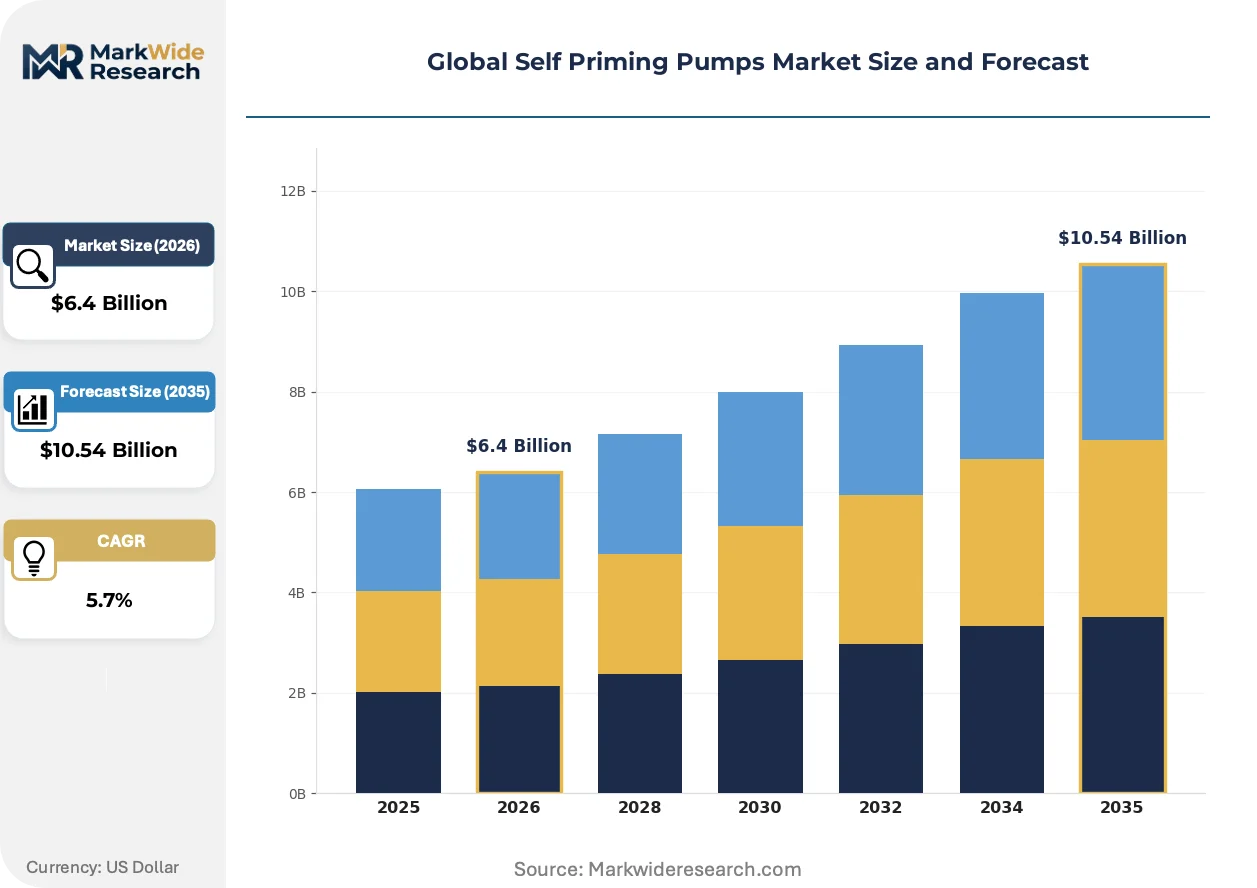
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Diaphragm Pumps, Gear Pumps, Screw Pumps Industry Vertical: Water & Wastewater, Oil & Gas, Agriculture, Chemicals End User: Residential, Commercial, Industrial, Municipal Material: Stainless Steel, Plastic, Cast Iron, Bronze |
| Companies Covered | Xylem Inc., Gorman-Rupp, Grundfos Holding A/S, KSB SE & Co. KGaA, Sulzer Ltd., Kirloskar Brothers Limited, Flowserve, ANDRITZ, BBA Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self Priming Pumps Market Strategic Shifts & Innovations
Digitalization of pump performance monitoring and permanent magnet motor integration are compressing energy intensity benchmarks while regulatory chemistry constraints reshape material selection protocols across manufacturing bases.
Variable frequency drive integration with self-priming centrifugal units is automating suction lift optimization across fluctuating demand curves. Municipal wastewater operators in Germany and the Netherlands are specifying VFD-equipped packages for diurnal flow variation management. This automation is compressing energy consumption differentials between premium and standard efficiency tiers, eroding historical price-performance segmentation.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based sealing compounds from pump manufacturing processes. Wet-end OEMs serving European process industries are reformulating elastomer specifications to perfluoropolyether and hydrofluoroolefin alternatives. Chemical transfer applications in France and Belgium face the steepest compliance timelines, accelerating qualification cycles for fluorine-free sealing architectures.
Specification-driven buyers are unbundling aftermarket service contracts from initial equipment procurement. Water and wastewater utilities in Denmark and Sweden now tender maintenance separately through framework agreements with independent service providers. This disintermediation is compressing OEM service revenue streams while expanding third-party parts market penetration in Nordic municipal segments.
Global Self Priming Pumps Market Segmentation
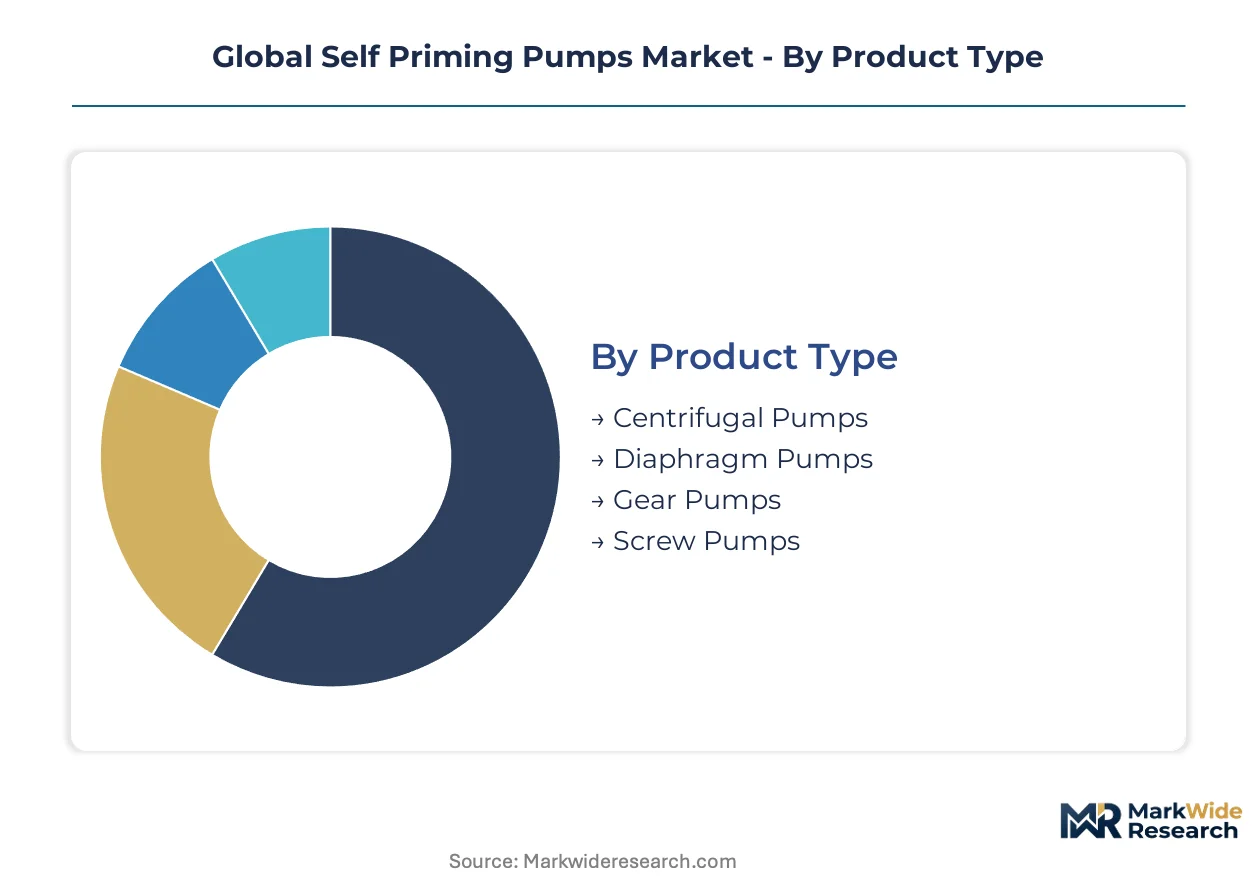
Self-priming pump procurement varies sharply by technical specification, duty cycle, and regulatory exposure. Buyers prioritize hydraulic efficiency curves in municipal wastewater contracts while agricultural operators optimize for capital cost and field portability.
Product Type:
Impeller geometry and priming mechanism architecture differentiate performance ceilings and maintenance intervals across buyer categories.
- Centrifugal Pumps:Volute casing designs with semi-open or enclosed impellers evacuate suction lines through recirculation ports, achieving 25-foot lifts without external priming. Municipal wastewater treatment plants in Germany and the Netherlands specify these units for diurnal flow variation management under EU Green Deal efficiency mandates.
- Diaphragm Pumps:Positive-displacement air-operated designs eliminate mechanical seals entirely, rendering them immune to dry-run damage and chemical attack. Chemical transfer operations in France and Belgium favor these architectures where REACH compliance constrains elastomer selection and air-lock immunity proves critical.
- Gear Pumps:Intermeshing rotor designs deliver precise volumetric metering for viscous fluids and lubricating oils.
- Screw Pumps:Progressive cavity configurations handle high-solids slurries with minimal shear damage to pumped media.
Centrifugal pumps lead volumes today; diaphragm pumps are gaining share fastest.
Industry Vertical:
Regulatory stringency and infrastructure investment cycles create divergent specification premiums across end-use sectors.
- Water & Wastewater:Variable suction lift requirements in intermittent-duty bypass operations demand robust self-priming capability without operator attendance. Smart city sewage mandates in Gujarat and Maharashtra pull specification-grade centrifugal units into procurement pipelines for municipal network expansion.
- Oil & Gas:Remote wellpad dewatering in isolated extraction sites requires portable, explosion-rated units where manual priming is operationally impractical and maintenance access is limited.
- Agriculture:Seasonal drainage contractors prioritize cast iron wet-ends for cost-sensitive field deployment.
- Chemicals:Process industries specify corrosion-resistant materials and fluorine-free sealing architectures under EU F-Gas phase-down schedules.
Water and wastewater dominates revenue today; oil and gas shows the steepest expansion trajectory.
End User:
Procurement sophistication and lifecycle cost visibility separate specification-driven buyers from price-sensitive purchasers.
- Industrial:Manufacturing facilities with continuous process streams demand high-availability pumping with predictive maintenance integration. Energy Star qualification for pump systems shapes federal procurement preferences in US industrial contracts.
- Municipal:Public wastewater utilities tender through framework agreements with independent service providers, compressing OEM service revenue while expanding third-party parts penetration.
- Commercial:Building services contractors specify compact self-priming units for HVAC condensate and stormwater management.
- Residential:Homeowner purchases concentrate in sump and sewage ejector applications with limited suction lift requirements.
Industrial end users command premium pricing today; municipal procurement is climbing the fastest.
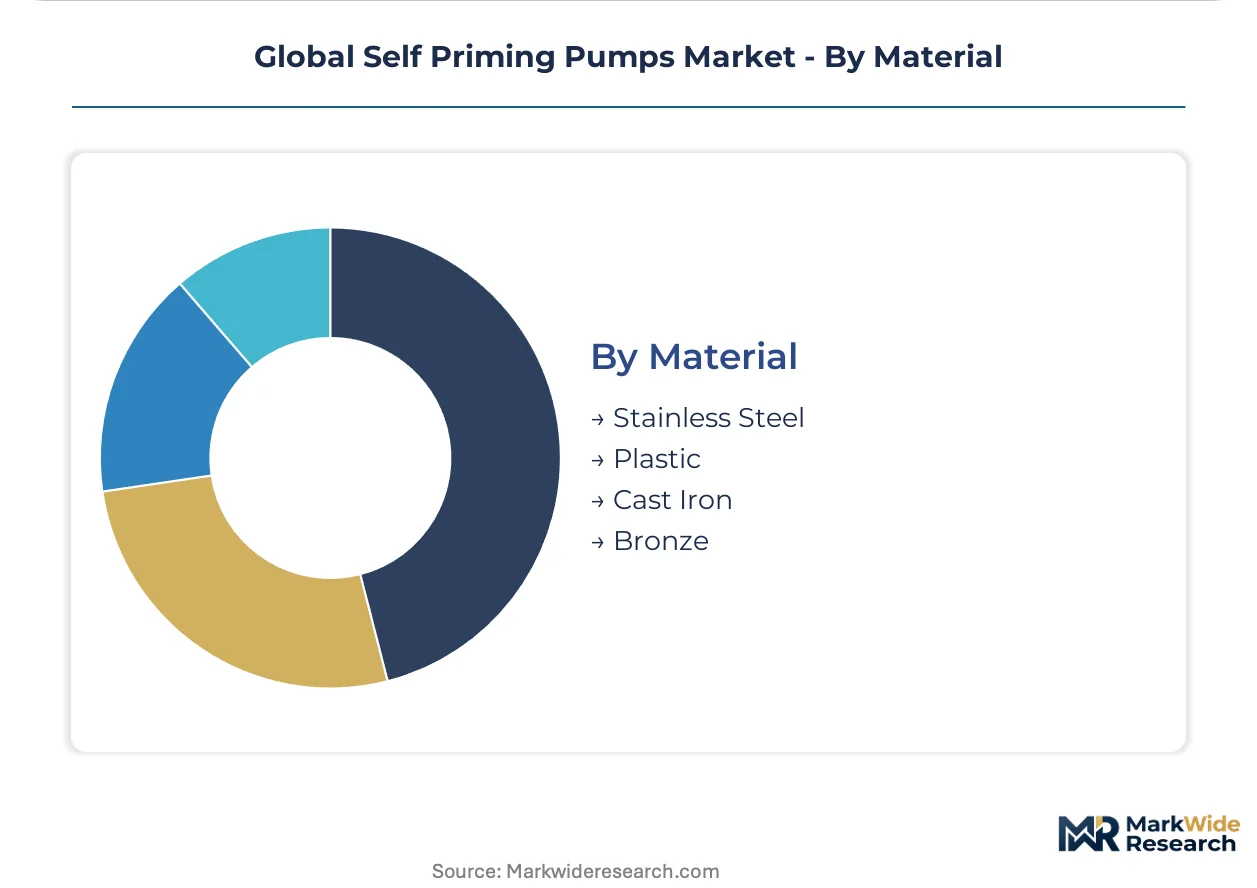
Material:
Wet-end composition determines corrosion resistance, weight, and embedded carbon intensity across regulatory jurisdictions.
- Cast Iron:Foundry-grade pig iron construction delivers cost-effective abrasion resistance for agricultural drainage and construction dewatering. Foundry input volatility compresses margin stability for manufacturers serving price-sensitive segments.
- Stainless Steel:Austenitic and duplex grades provide potable water compatibility and chemical process resistance. European carbon border adjustment mechanisms recalibrate total cost-of-ownership calculations in favor of emissions-transparent stainless configurations.
- Plastic:Thermopolymer housings reduce weight for portable applications and eliminate galvanic corrosion in marine environments.
- Bronze:Naval alloy compositions resist seawater corrosion in coastal and offshore installations.
Cast iron leads installed base today; stainless steel is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydraulic engineers concentrate in Germany's Ruhr industrial basin and India's Pune-Ahmedabad corridor, anchoring wet-end design capabilities that migrate through multinational engineering subsidiaries into regional specification standards.
United States
Municipal wastewater utilities in Texas and Florida are expanding self-priming procurement for hurricane-resilient bypass infrastructure. EPA effluent limitations under the Clean Water Act are tightening qualification thresholds for federal procurement preferences. The Gulf Coast petrochemical corridor around Houston drives specification-grade demand for explosion-rated portable units in refinery turnaround operations.
Germany
Variable frequency drive integration dominates municipal tender specifications in North Rhine-Westphalia and Bavaria for diurnal flow optimization. EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon sealing compounds from manufacturing processes. The Ruhr industrial basin hosts concentrated wet-end engineering talent pools that supply design capabilities to pan-European OEM operations.
India
Smart city sewage mandates in Gujarat and Maharashtra are pulling specification-grade centrifugal units into municipal procurement pipelines. BIS certification requirements for potable water contact surfaces shape import eligibility and incentivize domestic assembly partnerships. The Pune-Ahmedabad industrial corridor clusters foundry capacity and hydraulic engineering expertise serving both domestic and export markets.
China
Rare earth processing capacity concentration creates upstream dependency for permanent magnet motor integration programs. The country's national environmental regulator is tightening industrial wastewater discharge standards that elevate pump efficiency requirements. Yangtze River Delta manufacturing bases supply cast iron wet-end components to mid-tier global OEMs.
Netherlands
Water and wastewater utilities in Randstad municipalities are unbundling aftermarket service contracts from initial equipment procurement through framework agreements. EU Green Deal water reuse targets are accelerating specification of high-efficiency permanent magnet configurations. The Eindhoven region hosts smart monitoring platform development that integrates with specification-grade pump packages.
Global Self Priming Pumps Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered specification segments. The vendor base organizes around three strategic archetypes: integrated flow control conglomerates with smart monitoring platforms, foundry-anchored wet-end specialists serving cost-sensitive agricultural drainage, and high-efficiency motor integrators targeting premium municipal efficiency mandates. Dominant competitive moves include backward integration into permanent magnet supply chains and geographic expansion through domestic assembly partnerships to circumvent import certification barriers.
Among Danish and German pump engineering groups, Grundfos Holding A/S and KSB SE & Co. KGaA occupy positions emphasizing high-efficiency motor integration and specification-grade municipal tenders. Xylem Inc. represents the integrated flow control archetype with smart monitoring capabilities. Gorman-Rupp anchors the foundry-specialist tier serving North American agricultural and construction dewatering segments. Kirloskar Brothers Limited exemplifies domestic assembly strategies that navigate India's BIS certification requirements for foreign OEM market access.
| Leading Market Players |
|---|
| Xylem Inc. |
| Gorman-Rupp |
| Grundfos Holding A/S |
| KSB SE & Co. KGaA |
| Sulzer Ltd. |
| Kirloskar Brothers Limited |
| Flowserve |
| ANDRITZ |
| BBA Pumps |
| Others |
Cost & Logistics Intelligence
Specialized hydraulic engineers concentrated in Germany's Ruhr basin and India's Pune-Ahmedabad corridor anchor labor-cost differentials that widen pricing-tier spreads between specification-grade municipal units and economy agricultural models. Foundry-grade pig iron volatility and rare earth magnet supply concentration further stratify cost structures across premium permanent-motor configurations and standard cast iron wet-ends.
Pricing Analysis
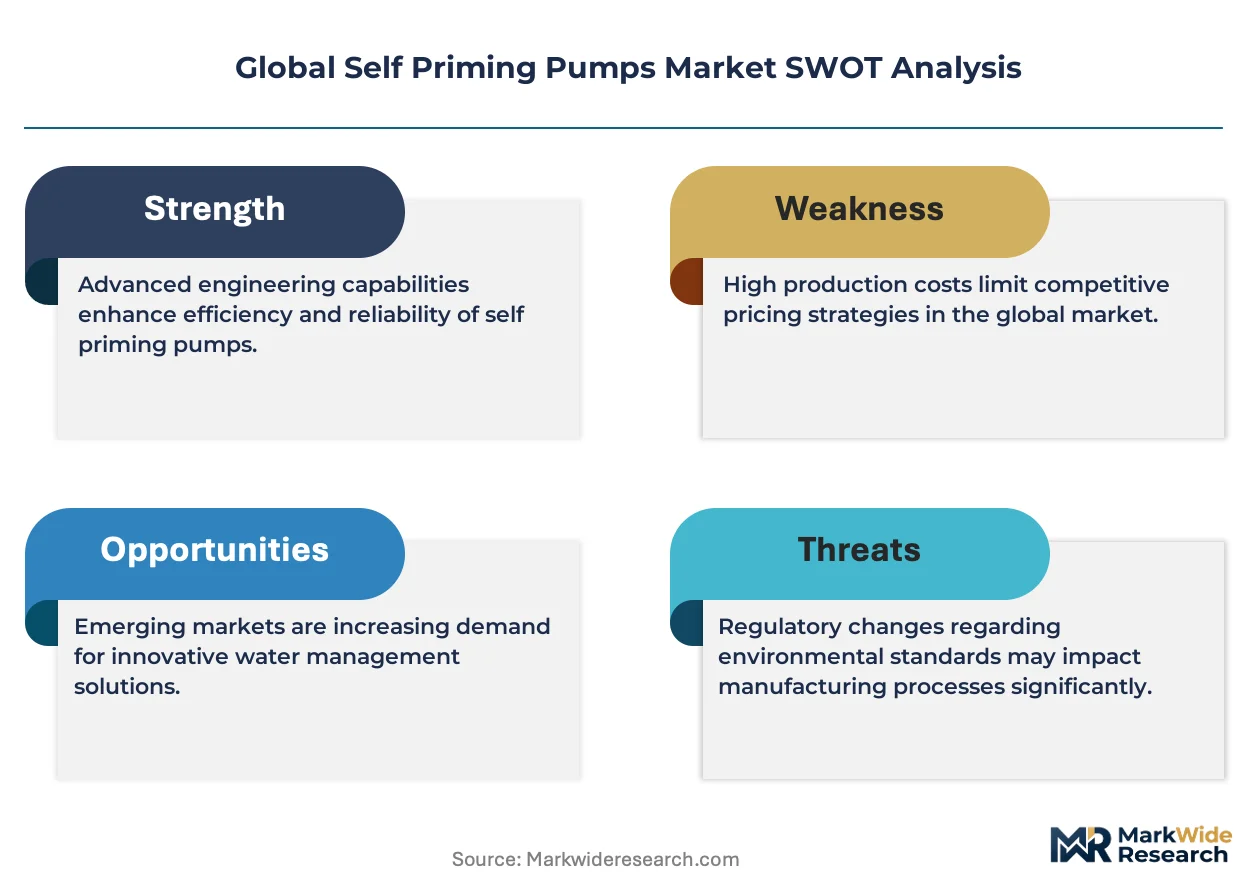
The bundled-versus-unbundled service split now defines transaction architecture. Specification-grade centrifugal packages for municipal wastewater tenders carry premium positioning through integrated smart monitoring and aftermarket service contracts, while agricultural drainage contractors procure bare units through distributor channels with minimal support attachment. Price differentiation hinges on Energy Star qualification tier and hydraulic efficiency certification level. Cost compression in economy cast iron segments intensifies because foundry input volatility erodes manufacturer margin buffers. Agricultural end users exhibit highest price sensitivity; municipal utilities with federal procurement preferences show lowest.
Supply Chain Analysis
Workforce availability constraints in Germany's engineering clusters and China's rare earth processing zones shape manufacturing geography decisions. Supply concentrates in China for permanent magnet motor components, India for foundry-grade cast iron wet-ends, and Germany for precision impeller machining. Raw material dependencies include neodymium-iron-boron magnet alloys, foundry-grade pig iron, and fluorine-free elastomer formulations. Single-source vulnerability in rare earth processing creates upstream risk for high-efficiency motor programs. Distribution runs through OEM-direct specification sales for municipal tenders and independent distributor networks for agricultural replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA effluent limitations and EU Green Deal water reuse mandates mechanically expand specification-grade demand. Procurement velocity in India's smart city corridors accelerates contract flow for qualified suppliers.
For Market Incumbents: Deploy permanent magnet motor integration programs to defend specification-grade positioning against emerging high-efficiency specialists. Incumbents must anchor backward integration into rare earth magnet supply chains to offset Chinese processing concentration risk. Channel control through exclusive municipal service partnerships protects aftermarket revenue streams from independent provider disintermediation.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in portable dewatering units creates white-space opportunity for mid-tier challengers. New entrants should target India's BIS certification arbitrage through domestic assembly partnerships circumventing import eligibility barriers. Construction dewatering rental fleet expansion offers the most penetrable application segment. A telemetry-enabled fleet-as-a-service go-to-market angle bypasses capital-intensive OEM manufacturing requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among foundry-anchored wet-end specialists serving agricultural drainage segments. Long-term viability favors manufacturers with emissions-transparent stainless steel configurations positioned for European carbon border adjustment mechanics. Acquisition targets should display embedded hydraulic engineering talent pools in Germany or India. The signal to watch is BIS certification timeline acceleration triggering domestic partnership premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Energy Star qualification tiers reshape municipal procurement preferences across North American utilities. |
| Domestic Assembly Partnership Formation | BIS certification arbitrage unlocks import-constrained demand in India's smart city corridors. |
| Fluorine-Free Sealing Architecture Development | EU F-Gas Regulation phase-down eliminates hydrofluorocarbon compounds from European process industry supply. |
| Telemetry-Enabled Fleet Rental Expansion | Real-time performance monitoring differentiates bypass contractors in emergency flood control applications. |
| Rare Earth Magnet Supply Anchoring | Upstream control over neodymium processing mitigates dependency risk for high-efficiency motor programs. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's municipal procurement clusters. The analysis combines structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners alongside secondary validation through customs records, EPA enforcement databases, and EU ETS emissions disclosures. Bottom-up unit shipment modeling triangulates against top-down value estimates derived from tender documentation and framework agreement values.
Granularity-level framing applies product type, material grade, end-use vertical, and regional regulatory cluster as core segmentation dimensions. The analytical framework projects volume and value outputs across the modeling period through regression-based demand elasticity modeling and infrastructure investment pipeline tracking. CAGRs derive from segment-level growth rate reconciliation against macroeconomic indicators and policy implementation schedules. Industry-specific forecast inputs include smart city sewage mandate procurement timelines and permanent magnet motor adoption curves.
Caveats apply where rare earth export restriction escalation, foundry input price spikes, or municipal budget freeze triggers could materially shift the outlook. Forecasts embed assumptions regarding regulatory implementation pacing and infrastructure funding continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market