
 Vacuum Pump Stations Market | 2026-2036
Vacuum Pump Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Pump Stations Market Insights
German vacuum pump engineering is broadening its addressable base as Asian semiconductor capital expenditure scales. Atlas Copco leverages its compressor-to-vacuum technology platform to cross-sell integrated station packages across process industries. Busch Vacuum Solutions anchors European demand through its oil-free claw and screw pump architectures purpose-built for food and pharmaceutical cleanrooms. Edwards Vacuum dominates high-vacuum subsystems for semiconductor fabrication, sustaining R&D intensity in magnetically levitated turbopump integration.
Vacuum pump stations are engineered pressure-reduction systems comprising multiple pump stages, control instrumentation, and gas handling modules that evacuate process chambers to operational vacuums ranging from rough (10^-3 mbar) to high/ultra-high regimes (10^-7 to 10^-11 mbar). These systems serve semiconductor wafer processing, chemical vapor deposition, and freeze-drying operations where precise atmosphere control determines yield and product integrity. Dry vacuum pump configurations lead product type demand as semiconductor fabs eliminate hydrocarbon contamination risks from oil-sealed architectures. Oil-free scroll and claw technologies within the technology dimension command premium positioning due to their compatibility with cleanroom protocols and aggressive chemical process streams. Chemical processing and semiconductor fabrication use cases concentrate margin pools, while wastewater treatment applications represent a volume-driven, specification-tolerant segment.
EPA emissions standards and OSHA workplace exposure limits in the United States shape leak-tightness and vapor recovery requirements for chemical processing installations. REACH substance restrictions and CE machinery directives in Europe constrain seal materials and lubricant formulations used in pump station construction. China's SAMR energy efficiency labeling and MEE pollution discharge rules tighten operational parameters for domestic and imported equipment alike. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions, as fluoropolymer seals and lubricants face prospective substitution mandates that could alter pump station design architectures and aftermarket service economics.
Market Dynamics
Semiconductor fabrication's contamination intolerance is forcing a wholesale migration from oil-sealed to dry vacuum architectures, compressing replacement cycles and elevating specification thresholds across process industries.
Growth Catalysts
- GB standards compliance:China's dual carbon goals and SAMR energy efficiency labeling mandate equipment upgrades across industrial parks, pulling demand for high-efficiency pump stations.
- Flat-panel display expansion:OLED manufacturing lines in Taiwan and South Korea require ultra-clean vacuum environments, accelerating procurement of oil-free scroll and claw pump systems.
- Freeze-drying pharmaceutical protocols:FDA and EMA sterility requirements for biologics storage are extending vacuum pump station deployment into cold chain infrastructure.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnets for high-efficiency motors concentrate in Chinese processing facilities, exposing pump manufacturers to input volatility and export restriction risk.
- PFAS seal material substitution timeline:REACH restrictions and prospective EPA action on fluoropolymers are compressing R&D budgets as engineers validate alternative elastomer chemistries.
- High-vacuum turbopump technical ceiling:Magnetically levitated bearing systems face reliability thresholds below 10^-9 mbar, limiting addressable market in particle physics and space simulation.
Strategic Opportunities
- Hydrogen economy infrastructure:Electrolyzer and fuel cell manufacturing in Germany and Japan requires specialized vacuum stations for membrane coating and leak testing.
- Service contract unbundling:Predictive maintenance platforms using vibration analytics are creating recurring revenue streams separate from equipment sales.
- Carbon border adjustment mechanism:EU CBAM implementation incentivizes local production of energy-efficient vacuum equipment to avoid embodied carbon tariffs on imports.
Industry Challenges
- Vacuum engineering talent scarcity:Specialized knowledge in molecular flow dynamics and cryogenic pump integration is concentrating at a handful of academic programs in the United States and Germany.
- Legacy system interoperability:Semiconductor fabs running 200mm wafer lines face integration friction when retrofitting dry pumps into toolsets designed for oil-sealed architectures.
- CE-MDR certification timelines:European machinery directive conformity assessment periods have extended 40% since 2021, delaying market entry for new pump station configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Pump Stations Market |
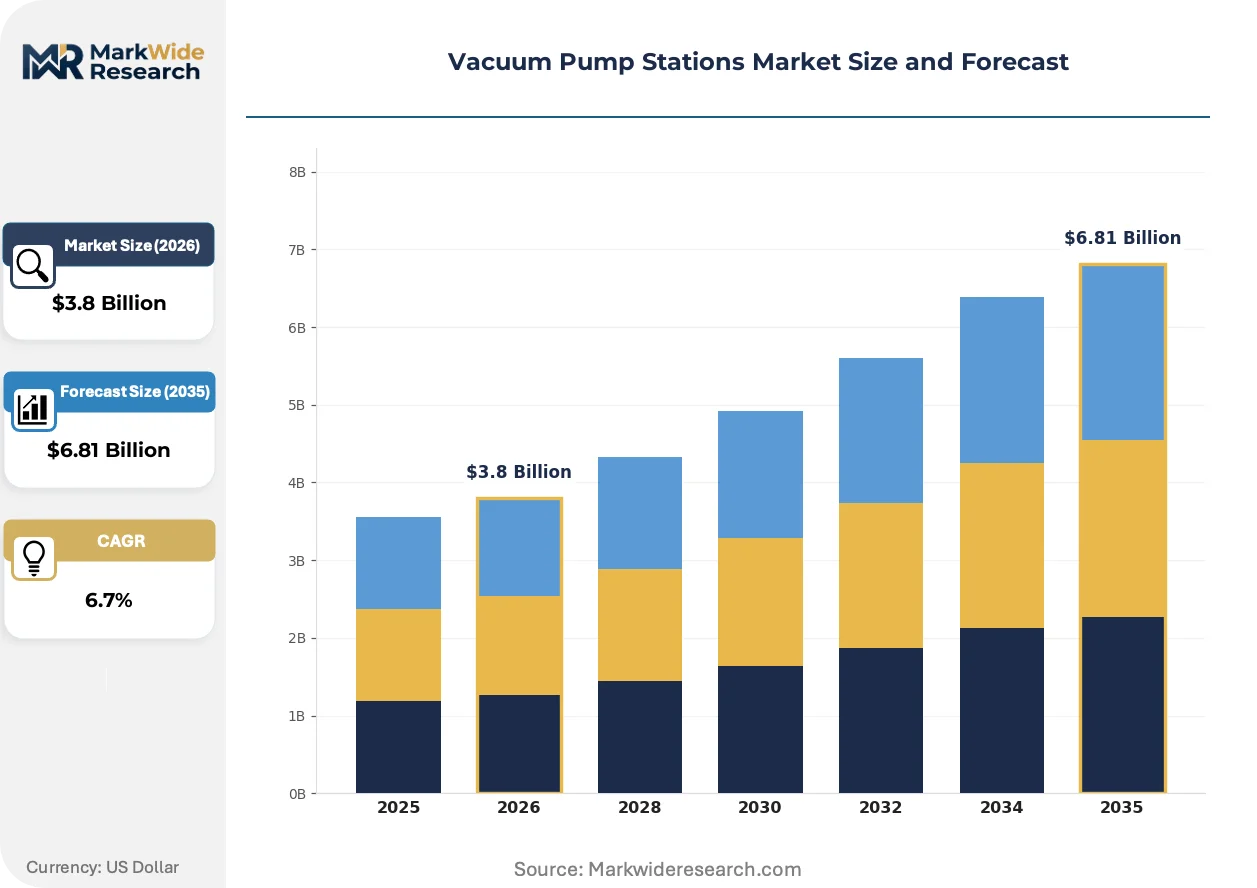
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Vacuum Pumps, Wet Vacuum Pumps, Two-Stage Vacuum Pumps, Rotary Vane Pumps, Liquid Ring Pumps Technology: Oil-Sealed, Oil-Free, Diaphragm Vacuum, Scroll Vacuum, Claw Vacuum Use Case: Food Processing, Semiconductor Fabrication, Paper Manufacturing, Chemical Processing, Wastewater Treatment End User: Cement Manufacturers, Pharmaceutical Firms, Pulp & Paper Mills, Plastic Producers, Textile Plants |
| Companies Covered | Atlas Copco, Busch Vacuum Solutions, Edwards Vacuum, Pfeiffer Vacuum+Fab Solutions, Leybold, ULVAC, Elmo Rietschle, Becker Pumps, Gardner Denver, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Pump Stations Market Trends and Innovations
Dry vacuum technologies are compressing the competitive set as contamination-sensitive processes eliminate legacy architectures. Control system intelligence and regulatory chemistry mandates are simultaneously reshaping product roadmaps and service economics.
Magnetically levitated turbopump arrays are overtaking oil-lubricated diffusion pumps in semiconductor etch and deposition tools. Foundries in Taiwan and South Korea specify mag-lev systems for 5nm and below process nodes. The technology is overtaking mechanical bearing systems by eliminating particulate generation and extending mean time between maintenance by 300%.
REACH substance restrictions on PFAS and fluorinated lubricants are forcing seal material redesigns across European-manufactured pump stations. Compound semiconductor and photovoltaic manufacturers face the steepest compliance burden. German and French producers are accelerating validation of perfluoropolyether alternatives and graphite-based dry running seals.
Integrated vacuum stations with embedded IoT sensors are displacing standalone pump installations monitored through separate control systems. Semiconductor capital equipment buyers in East Asia now specify Ethernet-IP connectivity and cloud-native diagnostics as standard. Equipment-as-a-service contracts are capturing 15-20% of new installations in pharmaceutical freeze-drying, transferring operational risk from plant operators to OEM service organizations.
Vacuum Pump Stations Market Segmentation
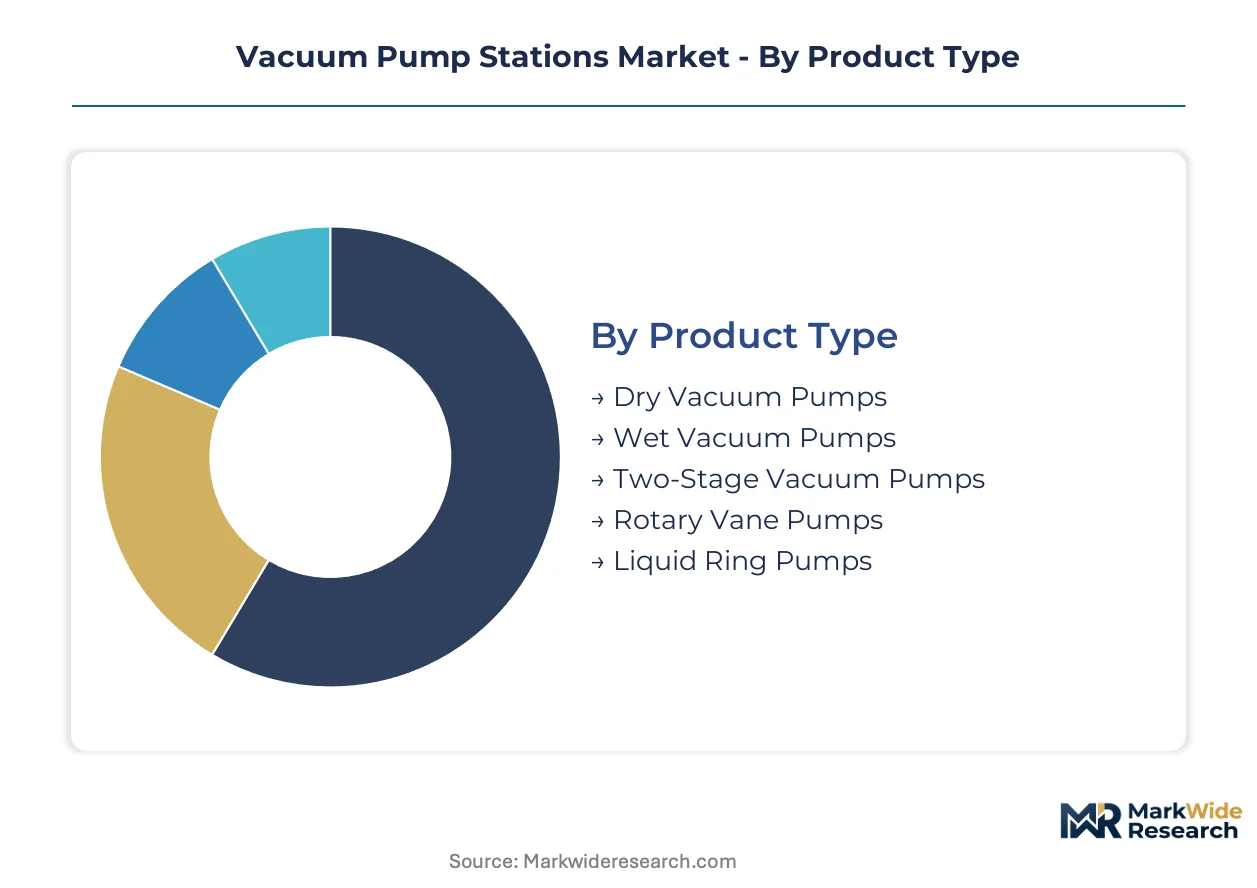
Vacuum pump station specifications diverge sharply across contamination tolerance thresholds and process pressure regimes. Semiconductor fabs demand oil-free architectures incompatible with legacy chemical processing installations. Understanding segment boundaries reveals where technology substitution creates displacement risk versus incremental upgrade cycles.
Product Type:
Dry vacuum architectures dominate procurement specifications where hydrocarbon contamination risks disqualify oil-sealed alternatives.
- Dry Vacuum Pumps:Non-contact pumping mechanisms eliminate lubricant vapor backstreaming into process chambers. Taiwan and South Korea foundries specify dry scroll and claw configurations for 5nm node production, where molecular contamination destroys wafer yields.
- Wet Vacuum Pumps:Liquid-sealed compression chambers handle saturated vapor loads and condensable process gases. Chemical processing plants in Germany deploy liquid ring variants for solvent recovery applications where explosive vapor mixtures require flameproof construction.
- Two-Stage Vacuum Pumps:Serial pump configurations achieve deeper ultimate vacuums than single-stage architectures. Laboratory freeze-drying operations specify these for pharmaceutical stability testing protocols.
- Rotary Vane Pumps:Sliding vane mechanisms in oil-bathed housings deliver cost-effective rough vacuum. Legacy toolsets in 200mm semiconductor fabs retain these for non-critical backing pump duties.
- Liquid Ring Pumps:Impeller-driven liquid pistons compress gases without internal lubrication. Wastewater treatment facilities specify these for biogas extraction where particulate tolerance outweighs energy efficiency priorities.
Dry vacuum pumps lead on scale; wet vacuum pumps lead on momentum in chemical processing retrofit cycles.
Technology:
Seal chemistry and bearing architecture determine compliance trajectories under tightening PFAS restrictions.
- Oil-Sealed:Hydrocarbon lubricants enable tight clearances and high compression ratios in rotary vane and piston architectures. REACH substance restrictions are compressing addressable market share as semiconductor fabs eliminate oil-based systems entirely.
- Oil-Free:Dry-running mechanisms using precision-machined scrolls, claws, or screws eliminate lubricant contamination pathways. FDA and EMA sterility requirements for biologics manufacturing are accelerating pharmaceutical adoption.
- Diaphragm Vacuum:Elastomeric membrane compression isolates process gases from mechanical wear surfaces. Analytical instrumentation OEMs specify these for mass spectrometer foreline pumping where chemical inertness is mandatory.
- Scroll Vacuum:Interleaved spiral orbiting mechanisms achieve oil-free compression with minimal particulate generation. Flat-panel display manufacturing lines in South Korea specify these for OLED deposition chambers.
- Claw Vacuum:Non-contacting rotor profiles handle aggressive chemical process streams without seal degradation. Compound semiconductor fabs processing gallium arsenide wafers favor claw architectures for hydrogen chloride tolerance.
Oil-free technology leads on scale; scroll vacuum leads on momentum in display manufacturing expansion.
Use Case:
Process contamination tolerance and vacuum depth requirements segment procurement specifications across industrial verticals.
- Food Processing:Vacuum packaging and freeze-drying operations require oil-free compression to prevent flavor contamination. HACCP protocols in EU meat processing facilities mandate stainless steel pump construction with CIP compatibility.
- Semiconductor Fabrication:Etch, deposition, and ion implantation tools demand ultra-clean vacuum environments. Taiwan foundries specify mag-lev turbopump stations for advanced node production where particle counts below 0.1 per cubic foot determine yield economics.
- Paper Manufacturing:Dewatering and deaeration applications tolerate oil-sealed architectures where process contamination risks are absent. Pulp mills specify liquid ring pumps for black liquor evaporation duties.
- Chemical Processing:Distillation and solvent recovery operations require corrosion-resistant materials and vapor recovery integration. EPA emissions standards in the United States mandate leak-tightness verification for toxic chemical handling.
- Wastewater Treatment:Biogas extraction and sludge dewatering prioritize capital cost over energy efficiency. Municipal facilities specify robust liquid ring configurations with minimal maintenance intervals.
Semiconductor fabrication leads on scale; food processing leads on momentum in cold chain infrastructure expansion.
End User:
Capital intensity and regulatory exposure differentiate procurement patterns across manufacturing verticals.
- Cement Manufacturers:Pneumatic conveying and kiln gas evacuation applications tolerate specification-tolerant equipment. Chinese industrial parks under GB standards compliance mandates are upgrading legacy installations for energy efficiency.
- Pharmaceutical Firms:Sterile manufacturing and lyophilization operations require validated oil-free systems with batch documentation. FDA 21 CFR Part 11 compliance drives specification of integrated control systems with electronic signature capability.
- Pulp & Paper Mills:White water deaeration and felt conditioning applications specify corrosion-resistant liquid ring pumps. Scandinavian mills prioritize energy recovery integration for steam system optimization.
- Plastic Producers:Extruder degassing and thermoforming vacuum applications span dry and wet pump configurations depending on resin type. PET bottle manufacturing specifies oil-free systems to prevent acetaldehyde contamination.
- Textile Plants:Yarn conditioning and fabric finishing operations utilize low-vacuum systems with minimal specification complexity. Indian textile clusters under BIS energy labeling are replacing inefficient liquid ring installations.
Pharmaceutical firms lead on scale; cement manufacturers lead on momentum under China's dual carbon equipment upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon mandates are pulling equipment upgrade cycles faster than EPA emissions timelines in the United States, creating divergent procurement rhythms across manufacturing bases.
China
SAMR energy efficiency labeling and MEE pollution discharge rules are accelerating replacement of legacy liquid ring installations in coastal industrial parks. GB standards compliance deadlines in 2025-2026 are compressing procurement timelines for cement and chemical processing facilities. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou are absorbing the bulk of dry vacuum pump station deployments for semiconductor foundry expansion.
United States
EPA emissions standards and OSHA workplace exposure limits are tightening leak-tightness specifications for chemical processing installations. FDA sterility requirements for biologics manufacturing are extending vacuum pump deployment into pharmaceutical cold chain infrastructure. Texas Gulf Coast petrochemical corridors and Pacific Northwest semiconductor fabrication zones are driving regional equipment procurement concentration.
Germany
REACH substance restrictions on PFAS and fluorinated lubricants are forcing seal material redesigns across domestic pump station production. EU machinery directive conformity assessment periods have extended 40% since 2021, delaying market entry for new configurations. Bavarian and Baden-Württemberg industrial clusters anchor European demand for oil-free claw and screw pump architectures in food and pharmaceutical cleanrooms.
South Korea
Flat-panel display manufacturing lines for OLED production are requiring ultra-clean vacuum environments at scale. National semiconductor self-sufficiency programs are expanding domestic foundry capacity beyond Samsung and SK Hynix footprints. Seoul Capital Area and Busan-Ulsan manufacturing belts are specifying mag-lev turbopump stations for advanced node chip fabrication.
Taiwan
TSMC-led foundry expansion at 3nm and 2nm process nodes is demanding contamination control thresholds below 0.1 particles per cubic foot. Science park infrastructure in Hsinchu and Tainan is absorbing integrated vacuum station packages with Ethernet-IP connectivity and cloud-native diagnostics as standard procurement specifications.
Vacuum Pump Stations Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold another in high-vacuum subsystems. The vendor base concentrates around integrated compressor-to-vacuum platforms, oil-free dry pump architectures, and magnetically levitated turbopump arrays. Three archetypes dominate: diversified industrial conglomerates with cross-selling capabilities, pure-play vacuum technology specialists, and regional fabrication houses serving specification-tolerant segments. Capacity expansion in East Asian manufacturing clusters and strategic partnerships for hydrogen economy infrastructure represent the dominant competitive moves.
Within the diversified industrial tier, Atlas Copco represents the compressor-to-vacuum cross-selling model. Among pure-play vacuum specialists, Edwards Vacuum and Busch Vacuum Solutions exemplify contrasting technology anchoring strategies. These three occupy positions that span contamination-sensitive semiconductor fabrication through specification-tolerant chemical processing applications.
| Leading Market Players |
|---|
| Atlas Copco |
| Busch Vacuum Solutions |
| Edwards Vacuum |
| Pfeiffer Vacuum+Fab Solutions |
| Leybold |
| ULVAC |
| Elmo Rietschle |
| Becker Pumps |
| Gardner Denver |
| Others |
Pricing and Supply Chain Analysis
Specialized vacuum engineering talent concentrated in Bavaria and Baden-Württemberg feeds labor-cost differentials that widen pricing-tier spreads between German-engineered premium stations and specification-tolerant economy alternatives from Asian fabrication houses.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-tier dry vacuum pump stations. Three-tier pricing structure across premium, standard, and economy levels separates mag-lev turbopump arrays from oil-free scroll systems and legacy liquid ring configurations. Pricing pressure stems from GB standards compliance deadlines compressing procurement timelines for cement and chemical processing facilities. Municipal wastewater treatment operators exhibit highest price sensitivity, while semiconductor foundries prioritize contamination control over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Europe corridors is forcing inventory positioning shifts among German pump manufacturers. Permanent magnet processing concentrates in China, while precision-machined scroll and claw components source from Japan and Taiwan. Supply chain risk centers on rare earth export restriction exposure. Distribution runs through OEM direct sales for semiconductor capital equipment and regional distributor networks for specification-tolerant industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story where semiconductor fabrication's migration to sub-5nm nodes pulls procurement toward premium oil-free architectures with embedded IoT diagnostics.
For Market Incumbents: Cement leadership in mag-lev turbopump integration by deepening captive production of magnetically levitated bearing systems. Threat substitution from dry-running scroll technologies in flat-panel display manufacturing demands accelerated R&D in claw pump hydrogen chloride tolerance. Prioritize certification investment for FDA 21 CFR Part 11 compliance in pharmaceutical freeze-drying segments. For New Entrants and Emerging Players: Cloud-native diagnostics platforms offer the most penetrable entry vector for aftermarket service unbundling. Target pharmaceutical cold chain infrastructure where predictive maintenance contracts are displacing standalone equipment sales. Pursue hydrogen economy infrastructure partnerships in Germany and Japan for electrolyzer membrane coating applications. For Investors and Strategic Acquirers: Industrial conglomerates with compressor-to-vacuum cross-selling capabilities are the most active acquirer in this space. Five-to-ten year viability hinges on PFAS-compliant seal chemistry portfolios. Acquisition target archetype: pure-play oil-free specialists with validated graphite-based dry running seals. Watch REACH substance restriction implementation timelines as inflection indicator for European manufacturing cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Mag-Lev Bearing System Integration | Eliminates particulate generation for TSMC's 3nm node production requirements. |
| PFAS-Compliant Seal Validation | Secures market access under ECHA restrictions on fluoropolymer materials. |
| Predictive Maintenance Platform Launch | Captures recurring revenue from pharmaceutical lyophilization operations. |
| Hydrogen Economy Partnership | Positions stations for electrolyzer membrane coating in German industrial clusters. |
| Cloud-Native Diagnostics Integration | Meets Ethernet-IP connectivity specifications from South Korean display manufacturers. |
Research Methodology
Bottom-up semiconductor fabrication and pharmaceutical manufacturing modeling reconciled against top-down vacuum equipment production tracking forms the analytical core. Primary interviews with maintenance directors at foundries, OEM procurement teams, aftermarket service heads, and plant engineers in chemical processing facilities combined with secondary validation from SEC filings, customs trade data, SAMR energy efficiency labeling disclosures, and ECHA REACH substance restriction databases. Triangulation across stakeholder inputs and documentary sources ensures segment-level accuracy.
Input-output matrices map pump station deployments across technology type, use case contamination tolerance, and end-user capital intensity dimensions. CAGRs derive from equipment replacement cycle analysis and regulatory compliance deadline modeling. Forecast inputs incorporate GB standards implementation timelines and PFAS substitution R&D expenditure patterns across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for oil-sealed to dry vacuum migration would alter the outlook. Semiconductor capital expenditure volatility and rare earth supply disruption represent primary forecast revision risks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Automatic Water Level Controller Market