
 Paint Pump Market | 2026-2036
Paint Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Pump Market Insights
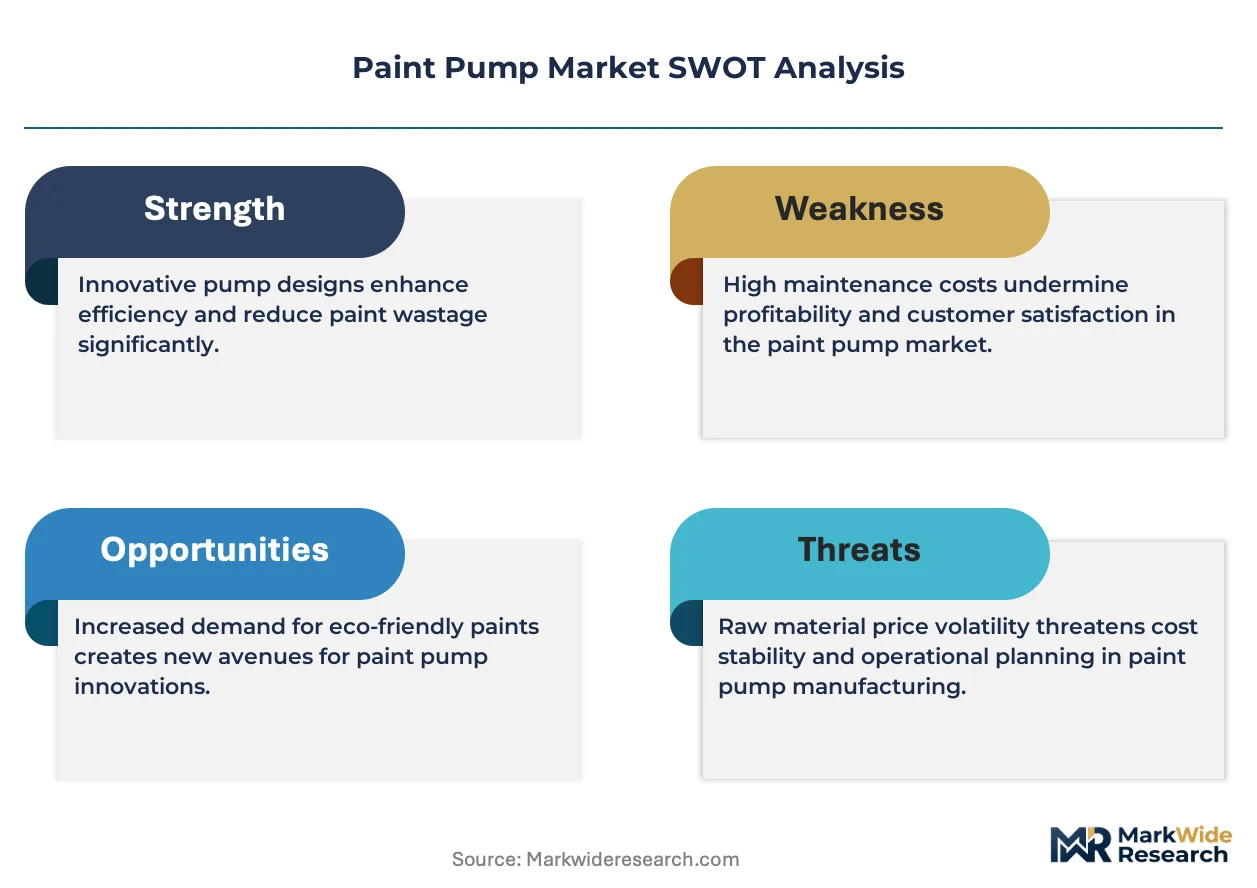
Ceramic-reinforced piston liners is hardening cost structures across premium pump portfolios. Graco Inc. leverages its North American service network to sustain aftermarket revenue density. WIWA Wilhelm Wagner GmbH & Co. KG anchors European industrial coating with specialized high-pressure architectures. Sames Kremlin competes through integrated fluid delivery systems that extend beyond standalone pump hardware.
A paint pump is a positive-displacement device engineered to transfer viscous coating media at controlled pressures ranging from 500 to 7,500 psi, utilizing piston, diaphragm, or rotary mechanisms to maintain consistent flow rates despite viscosity fluctuations. Its primary commercial purpose is to atomize and deliver architectural, industrial, or automotive coatings with minimal overspray and material waste. Airless pumps dominate volume shipments in construction end-use where speed and portability outweigh precision requirements, while diaphragm pumps capture expanding share in marine applications where corrosion-resistant fluid paths command margin premiums. Electric pump technology is gaining fastest traction as shipyards and automotive plants phase out pneumatic infrastructure to meet energy-efficiency targets.
EPA VOC emission limits and OSHA workplace exposure standards directly constrain allowable spray transfer efficiencies, compelling fleet upgrades toward higher-performance pump systems. REACH chemical restrictions in Europe and China's MEE environmental compliance deadlines further narrow the viable equipment pool for cross-border coating operations. Stakeholders must weigh capital replacement cycles against pending regulatory phase-ins that will disqualify legacy manual and low-pressure equipment from certified industrial applications.
Market Dynamics
Waterborne coating mandates across automotive finishing lines are compressing equipment replacement cycles and forcing pump architecture redesigns. Ceramic-reinforced piston liners and corrosion-resistant fluid paths are becoming baseline specifications as regulatory thresholds tighten.
Growth Catalysts
- EPA VOC emission limits:Automotive OEMs in the United States face mandatory spray transfer efficiency upgrades, accelerating fleet replacement toward higher-performance pump systems.
- China's marine shipyard sector:New-build contracts for vessels are specifying diaphragm pumps with superior transfer efficiency, concentrating demand in coastal construction clusters.
- Electric pump technology:Shipyards and automotive plants are phasing out pneumatic infrastructure to meet energy-efficiency targets, creating pull for electrified fluid delivery architectures.
Market Restraints
- Ceramic liner cost volatility:Reinforced piston materials are hardening cost structures across premium pump portfolios, squeezing margin flexibility for mid-tier manufacturers.
- Supply concentration in specialized alloys:Corrosion-resistant fluid path components depend on limited European and Japanese metallurgical suppliers, creating vulnerability to trade friction.
- REACH chemical restrictions:Cross-border coating operations in Europe face narrowing equipment pools as legacy pump chemistries lose certification eligibility.
Strategic Opportunities
- India's industrial coating infrastructure:Automotive and construction sectors remain underpenetrated by automated fluid delivery systems, offering white space for electric pump deployment.
- Integrated fluid delivery systems:Convergence of pump hardware with smart monitoring and predictive maintenance software creates bundled value propositions beyond standalone equipment.
- Brazil's ANVISA compliance deadlines:Pharmaceutical and food-contact coating mandates are opening certified equipment procurement windows for corrosion-resistant diaphragm architectures.
Industry Challenges
- Certification timeline compression:OSHA workplace exposure standards and MEE environmental deadlines in China are shortening validation windows for new pump designs.
- Legacy pneumatic infrastructure integration:Shipyards and plants with entrenched compressed air systems face capital-intensive retrofitting to accommodate electric pump architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Pump Market |
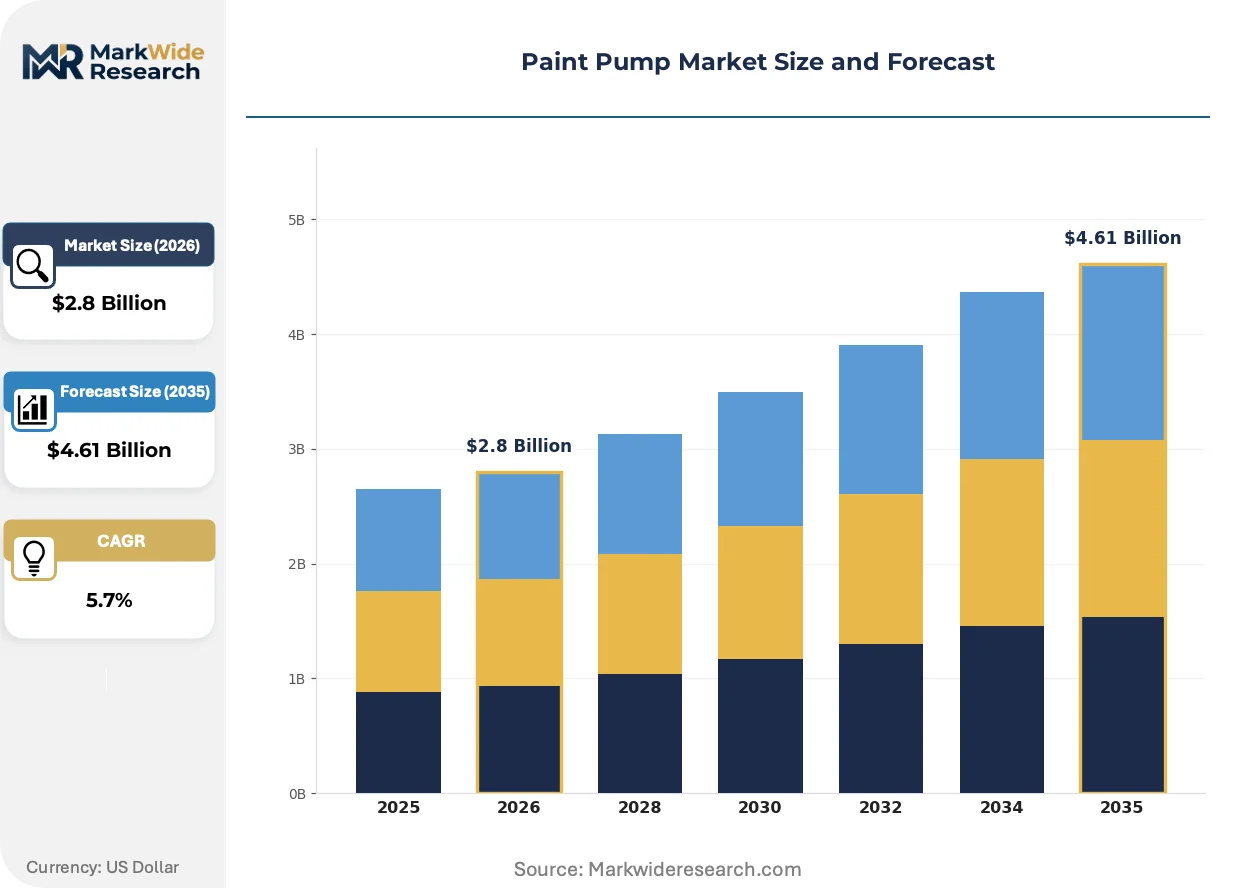
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airless Pumps, Diaphragm Pumps, Piston Pumps, Electric Pumps Application: Industrial Coating, Decorative Coating, Automotive Finishing, Wood Finishing End User: Construction, Automotive, Marine, Furniture Technology: Manual, Automatic, Semi-Automatic, High-Pressure |
| Companies Covered | Graco Inc., WAGNER Group, Titan Tool Inc., Anest Iwata Corporation, SATA GmbH & Co. KG, WIWA Wilhelm Wagner GmbH & Co. KG, Sames Kremlin, Carlisle Fluid Technologies, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Pump Market Trends and Innovations
Paint pump technology is pivoting toward electrification and intelligence as regulatory pressure and energy costs reshape equipment specifications. Three developments are restructuring competitive requirements.
Smart sensor arrays embedded in pump housings are enabling real-time viscosity monitoring and pressure adjustment without operator intervention. Automotive finishing lines in Germany are adopting these systems fastest, with marine shipyards in China following at compressed implementation timelines. The technology is integrating predictive maintenance protocols that reduce unplanned downtime and extend service intervals beyond traditional pneumatic equivalents.
REACH chemical restrictions in Europe are disqualifying legacy pump materials from certified industrial applications, forcing alloy substitution in fluid-contact components. Manufacturers serving cross-border coating operations must maintain dual material certifications or abandon European market access. Diaphragm pump architectures with fluoropolymer fluid paths are capturing preference as they satisfy both REACH compliance and corrosion resistance requirements.
Service unbundling is separating aftermarket maintenance from original equipment sales as fleet operators seek specialized third-party providers. Automotive plants in Mexico are contracting independent service networks rather than manufacturer-captive technicians, compressing Graco's historical aftermarket revenue density. This pattern is most visible in high-volume coating operations where internal maintenance capabilities justify direct parts procurement over bundled service agreements.
Paint Pump Market Segmentation
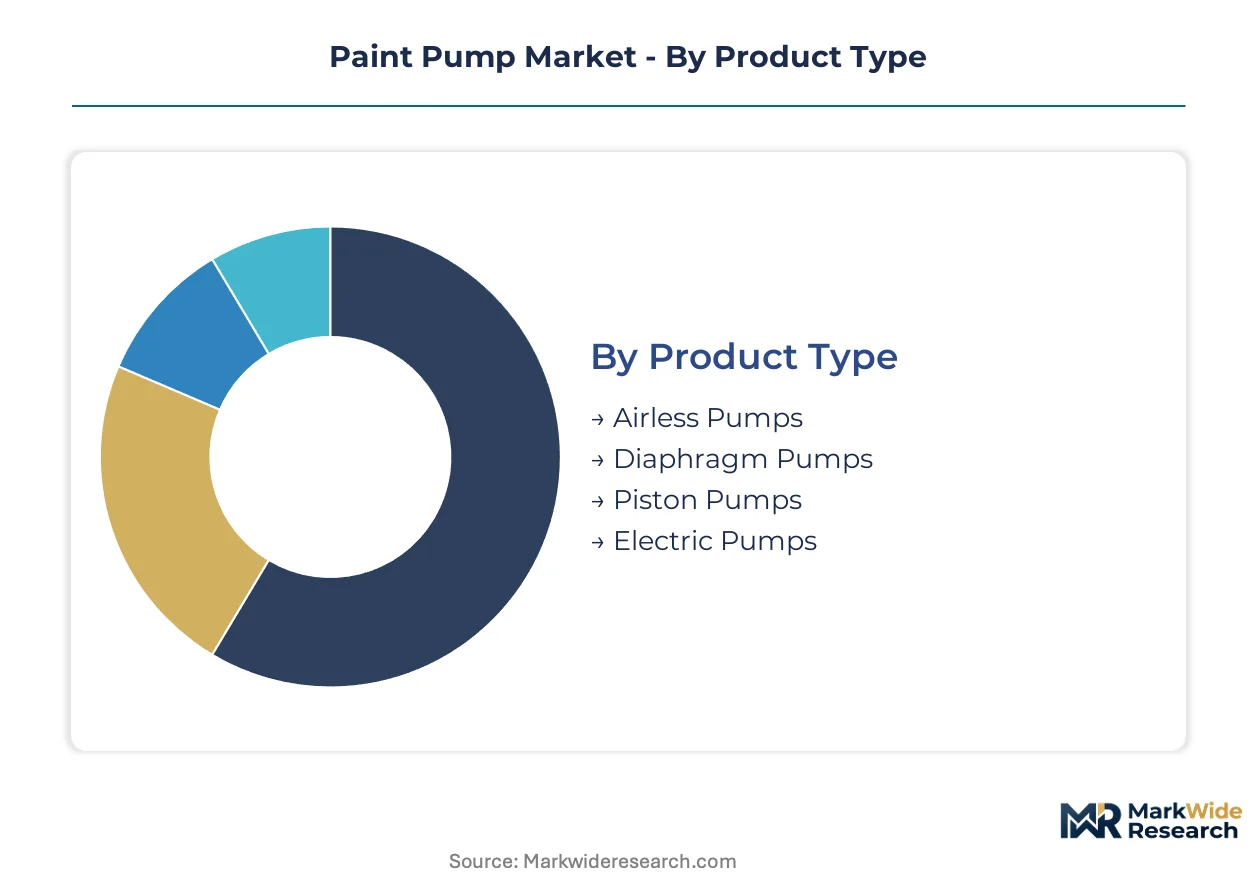
Paint pump procurement patterns diverge sharply across product architectures and end-use requirements. Equipment specification varies by coating viscosity, pressure demands, and regulatory compliance thresholds in target applications.
Product Type:
Supply concentration in high-pressure component manufacturing favors established pump architectures with proven aftermarket support networks.
- Airless Pumps:These systems generate atomization through hydraulic pressure alone, eliminating compressed air from the coating process. Construction contractors across the United States favor portable airless units for exterior architectural projects where speed outweighs precision requirements. Fleet operators in this segment prioritize equipment durability over transfer efficiency metrics.
- Diaphragm Pumps:Isolation of coating media from mechanical components through elastomeric diaphragms enables corrosion-resistant fluid paths. China's marine shipyards specify these architectures for new-build vessel contracts where saltwater exposure demands superior material compatibility. Regulatory pressure from MEE environmental compliance deadlines accelerates specification upgrades in coastal construction clusters.
- Piston Pumps:Positive-displacement mechanisms deliver consistent flow rates across viscosity fluctuations in industrial coating operations.
- Electric Pumps:Electrified architectures displace pneumatic infrastructure in automotive plants pursuing energy-efficiency targets.
Airless pumps absorb the bulk of installed capacity; electric pumps are expanding most quickly.
Application:
Cost tier differentiation separates high-precision finishing systems from high-volume coating equipment in commercial procurement.
- Industrial Coating:Protective and functional coating applications on metal substrates demand pressure ratings exceeding 5,000 psi for proper film formation. Heavy machinery manufacturers in Germany specify ceramic-reinforced piston liners for continuous-duty production lines. OSHA workplace exposure standards constrain allowable spray transfer efficiencies, compelling fleet upgrades toward higher-performance pump systems.
- Automotive Finishing:OEM clearcoat and basecoat applications require viscosity-controlled delivery with minimal overspray. Assembly plants in Mexico are expanding pump replacement cycles as waterborne coating mandates from EPA VOC emission limits tighten specification requirements. Color-change speed and material waste reduction dominate equipment selection criteria.
- Decorative Coating:Architectural and ornamental applications prioritize portability and rapid setup over precision control.
- Wood Finishing:Furniture and cabinetry coating operations balance transfer efficiency with fine-finish quality requirements.
Industrial coating commands the largest equipment installed base; automotive finishing shows the steepest specification upgrade trajectory.
End User:
Customer type determines service bundling preferences and aftermarket revenue capture models for pump manufacturers.
- Construction:General contractors and specialty painters purchase portable equipment through distribution channels with minimal technical support. Rental fleet operators in the United States rotate equipment aggressively, compressing manufacturer service attachment rates. Price sensitivity and immediate availability outweigh performance optimization in procurement decisions.
- Marine:Shipyards and vessel maintenance operations require corrosion-resistant fluid paths for saltwater-exposed coating applications. New-build contracts in China's coastal provinces specify diaphragm pump architectures with fluoropolymer components. REACH chemical restrictions in Europe disqualify legacy pump materials from certified industrial applications, forcing alloy substitution.
- Automotive:OEM and tier supplier finishing lines demand integrated fluid delivery systems with predictive maintenance capabilities.
- Furniture:Small-to-medium manufacturers balance capital constraints against coating quality requirements in equipment selection.
Construction absorbs the majority of unit shipments; marine end users are gaining share fastest on specification premiumization.
Technology:
Maturity gradients separate legacy pneumatic infrastructure from emerging electrified and intelligent pump architectures.
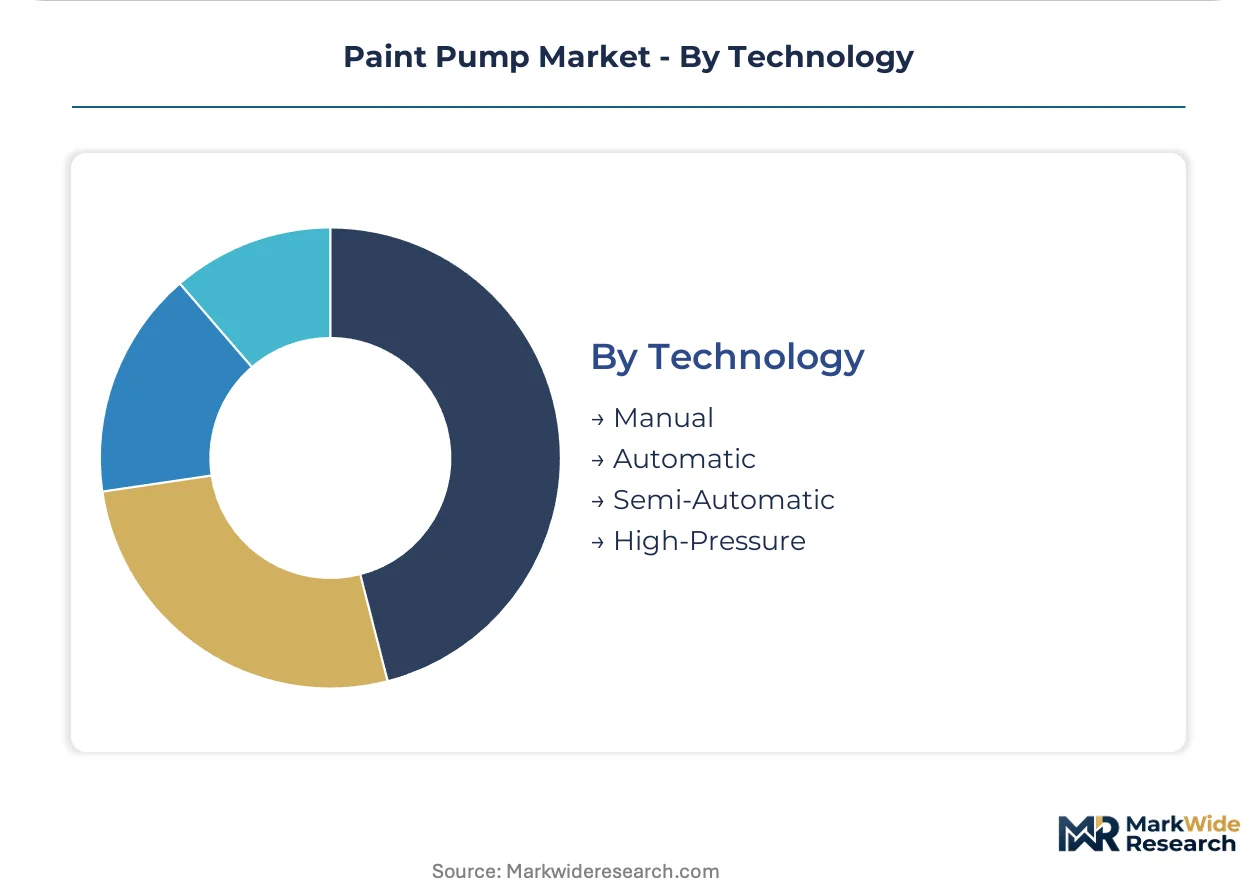
- Automatic:Sensor-integrated systems enable real-time viscosity monitoring and pressure adjustment without operator intervention. Automotive finishing lines in Germany adopt these architectures fastest, with smart sensor arrays embedded in pump housings reducing unplanned downtime. Predictive maintenance protocols extend service intervals beyond traditional pneumatic equivalents.
- High-Pressure:Systems operating above 3,000 psi deliver atomization quality required for industrial coating specifications. Ceramic-reinforced piston liners harden cost structures across premium pump portfolios, squeezing margin flexibility for mid-tier manufacturers. Supply concentration in specialized alloys for corrosion-resistant fluid paths creates vulnerability to trade friction.
- Manual:Operator-controlled pump systems persist in small-scale applications with limited capital budgets.
- Semi-Automatic:Intermediate architectures balance labor cost reduction against full automation investment requirements.
Automatic technology holds the largest addressable equipment base; high-pressure systems are climbing the fastest on specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate diaphragm pump demand from marine shipyards executing new-build vessel contracts under MEE environmental compliance deadlines.
United States
EPA VOC emission limits accelerate fleet replacement across automotive OEM finishing lines in Michigan and Ohio. OSHA workplace exposure standards constrain allowable spray transfer efficiencies, compelling upgrades toward higher-performance pump systems. Construction contractors in Texas and Florida favor portable airless units for exterior architectural projects where speed dominates procurement decisions.
Germany
REACH chemical restrictions disqualify legacy pump materials from certified industrial applications, forcing alloy substitution in fluid-contact components. Heavy machinery manufacturers in Bavaria specify ceramic-reinforced piston liners for continuous-duty production lines. Automotive finishing lines in Baden-Württemberg adopt smart sensor arrays fastest, embedding real-time viscosity monitoring without operator intervention.
China
MEE environmental compliance deadlines tighten specification requirements across coastal construction clusters. Marine shipyards in Jiangsu and Zhejiang provinces specify diaphragm pumps with fluoropolymer fluid paths for corrosion-resistant performance. New-build vessel contracts concentrate demand for higher transfer efficiency equipment in Dalian and Shanghai port zones.
Mexico
Automotive assembly plants in Nuevo León and Guanajuato expand pump replacement cycles as waterborne coating mandates tighten. Color-change speed and material waste reduction dominate equipment selection criteria for OEM clearcoat applications. Independent service networks challenge manufacturer-captive technicians, compressing historical aftermarket revenue capture models.
India
Automotive and construction sectors remain underpenetrated by automated fluid delivery systems, offering deployment white space for electric pump architectures. BIS certification requirements shape equipment import specifications for industrial coating infrastructure. Manufacturing clusters in Maharashtra and Tamil Nadu concentrate early specification trials for corrosion-resistant diaphragm architectures.
Paint Pump Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in premium industrial systems and fragmented competition in portable construction equipment. European and North American incumbents anchor high-pressure architectures through established aftermarket networks. Three archetypes dominate: integrated fluid delivery system providers, component specialists with metallurgical expertise, and scale-driven portable equipment fabricators. Capacity expansion in corrosion-resistant alloys and strategic partnerships for smart monitoring software represent the dominant competitive vectors.
Among North American service-network anchors, Graco Inc. exemplifies the integrated system archetype through captive aftermarket density. WIWA Wilhelm Wagner GmbH & Co. KG occupies a position within the European high-pressure specialist tier, representing metallurgical expertise in fluid-contact components. Sames Kremlin sits within the convergence-focused group, anchoring bundled value propositions that extend beyond standalone pump hardware into predictive maintenance protocols.
| Leading Market Players |
|---|
| Graco Inc. |
| WAGNER Group |
| Titan Tool Inc. |
| Anest Iwata Corporation |
| SATA GmbH & Co. KG |
| WIWA Wilhelm Wagner GmbH & Co. KG |
| Sames Kremlin |
| Carlisle Fluid Technologies |
| Ingersoll Rand |
| Others |
Pricing and Supply Chain Analysis
China's MEE environmental compliance deadlines gate qualified supply and premium-tier pricing access, as only pump architectures with fluoropolymer fluid paths and ceramic-reinforced components satisfy certification thresholds for marine shipyard contracts. Buyers face extended lead times for compliant equipment, while spot inventory of legacy pneumatic systems trades at widening discounts to electrified alternatives.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement premiums from spot inventory discounts in the paint pump market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and aftermarket service bundling. Price differentiation hinges on REACH-compliant material certification and ceramic liner quality tiers. Cost compression in mid-tier portfolios is intensifying because ceramic-reinforced piston materials harden manufacturing economics. Construction contractors exhibit highest price sensitivity, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
REACH chemical qualification and MEE environmental certification gate supply access for fluid-contact component suppliers. Manufacturing concentration rests on Germany, Japan, and China for corrosion-resistant alloys and ceramic-reinforced piston liners. Raw material dependencies draw from specialized metallurgical feedstocks, fluoropolymer resins, and high-pressure seal elastomers. Single-source vulnerability in European and Japanese metallurgical suppliers creates exposure to trade friction. Distribution runs through manufacturer-direct channels for automotive and marine OEMs, with construction equipment flowing through rental fleet operators and distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paint pump market operates as a cost-of-compliance story, where EPA VOC emission limits and REACH chemical restrictions erect barrier-to-entry moats that favor incumbents with certified material portfolios and established aftermarket networks.
For Market Incumbents: Lock in aftermarket revenue density by expanding captive service networks before independent technicians capture automotive plant contracts in Mexico. Deepen backward integration into ceramic-reinforced piston liner production to offset alloy cost volatility. Prioritize certification investment for dual REACH-MEE compliance to defend margin position against emerging Asian competitors. For New Entrants and Emerging Players: Begin with India's underpenetrated automotive and construction sectors, where BIS certification requirements are less stringent than REACH or EPA thresholds. Target electric pump deployment in Maharashtra and Tamil Nadu manufacturing clusters, where energy-efficiency mandates are displacing pneumatic infrastructure. Pursue a channel partnership go-to-market angle with established industrial distributors rather than direct OEM sales. For Investors and Strategic Acquirers: Automotive OEM specification of smart sensor arrays with predictive maintenance capabilities is the leading indicator that integrated fluid delivery system providers will command valuation premiums over standalone pump hardware manufacturers. Long-term viability favors acquisition targets with captive metallurgical expertise and software-enabled service bundling. Watch for MEE compliance deadline acceleration in China's coastal provinces as the signal for specification upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Components | Captive supply of reinforced piston liners insulates margin from alloy price volatility. |
| Smart Monitoring Software Platform | Predictive maintenance protocols extend service intervals beyond pneumatic equivalents for automotive OEMs. |
| REACH-Compliant Material Certification | Dual certification with MEE standards unlocks cross-border coating operations in Europe and China. |
| Independent Service Network Expansion | Third-party maintenance contracts capture aftermarket revenue from manufacturer-captive models in Mexico. |
| Electric Pump Architecture Deployment | Electrified systems displace pneumatic infrastructure in shipyards pursuing energy-efficiency targets. |
Research Methodology
Trade publications, customs and import-export databases, and SEC regulatory filings formed the secondary backbone of this analysis, supplemented by primary interviews with maintenance directors at automotive finishing plants, procurement leads at marine shipyards, aftermarket service heads at distributor networks, and plant engineers at industrial coating operations. Bottom-up and top-down triangulation validated segment-level estimates against equipment shipment data and end-use demand patterns.
Bottom-up modeling aggregated product-level specifications and replacement cycle frequencies across the projection horizon, while top-down approaches cross-checked aggregate market evolution against macroeconomic indicators and regulatory implementation timelines. Segmentation dimensions included pump architecture type, end-use industry, pressure rating tier, and geographic regulatory cluster. CAGRs were derived from fitted growth curves incorporating technology substitution rates and compliance-driven replacement acceleration. Industry-specific forecast inputs captured waterborne coating mandate phase-ins and electric infrastructure retrofit timelines.
Underlying measurement precision varies by segment; automotive finishing and marine shipyard applications carry tighter precision than fragmented construction contractor demand. Forecasts reflect assumptions regarding regulatory deadline adherence and technology substitution elasticities. A model refresh is warranted upon material change in MEE environmental compliance enforcement intensity or ceramic alloy supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Automatic Tank Cleaning Systems Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Air Compressor Controller Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Cooling Pump Market