
 Water Pump Market | 2026-2036
Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Water Pump Market Outlook
Variable frequency drive integration is reconfiguring how water pumps are specified and operated across municipal and industrial networks. Grundfos leverages its digital pump portfolio to capture premium positions in smart water infrastructure. Xylem anchors its competitive stance through advanced monitoring platforms that reduce lifecycle energy consumption. KSB competes on manufacturing scale, sustaining broad coverage across European utility frameworks and Asian industrial expansion.
A water pump is a mechanical device that imparts kinetic energy to fluid through rotational or reciprocating action, typically achieving flow rates from liters per minute to thousands of cubic meters per hour and pressure heads measured in meters, to enable water transport, pressure boosting, or drainage across agricultural, municipal, and industrial systems. Centrifugal pumps dominate installed base volumes due to their simplicity and broad flow-range adaptability, though submersible pumps command margin premiums in deep-well and wastewater applications where reliability requirements intensify. Solar power sourcing represents the fastest-expanding segment as off-grid irrigation and rural water supply projects displace diesel dependence, while electric-drive systems retain structural leadership in urban municipal networks where grid connectivity is assured.
The EU Ecodesign Directive and REACH frameworks enforce efficiency minimums and material compliance that reshape product development cycles for manufacturers serving European jurisdictions. The EPA's WaterSense program and DOE pump efficiency standards in the United States similarly redirect procurement specifications toward certified high-efficiency equipment. Stakeholders must monitor how efficiency regulations proliferate across jurisdictions and whether solar pump subsidies in agrarian economies sustain their current trajectory or face fiscal recalibration.
Market Dynamics
Variable frequency drive integration is compressing energy consumption curves across municipal and industrial pump networks, forcing specification standards to migrate from static head-flow curves to dynamic performance optimization.
Growth Catalysts
- Solar irrigation acceleration:India's agricultural heartland is replacing diesel pumps with solar-powered units at accelerating rates, driven by rural electrification gaps and diesel cost volatility.
- EU Ecodesign Directive:Tightening minimum efficiency requirements for clean water pumps are redirecting procurement specifications toward certified high-efficiency equipment across European utility frameworks.
- Submersible reliability premiums:Deep-well and wastewater applications command margin premiums where failure costs intensify, concentrating demand around sealed-motor designs with extended mean time between failures.
Market Restraints
- Copper and rare-earth magnet volatility:Permanent magnet motor costs fluctuate with neodymium and copper price cycles, compressing margins on premium efficiency tiers.
- Foundry capacity concentration:Cast iron and stainless steel pump housing production clusters in Chinese and Indian manufacturing zones, creating geographic supply vulnerability.
- Legacy infrastructure lock-in:Municipal water utilities face high replacement costs for embedded base of fixed-speed pumps, slowing upgrade cycles despite efficiency gains.
Strategic Opportunities
- Smart water infrastructure convergence:Integration of pump controls with SCADA and IoT monitoring platforms creates recurring revenue streams through predictive maintenance contracts.
- Southeast Asian utility procurement:Municipal water authorities in Vietnam, Thailand, and Indonesia are scaling energy-efficient pump system tenders as urbanization strains distribution networks.
- Aftermarket service unbundling:Remote monitoring capabilities enable pump OEMs to sell performance guarantees separate from hardware, capturing lifecycle value.
Industry Challenges
- Embedded systems integration complexity:Retrofitting VFD controls onto legacy pump installations requires specialized commissioning expertise that remains scarce in regional distributor networks.
- Multi-jurisdiction certification timelines:Manufacturers serving both EU Ecodesign and EPA WaterSense markets face divergent test protocols that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Pump Market |
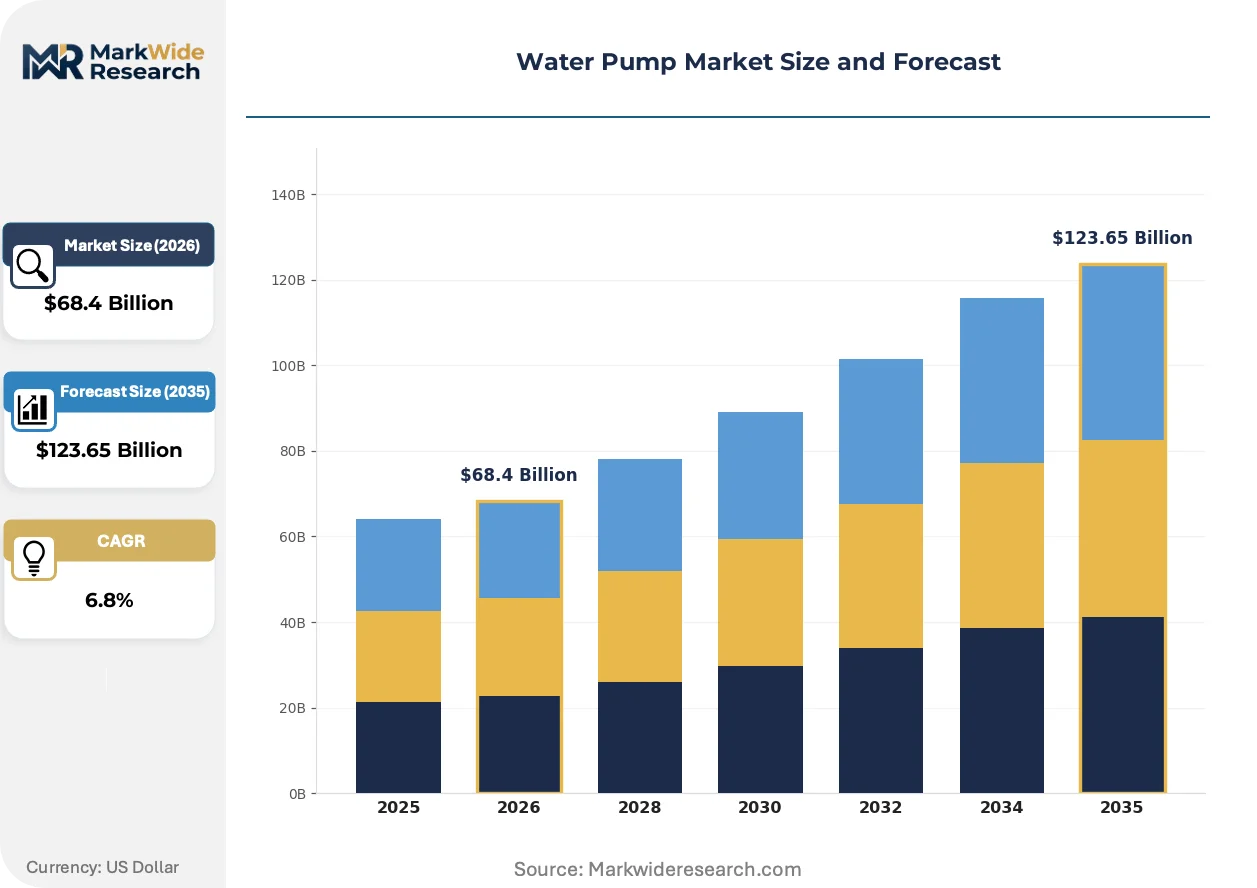
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Submersible Pumps, Positive Displacement Pumps, Diaphragm Pumps Application: Agricultural Irrigation, Water Supply Systems, Industrial Processes, Municipal Use End User: Agriculture, Construction, Manufacturing, Residential Power Source: Electric, Diesel, Solar, Gasoline |
| Companies Covered | Grundfos, Xylem, KSB, Weir Group, Sulzer, Flowserve Corporation, Pentair, Ebara Corporation, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Pump Market Strategic Shifts
Pump system architecture is migrating from mechanical reliability to data-driven performance optimization, with sensor integration and cloud analytics redefining how operators specify, commission, and maintain fluid handling assets.
Intelligent pump controllers with embedded pressure transducers and flow sensors are digitizing how municipal water utilities manage distribution network pressure. Dutch and German utilities are deploying these systems at scale to reduce burst frequency and energy consumption. The technology is digitizing traditional pump specification from static curve matching to real-time adaptive control.
The EU Ecodesign Directive's 2023 efficiency tier upgrades are forcing manufacturers to redesign hydraulic sections and motor laminations for clean water pump categories. Compliance costs are filtering marginal producers from European tender participation. Commercial building services and agricultural irrigation segments face the steepest redesign timelines.
Performance-based service contracting is displacing traditional equipment-plus-warranty sales in industrial process water applications. Chemical manufacturers and food processors in the US Midwest are piloting contracts where pump OEMs retain ownership and charge per cubic meter moved. This model concentrates most visibly in water-intensive manufacturing verticals with predictable baseline consumption profiles.
Water Pump Market Segmentation
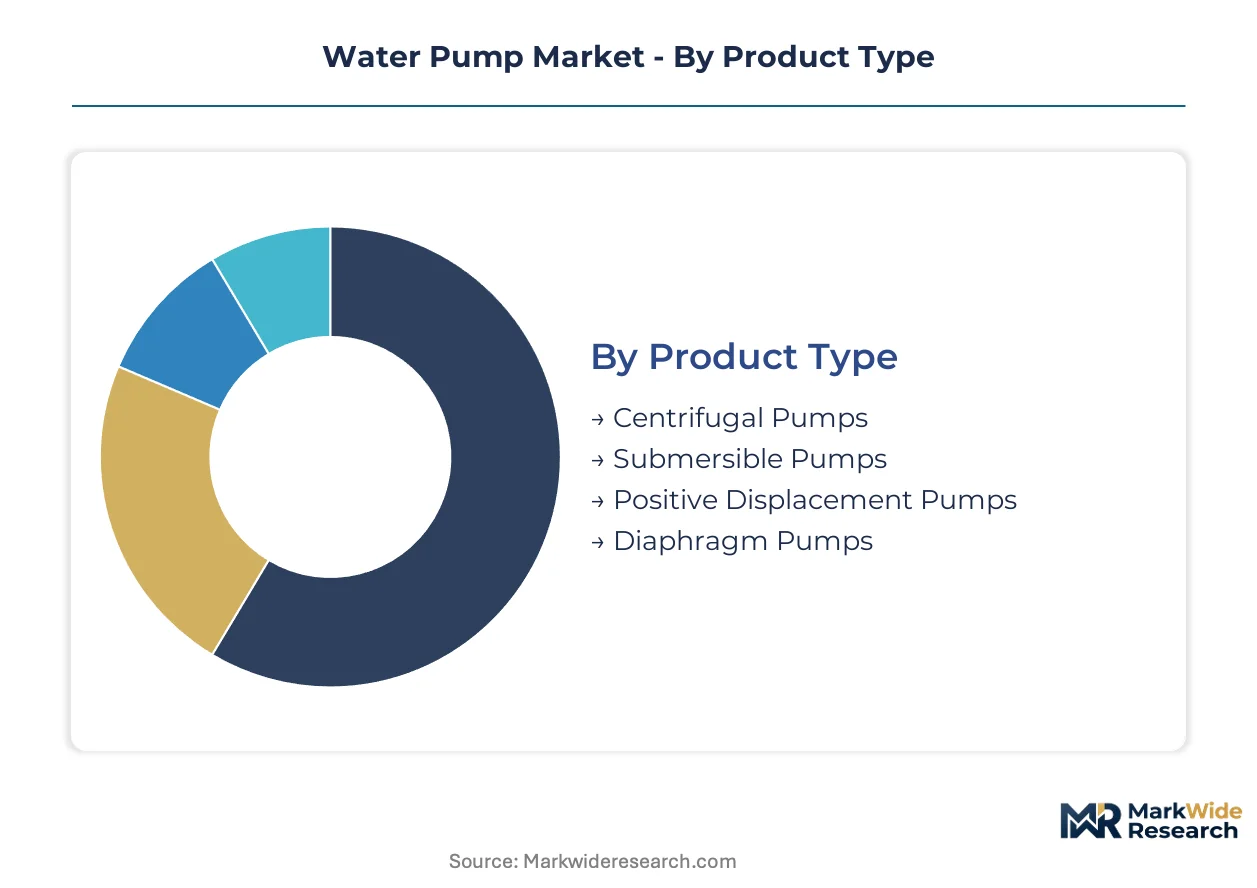
Water pump specification diverges sharply across power source, application intensity, and duty cycle requirements. Procurement patterns in this market track energy cost trajectories and regulatory compliance burdens more closely than capital expenditure thresholds.
Product Type:
Cost tier stratification across product categories reflects motor complexity, sealing technology, and materials specification.
- Centrifugal Pumps:These units employ rotating impellers to generate radial flow through volute casings, achieving flow rates from hundreds to thousands of cubic meters per hour. Demand concentrates in municipal water supply networks across India and Southeast Asian urban centers, where distribution infrastructure expansion drives specification toward mid-head, high-flow configurations. The segment holds installed capacity. Submersible Pumps is rotating up the share rankings.
- Submersible Pumps:Sealed motor designs operate fully immersed, eliminating suction lift limitations and enabling deep-well extraction beyond 200 meters. Premium pricing persists in wastewater treatment facilities and offshore dewatering applications across Germany and the Netherlands, where mean time between failure metrics dominate procurement criteria. The segment holds installed capacity. Submersible Pumps is rotating up the share rankings.
- Positive Displacement Pumps:Reciprocating or rotary mechanisms deliver fixed fluid volumes per cycle, suiting high-viscosity or precise metering requirements in chemical processing and food manufacturing.
- Diaphragm Pumps:Isolated pumping chambers handle abrasive slurries and corrosive fluids through elastomer or thermoplastic membrane actuation, common in mining tailings and industrial wastewater transfer.
Centrifugal designs dominate unit volumes. Submersible configurations are climbing the fastest.
Application:
Application intensity determines hydraulic specification, materials selection, and control system integration depth.
- Agricultural Irrigation:Seasonal duty cycles and remote deployment locations favor modular, repairable designs with tolerance for voltage fluctuation and particulate contamination. India's Punjab and Haryana states anchor demand as solar-powered replacements for diesel units accelerate through rural electrification subsidies and fuel cost volatility.
- Water Supply Systems:Continuous operation requirements in municipal distribution networks impose efficiency mandates under EU Ecodesign Directive tiers and EPA WaterSense certification. Dutch utilities specify variable frequency drive integration to reduce burst frequency and energy consumption across aging pipeline infrastructure.
- Industrial Processes:Chemical manufacturers and food processors in the US Midwest pilot performance-based contracting where OEMs retain equipment ownership and charge per cubic meter moved.
- Municipal Use:Urban drainage, sewage handling, and flood control applications in Vietnamese and Indonesian cities drive demand for corrosion-resistant submersible configurations.
Agricultural Irrigation holds installed capacity. Water Supply Systems is rotating up the share rankings.
End User:
Customer type dictates procurement channel, service contract structure, and financing mechanism preferences.
- Agriculture:Fragmented landholding patterns and seasonal cash flows concentrate demand around subsidized solar pump programs and cooperative procurement schemes in India.
- Construction:Project-based demand cycles favor rental and leasing models for dewatering and concrete supply applications, with equipment utilization rates driving fleet composition decisions.
- Manufacturing:Process water reliability requirements sustain premium pricing for predictive maintenance contracts and remote monitoring integration in German and US industrial corridors.
- Residential:Pressure boosting and groundwater extraction applications in suburban developments across Thailand and Indonesia specify compact, self-priming centrifugal units with dry-run protection.
Agriculture holds installed capacity. Manufacturing is rotating up the share rankings.
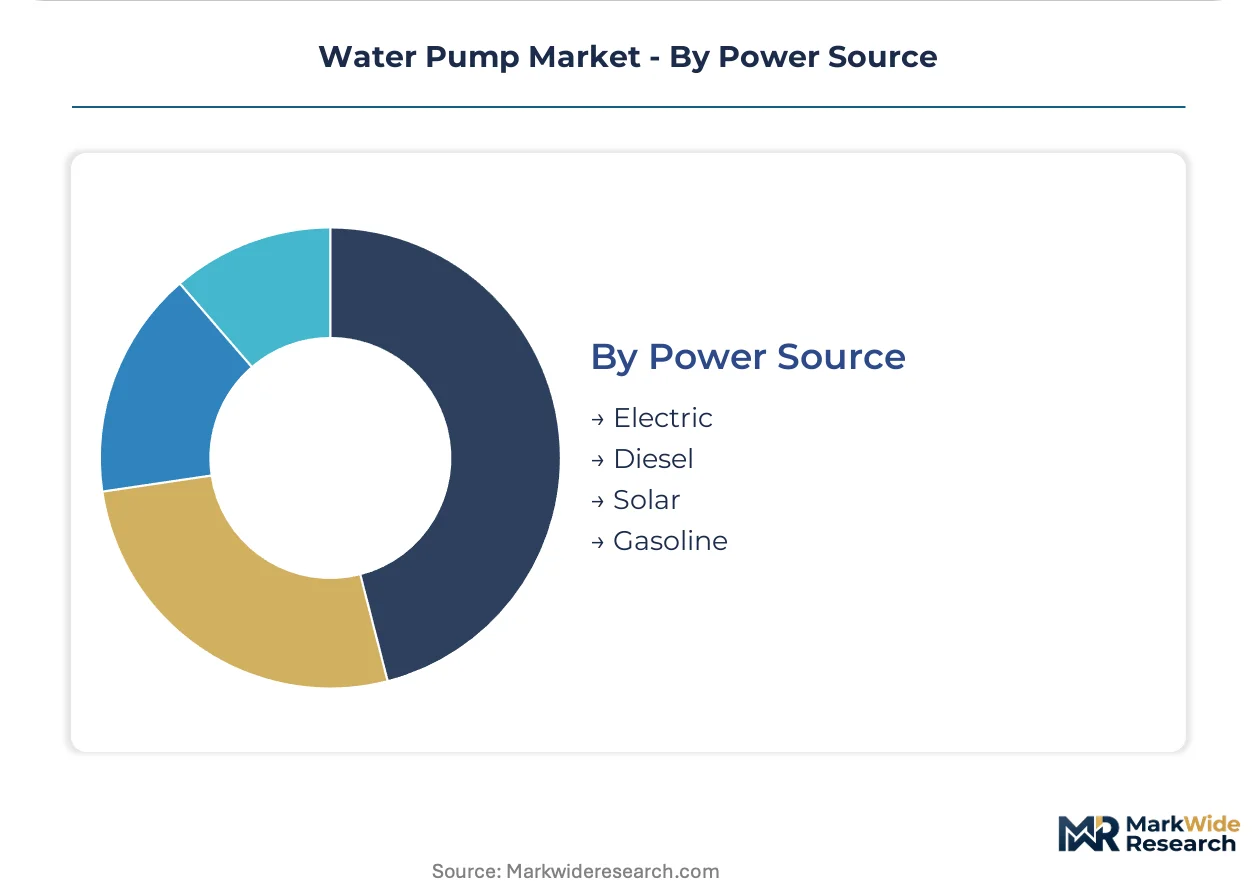
Power Source:
Energy input modality shapes total cost of ownership calculations and deployment feasibility across grid-connected and off-grid contexts.
- Electric:Grid-connected motors dominate urban municipal and industrial installations where three-phase supply reliability supports continuous operation. European utilities specify premium efficiency tiers under Ecodesign Directive minimums.
- Diesel:Portable and backup power applications persist in construction dewatering and emergency flood response, though fuel cost volatility and emissions regulations compress addressable market scope.
- Solar:Photovoltaic-powered DC motors with surface or submersible pump heads are expanding most quickly in Indian agricultural heartland and sub-Saharan rural water supply projects, displacing diesel dependence where grid extension is uneconomic.
- Gasoline:Light-duty, intermittent applications in residential and small-scale agricultural contexts favor portability and low capital outlay over efficiency optimization.
Electric holds installed capacity. Solar is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in water pump trade reveal concentrated manufacturing hubs in Germany and China supplying deficit markets across Southeast Asia and the Middle East. Currency fluctuations and freight cost volatility are redirecting procurement strategies toward regional sourcing partnerships.
India
Agricultural electrification and rural irrigation modernization drive pump demand across Punjab and Haryana states. The Ministry of New and Renewable Energy's PM-KUSUM scheme subsidizes solar pump adoption for diesel displacement. Ahmedabad and Rajkot manufacturing clusters produce centrifugal units for domestic distribution and African export markets.
Germany
Municipal infrastructure renewal and industrial process water reliability sustain premium equipment procurement. The EU Ecodesign Directive's 2023 efficiency tier upgrades enforce minimum hydraulic performance standards. The Ruhr industrial corridor and Bavarian manufacturing zones anchor European pump production capacity.
United States
Industrial water reuse mandates and municipal lead pipe replacement programs stimulate pump system upgrades. EPA WaterSense certification requirements redirect procurement toward verified high-efficiency equipment. The Great Lakes manufacturing belt and Texas Gulf Coast petrochemical clusters specify submersible configurations for process applications.
China
Urban water distribution expansion and agricultural mechanization sustain domestic pump consumption at scale. National standards under GB/T series regulate efficiency testing protocols for clean water pump categories. Zhejiang and Jiangsu province foundry clusters supply cast iron housings for regional OEM assembly networks.
Vietnam
Mekong Delta irrigation intensification and Ho Chi Minh City flood control infrastructure drive submersible pump procurement. Ministry of Agriculture and Rural Development programs promote solar-powered units for off-grid delta farming. Da Nang industrial zone manufacturers assemble imported components for domestic municipal tenders.
Water Pump Market Competitive Environment
On the supply side, the industry is tiered between integrated multinational OEMs with digital service platforms and regional fabricators competing on price-accessibility for agricultural segments. Strategic archetypes include full-lifecycle solution providers, component-scale specialists, and solar-irrigation system integrators. Competitive moves center on predictive maintenance service unbundling and foundry-to-final-assembly vertical consolidation.
Among European-headquartered multinationals, Grundfos A/S and KSB SE & Co. KGaA exemplify the integrated solution archetype, bundling hardware with remote monitoring capabilities. Xylem Inc. occupies a parallel position in North American utility markets. Japanese manufacturers including Ebara Corporation and Kubota Corporation represent precision-engineering specialists with concentrated strength in Asian industrial and agricultural verticals. These named entities anchor competitive positioning without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| KSB |
| Weir Group |
| Sulzer |
| Flowserve Corporation |
| Pentair |
| Ebara Corporation |
| Kubota Corporation |
| Others |
Value Chain & Pricing Dynamics
Foundry capacity utilization in Zhejiang and Jiangsu provinces sits above sustainable thresholds, compressing lead times for cast iron pump housings and forcing European OEMs to absorb premium pricing for stainless steel variants or accelerate qualification of Indian alternative suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across municipal and process water applications. Three-tier pricing structure across premium, standard, and economy levels separates EU Ecodesign-certified units from baseline efficiency tiers and unbranded regional alternatives. Pricing pressure stems from copper and rare-earth magnet cost volatility, which squeezes margins on permanent magnet motor configurations. Agricultural cooperatives in India exhibit highest price sensitivity, while German municipal utilities prioritize lifecycle cost optimization over upfront capital outlay.
Supply Chain Analysis
Contract manufacturing concentration rests with foundry clusters in China, India, and Germany that supply cast iron and stainless steel housings to assembly networks. Raw material dependencies draw from copper winding wire, neodymium permanent magnets, and elastomer sealing compounds. Single-source vulnerability concentrates in Chinese rare-earth processing capacity, exposing motor manufacturers to export restriction risk. Distribution runs through authorized distributor networks for specification-grade equipment and direct procurement channels for utility-scale tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-powered irrigation penetration in India's agricultural heartland signals early-cycle expansion, with subsidy programs accelerating displacement of diesel-dependent pumping infrastructure.
For Market Incumbents: Pre-empt margin erosion in centrifugal pump commoditization by deepening backward integration into permanent magnet motor production and securing captive foundry capacity in India. Anchor defensive positioning through predictive maintenance platform lock-in with European municipal utilities facing Ecodesign Directive compliance deadlines. For New Entrants and Emerging Players: Sub-Saharan Africa's rural water supply gap offers lowest competitive density for solar pump system integrators. Target off-grid community water projects with modular DC submersible configurations bundled with photovoltaic panel procurement and local technician training programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart pump controller development, favoring scaled players with software engineering depth. Prioritize acquisition targets with embedded IoT monitoring capabilities and recurring revenue service contracts in water-intensive manufacturing verticals. Watch solar pump subsidy fiscal sustainability in agrarian economies as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captures margin compression from neodymium price volatility while securing EU Ecodesign compliance pathways. |
| Predictive Maintenance Platform Deployment | Converts Grundfos and Xylem hardware sales into recurring revenue streams through SCADA-integrated service contracts. |
| Solar Pump System Integration | Addresses India's PM-KUSUM subsidy window with bundled photovoltaic-to-pump solutions for diesel displacement. |
| Foundry Capacity Expansion in India | Reduces geographic supply vulnerability from Chinese cast iron concentration while serving African export markets. |
| Smart Water Infrastructure Partnership | Aligns Dutch and German utility digitization mandates with embedded pressure transducer and flow sensor deployments. |
Study Parameters
Cross-validation between OEM procurement director interviews and customs trade data anchors the qualitative findings on supply chain geographic concentration. Primary fieldwork engaged maintenance directors at municipal water utilities, plant engineers in chemical processing facilities, aftermarket service heads at regional distributors, and agricultural cooperative procurement leads across Punjab and Haryana. Secondary sources included EU Ecodesign Directive technical documentation, EPA WaterSense certification databases, Indian Ministry of New and Renewable Energy subsidy disbursement records, and SEC filings from listed pump manufacturers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Calibration against historical efficiency regulation adoption curves shaped the projection framework across the analysis window. Segmentation dimensions modeled encompass power source modality, pump product architecture, application intensity tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating solar irradiance mapping for agricultural applications and urbanization density projections for municipal water supply. Forecast inputs integrated copper and rare-earth magnet price cycle assumptions alongside subsidy program fiscal sustainability assessments.
Practitioners should monitor rare-earth export policy shifts and agricultural subsidy recalibration for early signals of demand trajectory revision. Forecasts embed assumptions regarding Ecodesign Directive enforcement continuity and solar photovoltaic cost curves. Quarterly review of foundry capacity utilization indicators and municipal tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Dosing Pumps Market