
 Dual Carbon Battery Market | 2026-2036
Dual Carbon Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Carbon Battery Market Analysis
The EU Green Deal battery sustainability mandate is consolidating procurement criteria across European automotive OEMs. Panasonic leverages its Osaka R&D campus to sustain electrochemical innovation pipelines for next-generation cathode designs. Samsung SDI anchors South Korean output through Gyeonggi Province manufacturing complexes with backward integration into carbon precursor supply. BYD dominates Chinese vertical scope through in-house production of prismatic dual carbon cells for its vehicle platforms.
A dual carbon battery employs carbonaceous materials for both anode and cathode electrodes, eliminating transition metal oxides and enabling operation at voltages up to 4.5V with simplified thermal management architectures. The electrochemical technology segment leads commercialization timelines, while supercapacitors occupy niche high-power buffering roles in hybrid energy systems. Cylindrical formats command industrial margins through established winding equipment compatibility, though prismatic designs are capturing automotive design-in share for pack-level volumetric efficiency.
The EPA tailpipe emission rules and NHTSA fuel economy standards are tightening compliance windows for US vehicle electrification, directly shaping battery chemistry procurement specifications. Japan's METI and South Korea's MFDS coordinate safety certification protocols that govern market access for imported cells. China's SAMR enforces GB standards on cycle life and thermal runaway containment that constrain non-domestic suppliers. Stakeholders must monitor evolving carbon sourcing disclosure requirements under the EU CSRD and prepare supply chain documentation for battery passport traceability mandates.
Market Dynamics
Fast-charging requirements from electric vehicle OEMs are compressing cell qualification timelines and forcing carbon precursor suppliers to synchronize capacity expansion with automotive platform launches.
Growth Catalysts
- Japan METI Battery Subsidy Framework:Direct capital grants for domestic gigafactory construction accelerate electrode manufacturing scale-up and reduce payback periods for carbon anode production lines.
- Electrochemical Technology Maturation:Simplified thermal management architectures cut pack-level engineering costs and open design wins in commercial vehicle platforms seeking reduced cooling overhead.
- South Korean Manufacturing Clusters:Concentrated cathode active material output in Gyeonggi Province creates localized supply density that shortens logistics lead times for cell assembly operations.
Market Restraints
- Carbon Precursor Supply Concentration:Synthetic graphite and hard carbon feedstock production clusters in China create single-source dependency risks for non-domestic cell manufacturers.
- High-Purity Carbon Cost Structure:Needle coke and biomass-derived hard carbon purification requirements impose raw material cost floors that resist economies of scale compression.
- Transition Metal Oxide Substitution Inertia:Established lithium-ion cathode supply chains for NMC and LFP chemistries lock in incumbent procurement relationships and qualification protocols.
Strategic Opportunities
- EU Battery Passport Traceability Mandates:Carbon sourcing disclosure requirements create first-mover advantages for suppliers with verified supply chain documentation and blockchain-tracked material flows.
- Grid-Scale Stationary Storage:Long-cycle-life dual carbon architectures address frequency regulation and peak shaving applications where calendar aging tolerance outweighs energy density priorities.
- Aviation Electrification:Simplified thermal management and non-flammable electrolyte compatibility position the chemistry for electric vertical take-off and landing aircraft auxiliary power units.
Industry Challenges
- Electrolyte Formulation Expertise Gap:Shortage of electrochemists with high-voltage carbonate electrolyte stabilization experience extends R&D cycle times for 4.5V operation.
- Cell-to-Pack Integration Complexity:Cylindrical-to-prismatic format transitions require retooling of winding equipment and laser welding stations, straining capital allocation decisions.
- Cross-Border Safety Certification Delays:Divergent thermal runaway test protocols between Japan's METI and South Korea's MFDS force redundant validation campaigns for regional market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Carbon Battery Market |
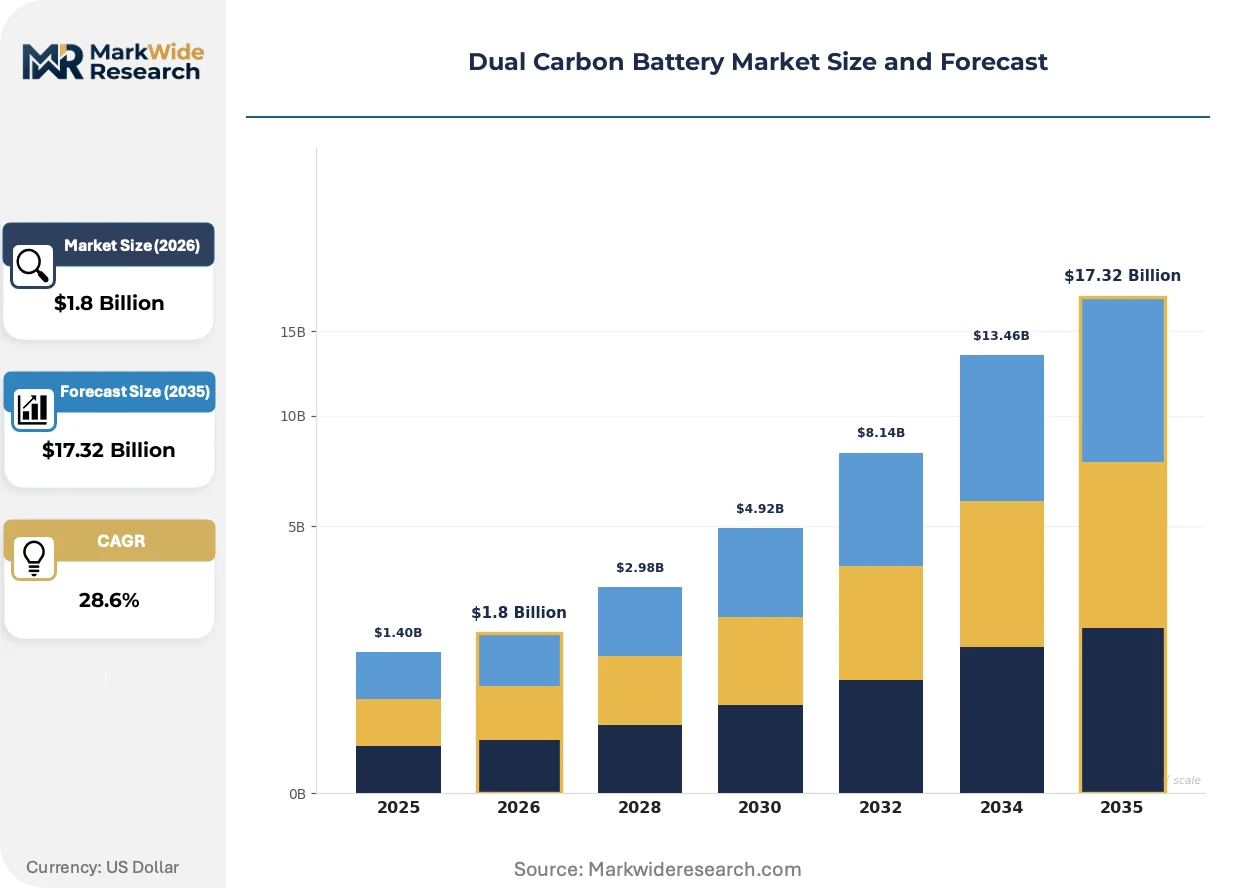
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Coin Cell, Cylindrical, Prismatic End User: Consumer Electronics, Automotive, Energy Storage, Industrial Applications Technology: Electrochemical, Supercapacitors, Hybrid Systems, Energy Management Application: Grid Storage, Electric Vehicles, Portable Devices, Renewable Integration |
| Companies Covered | LG Chem, Panasonic, Samsung SDI, BYD, JSR Corporation, Johnson Controls, Hitachi Chemical, Lishen Tianjin, Power Japan Plus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Carbon Battery Market Emerging Trajectories
Carbonaceous electrode engineering is compressing the performance gap between conventional lithium-ion and next-generation solid-state architectures while bypassing cobalt supply constraints.
Hard carbon anode formulations derived from lignin and biomass precursors are electrifying automotive procurement specifications. European OEMs have accelerated qualification timelines for prismatic cell formats that leverage these materials. The shift is compressing incumbent synthetic graphite supply contracts and forcing electrode suppliers to diversify precursor sourcing strategies.
EU CSRD carbon footprint disclosure mandates are reshaping procurement documentation requirements. Battery manufacturers must now submit granular Scope 3 emissions data for carbon precursor extraction through cell assembly. Automotive OEMs in Germany and France are prioritizing suppliers with certified supply chain traceability systems, compressing qualification windows for undocumented producers.
Fleet operators are consolidating cell procurement through direct long-term offtake agreements rather than tiered distributor networks. Commercial vehicle platforms in Japan and South Korea now source dual carbon cells through bilateral contracts with electrode manufacturers, bypassing traditional battery pack integrators. The disintermediation concentrates volume commitments with vertically integrated cell producers and fragments legacy channel margins across smaller aftermarket service providers.
Dual Carbon Battery Market Segmentation
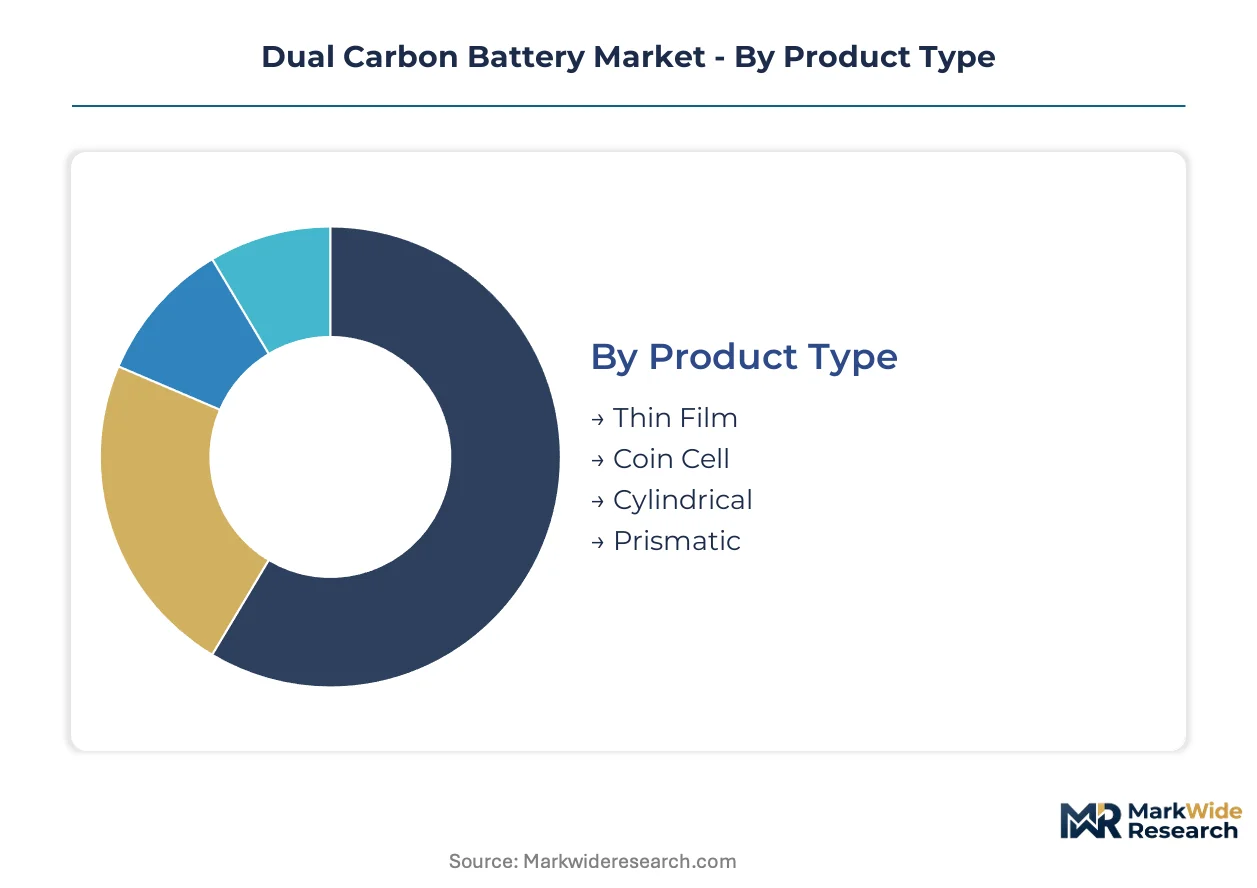
Dual carbon battery procurement splits across four analytical dimensions that shape cell qualification protocols and pricing structures. Product format determines manufacturing equipment compatibility and thermal management architecture. End-use concentration drives cycle life specifications and safety certification requirements.
Product Type:
Automotive OEMs and consumer electronics manufacturers prioritize different form factors based on pack integration constraints and production scale.
- Cylindrical:Established winding equipment compatibility supports high-throughput manufacturing for automotive module assembly. Demand concentrates in South Korean manufacturing clusters where Samsung SDI and LG Chem operate Gyeonggi Province facilities, driven by fast-charging platform requirements from electric vehicle OEMs.
- Prismatic:Rectangular aluminum housings maximize volumetric efficiency at the pack level for commercial vehicle platforms. BYD dominates Chinese output through in-house production lines serving its vehicle platforms, with procurement expanding for grid-scale stationary storage applications seeking simplified thermal management.
- Thin Film:Flexible polymer substrates enable conformal integration into wearable electronics and medical devices.
- Coin Cell:Compact metal can designs address low-power backup applications in industrial sensors and IoT endpoints.
Volume sits with Cylindrical formats; growth tilts toward Prismatic designs.
End User:
Procurement scale and qualification timelines diverge sharply between consumer-facing and industrial buyers.
- Automotive:Electric vehicle platforms demand 4.5V operation with simplified thermal management architectures. Japan's METI battery subsidy framework accelerates domestic gigafactory construction for electrode manufacturing scale-up, compressing payback periods for carbon anode production lines serving this segment.
- Energy Storage:Grid-scale operators prioritize calendar aging tolerance and long cycle life over energy density. Frequency regulation and peak shaving applications in Japan and South Korea source through bilateral offtake agreements with electrode manufacturers, bypassing traditional pack integrators.
- Consumer Electronics:Smartphone and laptop manufacturers drive demand for fast-charging coin cell and prismatic formats.
- Industrial Applications:Material handling equipment and backup power systems specify ruggedized cylindrical designs.
Revenue concentrates with Automotive buyers; expansion accelerates fastest in Energy Storage deployments.
Technology:
Electrochemical maturity separates commercial deployment timelines from emerging hybrid architectures.
- Electrochemical:Carbonaceous anode and cathode electrodes operate at voltages up to 4.5V without transition metal oxides. Commercial vehicle platforms in Europe consolidate procurement around this chemistry to satisfy EU Green Deal battery sustainability mandates and carbon footprint disclosure requirements under CSRD.
- Supercapacitors:High-power density carbon electrodes enable rapid charge-discharge cycling for hybrid energy systems. Niche demand buffers regenerative braking loads in electric vertical take-off and landing aircraft auxiliary power units, where non-flammable electrolyte compatibility outweighs energy density limitations.
- Hybrid Systems:Combined electrochemical-capacitor architectures balance energy and power density for pulsed load applications.
- Energy Management:Integrated battery management systems optimize charge protocols and thermal regulation across cell formats.
Deployment volume favors Electrochemical cells; technology development investment flows most heavily toward Hybrid Systems.
Application:
Grid-connected versus mobile use cases impose divergent duty cycle and safety certification requirements.
- Electric Vehicles:Fast-charging architectures compress cell qualification timelines and force carbon precursor suppliers to synchronize capacity expansion with automotive platform launches. EPA tailpipe emission rules and NHTSA fuel economy standards tighten compliance windows for US vehicle electrification, directly shaping procurement specifications.
- Grid Storage:Stationary installations prioritize 20-year calendar life and reduced cooling overhead. EU battery passport traceability mandates reshape procurement documentation requirements, with German and French automotive OEMs prioritizing suppliers with certified supply chain traceability systems.
- Portable Devices:Consumer electronics specify compact prismatic and coin cell formats for handheld equipment.
- Renewable Integration:Solar and wind pairing applications demand high cycle tolerance for daily charge-discharge regimes.
Capital deployment concentrates in Electric Vehicles; policy support expands fastest for Grid Storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in East Asian manufacturing clusters while consumption demand disperses across automotive electrification corridors in Europe and North America. Carbon precursor refining and electrode fabrication anchor output in Japan, South Korea, and China. Procurement specifications diverge sharply between EPA-driven US compliance windows and EU Green Deal sustainability mandates.
Japan
Domestic gigafactory construction accelerates under METI battery subsidy frameworks that compress payback periods for carbon anode production lines. Osaka R&D campuses sustain electrochemical innovation pipelines for next-generation cathode designs. Kansai manufacturing corridors anchor electrode material output serving both domestic vehicle platforms and export markets.
South Korea
Gyeonggi Province manufacturing complexes concentrate cathode active material output that shortens logistics lead times for cell assembly operations. MFDS safety certification protocols govern market access requirements for imported cells alongside domestic qualification standards. Busan-Ulsan industrial zones host backward integration into carbon precursor supply chains.
China
GB standards on cycle life and thermal runaway containment constrain non-domestic suppliers while SAMR enforces domestic procurement preferences. BYD dominates vertical scope through in-house production of prismatic dual carbon cells for captive vehicle platforms. Yangtze River Delta clusters concentrate synthetic graphite and hard carbon feedstock refining capacity.
Germany
EU Green Deal battery sustainability mandates consolidate procurement criteria across automotive OEMs seeking simplified thermal management architectures. KBA type-approval processes intersect with CSRD carbon footprint disclosure requirements that reshape supplier qualification documentation. Bavaria and Baden-Württemberg host pack integration facilities for commercial vehicle platforms.
United States
EPA tailpipe emission rules and NHTSA fuel economy standards tighten compliance windows for vehicle electrification procurement specifications. IRA domestic content bonuses accelerate electrode manufacturing investment decisions. Michigan and California automotive corridors drive fast-charging platform requirements that compress cell qualification timelines.
Dual Carbon Battery Market Vendor Landscape
The competitive structure tilts toward diversified chemical conglomerates with captive materials science capabilities. Tier-one suppliers consolidate around automotive qualification relationships while specialty carbon producers occupy upstream precursor niches. Strategic archetypes span vertically integrated cell manufacturers, electrode material specialists, and diversified industrial chemical groups. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players synchronize carbon precursor output with automotive platform launch schedules.
Within the diversified chemical conglomerate tier, LG Chem and Samsung SDI exemplify Korean industrial groups that anchor electrode manufacturing scale. Panasonic occupies a position representing Japanese precision materials specialists with sustained R&D commitments. BYD sits within the vertically integrated vehicle OEM archetype that controls cell production for captive demand. These three players collectively represent the structural concentration around East Asian manufacturing corridors where carbon precursor supply density enables cost positioning.
| Leading Market Players |
|---|
| LG Chem |
| Panasonic |
| Samsung SDI |
| BYD |
| JSR Corporation |
| Johnson Controls |
| Hitachi Chemical |
| Lishen Tianjin |
| Power Japan Plus |
| Others |
Supply Flow & Price Mechanics
Backward integration into carbon precursor refining anchors supply positioning and pricing power for electrode manufacturers serving automotive OEMs. Japanese and South Korean producers leveraging METI subsidy frameworks compress raw material cost floors that resist economies of scale for non-integrated competitors.
Pricing Analysis
Margin tightening in prismatic cell tiers reflects hard carbon purification cost floors that synthetic graphite incumbents exploit. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified suppliers from commercial vehicle tier-2 vendors and aftermarket distributors. Pricing pressure stems from China's SAMR-enforced GB standards constraining import qualification windows. Fleet operators show highest price sensitivity through bilateral offtake negotiations, while aviation auxiliary power unit buyers absorb premiums for non-flammable electrolyte compatibility.
Supply Chain Analysis
Dual-sourcing requirements from European automotive OEMs mandate multi-supplier qualification for needle coke and biomass-derived hard carbon precursors. Geographic concentration centers on China for synthetic graphite refining, Japan for electrochemical-grade carbon processing, and South Korea for cathode active material output. Raw material dependencies rest on lignin biomass, petroleum needle coke, and high-purity carbonate electrolytes. Single-source vulnerability in Yangtze River Delta carbon refining clusters exposes non-Chinese cell manufacturers to SAMR export licensing discretion. Distribution runs through electrode manufacturers directly to pack integrators, bypassing traditional battery distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is reshaping around captive carbon precursor supply as players race to secure backward integration into hard carbon refining. The upstream lever determining winner-take-most dynamics is control over biomass precursor qualification pipelines for automotive platform design-ins.
For Market Incumbents: Deepen Gyeonggi Province manufacturing density through capacity additions synchronized with Samsung SDI and LG Chem platform launches. Secure METI certification reciprocity with MFDS to compress redundant thermal runaway validation campaigns. Defend against BYD's vertical scope expansion by locking European OEMs into long-term prismatic cell offtake agreements before EU battery passport mandates fully activate. For New Entrants and Emerging Players: The EU Green Deal battery sustainability mandate in Germany and France opens a window for carbon sourcing disclosure specialists with blockchain-tracked material flows. Target grid-scale stationary storage procurement channels where calendar aging tolerance specifications are less stringent than automotive qualification timelines. Enter through certified hard carbon anode supply contracts rather than finished cell manufacturing to bypass capital-intensive winding equipment investments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified chemical conglomerates seeking electrode manufacturing scale. Long-term viability over the mid-term analysis window hinges on securing automotive platform design-ins before incumbent qualification relationships solidify. Watch for inflection in EPA tailpipe rule stringency revisions that would compress US vehicle electrification procurement timelines and favor pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Precursor Refining | Captive needle coke and hard carbon supply locks in margin control against Chinese feedstock volatility. |
| Automotive Platform Design-In Agreement | Long-term offtake contracts with BYD or Panasonic anchor volume visibility through vehicle launch cycles. |
| EU Battery Passport Traceability Certification | Blockchain-tracked carbon sourcing documentation secures German and French OEM procurement priority. |
| Prismatic Cell Format Manufacturing Scale-Up | Rectangular aluminum housing production lines capture commercial vehicle pack integration specifications. |
| Cross-Border Safety Certification Harmonization | METI-MFDS reciprocal validation protocols compress regional market entry timelines for electrode suppliers. |
Methodological Framework
Document review covered customs trade data for carbon precursor flows, SAMR GB standard filings, and EU CSRD disclosure frameworks, complemented by interviews with electrode manufacturing plant managers, automotive OEM platform engineers, and carbon precursor procurement leads at Tier 1 suppliers. Secondary validation drew from METI subsidy award disclosures, KBA type-approval registries, and SEC filings of diversified chemical conglomerates. Bottom-up cell production estimates triangulated against top-down automotive electrification demand projections.
Cross-reference between historical capacity expansion patterns and expert panel inputs on fast-charging platform timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, end-use concentration, technology maturity, and application duty cycle. CAGRs derived from electrolyte formulation advancement curves and carbon electrode yield improvement trajectories. Industry-specific inputs incorporated EPA rulemaking comment filings and aviation electrification auxiliary power unit qualification protocols.
The model assumes a particular technology adoption path favoring electrochemical dual carbon architectures; alternative pathways for solid-state hybrid systems would alter the outlook for thermal management simplification value propositions. Deviation in China's SAMR export licensing posture for synthetic graphite would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Solid-State Battery Market