
 Asia Pacific Industrial Sensors Market | 2026-2036
Asia Pacific Industrial Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Sensors Market Outlook
CE marking under the EU AI Act's extraterritorial reach is rotating competitive eligibility for Asia Pacific suppliers serving European-linked supply chains. Texas Instruments leverages its analog heritage to sustain design-win rates in pressure sensor modules for process automation. STMicroelectronics anchors MEMS production scale through dedicated 8-inch fabrication in Singapore. Emerson Electric Co competes on integrated sensor-to-control system architectures for oil and gas deployments across Southeast Asia.
Asia Pacific industrial sensors are electromechanical or solid-state transducers that convert physical variables including pressure, temperature, displacement, and flow into standardized electrical signals, typically operating across ranges from minus 40 degrees Celsius to 125 degrees Celsius with accuracy thresholds of 0.1 to 0.5 percent full scale, serving primarily to enable closed-loop process control and predictive maintenance in automated manufacturing environments. Pressure sensors dominate value capture in oil and gas applications where safety monitoring mandates dictate specification rigor. Wireless technology segments are expanding fastest as battery-less energy harvesting and 5G-integrated backhaul reduce cabling infrastructure costs in brownfield facilities. Proximity sensors occupy mature margin pools in automotive manufacturing, though infrared variants are penetrating food and beverage lines for non-contact contamination detection.
Japan's METI enforces JIS standards for industrial sensor reliability that shape procurement specifications across precision manufacturing. China's MIIT administers GB standards and dual carbon goals that mandate energy-efficient sensor networks in heavy industry. South Korea's MFDS and KOSHA frameworks govern safety-critical sensor deployments in chemical processing. Stakeholders must monitor how divergent national certification timelines fragment product platform strategies across the region.
Market Dynamics
Smart factory investments by automotive manufacturers in Japan are accelerating sensor deployment across assembly lines, while China's GB standards for industrial IoT interoperability mandate upgraded digital sensor architectures that reshape procurement specifications.
Growth Catalysts
- Automotive assembly automation:Japanese manufacturers are embedding pressure and proximity sensors into robotic welding and painting lines to enable real-time quality feedback loops.
- MIIT dual carbon mandates:China's energy-efficiency regulations require heavy industry operators to deploy networked temperature and flow sensors for emissions monitoring and process optimization.
- Semiconductor fab expansion:South Korea's fabrication corridors are driving specialized environmental sensor procurement for cleanroom particle detection and chemical vapor monitoring.
Market Restraints
- Raw material concentration:Rare earth processing for MEMS substrates concentrates in Chinese supply chains, exposing sensor fabricators to input volatility and export restriction risk.
- JIS certification timelines:Japan's METI reliability standards impose extended validation periods that delay product launches and compress commercialization windows.
- Wireless substitution pressure:Battery-less energy harvesting architectures are eroding demand for traditional wired sensor installations in brownfield retrofit projects.
Strategic Opportunities
- Southeast Asia oil and gas:Integrated sensor-to-control systems for offshore platform safety monitoring remain underpenetrated in Indonesian and Malaysian waters.
- Food and beverage infrared:Non-contact contamination detection using thermal proximity sensors is opening new specification channels in Australian and Thai processing plants.
- 5G-integrated backhaul:The convergence of cellular connectivity and edge computing enables predictive maintenance subscriptions that transform sensor vendors into service providers.
Industry Challenges
- Embedded firmware expertise:Sensor manufacturers face acute shortages of engineers capable of integrating AI-driven edge analytics into legacy analog architectures.
- Legacy system integration:Brownfield facilities in China's rust belt regions operate proprietary fieldbus protocols that resist seamless digital sensor retrofit without costly gateway infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Sensors Market |
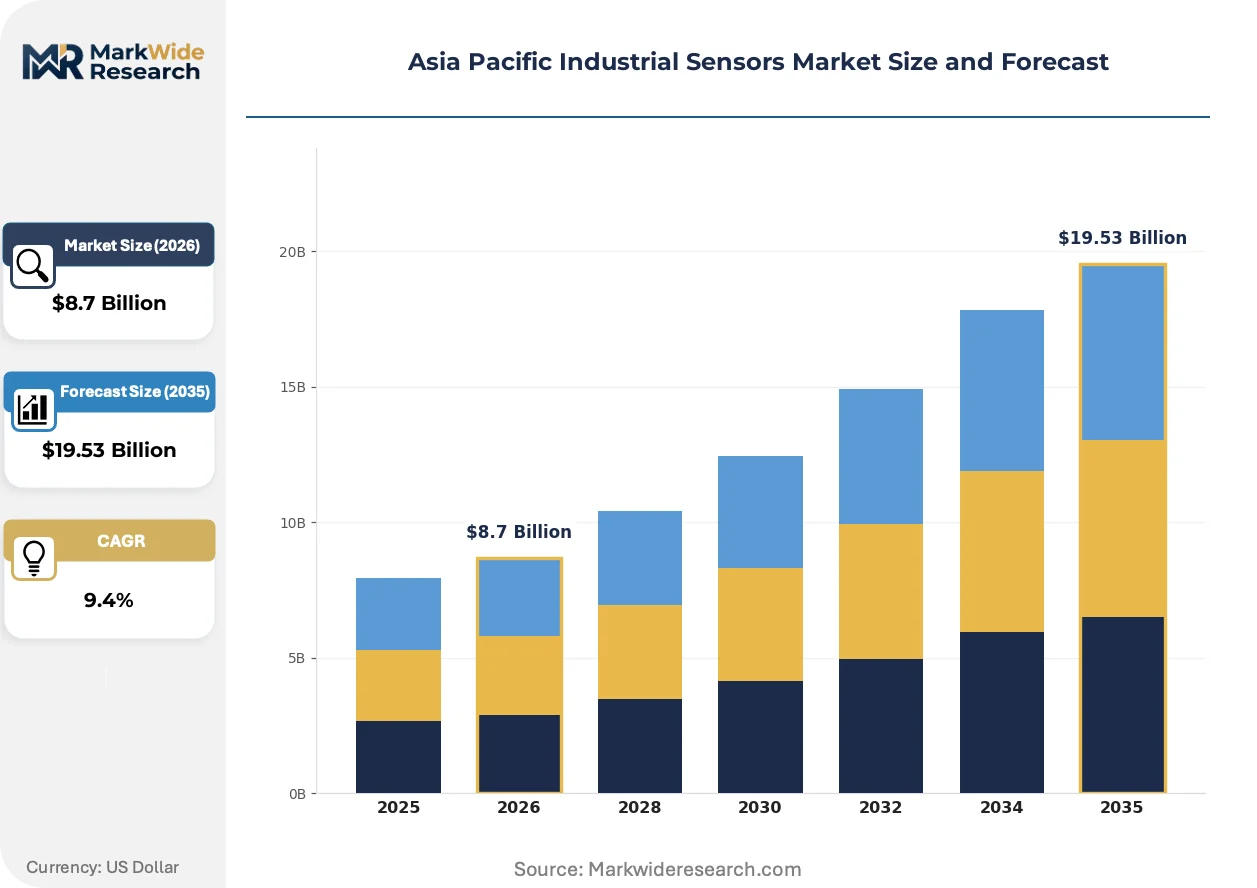
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Level Sensors Technology: Analog, Digital, Wireless, Infrared End User: Manufacturing, Oil & Gas, Food & Beverage, Transportation Application: Process Automation, Safety Monitoring, Asset Tracking, Environmental Monitoring |
| Companies Covered | Texas Instruments Incorporated, STMicroelectronics N.V., Emerson Electric Co, Rockwell Automation Inc., ABB Ltd., Honeywell International Inc., Siemens AG, Omron Corporation, TE Connectivity Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Sensors Market Strategic Shifts
Digital sensor architectures are displacing analog legacy installations across Asia Pacific manufacturing, while regulatory mandates and procurement model evolution reshape how industrial operators specify and source transducer technologies.
MEMS-based pressure transducers are displacing traditional piezoelectric assemblies in process automation applications. Chemical processors in South Korea's Yeosu industrial complex are adopting these solid-state alternatives for corrosion-resistant inline monitoring. The shift is compressing maintenance cycles and enabling predictive replacement schedules that reduce unplanned downtime.
China's GB standards for industrial IoT interoperability are mandating unified communication protocols across heavy industry sensor networks. The regulation forces steel and cement producers to retire proprietary fieldbus systems in favor of standardized digital architectures. Equipment suppliers are responding by pre-certifying sensor modules to MIIT specifications, accelerating procurement timelines for state-owned enterprise buyers.
Sensor-as-a-service contracting is displacing traditional capital equipment purchasing in Japanese automotive supply chains. Tier-one suppliers now specify outcome-based agreements where vendors retain ownership of installed sensor assets and charge per monitored parameter. The model concentrates most visibly in Toyota's Nagoya production network, where predictive maintenance guarantees have replaced upfront hardware transactions.
Asia Pacific Industrial Sensors Market Segmentation
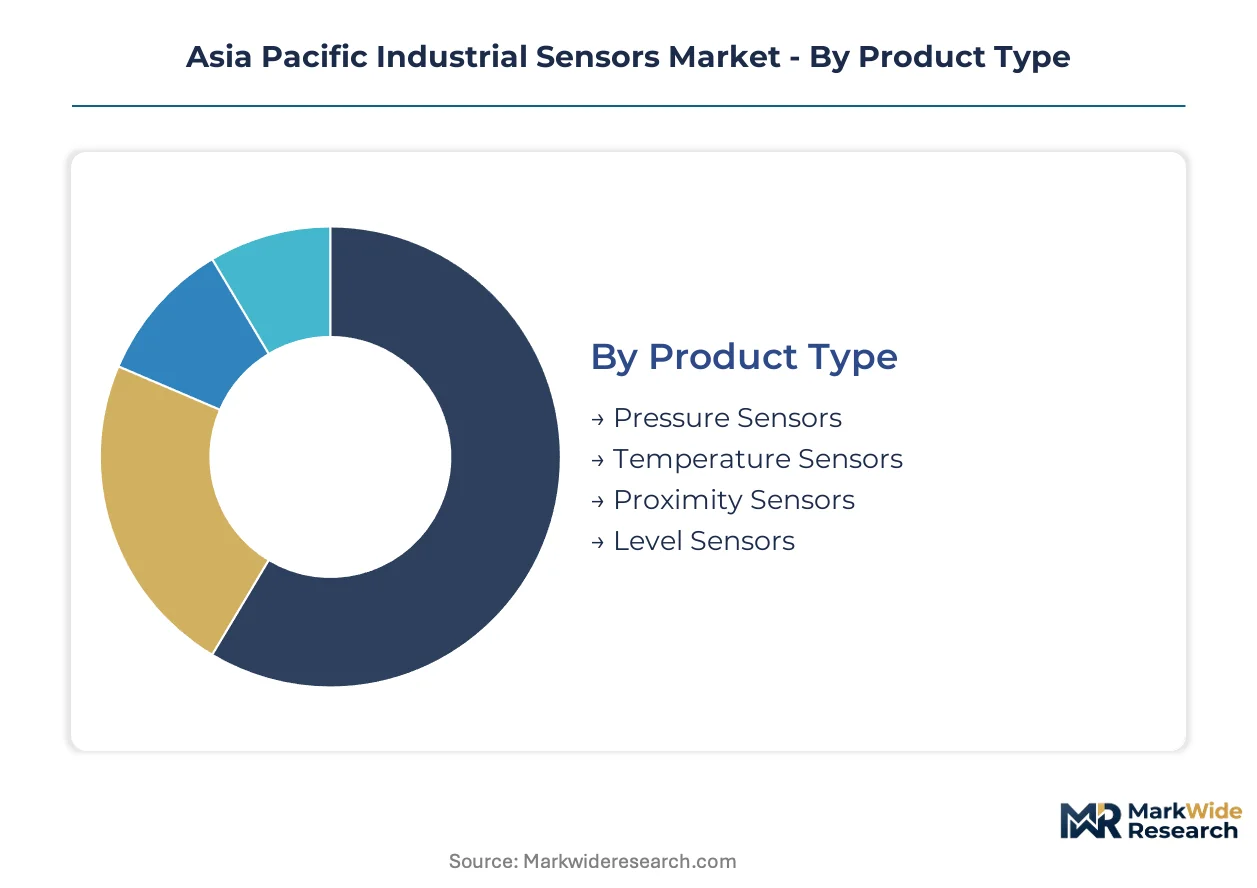
Industrial sensor procurement in Asia Pacific follows distinct channel patterns where product type determines integration complexity and technology selection drives aftermarket service attach rates. Understanding these segment interdependencies reveals how specification choices cascade through deployment architectures.
Product Type:
Pressure and temperature sensors move through systems integrators serving process industries, while proximity and level variants flow directly to OEM equipment builders and facility engineering teams.
- Pressure Sensors:Piezoelectric and MEMS-based transducers measure fluid and gas pressure across ranges from vacuum to 10,000 psi with 0.1% accuracy. Demand concentrates in Japan's automotive paint shops and South Korea's Yeosu petrochemical complex where METI and KOSHA safety mandates enforce continuous pipeline monitoring.
- Temperature Sensors:Thermocouple and RTD assemblies operate from minus 40 to 125 degrees Celsius for thermal process control. Chinese steel mills under MIIT dual carbon regulations are retrofitting blast furnaces with networked temperature arrays to optimize energy consumption and emissions profiles.
- Proximity Sensors:Inductive and capacitive variants detect object presence without physical contact for automated material handling.
- Level Sensors:Ultrasonic and radar technologies measure liquid and solid fill heights in storage vessels and process tanks.
Pressure sensors dominate installed base in heavy process industries. Proximity sensors are where expansion concentrates in automotive assembly automation.
Technology:
Cost tier stratification separates legacy analog installations from premium digital architectures, with wireless commanding service-contract premiums and infrared occupying specialized contamination-detection niches.
- Analog:4-20mA and 0-10V output signals persist in China's rust belt manufacturing facilities where proprietary fieldbus protocols resist digital migration without costly gateway infrastructure.
- Digital:IO-Link and Ethernet-IP enabled sensors provide diagnostic data streams and remote configuration capabilities. Japanese automotive suppliers specify these for predictive maintenance integration across Toyota's Nagoya production network.
- Wireless:Battery-less energy harvesting with 5G-integrated backhaul eliminates cabling in brownfield retrofit projects.
- Infrared:Thermal proximity detection enables non-contact contamination monitoring in food and beverage processing lines.
Analog retains volume leadership in legacy infrastructure. Digital architectures are climbing the fastest as GB standards mandate interoperable sensor networks.
End User:
Application maturity varies sharply by sector, with oil and gas demanding certified safety architectures and food and beverage prioritizing hygienic sensor housings over performance specifications.
- Manufacturing:Automotive and electronics assembly lines deploy multi-sensor arrays for robotic guidance and quality feedback. South Korean semiconductor fabs drive specialized environmental sensor procurement for cleanroom particle detection.
- Oil & Gas:Offshore platforms and refineries require explosion-proof pressure and temperature monitoring with SIL-rated safety integrity. Indonesian and Malaysian waters remain underpenetrated for integrated sensor-to-control systems.
- Food & Beverage:Stainless steel hygienic sensors withstand washdown protocols in Australian and Thai processing plants.
- Transportation:Railway and logistics infrastructure deploys asset tracking and condition monitoring sensors.
Manufacturing captures the largest revenue pool. Oil and gas presents the steepest expansion trajectory for integrated safety systems.
Application:
Customer type differentiation separates process automation buyers seeking operational efficiency from safety monitoring purchasers driven by regulatory compliance mandates.
- Process Automation:Closed-loop control systems integrate pressure, temperature, and flow sensors for real-time manufacturing optimization. Chinese cement producers under GB standards are retiring proprietary fieldbus systems for unified digital architectures.
- Safety Monitoring:Emergency shutdown and leak detection systems require certified sensors with diagnostic coverage. South Korea's MFDS and KOSHA frameworks govern chemical processor procurement specifications.
- Asset Tracking:RFID and wireless sensor networks monitor equipment location and condition across distributed facilities.
- Environmental Monitoring:Emissions and effluent sensors track regulatory compliance parameters.
Process automation commands the highest sensor density per facility. Safety monitoring is gaining share fastest as regulatory enforcement tightens across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's sensor procurement dominance, while Japan's Chubu Centrair International Airport anchors Nagoya's automotive supply chain sensor flows. These infrastructure nodes concentrate specification authority and certification requirements across the region.
China
Steel mills in Hebei province deploy networked temperature arrays under MIIT dual carbon mandates to optimize blast furnace emissions. GB standards for industrial IoT interoperability force retirement of proprietary fieldbus systems in favor of unified digital architectures. The Yangtze River Delta concentrates sensor fabrication scale, with Shanghai-based systems integrators pre-certifying modules to accelerate state-owned enterprise procurement timelines.
Japan
Automotive manufacturers embed pressure and proximity sensors into robotic welding lines across Toyota's Nagoya production network. METI enforces JIS reliability standards that impose extended validation periods, compressing commercialization windows for new entrants. The Kanto region around Tokyo hosts precision manufacturing clusters where sensor-as-a-service contracting displaces traditional capital equipment purchasing among tier-one suppliers.
South Korea
Semiconductor fabrication corridors in Gyeonggi province drive specialized environmental sensor procurement for cleanroom particle detection and chemical vapor monitoring. MFDS and KOSHA frameworks govern safety-critical sensor deployments in Yeosu petrochemical complexes. The Seoul Capital Area anchors MEMS production scale through dedicated fabrication facilities serving process automation applications.
Indonesia
Offshore oil and gas platforms in the Java Sea require explosion-proof pressure monitoring with SIL-rated safety integrity. The country's national energy regulator mandates continuous pipeline monitoring systems that favor integrated sensor-to-control architectures. Batam island's industrial zone concentrates procurement specification authority for Indonesian and Malaysian waters safety systems.
Australia
Food and beverage processors in Queensland deploy stainless steel hygienic sensors for washdown protocols in meat and dairy operations. Thermal proximity detection enables non-contact contamination monitoring across Thai-Australian supply chains. The Port of Melbourne's logistics infrastructure anchors condition monitoring sensor deployment for distributed mining equipment fleets.
Asia Pacific Industrial Sensors Market Competitive Environment
Listed leaders compete with private specialists across certification depth and integration capability. The vendor base stratifies into three tiers: diversified electronics conglomerates with analog heritage, MEMS-focused semiconductor fabricators, and industrial automation specialists with control system integration expertise. Two strategic archetypes dominate competitive positioning: scale-driven component suppliers competing on design-win rates, and solution architects bundling sensor hardware with predictive maintenance software. M&A activity concentrates on edge analytics capabilities, while capacity expansion targets 8-inch MEMS fabrication in Singapore and Penang.
Among diversified electronics conglomerates, Texas Instruments Incorporated and STMicroelectronics N.V. exemplify scale-driven component suppliers with established analog and MEMS production legacies. Emerson Electric Co occupies a position within the solution architect tier, representing integrated sensor-to-control system capability for process industries. These three companies anchor the competitive structure, with Texas Instruments and STMicroelectronics sitting within the semiconductor fabrication archetype and Emerson anchoring the industrial automation integration segment.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| Emerson Electric Co |
| Rockwell Automation Inc. |
| ABB Ltd. |
| Honeywell International Inc. |
| Siemens AG |
| Omron Corporation |
| TE Connectivity Ltd. |
| Others |
Value Chain & Pricing Dynamics
Eight-inch MEMS fabrication scale in Singapore and Penang anchors cost floors across Asia Pacific sensor markets, concentrating wafer-level economics among fabricators with dedicated foundry lines while compressing margin structures for second-tier assemblers lacking captive capacity.
Pricing Analysis
Certification level creates the primary spread between JIS-validated modules for Japanese automotive lines and uncertified commodity pressure transducers serving China's rust belt retrofit projects. Three-tier pricing structure across premium SIL-rated safety sensors, standard industrial-grade digital architectures, and economy analog legacy units reflects differentiation by METI/MIIT compliance burden and predictive maintenance software bundling. Cost compression in the analog tier intensifies as wireless energy-harvesting substitutes erode wired installation demand. State-owned steel mills in Hebei province exhibit acute price sensitivity, while semiconductor fabs in Gyeonggi province prioritize specification rigor over unit cost.
Supply Chain Analysis
Shanghai port congestion and container availability fluctuations on the transpacific lane elevate inbound logistics costs for MEMS substrate shipments originating from Chinese rare earth processing facilities. Supply concentrates in China for MEMS materials, Singapore and Malaysia for 8-inch wafer fabrication, and Japan for precision assembly equipment. Rare earth dependencies for piezoelectric substrates and specialized ceramic housings tether sensor fabricators to concentrated upstream refining. Single-source vulnerability in Chinese rare earth export licensing poses structural risk. Distribution runs through Shanghai-based systems integrators for state-owned enterprise procurement and direct OEM relationships for Japanese automotive tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless sensor architectures and battery-less energy harvesting threaten traditional wired incumbent positions, forcing established suppliers to defend installed base relationships through service-model transformation.
For Market Incumbents: Shield core automotive design-win positions in Toyota's Nagoya network by embedding predictive maintenance software subscriptions that raise switching costs for tier-one procurement committees. Deepen backward integration into MEMS wafer capacity at Singapore facilities to offset rare earth price volatility exposure from Chinese substrate suppliers. Counter wireless substitution pressure by certifying hybrid wired-wireless gateway modules to MIIT interoperability mandates. For New Entrants and Emerging Players: Differentiate on edge-analytics firmware integration for brownfield facilities in China's rust belt regions, where legacy fieldbus protocol translation creates specification gaps that incumbent analog suppliers ignore. Target Indonesian and Malaysian offshore oil and gas waters for integrated sensor-to-control safety systems, the most penetrable geography given underdeveloped local integration expertise. Pursue sensor-as-a-service contracting models with Australian food and beverage processors seeking contamination detection outcome guarantees without capital equipment ownership. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor fabricators with captive 8-inch MEMS capacity and industrial automation specialists with predictive maintenance software stacks. Long-term viability hinges on AI-driven edge analytics integration capability rather than hardware component margins alone. Acquisition target archetype: mid-scale digital sensor vendors with pre-certified GB/MIIT module libraries and embedded firmware engineering teams. Watch for inflection when JIS certification timelines compress from validation backlog clearance at METI testing facilities.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Capacity Expansion | Singapore-based 8-inch wafer additions secure substrate supply independence from Chinese rare earth volatility. |
| GB Standards Pre-Certification Program | MIIT-aligned module libraries accelerate state-owned enterprise procurement timelines in Yangtze River Delta. |
| Predictive Maintenance Software Integration | Edge-analytics subscriptions transform hardware vendors into service providers with recurring revenue streams. |
| Wireless Energy Harvesting Partnership | Battery-less architectures with 5G backhaul capture brownfield retrofit demand from cabling-averse facilities. |
| Sensor-as-a-Service Contracting Model | Outcome-based agreements with Toyota tier-one suppliers displace upfront capital equipment transactions. |
Study Parameters
A standing panel of plant engineers at Japanese automotive assembly facilities, procurement directors at Chinese state-owned steel enterprises, MEMS fabrication operations managers in Singapore, and safety system integrators for Indonesian offshore platforms provided ongoing calibration against secondary validation from MIIT policy filings, METI JIS standard updates, customs trade data for sensor component flows, and SEC disclosures from listed industrial automation suppliers. Bottom-up demand modeling from end-user specification interviews triangulated against top-down market sizing from fabrication capacity and systems integrator revenue aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled sensor procurement by product type, technology architecture, end-use sector intensity, and application safety criticality, with CAGRs derived from segment-level demand elasticity and replacement cycle analysis. Forecast inputs incorporated GB standards implementation timelines, JIS certification queue lengths, and semiconductor fab expansion schedules for cleanroom environmental monitoring demand.
The analysis sits within stated boundaries; outcomes outside sustained MIIT dual carbon enforcement, stable rare earth export licensing, and continued automotive smart factory investment would require recalibration. Forecasts reflect assumptions regarding wireless substitution velocity and predictive maintenance subscription adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Non-Contact Infrared Thermometer Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Global Temperature Sensors Market