
 Cable Management Accessories Market | 2026-2036
Cable Management Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Management Accessories Market Intelligence
The replacement of traditional PVC with low-smoke, zero-halogen (LSZH) compounds in cable sleeves and ties is expanding product application in confined public spaces. Panduit leverages its extensive product portfolio to serve data center and enterprise clients. TE Connectivity sustains its market position through a focus on high-performance connectors and accessories for harsh environments. Belden differentiates with specialized solutions for industrial and broadcast applications.
Cable management accessories are components used to organize, secure, and protect electrical or data cables within an enclosure or along a pathway. These products, including cable ties made from nylon 6/6 and metallic cable trays, ensure operational safety and simplify maintenance. Within product types, cable ties and clips represent a high-volume, commoditized segment, while engineered cable trays offer higher margins. Data centers and telecommunications are the primary application areas, driven by demand from large-scale operators and electrical contractors.
Product compliance with the EU's Restriction of Hazardous Substances (RoHS) directive and UL certification in the United States is mandatory for market access. National building codes and fire safety standards, such as those governed by the National Electrical Code (NEC) in the US, dictate material specifications for plenum and riser-rated accessories. Vendor selection will increasingly hinge on the ability to provide certified, sustainable materials that meet evolving international environmental and safety regulations.
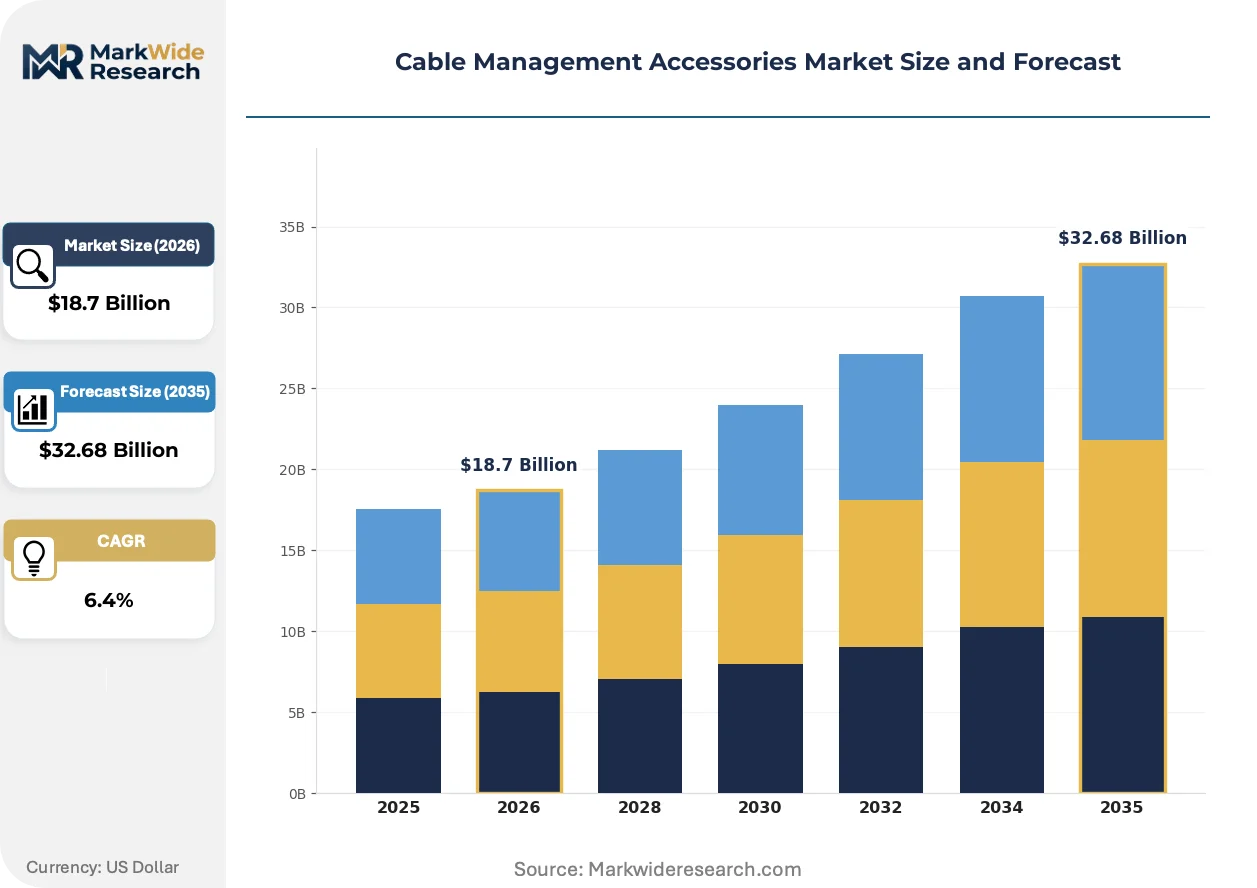
Market Dynamics
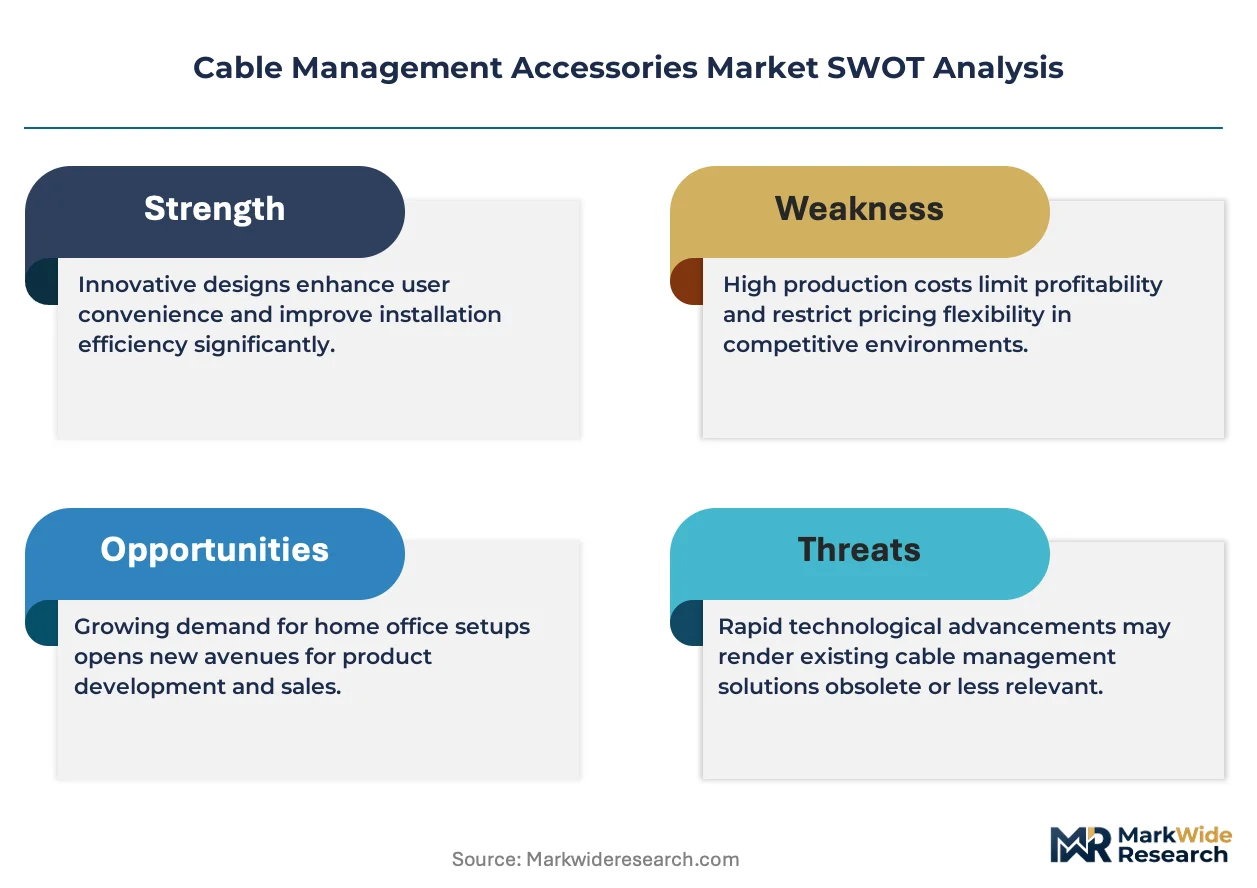
The convergence of data center infrastructure density and stringent fire safety regulations serves as the central force shaping the market. This dynamic compels a shift away from commodity components toward engineered, certified solutions like low-smoke, zero-halogen accessories.
Growth Catalysts
- Data Center Expansion:Hyperscale data center construction in the United States and Northern Europe creates sustained, high-volume demand for engineered cable trays, high-density ties, and fiber management accessories to support massive server deployments.
- LSZH Material Mandates:Stricter fire safety codes for public infrastructure, particularly in European Union transit and tunnel projects, mandate the use of low-smoke, zero-halogen (LSZH) materials, displacing traditional PVC in cable sleeves and ties.
- Grid Modernization Programs:National power grid upgrades in countries like China and India necessitate extensive use of durable, weather-resistant cable management accessories for new transmission and distribution lines, ensuring long-term operational reliability.
Market Restraints
- Raw Material Volatility:Price fluctuations in nylon 6/6 and other engineering polymers, driven by petrochemical market dynamics, directly impact manufacturing costs and compress margins for high-volume, commoditized products like standard cable ties.
- Threat from Integrated Solutions:The adoption of pre-terminated cable assemblies and integrated wire harnesses in automotive and industrial OEM sectors reduces the requirement for discrete cable management components, acting as a substitution threat.
- Complex Certification Pathways:Navigating disparate and evolving regulatory requirements, such as UL certification in the US and specific GB standards in China, creates significant cost and time-to-market barriers for suppliers.
Strategic Opportunities
- Renewable Energy Infrastructure:The global build-out of solar and wind farms presents an opportunity for specialized, UV-resistant and corrosion-proof cable accessories designed for long-term exposure in harsh outdoor environments.
- Industrial Automation Niche:Developing accessories for robotics and automated manufacturing lines that withstand constant motion, abrasion, and chemical exposure opens a high-margin segment for specialized suppliers.
- Sustainable Material Development:Formulating bio-based or recycled-content polymers that meet performance specifications and fire safety standards offers a path to differentiation for vendors targeting environmentally conscious enterprise customers.
Industry Challenges
- Compliance Documentation Burden:Maintaining up-to-date documentation for substance regulations like RoHS and REACH across thousands of individual SKUs represents a significant and continuous administrative challenge for manufacturers and distributors.
- Counterfeit Product Infiltration:The proliferation of low-cost, non-compliant counterfeit cable accessories, particularly in developing economies, erodes brand equity and introduces significant safety and liability risks into installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Management Accessories Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Ties, Cable Clips, Cable Trays, Cable Lugs, Cable Sleeves Application: Data Centers, Telecommunications, Electrical Wiring, Power Distribution, Security Systems End User Industry: Telecom Operators, Data Processing Centers, Electrical Contractors, Security Installers, Residential Developers Distribution Channel: Direct Sales, Online Retail, Distributors, System Integrators, Electrical Wholesalers |
| Companies Covered | TE Connectivity, Phoenix Contact, Belden, Tripp Lite, Amphenol, Panduit, Chatsworth Products, HARTING, Leviton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Management Accessories Market Strategic Shifts & Innovations
Product evolution is driven by the dual pressures of material science advancements and tightening international safety standards. This forces a market bifurcation between high-performance, certified solutions for critical applications and commoditized products for less demanding environments.
Advanced low-smoke, zero-halogen (LSZH) compounds provide critical fire safety benefits by reducing toxic fume and smoke emission. Data centers, mass transit systems, and public buildings are rapidly adopting these materials to comply with updated building and electrical codes. This material innovation is consolidating the supply base toward manufacturers with the advanced compounding capabilities and certification access necessary to compete.
The European Union's Restriction of Hazardous Substances (RoHS) directive continues to exert significant influence on product design and material selection. It compels manufacturers to eliminate specified hazardous materials, impacting everything from metallic coatings on cable trays to the pigments used in plastic ties. Consequently, global electronics and electrical equipment firms must validate their entire supply chain, including accessory providers, to ensure compliance for market access.
A notable behavioral shift involves the adoption of project-based kitting and just-in-time delivery for large infrastructure builds. This model disrupts traditional wholesale distribution channels by favoring direct-from-manufacturer or specialized logistics provider relationships that reduce on-site inventory. The trend is most visible in large-scale data center construction projects across North America, where contractors prioritize supply chain efficiency and minimized labor.
Cable Management Accessories Market Segmentation
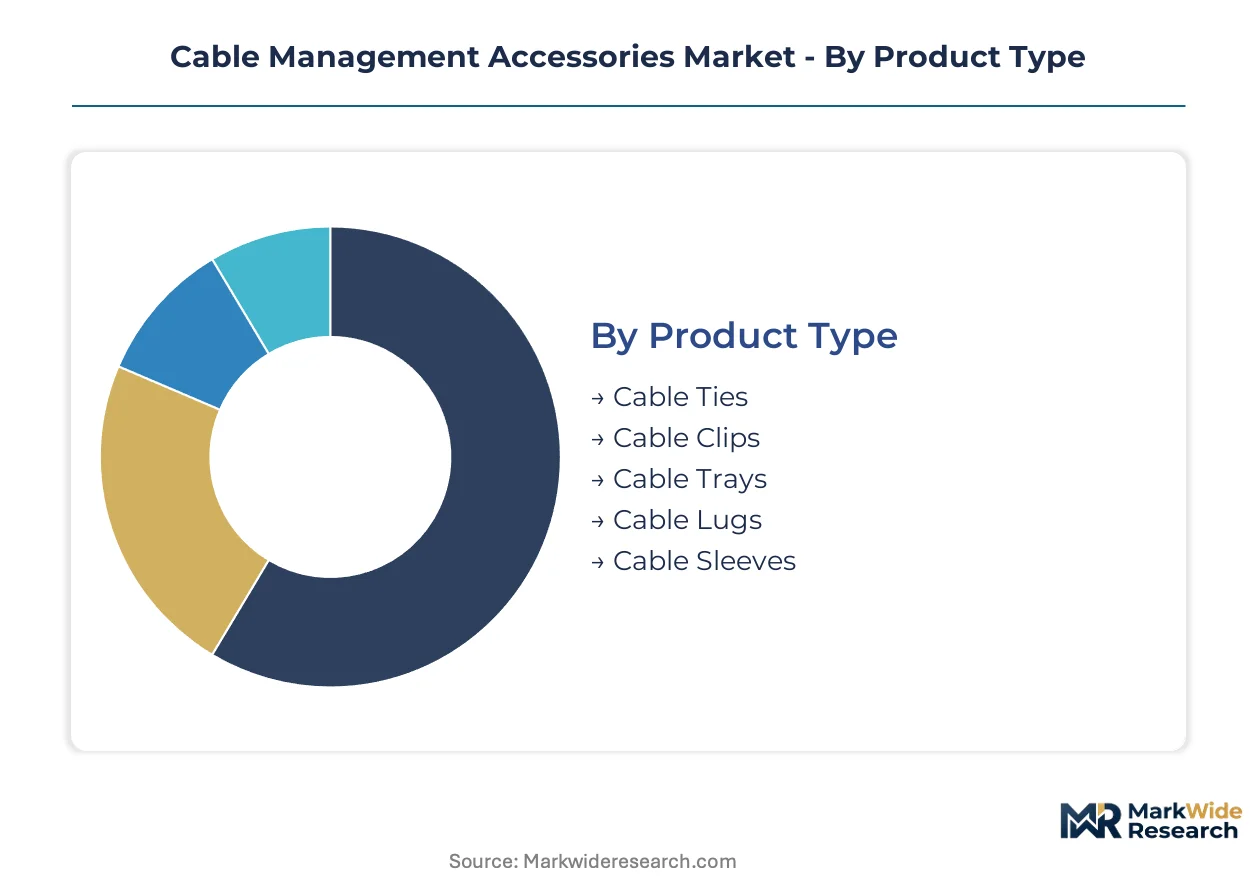
Understanding the segmentation of the cable management accessories market provides clarity on specific product demands and evolving application requirements. This analysis dissects the market by product type, application, end user industry, and distribution channel, highlighting distinct commercial landscapes within each category. It helps identify areas of high growth and specialized needs across the industry.
Product Type:
The market for cable management accessories bifurcates between high-volume, commoditized products and specialized, engineered solutions with higher price points. Cable ties and clips represent the former, while advanced cable trays and sleeves fall into the latter category.
- Cable Ties:These fasteners, often made from nylon 6/6, secure electrical cables and wires, providing organization and preventing entanglement. Demand is particularly strong in data center installations in China, driven by extensive telecommunications infrastructure upgrades.
- Cable Trays:Metallic or non-metallic structures form organized pathways for numerous cables, supporting heavy loads and ensuring proper ventilation. Hyperscale data center construction in the United States and Northern Europe drives significant demand for engineered cable tray systems.
- Cable Clips:These small devices anchor single or small bundles of cables to surfaces.
- Cable Lugs:Connect electrical cables to appliances, other cables, or surfaces, ensuring a secure electrical contact.
- Cable Sleeves:Protective coverings for cable bundles, often made from flexible materials like braided PET or LSZH compounds.
Mature deployment sits with Cable Ties, serving a broad range of general-purpose applications. Newer deployment is concentrated in Cable Trays, especially for large-scale infrastructure projects.
Application:
Contribution to market margin varies significantly across different applications, with highly technical environments demanding more specialized and higher-value cable management solutions. Less complex applications often rely on standard, cost-effective components.
- Data Centers:These facilities require high-density, fiber management accessories and specialized pathways to organize vast networks of power and data cables. Sustained expansion of cloud infrastructure in the United States drives continuous demand for these critical components.
- Telecommunications:Extensive network infrastructure, including fiber optic deployments and 5G rollouts, necessitates robust and weather-resistant cable management solutions. National grid modernization programs in India create substantial demand for durable accessories.
- Electrical Wiring:This segment involves organizing cables within commercial, industrial, and residential buildings for power and lighting.
- Power Distribution:Accessories used in substations, transmission lines, and utility grids to secure and protect heavy power cables.
- Security Systems:Cable management for surveillance cameras, access control systems, and alarm installations, often emphasizing discreet routing.
Specialized accessory requirements are most pronounced in Data Centers. Broader adoption is observed across Electrical Wiring applications.
End User Industry:
The concentration of supply chains differs among end user industries, with some favoring direct procurement for scale and others relying on diverse distribution networks for project-specific needs.
- Telecom Operators:Large-scale purchasers of cable management accessories for network build-outs and maintenance, often engaging in direct procurement relationships with manufacturers. Extensive fiber network upgrades in China drive substantial volume.
- Electrical Contractors:Professionals responsible for installing electrical systems in various settings, sourcing a wide range of cable management products through wholesale channels. Commercial construction projects across Germany generate consistent demand.
- Data Processing Centers:Operators of large data facilities, requiring specialized and high-performance cable management solutions.
- Security Installers:Companies that implement security systems, needing discreet and efficient cable routing solutions.
- Residential Developers:Builders of housing units, typically requiring standard, cost-effective cable management components for new construction.
Volume purchasing dominates among Telecom Operators. Project-specific sourcing characterizes Security Installers.
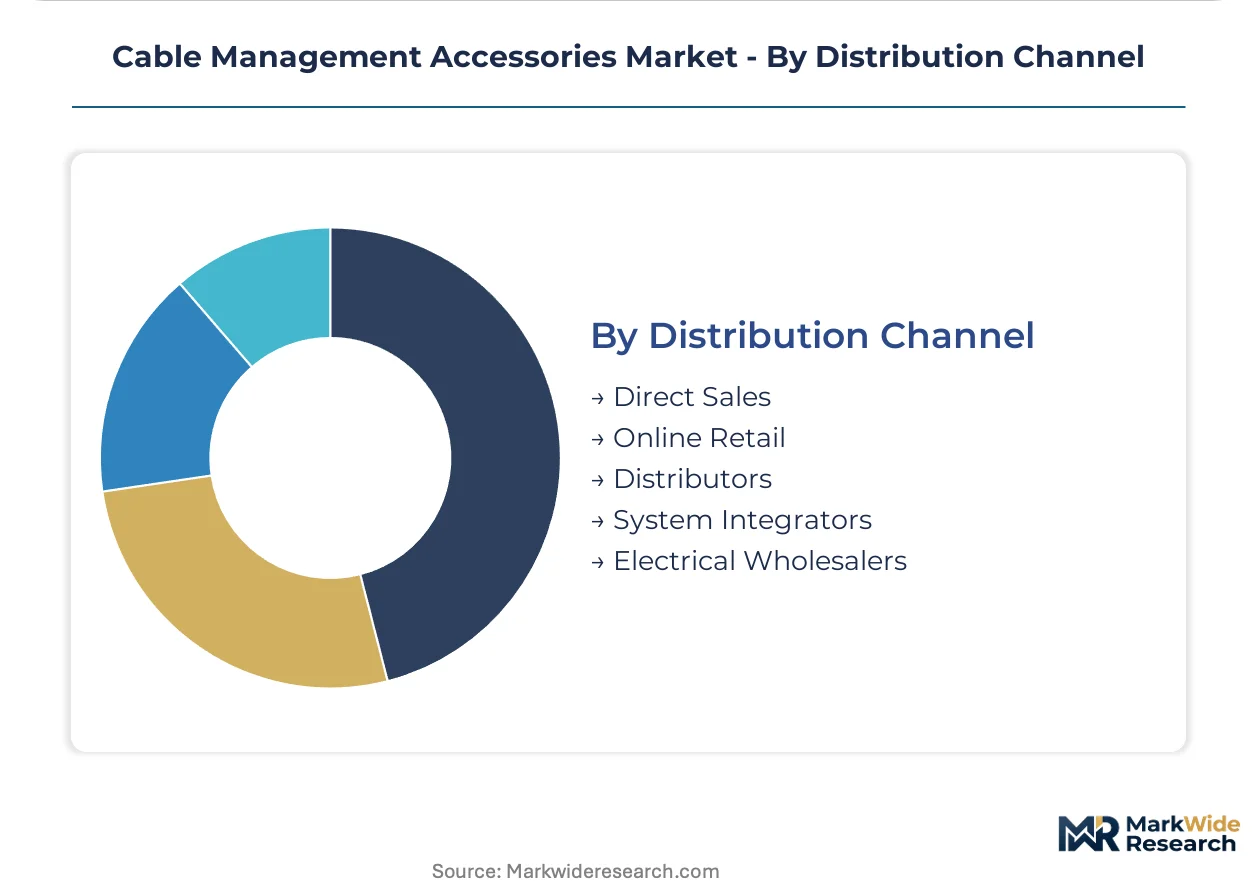
Distribution Channel:
The maturity of distribution channels impacts market reach, with established networks providing broad availability and newer channels offering convenience or specialized services.
- Distributors:These entities provide broad market access, maintaining inventory and logistics for a wide array of cable management products to diverse customers. They are a primary channel for electrical contractors in the United Kingdom.
- Electrical Wholesalers:Specialized distributors focused on electrical products, offering local availability and technical support to electricians and contractors. They serve as a critical link for small to medium-sized projects in France.
- Direct Sales:Manufacturers selling directly to large enterprise customers or for specialized projects, often involving custom solutions.
- Online Retail:E-commerce platforms offering convenient access to a wide range of cable management accessories for smaller purchases and individual users.
- System Integrators:Companies that combine various components into a single system, often bundling cable management accessories with other equipment.
Traditional channels like Distributors maintain significant market share. Emerging channels include Online Retail, which is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cable management accessories concentrates in regions undergoing significant infrastructure development. Data center expansion and stringent fire safety regulations primarily drive this market's regional dynamics. National power grid modernization programs also contribute to sustained growth across key geographies.
China
China's extensive telecommunications and power grid upgrades generate substantial demand for cable management accessories. GB standards for material specifications ensure compliance for products utilized in these critical infrastructure projects. The Yangtze River Delta region experiences substantial demand for accessories supporting its rapidly expanding digital infrastructure and manufacturing bases.
United States
Hyperscale data center construction and cloud infrastructure expansion in the United States create continuous demand for advanced cable management solutions. The National Electrical Code (NEC) dictates material specifications for plenum and riser-rated accessories, ensuring fire safety. Northern Virginia continues as a primary hub for data center development, driving high-volume demand for engineered cable trays and fiber management solutions.
Germany
Stricter fire safety codes for public infrastructure and robust commercial construction projects drive demand in Germany. The EU's Restriction of Hazardous Substances (RoHS) directive and LSZH material mandates influence product design and selection. Commercial construction projects across major cities like Berlin and Munich generate consistent demand for compliant cable management solutions.
India
India's national power grid modernization programs and telecommunications network expansion necessitate extensive use of durable cable management accessories. BIS standards ensure quality and safety for electrical products, impacting market access for suppliers. Infrastructure development in metropolitan areas like Mumbai and Delhi requires weather-resistant accessories for new transmission lines and communication networks.
Cable Management Accessories Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the need to meet surging demand from data centers and critical infrastructure projects. The market structure features a tiered competitive environment, with established global players and agile specialized niche providers. Strategic archetypes include high-volume commodity manufacturers, engineered solution providers for demanding environments, and regional specialists. Companies actively pursue portfolio diversification and targeted geographic expansion to capture new opportunities across various end-use sectors.
On the premium-tier vector, TE Connectivity and Panduit exemplify providers offering high-performance solutions for critical applications. TE Connectivity, a global entity, operates within the specialized connector and harsh environment accessory market, reflecting its focus on high-reliability components. Panduit, an American-based corporation, represents a broad portfolio provider serving data center and enterprise clients with extensive cable management systems designed for scale. Belden, another American-headquartered company, occupies a position focused on specialized solutions for industrial and broadcast applications, highlighting differentiation through niche market expertise and robust product design.
| Leading Market Players |
|---|
| TE Connectivity |
| Phoenix Contact |
| Belden |
| Tripp Lite |
| Amphenol |
| Panduit |
| Chatsworth Products |
| HARTING |
| Leviton |
| Others |
Cost & Logistics Intelligence
The European Union's Restriction of Hazardous Substances (RoHS) directive gates qualified supply and premium-tier pricing access for cable management accessories. This mandate compels manufacturers to invest in compliant materials, impacting market entry and product cost structures.
Pricing Analysis
High-volume, commoditized products like standard cable ties operate on transactional pricing, while engineered solutions for critical applications command project-based rates. Price differentiation stems from UL certification and the use of LSZH compounds, providing a premium for safety-critical components. Raw material volatility, particularly in nylon 6/6, creates cost compression for basic products. Data centers exhibit lower price sensitivity for specialized accessories, whereas general electrical wiring applications remain highly cost-conscious.
Supply Chain Analysis
China's GB standards for material specifications reshape sourcing for critical infrastructure projects, favoring domestic or certified international suppliers. The global supply chain draws from key manufacturing hubs in China and Germany for polymer-based accessories and metallic trays. Raw material dependencies on nylon 6/6 and engineering polymers introduce significant commodity price volatility risks. Distribution predominantly runs through electrical wholesalers and direct sales channels for large-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable management accessories market is in a technology-transition phase, driven by low-smoke, zero-halogen (LSZH) materials displacing traditional PVC. This shift mandates material innovation and certification for critical applications.
For Market Incumbents: Extend product portfolios to include specialized LSZH and UV-resistant solutions for renewable energy infrastructure, countering the threat from integrated solutions. Invest in advanced compounding capabilities and UL/RoHS certification to maintain market access and differentiate from counterfeit products. Consolidate supply chains for key raw materials like engineering polymers to mitigate volatility. Control distribution channels through strategic partnerships with electrical wholesalers.
For New Entrants and Emerging Players: Enter via niche segments like industrial automation, developing accessories for robotics that withstand extreme motion and chemical exposure. Target underpenetrated markets in emerging economies with certified, mid-tier solutions. A go-to-market angle focused on sustainable material development, such as bio-based polymers, can attract environmentally conscious enterprise customers. Leverage online retail platforms for efficient market access and smaller project sales.
For Investors and Strategic Acquirers: Widespread adoption of LSZH materials in commercial building codes is the leading indicator that value will accrue to certified solution providers. The market exhibits long-term viability, supported by sustained data center expansion and grid modernization programs. Acquisition targets should be specialized manufacturers with strong intellectual property in material science or robust certification portfolios. Watch for increased M&A activity among mid-sized players seeking compliance and scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meet surging demand from hyperscale data center construction in the United States. |
| Green Manufacturing Transition | Align with EU's RoHS directive and evolving sustainability mandates for material selection. |
| Product Launch | Introduce specialized UV-resistant accessories for solar farm and wind turbine installations. |
| Strategic Partnership | Secure access to advanced LSZH compounding technologies for fire-safe components. |
| Geographic Expansion | Penetrate growing infrastructure markets in China and India through local partnerships. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with electrical contractors, data center operators, and procurement leads. This approach involved validating market sizing and trends through bottom-up and top-down triangulation. Secondary sources included UL standards, National Electrical Code (NEC) guidelines, and EU RoHS directives, ensuring comprehensive data coverage.
The analytical framework reconciled multiple data streams to construct volume and value projections across the analysis window. Segmentation dimensions modeled included product type, application, end user industry, distribution channel, and material composition. Compound annual growth rates were derived from historical trends and projected future demand, with key inputs such as hyperscale data center build rates and national grid modernization budgets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme raw material volatility or rapid regulatory shifts. These forecasts reflect assumptions regarding infrastructure investment and technological adoption patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Detector Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
North America Wire and Cable Market
Cables
LED Cable Market
Cables
EDM Wires Market
Cables
High-Speed Interconnects Market
Cables
Power and Signal Cables Market
Cables
Global Cable Blowing Equipment Market
Cables
GCC Cable Accessories Market
Cables
Europe Cable Management Market
Cables
Cable Assembly Market
Cables
Network Cable Tester Market
Cables
United States Cable Accessories Market
Cables
Cable Testers Market
Cables
Low-Temperature Cable Market
Cables
US Cables Market