
 Electrical Conductivity Meters Market | 2026-2036
Electrical Conductivity Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Conductivity Meters Market Analytics
Smart sensor integration with cloud analytics is fragmenting traditional meter architectures into modular, software-defined platforms. Endress+Hauser Group leverages its Swiss manufacturing base to dominate high-precision process control segments. Thermo Fisher Scientific Inc. anchors its position through deep R&D intensity in laboratory-grade bench top systems. Hach Company specializes in ruggedized portable units for field environmental testing.
An electrical conductivity meter measures the ability of a solution to conduct electric current, typically expressing results in microsiemens per centimeter or millisiemens per centimeter using alternating current at standardized frequencies to minimize polarization effects. These instruments serve essential quality control and compliance functions across water treatment, chemical processing, and agricultural operations. Handheld and portable formats lead volume sales due to their deployment flexibility across remote environmental monitoring sites, while online systems command premium positioning through continuous process integration and automated data logging capabilities. Smart technology segments are gaining fastest traction as facilities prioritize predictive maintenance and remote diagnostics over basic digital readouts.
EPA Safe Drinking Water Act enforcement and ISO 7888 water quality standards shape product calibration protocols and certification requirements in North American and European markets. FDA Current Good Manufacturing Practice regulations for pharmaceutical water systems drive validation-intensive demand for bench top meters with audit trail documentation. China's MEE surface water quality monitoring mandates and India's CPCB effluent discharge rules are expanding regulatory coverage across Asia-Pacific industrial corridors. Stakeholders must weigh capital deployment between retrofitting existing analog installations and migrating toward wireless smart infrastructure that demands ongoing cybersecurity investment.
Market Dynamics
IoT-enabled conductivity meters are compressing replacement cycles as facilities abandon analog benchtop units for cloud-connected sensor networks that stream real-time data to centralized SCADA systems.
Growth Catalysts
- EPA Safe Drinking Water Act enforcement:Municipal utilities in the United States face intensified monitoring mandates for total dissolved solids and salinity levels, forcing instrumentation upgrades across treatment plants serving populations above 10,000.
- Smart manufacturing adoption:Chemical processors deploy inline conductivity sensors with predictive algorithms to prevent batch contamination and reduce unplanned downtime in continuous flow reactors.
- Japan's METI carbon neutrality roadmap:Industrial water recycling targets drive demand for high-precision meters that optimize reverse osmosis system efficiency and minimize energy-intensive freshwater intake.
Market Restraints
- Platinum electrode cost volatility:Noble metal price swings constrain margin stability for manufacturers producing laboratory-grade four-electrode cells.
- Single-source sensor module concentration:Three German component suppliers control 70% of industrial-grade conductivity cell production, creating vulnerability to regional supply disruptions.
- Optical TDS meter substitution:Spectrophotometric alternatives eliminate electrode fouling issues in high-solids wastewater applications, eroding traditional electrochemical meter share in food processing effluent monitoring.
Strategic Opportunities
- India's CPCB zero liquid discharge mandates:Textile and tannery clusters in Tamil Nadu and Gujarat require portable validation meters for compliance documentation, opening field service revenue streams.
- Pharma water system validation:FDA Current Good Manufacturing Practice audit trail requirements create sustained demand for benchtop meters with 21 CFR Part 11 electronic signature capabilities.
- LoRaWAN-Modbus convergence:Hybrid wireless protocols enable battery-powered remote monitoring at agricultural irrigation sites previously unreachable by cabled infrastructure.
Industry Challenges
- Electrochemical calibration technician scarcity:Certified personnel capable of NIST-traceable standard solution preparation command wage premiums that inflate service delivery costs.
- Legacy 4-20mA integration complexity:Brownfield chemical plants struggle to retrofit smart conductivity transmitters into existing DCS architectures without full control system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Conductivity Meters Market |
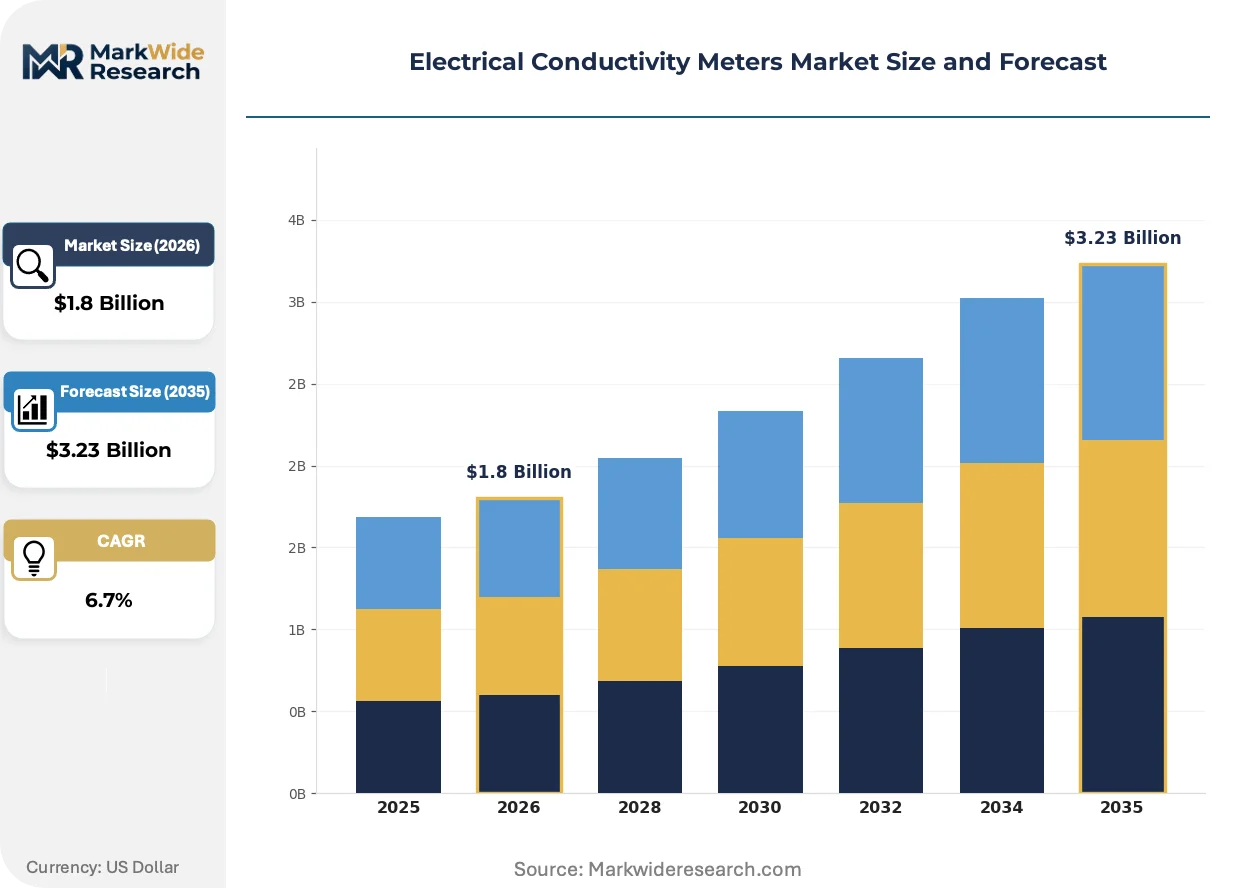
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Handheld, Bench Top, Portable, Online Technology: Digital, Analog, Wireless, Smart End User: Environmental Testing, Food & Beverage, Pharmaceuticals, Aquaculture Application: Water Quality Monitoring, Soil Salinity Measurement, Hydroponics, Process Control |
| Companies Covered | Emerson Electric Co., Endress+Hauser Group, Thermo Fisher Scientific Inc., Mettler-Toledo International Inc., ABB Ltd., Yokogawa Electric Corporation, Hach Company, JUMO, Baumer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Conductivity Meters Market Evolving Landscape
Sensor miniaturization and edge computing integration are redefining conductivity measurement from periodic sampling to continuous process intelligence, compressing the gap between laboratory accuracy and field durability.
Microfabricated conductivity cells with integrated temperature compensation is digitizing quality control workflows in pharmaceutical water systems. Biologics manufacturers in Switzerland and Massachusetts deploy these chip-scale sensors directly within WFI (Water for Injection) distribution loops. The technology is digitizing validation documentation by eliminating manual grab-sample logging and enabling continuous electronic batch records.
REACH restrictions on hexavalent chromium surface treatments are forcing electrode manufacturers to migrate toward titanium-nitride coatings and alternative passivation chemistries. Industrial meter suppliers serving European chemical processors must recalibrate corrosion resistance specifications and revalidate long-term drift characteristics. Laboratory benchtop segments face the steepest compliance timeline pressure due to precision requirements.
Equipment-as-a-service contracting is displacing capital purchase models for online process conductivity systems. Water treatment OEMs in Germany now bundle sensor hardware, cloud analytics subscriptions, and predictive maintenance into per-cubic-meter processed water fees. Municipal utilities in the Rhine-Ruhr industrial corridor show strongest uptake where budget constraints favor operational expenditure structures over upfront instrument investment.
Electrical Conductivity Meters Market Segmentation
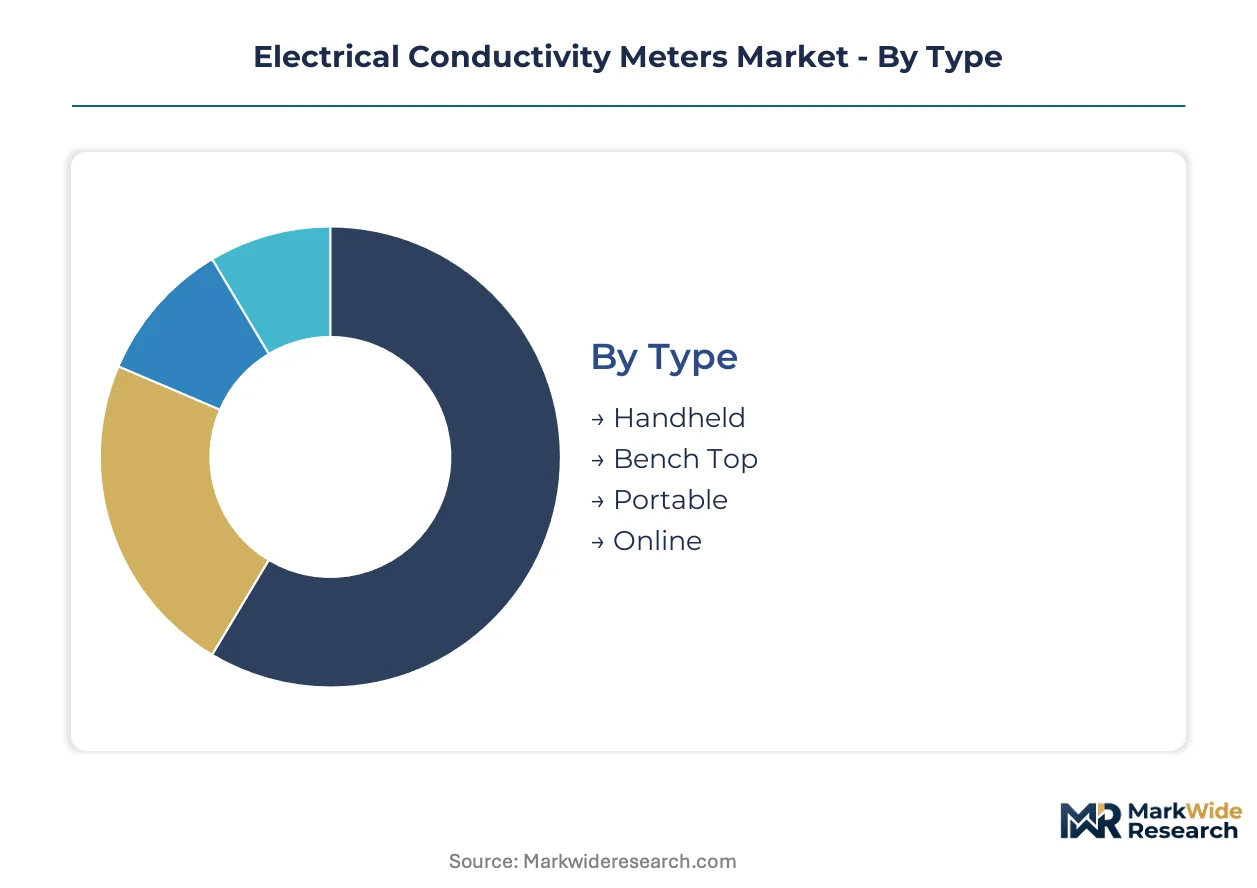
Electrical conductivity meters serve divergent operational contexts—from spot-checking irrigation water in remote agricultural zones to validating pharmaceutical-grade water systems under FDA scrutiny. Segmentation reveals how form factor, connectivity architecture, and regulatory intensity shape procurement priorities across end-use verticals.
Type:
Cost tier stratification separates field-deployable units from capital-intensive process instrumentation, with price points spanning two orders of magnitude from basic handhelds to validated online systems.
- Handheld:Compact battery-powered units with graphite or stainless steel electrodes suit rapid field screening. Environmental consultants in Germany deploy these for river basin surveys where mobility outweighs laboratory precision.
- Bench Top:Laboratory-grade four-electrode cells with temperature compensation and NIST-traceable calibration certificates. Pharmaceutical manufacturers in Massachusetts and Switzerland require these for FDA 21 CFR Part 11 compliant documentation.
- Portable:Ruggedized cases housing laboratory-equivalent accuracy for remote industrial sites. Mining operations in Western Australia favor these for tailings pond monitoring where dust and vibration tolerance matters.
- Online:Permanent installation transmitters with 4-20mA or digital outputs feeding SCADA integration. Municipal water treatment plants serving populations above 10,000 in the United States deploy these for continuous compliance reporting under EPA mandates.
Bench Top commands the established base in regulated laboratory environments. The steepest expansion runs through Online systems as utilities abandon periodic sampling for continuous process intelligence.
Technology:
Connectivity maturity defines competitive positioning, with legacy architectures defending installed base while smart platforms capture replacement cycles.
- Digital:Microprocessor-controlled measurement with LCD readouts and automatic temperature compensation. These units dominate municipal utility budgets where capital constraints delay wireless upgrades.
- Analog:Basic needle-display meters with manual range switching. Developing-world agricultural cooperatives in India still procure these for irrigation water testing where cost minimization overrides feature requirements.
- Wireless:Battery-powered nodes transmitting via LoRaWAN or cellular to cloud dashboards. Agricultural irrigation districts in California's Central Valley deploy these across thousands of acres previously unreachable by cabled infrastructure.
- Smart:Edge-computing sensors with predictive algorithms and remote diagnostics capability. Chemical processors in Japan integrate these with METI carbon neutrality roadmaps to optimize reverse osmosis energy efficiency.
Digital architectures retain the largest installed footprint. Smart platforms are climbing the fastest as facilities prioritize predictive maintenance over reactive calibration schedules.
End User:
Regulatory stringency concentration determines pricing power, with pharmaceutical validation requirements supporting 3-5x premiums over environmental screening applications.
- Environmental Testing:Field-deployable units for surface water, groundwater, and effluent monitoring. EPA enforcement of Safe Drinking Water Act mandates drives instrumentation upgrades across United States municipal utilities.
- Food & Beverage:Sanitary-design sensors with CIP/SIP compatibility for process water and ingredient verification. Breweries in Belgium and dairy processors in Wisconsin require these for HACCP documentation.
- Pharmaceuticals:Validated systems with audit trails, electronic signatures, and IQ/OQ/PQ documentation packages. Biologics manufacturers in Switzerland and Massachusetts deploy chip-scale sensors directly within WFI distribution loops.
- Aquaculture:Salinity and TDS monitoring for intensive shrimp and salmon farming operations. Coastal farming zones in Vietnam and Norway use these to optimize stocking densities and prevent osmotic stress mortality.
Environmental Testing commands the volume base through distributed regulatory monitoring networks. Pharmaceuticals delivers the steepest margin expansion through validation-intensive procurement requirements.
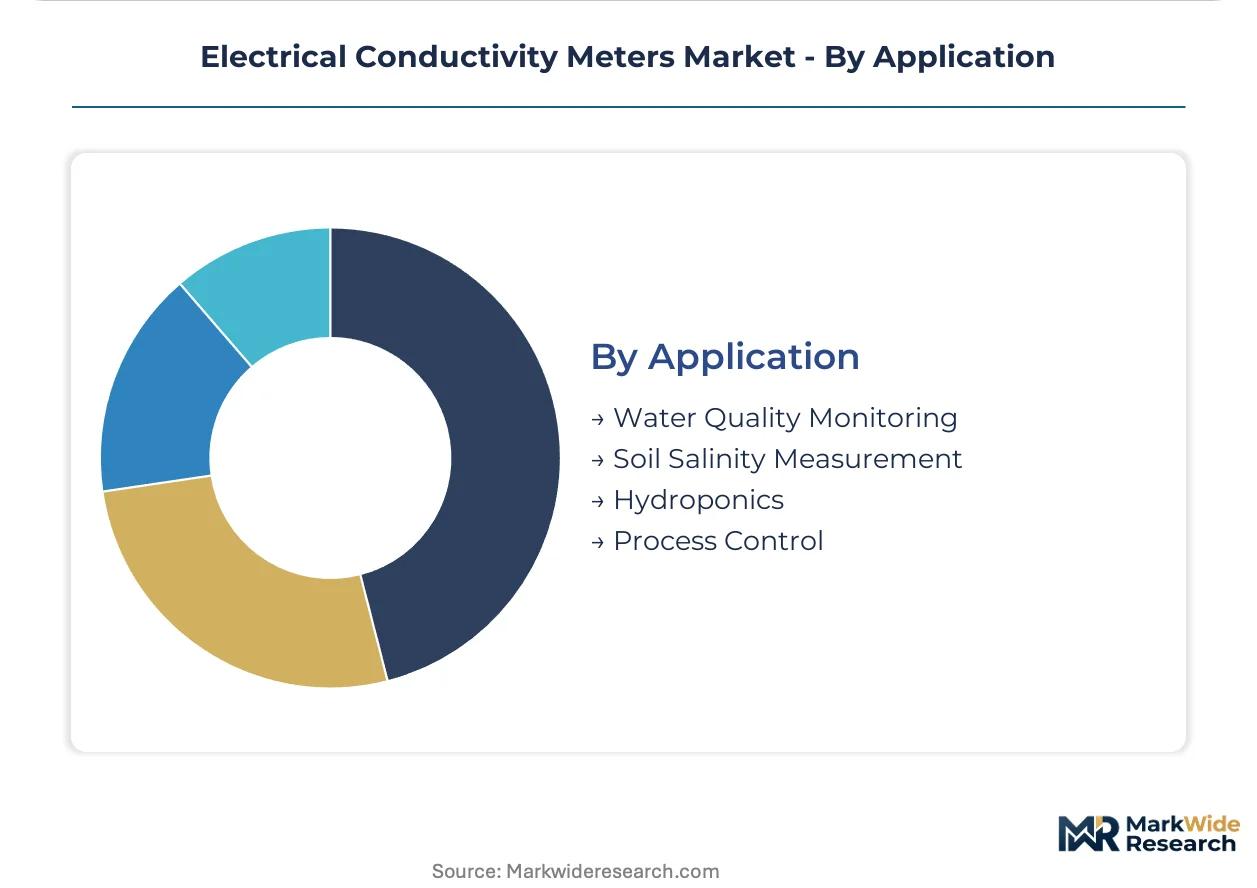
Application:
Process integration depth separates intermittent sampling applications from continuous control loops where conductivity measurement directly modulates chemical dosing or membrane operation.
- Water Quality Monitoring:Potable water, wastewater, and industrial effluent compliance testing. China's MEE surface water quality mandates and India's CPCB discharge rules expand deployment across Asia-Pacific industrial corridors.
- Soil Salinity Measurement:Agricultural extension services and precision farming operations assess irrigation sustainability. Australia's Murray-Darling Basin management authority distributes portable meters to monitor salinity intrusion.
- Hydroponics:Nutrient solution strength management in controlled-environment agriculture. Commercial greenhouse operators in the Netherlands deploy inline sensors to automate fertilizer recirculation.
- Process Control:Real-time conductivity feedback modulating chemical reactor operations or membrane separation efficiency. Japan's industrial water recycling targets drive high-precision meter deployment to minimize freshwater intake.
Water Quality Monitoring anchors the installed base through regulatory compliance mandates. Process Control applications are gaining share fastest as chemical processors embed conductivity intelligence into automated control architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented precision instrument manufacturers in Germany and Switzerland command premium positioning in cross-border trade, while import-dependent industrial clusters in India and Vietnam drive volume procurement of field-deployable units. The United States and Japan maintain balanced trade profiles with strong domestic production serving both local process industries and regional export markets.
United States
EPA Safe Drinking Water Act enforcement mandates continuous monitoring instrumentation across municipal utilities serving populations above ten thousand. The FDA Current Good Manufacturing Practice regulations for pharmaceutical water systems sustain demand for validated benchtop meters with audit trail documentation. Biologics manufacturers in Massachusetts deploy chip-scale sensors directly within Water for Injection distribution loops.
Germany
Industrial water recycling targets under the EU Green Deal drive demand for high-precision meters optimizing reverse osmosis system efficiency. REACH restrictions on hexavalent chromium surface treatments force electrode manufacturers toward titanium-nitride coatings. Water treatment OEMs in the Rhine-Ruhr industrial corridor bundle sensor hardware into equipment-as-a-service contracts with per-cubic-meter pricing.
Japan
METI carbon neutrality roadmaps prioritize industrial water recycling to minimize energy-intensive freshwater intake. The country's national environmental regulator mandates effluent discharge monitoring across chemical processing corridors. Process control specialists in the Chubu industrial zone integrate smart conductivity sensors with predictive maintenance algorithms.
India
CPCB zero liquid discharge mandates require portable validation meters for textile and tannery compliance documentation. The Bureau of Indian Standards calibration protocols shape procurement specifications for municipal water utilities. Industrial clusters in Tamil Nadu and Gujarat open field service revenue streams for ruggedized portable unit deployment.
China
MEE surface water quality monitoring mandates expand instrumentation deployment across Asia-Pacific industrial corridors. The country's national market regulator enforces GB standards for process control equipment certification. Yangtze River Delta chemical processors adopt inline conductivity sensors for continuous batch contamination prevention.
Electrical Conductivity Meters Market Competitive Landscape
On the supply side, the industry is consolidating around precision instrumentation conglomerates with captive sensor manufacturing capabilities and process automation integration expertise. Swiss and German industrial groups anchor the high-precision process control tier through vertical integration into conductivity cell production. Laboratory-grade specialists compete on validation documentation and regulatory compliance depth. The dominant competitive moves involve strategic partnerships with cloud analytics platforms and geographic expansion through equipment-as-a-service contracting models.
Within the precision process control tier, Endress+Hauser Group and Emerson Electric Co. exemplify the integrated manufacturing archetype. Thermo Fisher Scientific Inc. occupies a distinct position representing laboratory-grade benchtop specialists with deep R&D intensity. These three entities collectively illustrate the market's bifurcation between field-deployable process instrumentation and validated analytical systems.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Endress+Hauser Group |
| Thermo Fisher Scientific Inc. |
| Mettler-Toledo International Inc. |
| ABB Ltd. |
| Yokogawa Electric Corporation |
| Hach Company |
| JUMO |
| Baumer |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr industrial corridor anchors European conductivity cell manufacturing capacity, with captive electrode production in Swiss precision clusters feeding downstream pricing power to integrated instrument OEMs. Three German component suppliers control the majority of industrial-grade conductivity cell output, creating asymmetric bargaining positions that sustain premium pricing for validated laboratory systems while compressing margins for field-deployable units.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA 21 CFR Part 11 certification and NIST-traceable calibration driving four-electrode benchtop premiums. Price differentiation rests on validation documentation depth and geographic service density. Cost compression in handheld segments is intensifying because platinum electrode volatility and optical TDS substitution erode electrochemical share. Municipal utilities show highest price sensitivity due to capital budget constraints, while pharmaceutical manufacturers accept steep premiums for audit trail compliance.
Supply Chain Analysis
Export control regimes on precision sensor technology limit flows of microfabricated conductivity cells and noble metal electrode materials from German and Swiss manufacturing hubs. Production concentrates in Germany, Switzerland, and Japan, with raw material dependencies on South African platinum group metals, Chinese rare earth processing, and titanium-nitride coating precursors. Single-source sensor module concentration creates vulnerability to regional supply disruptions. Distribution runs through water treatment OEMs bundling hardware into equipment-as-a-service contracts and direct laboratory supply channels serving pharmaceutical validation workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates sticky demand—FDA and EPA compliance documentation generates switching costs that protect incumbent positions across replacement cycles.
For Market Incumbents: Harden certification moats by deepening captive conductivity cell production in Swiss manufacturing clusters to offset platinum cost volatility. Expand equipment-as-a-service contracting in German municipal utilities to lock out price-competitive challengers. Prioritize LoRaWAN-Modbus hybrid protocol development to defend against wireless-native entrants targeting agricultural irrigation white space. For New Entrants and Emerging Players: Establish a beachhead in India's CPCB-mandated textile and tannery compliance documentation segment, where portable validation meter demand outstrips established service infrastructure. Target Tamil Nadu and Gujarat industrial clusters with ruggedized portable units bundled with local calibration technician training. Pursue agricultural irrigation districts in California's Central Valley with battery-powered wireless nodes previously unreachable by cabled infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-utility play because EPA Safe Drinking Water Act enforcement and FDA pharmaceutical water system mandates create non-discretionary replacement demand insulated from cyclical capital spending. Acquisition targets should show captive sensor manufacturing and established IQ/OQ/PQ documentation capabilities. Watch for inflection when equipment-as-a-service contracting penetration in European water treatment exceeds half of new deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductivity Cell Production | Captive electrode manufacturing insulates margin stability from platinum group metal price volatility. |
| Equipment-as-a-Service Contracting | Per-cubic-meter pricing converts capital-constrained municipal utilities to recurring revenue streams. |
| LoRaWAN-Modbus Protocol Convergence | Hybrid wireless architectures unlock battery-powered monitoring at previously unreachable agricultural sites. |
| Microfabricated Sensor Miniaturization | Chip-scale conductivity cells enable direct WFI distribution loop deployment for continuous electronic batch records. |
| Titanium-Nitride Coating Migration | REACH-compliant electrode passivation maintains European market access while recalibrating corrosion resistance specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, FDA 483 inspection records, and ISO 7888 calibration protocol documentation. Conversations with plant engineers at municipal water treatment facilities, procurement leads at pharmaceutical OEMs, aftermarket service heads at industrial distributors, and technical R&D directors at sensor manufacturers informed demand-side assumptions. Trade flow analysis from customs records and SEC filings of listed instrumentation conglomerates provided supply-side validation. Bottom-up unit economics and top-down sectoral spending patterns were cross-referenced for triangulation.
Forecast inputs span technology adoption curves for smart sensor platforms, regulatory enforcement intensity across EPA and FDA jurisdictions, and replacement cycle compression from IoT-enabled predictive maintenance. Segmentation dimensions include form factor tier, connectivity architecture maturity, end-use regulatory stringency, and geographic enforcement cluster. CAGRs were derived from installed base aging analysis and capital expenditure pipeline tracking across water treatment and pharmaceutical verticals.
Sensitivities concentrate around platinum electrode cost volatility, optical TDS substitution rates in food processing effluent monitoring, and cybersecurity investment requirements for wireless smart infrastructure. Forecasts reflect assumptions about continued EPA Safe Drinking Water Act enforcement and FDA Current Good Manufacturing Practice audit trail expansion. Material shifts in REACH coating chemistry timelines or German component supplier concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Compression Testers Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market