
 Cable Market | 2026-2036
Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Market Analysis
India's expanding manufacturing footprint is reshaping regional supply dynamics for medium-voltage power cables. Prysmian Group leverages integrated compound-to-cable production across European and Asian facilities to sustain margin control. Nexans anchors its position through deep specialization in subsea and offshore wind interconnection systems. Fujikura Ltd. competes aggressively in optical fiber preform and ribbon cable technology for data center backbones.
A cable is an assembly of one or more insulated conductors encased in protective sheathing, typically rated by voltage class, conductor material purity, and jacket compound flame-resistance properties, designed to transmit electrical power or electromagnetic signals across fixed or dynamic installations. Fiber optic cables, constructed from doped silica glass cores with cladding indices engineered for total internal reflection, now dominate long-haul telecommunications and hyperscale data center interconnects due to bandwidth-density advantages over copper. Twisted pair cables retain structural importance in commercial building automation and industrial Ethernet where cost and electromagnetic compatibility requirements balance performance needs. Coaxial cables occupy narrowing but durable niches in broadband last-mile distribution and specialized broadcasting infrastructure.
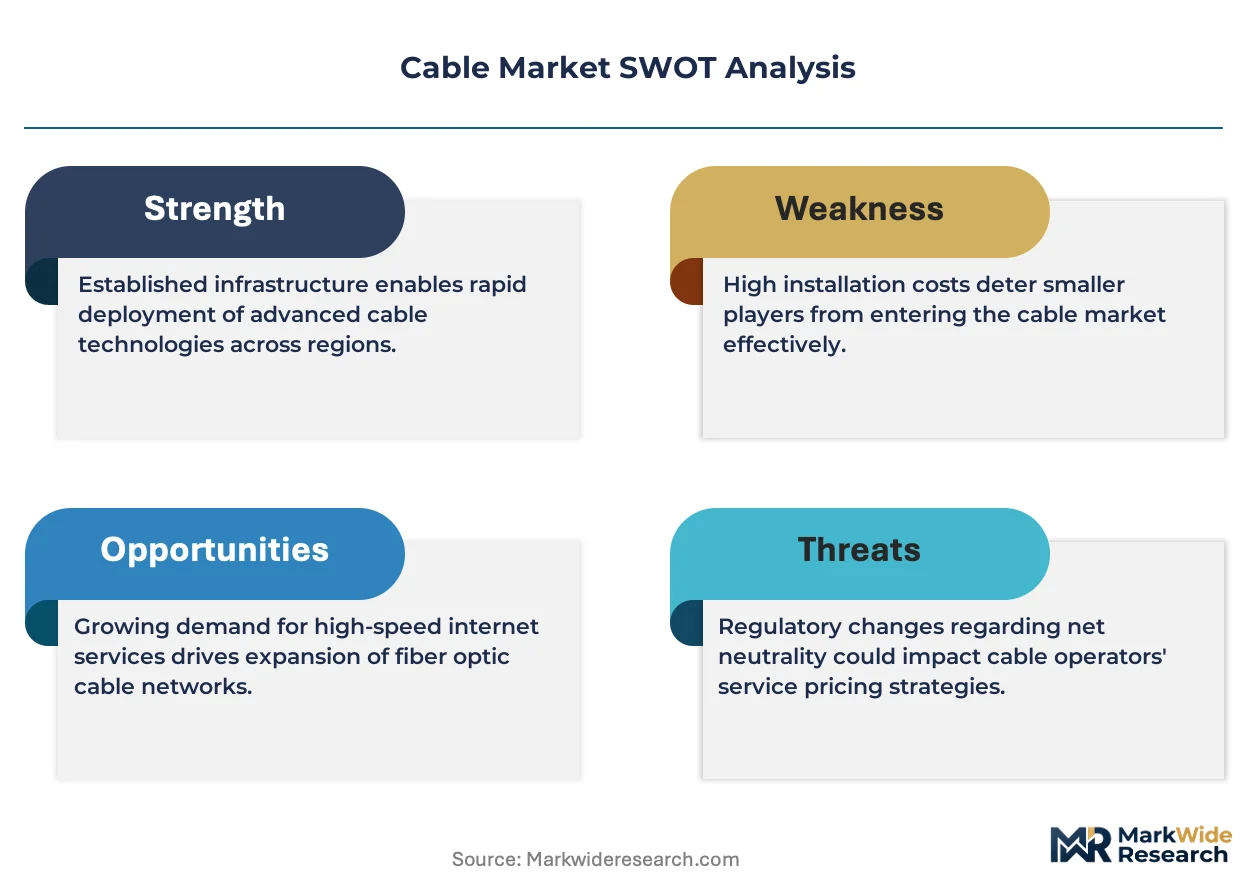
FCC broadband deployment mandates in the United States, EU Green Deal circular-economy requirements under ECHA REACH frameworks, and India's BIS certification standards for fire-resistant cables collectively elevate compliance costs while filtering substandard imports. China's GB standards for halogen-free low-smoke compounds and MEE environmental enforcement push formulation changes across Asian supply chains. Stakeholders must monitor how divergent national fire-safety and recyclability regimes fragment product platforms and force regional manufacturing localization decisions.
Market Dynamics
Hyperscale data center buildouts by cloud operators are compressing procurement timelines for fiber optic cable while simultaneously fragmenting product specifications across regional fire-safety regimes.
Growth Catalysts
- Hyperscale data center interconnects:Cloud operators in the United States and Germany are accelerating fiber optic cable orders for backbone infrastructure. This demand concentrates procurement power among a handful of buyers with custom performance requirements.
- FCC broadband deployment mandates:Universal service obligations in the United States are extending fiber-to-the-home networks into previously underserved census blocks. Rural electrification cooperatives are emerging as unexpected volume purchasers.
- China's dual carbon goals:MEE emissions enforcement is forcing manufacturers to reformulate jacket compounds toward halogen-free low-smoke materials. GB standard compliance is becoming a de facto export requirement across Asian supply chains.
Market Restraints
- Copper price volatility:Conductor material cost swings are compressing margin predictability for medium-voltage power cable producers. Hedging costs now represent a material line item in procurement budgets.
- Optical fiber preform supply concentration:Manufacturing of the doped silica glass precursor remains concentrated among a limited set of specialized chemical vapor deposition facilities. Bottlenecks in preform output constrain downstream ribbon cable capacity.
- Legacy coaxial infrastructure depreciation:Existing broadband last-mile networks are creating sunk-cost resistance to fiber replacement. Cable operators face stranded asset risk as subscriber preferences shift.
Strategic Opportunities
- India's grid modernization:State electricity boards are issuing high-voltage cable tenders for transmission network upgrades. Domestic manufacturing localization requirements under Make in India are creating captive demand for local compound production.
- EU Green Deal circular-economy mandates:ECHA REACH frameworks are elevating recyclability specifications for jacket materials. First-movers in closed-loop compound recovery are securing preferred supplier status with European utilities.
- Subsea wind farm interconnection:Offshore renewable projects are creating demand for specialized submarine power cables with enhanced mechanical protection. Installation vessel scarcity is extending contract visibility for qualified manufacturers.
Industry Challenges
- Halogen-free compound formulation expertise:The shift from conventional PVC jacketing to low-smoke zero-halogen materials requires polymer science capabilities concentrated among a limited talent pool. Training timelines are extending product development cycles.
- Multi-jurisdiction certification complexity:Simultaneous BIS, GB, and REACH compliance is forcing parallel testing protocols. Certification lag is delaying product launches in fast-tendering markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Market |
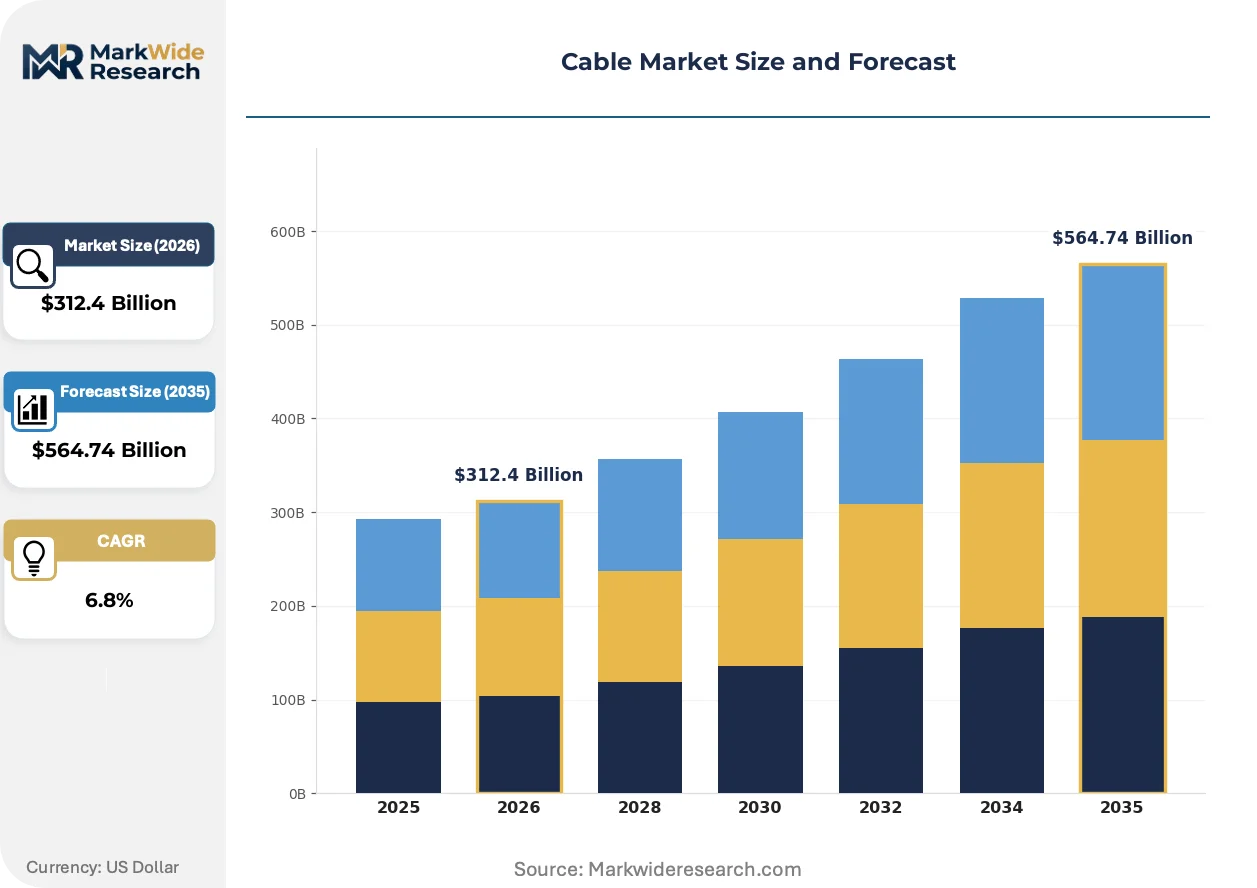
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial Cables, Fiber Optic Cables, Twisted Pair Cables, HDMI Cables Installation Type: Indoor, Outdoor, Aerial, Underground End User: Telecommunications, Broadcasting, Industrial, Commercial Material: Copper, Aluminum, Fiber, PVC |
| Companies Covered | Prysmian Group, Nexans, Southwire Company, Belden Inc., Fujikura Ltd., Furukawa Electric Co., Ltd., Sumitomo Electric Industries, Ltd., Leoni AG, KEI Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Market Emerging Trajectories
Ribbon fiber architectures and environmentally driven material substitutions are restructuring competitive advantage around bandwidth density and compound chemistry capabilities rather than traditional conductor metallurgy.
Multifiber push-on connector systems are collapsing installation labor requirements for hyperscale data center fiber deployments. Cloud operators are specifying pre-terminated ribbon cable assemblies to compress deployment schedules. This technology is collapsing the traditional advantage of field-splicing contractors and shifting value capture toward factory-terminated cable suppliers.
EU Green Deal circular-economy requirements under ECHA REACH are mandating recyclability disclosures for cable jacket compounds. Manufacturers are reformulating halogen-free materials to satisfy mechanical performance thresholds while enabling material recovery. European utilities are now specifying end-of-life take-back provisions in procurement frameworks, favoring suppliers with integrated compound-to-cable-to-recycling capabilities.
Buyer concentration among hyperscale cloud operators is compressing negotiation cycles and unbundling after-sales service from hardware supply. Procurement teams are demanding fixed-price multi-year frameworks with volume flexibility clauses. This pattern is most visible in United States and Germany data center clusters, where three buyers represent a disproportionate share of fiber backbone demand.
Cable Market Segmentation
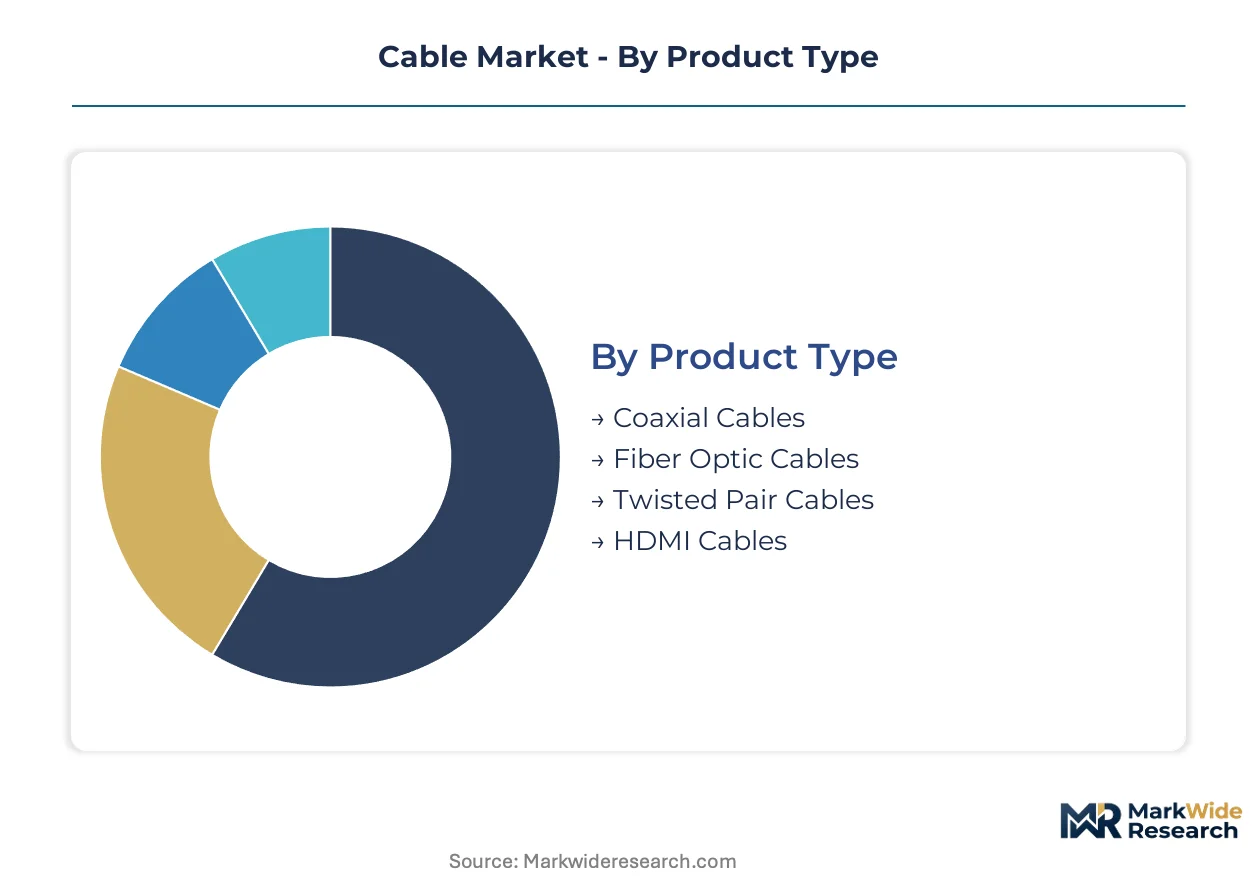
Cable procurement cycles vary dramatically across installation environments and end-use applications. Understanding these velocity differences helps suppliers align inventory strategies with actual consumption patterns rather than aggregate demand signals.
Product Type:
Replacement cycles stretch from months for consumer-grade patch cords to decades for buried power transmission infrastructure.
- Fiber Optic Cables:Doped silica glass cores with engineered cladding indices enable total internal reflection for bandwidth-intensive applications. Hyperscale data center operators in the United States and Germany are compressing procurement timelines for backbone interconnects while demanding custom fire-safety specifications.
- Coaxial Cables:Central conductor, dielectric insulator, and shielding layers maintain signal integrity across radio frequency applications. Legacy broadband last-mile networks in North America create sunk-cost resistance to fiber replacement, narrowing growth to specialized broadcasting niches.
- Twisted Pair Cables:Paired copper conductors with controlled twist rates balance electromagnetic compatibility against cost in commercial building automation.
- HDMI Cables:Shielded copper bundles with standardized connector geometries serve consumer electronics and professional AV installations with rapid obsolescence cycles.
Fiber optic cables anchor the volume base while HDMI cables gain share at the steepest rate due to consumer electronics refresh cycles.
Installation Type:
Underground and aerial deployments command premium pricing tiers driven by mechanical protection requirements and installation labor intensity.
- Underground:Armored sheathing and moisture barriers protect conductors from soil chemistry and mechanical stress across decades-long service lives. India's state electricity boards are issuing high-voltage tenders for transmission network upgrades requiring direct-burial ratings.
- Indoor:Plenum-rated and riser-rated jacket compounds address building code fire-safety requirements without heavy mechanical armoring. FCC broadband mandates are extending fiber-to-the-home networks into previously underserved census blocks with indoor termination complexity.
- Outdoor:UV-stabilized jacketing and temperature-extreme formulations serve utility-scale solar farms and wind turbine interconnections.
- Aerial:Self-supporting messenger wires and ice-loading specifications address utility pole attachment standards with specialized hardware requirements.
Indoor installations dominate current shipment volumes while underground segments expand most quickly on grid modernization investments.
End User:
Telecommunications buyers concentrate procurement power through multi-year framework agreements with volume flexibility clauses.
- Telecommunications:Backbone fiber and last-mile copper networks demand carrier-grade reliability certifications with mean-time-between-failure specifications. Cloud operators are unbundling after-sales service from hardware supply and demanding fixed-price multi-year frameworks.
- Industrial:Oil-resistant, flex-rated, and temperature-extreme cable configurations serve factory automation and process control with specialized connector ecosystems.
- Broadcasting:Coaxial and fiber infrastructure for content distribution maintains narrow but durable demand as IP-based workflows displace legacy formats.
- Commercial:Building automation, security systems, and structured cabling for office environments balance performance against installed cost constraints.
Telecommunications anchors the volume base while Industrial gains share at the steepest rate on manufacturing automation investments.
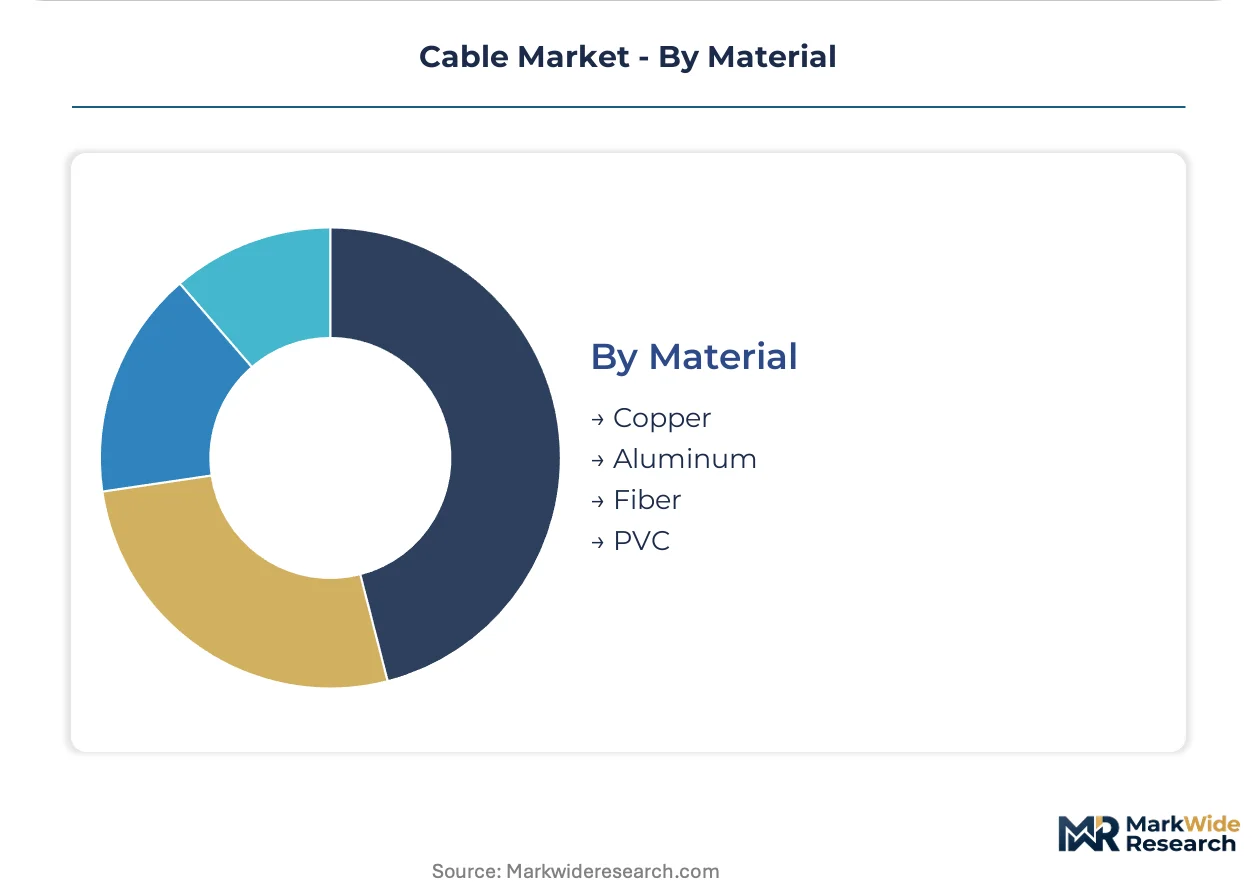
Material:
Raw material selection directly determines conductivity performance, fire-safety characteristics, and end-of-life recyclability under emerging circular-economy mandates.
- Copper:High-purity electrolytic tough pitch and oxygen-free grades deliver superior electrical conductivity for power transmission and signal integrity applications. Price volatility is compressing margin predictability for medium-voltage cable producers as hedging costs represent material budget line items.
- Fiber:Doped silica glass preforms manufactured through chemical vapor deposition enable bandwidth-density advantages with minimal signal attenuation. Preform supply concentration among limited specialized facilities constrains downstream ribbon cable capacity.
- Aluminum:Lower density and cost trade off against higher resistivity in aerial and long-span power distribution where weight matters.
- PVC:Conventional jacketing faces displacement by halogen-free low-smoke compounds under China's MEE emissions enforcement and EU REACH frameworks.
Copper anchors the volume base while Fiber climbs the fastest on data center interconnect demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized compound-to-cable manufacturing clusters concentrate in Germany, China, and the United States, with each hub serving distinct regulatory and demand environments. Geographic proximity to end-use sectors now determines competitive positioning more than raw material access.
United States
FCC broadband deployment mandates and hyperscale data center buildouts in Northern Virginia and Dallas-Fort Worth are accelerating fiber optic procurement. The FCC's universal service obligations extend fiber-to-the-home networks into rural census blocks. Rural electrification cooperatives in the Midwest and Southeast are emerging as unexpected volume purchasers of medium-voltage power cables.
Germany
Offshore wind farm interconnection projects in the North Sea and Baltic Sea are driving submarine power cable demand. ECHA REACH frameworks and EU Green Deal circular-economy mandates elevate recyclability specifications for jacket materials. The Ruhr industrial corridor hosts integrated compound-to-cable facilities serving European utility tenders.
China
Dual carbon goals and tightening MEE emissions standards are forcing manufacturers toward halogen-free low-smoke compounds under GB standards. Yangtze River Delta manufacturing clusters supply both domestic grid modernization and export markets. Preform supply concentration in specialized chemical vapor deposition facilities constrains downstream ribbon cable capacity expansion.
India
State electricity boards are issuing high-voltage cable tenders for transmission network upgrades under grid modernization programs. BIS certification standards for fire-resistant cables filter substandard imports while Make in India policies create captive demand for domestic compound production. Manufacturing localization concentrates in Gujarat and Maharashtra industrial corridors.
Japan
METI industrial policy supports advanced optical fiber preform development for data center interconnect applications. JIS standards govern product quality in telecommunications and industrial automation segments. Kanto and Kansai manufacturing belts maintain specialized capabilities in high-purity silica glass processing.
Cable Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The cable market structures around three tiers: integrated compound-to-cable producers, specialized fiber or subsea manufacturers, and regional fabricators serving utility tenders. Strategic differentiation follows vertical integration depth and certification breadth across multi-jurisdiction regimes. Dominant competitive moves include backward integration into compound production and geographic expansion to satisfy local content requirements.
Among European-anchored conglomerates, Prysmian Group and Nexans occupy positions exemplifying integrated production capabilities spanning power and telecommunications segments. Japanese manufacturers Fujikura Ltd. and Furukawa Electric Co., Ltd. represent specialized optical fiber and preform expertise. These archetypes illustrate how compound chemistry capabilities and bandwidth-density engineering now determine competitive positioning more than traditional conductor metallurgy scale.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Belden Inc. |
| Fujikura Ltd. |
| Furukawa Electric Co., Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Leoni AG |
| KEI Industries |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta optical fiber preform facilities is compressing margin buffers while simultaneously extending payment terms for downstream ribbon cable converters. This utilization squeeze forces suppliers to absorb copper price volatility through hedging instruments rather than pass-through mechanisms, restructuring buyer-supplier power dynamics across medium-voltage power cable tenders.
Pricing Analysis
ECHA REACH circular-economy mandates dictate the pricing tier structure across European utility procurement frameworks. Three-tier pricing stratifies across premium halogen-free compound grades, standard PVC-jacketed products, and economy-tier aluminum conductor configurations. Price differentiation hinges on GB standard compliance for Chinese export eligibility and BIS fire-resistance certification for Indian grid tenders. Pricing pressure stems from hyperscale cloud operators demanding fixed-price multi-year frameworks with volume flexibility clauses. Rural electrification cooperatives exhibit highest price sensitivity, while subsea wind farm developers prioritize mechanical protection specifications over unit cost.
Supply Chain Analysis
Extended payment terms now stretch to 180 days for compound suppliers serving European cable integrators, with supply-chain finance facilities bridging working capital gaps. Manufacturing concentrates in China, Germany, and the United States, with each hub captive to distinct regulatory clusters. Raw material dependencies center on high-purity copper cathodes, doped silica glass preforms, and halogen-free polymer formulations. Single-source vulnerability in chemical vapor deposition preform facilities constrains downstream ribbon cable expansion. Distribution runs through direct utility tender channels for power transmission cables and hyperscale procurement teams for data center interconnects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable market is approaching a platform-economics inflection as hyperscale cloud operators unbundle hardware supply from after-sales service, creating interoperability standards that favor factory-terminated assembly suppliers over field-splicing contractors.
For Market Incumbents: Build certification moats across BIS, GB, and REACH compliance regimes to filter substandard imports and capture Indian grid modernization tenders. Prysmian Group and Nexans demonstrate how integrated compound-to-cable production sustains margin control against copper price volatility. Incumbents should anchor capacity in Gujarat and Maharashtra industrial corridors to satisfy Make in India localization mandates. For New Entrants and Emerging Players: Mid-market commercial building automation in Southeast Asia represents the most penetrable entry point, where twisted pair Ethernet cables face less hyperscale buyer concentration than data center backbones. Subsea wind farm installation vessel scarcity extends contract visibility for qualified manufacturers willing to invest in mechanical protection engineering. New entrants should pursue direct partnerships with European utilities specifying end-of-life take-back provisions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across halogen-free compound formulation capabilities as polymer science talent scarcity extends product development timelines. Long-term viability favors acquisition targets with captive preform supply or integrated recycling infrastructure rather than pure-play fabricators. Watch hyperscale cloud operator procurement consolidation as the inflection signal—three buyers now disproportionately influence fiber backbone pricing frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Production | Captive halogen-free formulation supply secures margin control under MEE emissions enforcement. |
| Submarine Cable Capacity Expansion | Installation vessel scarcity extends contract visibility for North Sea and Baltic Sea interconnection projects. |
| Closed-Loop Recycling Infrastructure | ECHA REACH take-back provisions favor suppliers with integrated cable-to-compound recovery capabilities. |
| Pre-Terminated Ribbon Cable Assembly Scale-Up | Hyperscale cloud operators in Northern Virginia specify factory-terminated systems to compress deployment schedules. |
| Multi-Jurisdiction Certification Investment | Parallel BIS, GB, and REACH testing protocols reduce tender response lag in fast-cycling markets. |
Methodological Framework
Operator-level perspectives from utility procurement managers, hyperscale cloud operator infrastructure leads, compound formulation chemists, and subsea installation contractors anchored the qualitative base. Primary interviews triangulated against customs trade data, SEC filings from publicly traded cable manufacturers, ECHA REACH substance registration databases, and BIS certification records. Bottom-up demand modeling across installation types and end-use segments converged with top-down macroeconomic overlays to establish volume and value estimates.
Scenario-bracketing framed the analytical approach, with sensitivity testing across copper price volatility bands and preform supply constraint assumptions. Segmentation dimensions modeled include product type, installation environment, end-use sector, conductor material, and regional regulatory cluster. CAGRs derived from trend extrapolation of hyperscale data center capex disclosures, FCC broadband deployment timelines, and Indian state electricity board tender pipelines. Industry-specific forecast inputs incorporated MEE emissions enforcement trajectories and EU Green Deal circular-economy implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in copper commodity prices, cloud operator capex cycles, or offshore wind auction volumes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Management Accessories Market
Cables
Military Fiber Optic Cables Market
Cables
Flexible Cables Market
Cables
EPR Cable Market
Cables
Global Ethernet Cable Market
Cables
Polyurethane Cable Market
Cables
Class 1E Electric Cables Market
Cables
High-Temperature Superconducting Cables Market
Cables
Electric Submersible Cable Sales Market
Cables
EDM Wires Market
Cables
Wire and Cable Materials Market
Cables
Cable Tray Market
Cables
Cable Detector Market
Cables
Cable Fault Locator Market
Cables
Anti-Static Space Wires Market
Cables
UK Cables Market