
 Underwater Connectors Market | 2026-2036
Underwater Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Connectors Market Analysis
Offshore renewable energy developers is redrawing procurement priorities across the underwater connectors landscape. Teledyne Marine leverages its integrated sonar and connector portfolio to dominate deep-water installation contracts. Amphenol Corporation anchors North American supply through MIL-SPEC-qualified manufacturing lines for defense and energy clients. TE Connectivity competes on high-density fiber-optic penetrator assemblies rated for 6,000-meter depths.
Underwater connectors are sealed electromechanical interfaces engineered to maintain signal and power integrity across pressure differentials exceeding 600 bar, typically employing titanium housings, fluoropolymer insulation, and glass-to-metal hermetic seals for permanent subsea deployments. Wet-mate connectors lead product-type revenue due to their indispensable role in live-connection subsea operations without dry-docking, while hybrid optical-electrical variants represent the fastest-growing technology segment as bandwidth demands from seabed observation networks intensify. Offshore oil and gas applications remain the most mature demand pool, though marine research and underwater robotics segments are capturing disproportionate investment flows from government science agencies.
ISO 13628-15 subsea production system standards, DNV-ST-F203 flexible riser and cable integrity rules, and the EU Marine Equipment Directive collectively dictate connector qualification protocols, pressure-testing regimes, and material traceability requirements for market access. The US Navy's MIL-STD-810 environmental engineering guidelines and FAA-equivalent pressure-vessel certifications further segment defense-aerospace crossover demand. Stakeholders must monitor evolving seabed mining regulatory frameworks and corresponding equipment reliability specifications as new extraction zones receive exploration licenses.
Market Dynamics
The EU Marine Strategy Framework Directive is tightening subsea equipment reliability standards, forcing connector manufacturers to redesign qualification protocols and pressure-testing regimes for permanent deployments exceeding 600 bar differentials.
Growth Catalysts
- Offshore wind procurement:North Sea developers are scaling wet-mate connector assemblies for turbine inter-array cabling as capacity additions accelerate across Norwegian, UK, and Danish territorial waters.
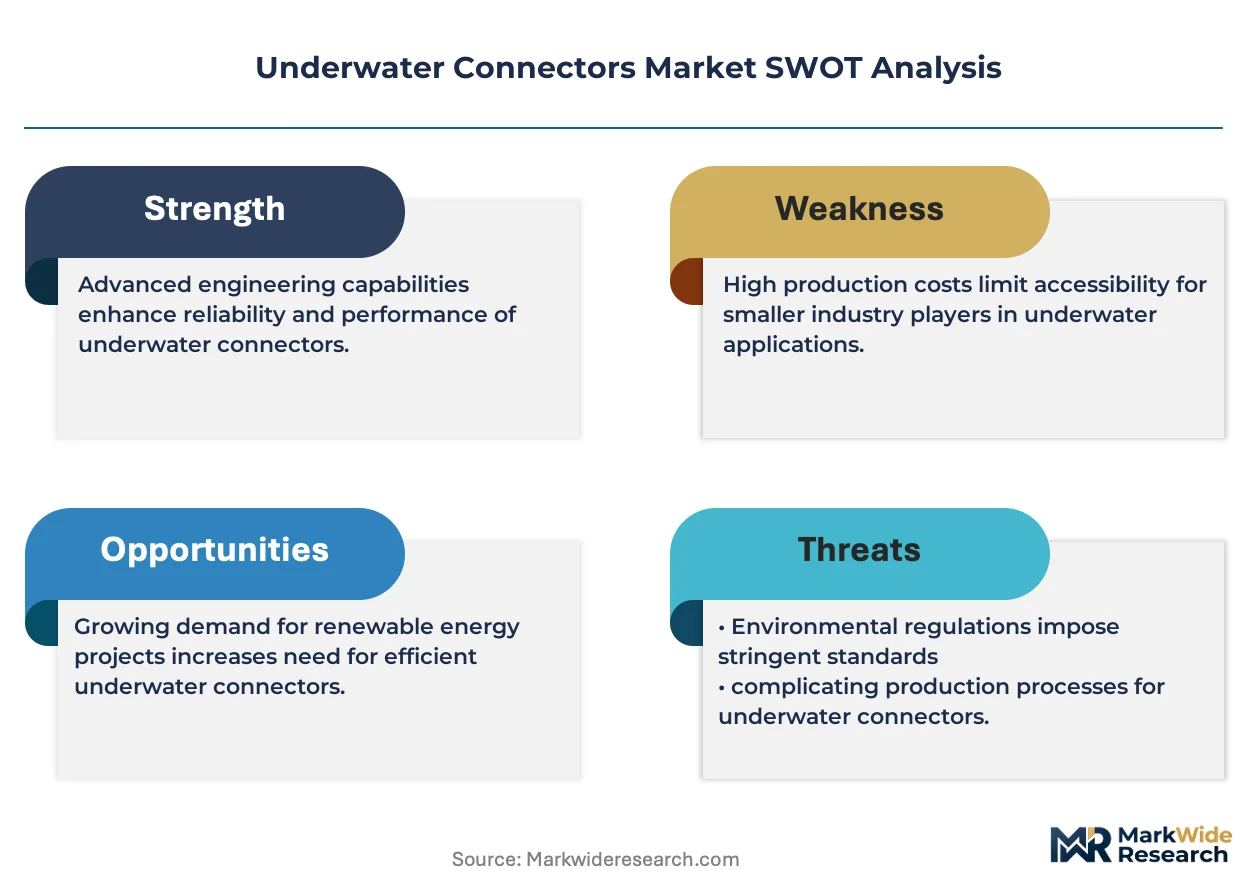
- ISO 13628-15 compliance:Subsea production system standards are mandating glass-to-metal hermetic seals and titanium housing traceability, expanding addressable market for qualified suppliers.
- Seabed observation networks:Government science agencies are channeling disproportionate investment flows into hybrid optical-electrical penetrator assemblies rated for extreme depth operations.
Market Restraints
- Fluoropolymer input volatility:Specialized insulation material supply concentrates among Japanese and European chemical producers, exposing connector manufacturers to price swings and allocation constraints.
- DNV-ST-F203 certification friction:Flexible riser and cable integrity rules impose multi-year qualification timelines that delay product commercialization and lock out unproven entrants.
- Dry-mate substitution in shallow water:Lower-cost mechanical sealing solutions are capturing maintenance-intensive applications above 200-meter depths, compressing addressable volume for premium wet-mate designs.
Strategic Opportunities
- India coastal infrastructure:The country's national maritime regulator is drafting subsea equipment standards for port modernization and undersea cable protection zones, creating first-mover positioning for qualified suppliers.
- Optical-electrical convergence:Fiber-optic penetrator assemblies are merging with power transmission interfaces to serve bandwidth-intensive seabed mining exploration systems awaiting licensing frameworks.
- US Navy MIL-STD-810 crossover:Defense-aerospace environmental engineering guidelines are opening dual-use qualification pathways for connector vendors with pressure-vessel certifications.
Industry Challenges
- Hermetic sealing expertise scarcity:Glass-to-metal seal engineering talent concentrates among legacy aerospace and nuclear suppliers, constraining production scale-up for qualified connector manufacturers.
- Legacy system integration complexity:Subsea oil and gas operators are demanding backward-compatible interfaces with decades-old ROV docking systems, fragmenting R&D resources across obsolete and next-generation form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Connectors Market |
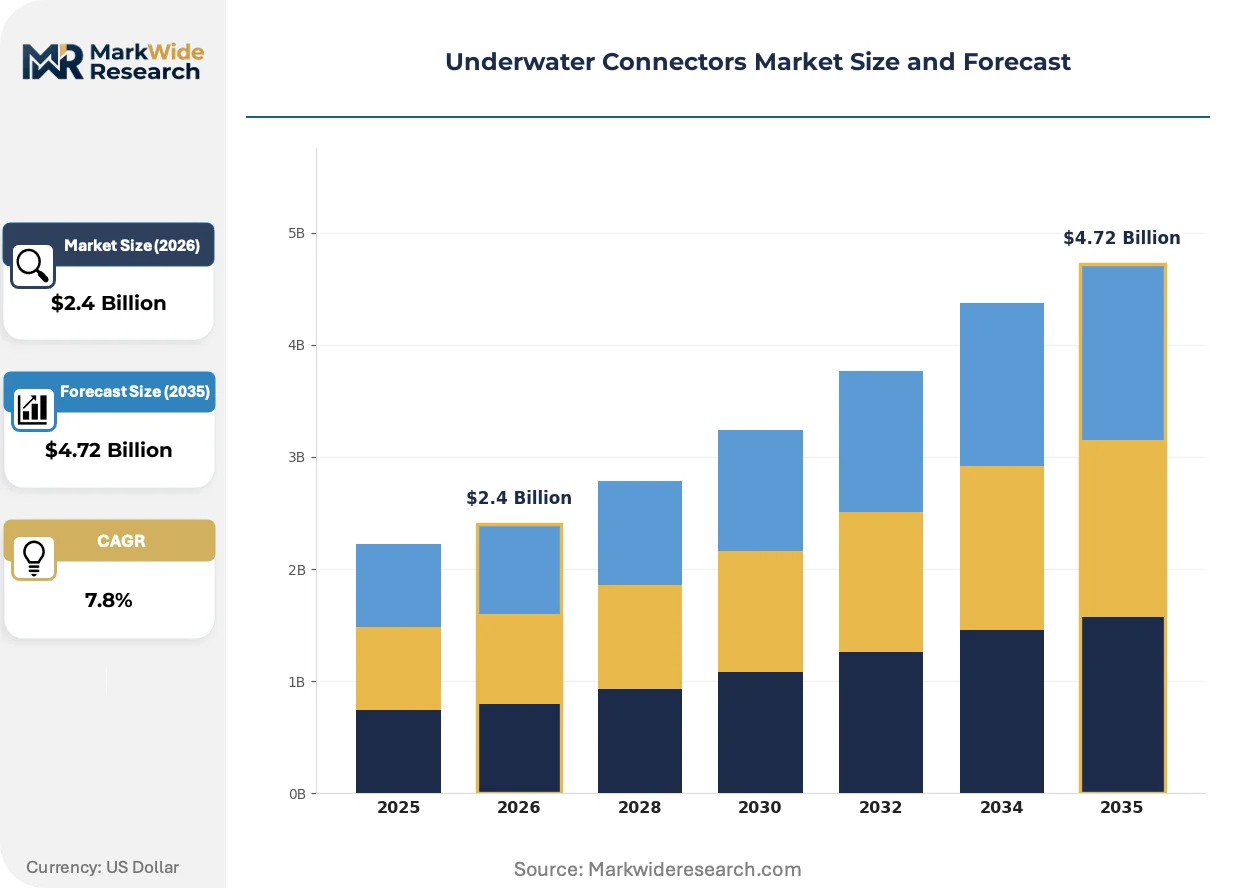
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry-Mate Connectors, Wet-Mate Connectors, Hybrid Connectors, Specialty Connectors Technology: Optical, Electrical, Electromechanical, RF, Hybrid Application: Subsea Exploration, Underwater Robotics, Marine Research, Offshore Oil & Gas End User: Marine Industry, Telecommunications, Defense, Renewable Energy |
| Companies Covered | Teledyne Marine, Fischer Connectors SA, Amphenol Corporation, Hydro Group, BIRNS Inc., TE Connectivity, Molex, Glenair Inc., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Connectors Market Emerging Trajectories
Deep-water installation contractors are reconfiguring technical specifications around integrated sensor-connector packages, compressing procurement cycles and elevating performance thresholds for pressure-rated electromechanical interfaces.
Titanium alloy housing fabrication is fragmenting as additive manufacturing processes displace conventional machining for complex internal channel geometries. Offshore wind farm developers in the North Sea basin are qualifying these additively produced connectors for turbine inter-array cabling at accelerated timelines. The technology is fragmenting supplier bases by enabling mid-tier manufacturers to bypass capital-intensive five-axis machining centers.
REACH substance restrictions are phasing out legacy fluoropolymer formulations in EU territorial waters, compelling reformulation of insulation compounds for subsea connectors deployed in North Sea oil and gas fields. Connector manufacturers are submitting pre-registration dossiers to ECHA for alternative perfluorinated materials ahead of sunset date enforcement. Marine research institutions are delaying procurement decisions pending compliance verification, compressing near-term order visibility for European suppliers.
Buyer concentration among integrated offshore contractors is consolidating specification authority away from equipment OEMs, shifting technical negotiation leverage toward EPC firms with direct vessel ownership. Wet-mate connector vendors are establishing dedicated engineering liaison teams at contractor headquarters in Aberdeen and Stavanger to secure design-in positioning. The restructuring is most visible in Norwegian sector awards, where framework agreements now span decade-long service commitments bundling installation, maintenance, and connector replacement liability.
Underwater Connectors Market Segmentation
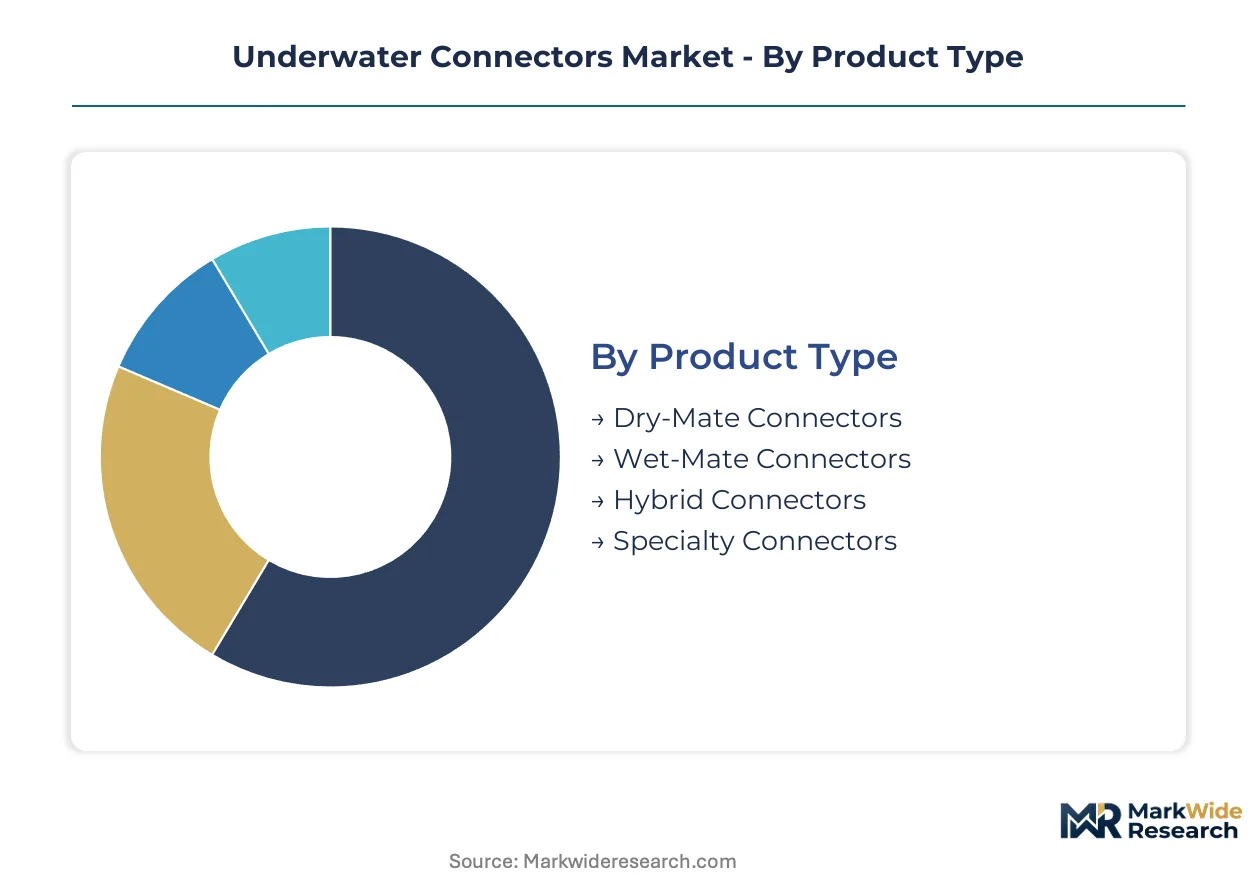
Underwater connector procurement splits across pressure-rated performance tiers, each facing distinct substitution threats from alternative sealing technologies. Technical specification divergence between permanent seabed installations and retrievable systems fragments supplier qualification requirements.
Product Type:
Dry-mate mechanical seals exert substitution pressure on premium wet-mate designs in shallow-water maintenance cycles, reshaping volume distribution across depth-rated categories.
- Wet-Mate Connectors:Titanium-housed electromechanical interfaces enable live-connection operations without vessel dry-docking. North Sea offshore wind developers are scaling procurement for turbine inter-array cabling as capacity additions accelerate across Norwegian, UK, and Danish territorial waters.
- Hybrid Connectors:Converged optical-electrical penetrator assemblies merge fiber-optic data transmission with power delivery in single pressure-rated housings. Government science agencies are channeling disproportionate investment into bandwidth-intensive seabed observation networks.
- Dry-Mate Connectors:Lower-cost mechanical sealing solutions capture maintenance-intensive applications above 200-meter depths.
- Specialty Connectors:Custom-engineered interfaces for extreme environment ROV docking systems.
Wet-Mate Connectors retain volume leadership; Hybrid Connectors hold the steepest expansion curve.
Technology:
Material science advancement is fragmenting technology trajectories, with optical fiber displacement of copper conductors accelerating in bandwidth-constrained deployments.
- Hybrid:Integrated optical-electrical architectures eliminate separate penetrator stacks, reducing footprint on crowded subsea production trees. TE Connectivity and Amphenol Corporation are competing on high-density assemblies rated for 6,000-meter depths.
- Optical:Pure fiber-optic penetrators deliver terabit-scale data rates for seabed sensor networks. Marine research institutions are delaying procurement decisions pending REACH compliance verification for alternative fluoropolymer formulations.
- Electromechanical:Combined signal-power interfaces dominate legacy oil and gas retrofit markets.
- Electrical:Copper-conductor designs face displacement pressure in bandwidth-intensive applications.
- RF:Radio-frequency connectors serve specialized underwater telemetry and acoustic positioning systems.
Electromechanical technology anchors installed base maintenance; Hybrid architectures are climbing the fastest.
Application:
Capital allocation shifts from hydrocarbon extraction toward renewable infrastructure are reordering application-level demand concentration.
- Offshore Oil & Gas:Mature demand pool requiring backward-compatible interfaces with decades-old ROV docking systems. DNV-ST-F203 certification rules impose multi-year qualification timelines that fragment R&D resources.
- Marine Research:Government science agencies are deploying hybrid optical-electrical penetrators for extreme-depth observation networks. ECHA pre-registration dossiers for alternative perfluorinated materials are compressing near-term order visibility.
- Subsea Exploration:Seabed mining exploration systems awaiting licensing frameworks.
- Underwater Robotics:Autonomous and remotely operated vehicle proliferation.
Offshore Oil & Gas retains revenue concentration; Marine Research is gaining share fastest.
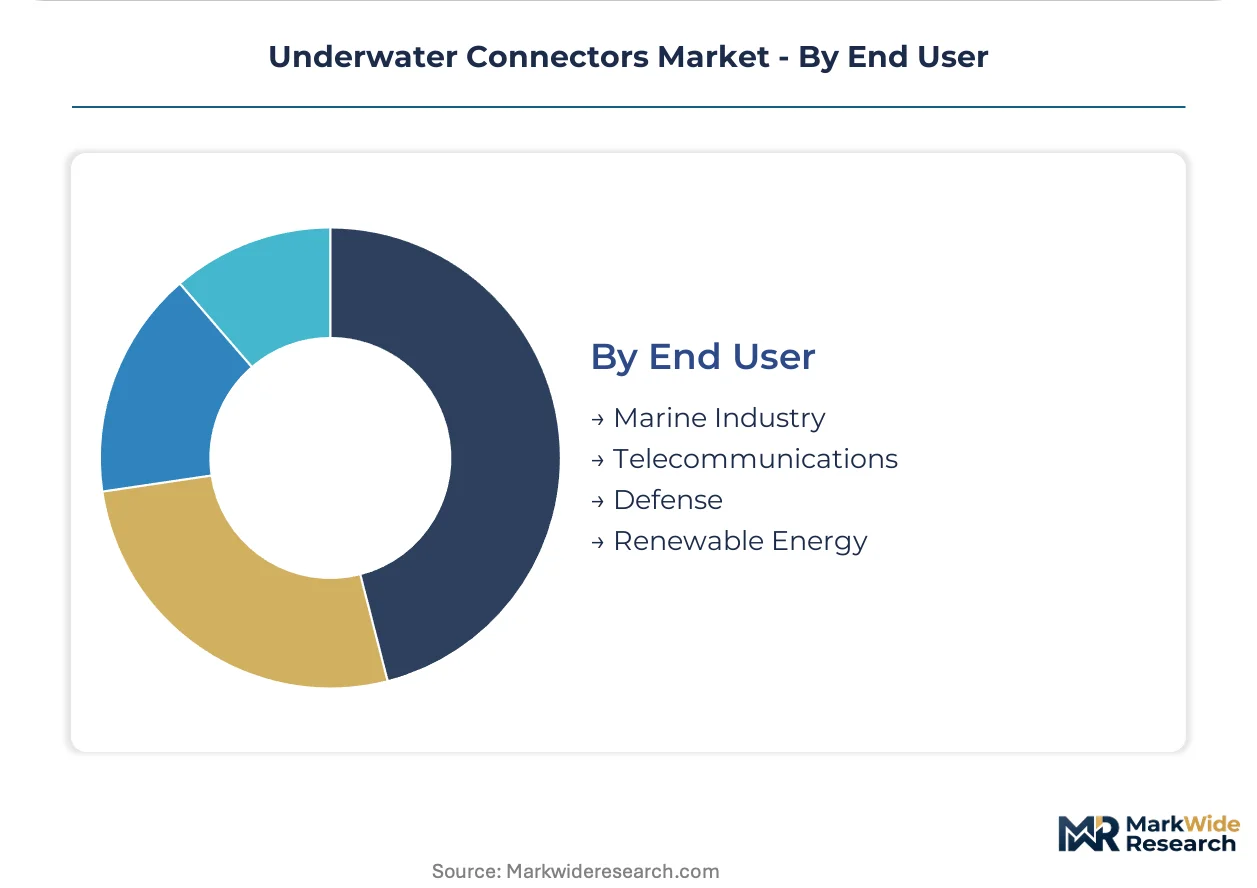
End User:
Defense-aerospace environmental engineering guidelines are opening dual-use qualification pathways, reshaping customer-type competitive dynamics.
- Renewable Energy:Offshore wind farm developers are qualifying additively manufactured connectors for accelerated installation timelines. EU Marine Strategy Framework Directive tightening is forcing redesign of qualification protocols.
- Defense:US Navy MIL-STD-810 guidelines and FAA-equivalent pressure-vessel certifications segment demand. Teledyne Marine leverages integrated sonar and connector portfolio for deep-water installation contracts.
- Marine Industry:Integrated offshore contractors consolidating specification authority.
- Telecommunications:Subsea cable protection zone requirements.
Marine Industry retains procurement volume leadership; Renewable Energy holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore wind interconnector network underwrites Europe's centrality in underwater connector procurement, while subsea cable protection corridors in the Norwegian Trench and UK continental shelf concentrate deployment activity.
Norway
Equinor's Hywind floating wind portfolio and Statnett subsea grid links drive wet-mate connector procurement at depths exceeding 500 meters. The Norwegian Maritime Authority enforces DNV-ST-F203 cable integrity rules for all new offshore installations. Stavanger hosts engineering liaison teams from major connector vendors negotiating decade-long framework agreements with integrated contractors.
United Kingdom
The Dogger Bank wind complex and Celtic Sea floating lease rounds require titanium-housed assemblies rated for 600-bar differentials. The Offshore Petroleum Regulator for Environment and Decommissioning coordinates with BEIS on seabed equipment reliability standards. Aberdeen clusters ROV service providers and connector maintenance operations for North Sea oil and gas decommissioning campaigns.
Denmark
Kriegers Flak and Thor offshore wind zones anchor Baltic Sea connector demand for inter-array cabling systems. The Danish Maritime Authority implements EU Marine Strategy Framework Directive protocols through national coastal zone regulations. Esbjerg port infrastructure supports installation vessel mobilization for Danish and German sector developments.
United States
The Vineyard Wind and South Fork offshore arrays activate Atlantic coast procurement for hybrid optical-electrical penetrators. The Bureau of Ocean Energy Management issues seabed mining exploration licenses contingent on MIL-STD-810 environmental qualification. Houston clusters subsea engineering contractors serving Gulf of Mexico oil and gas retrofit markets.
India
Mundra and Hazira port modernization projects under Gujarat Maritime Board jurisdiction create first-mover positioning for qualified suppliers. The Central Electricity Authority drafts subsea equipment standards for undersea cable protection zones. Chennai and Visakhapatnam anchor submarine cable landing station expansion on the eastern seaboard.
Underwater Connectors Market Vendor Landscape
Listed leaders compete with private specialists across defense-aerospace crossover segments and renewable energy installation contracts. The vendor base concentrates among integrated marine technology conglomerates and connector-specific fabricators with deep-water qualification heritage. Three archetypes dominate: sonar-integrated system houses, MIL-SPEC-qualified defense suppliers, and high-density fiber-optic penetrator specialists. Strategic moves center on additive manufacturing adoption for titanium housing fabrication and dedicated engineering liaison deployment at contractor headquarters.
Among the integrated marine technology tier, Teledyne Marine occupies a position exemplifying sonar-connector bundling for deep-water contracts. Amphenol Corporation and TE Connectivity represent the defense-aerospace crossover archetype, anchoring qualification pathways through pressure-vessel certifications and high-density assembly expertise. These three entities illustrate how technical specification authority shifts toward EPC firms with direct vessel ownership.
| Leading Market Players |
|---|
| Teledyne Marine |
| Fischer Connectors SA |
| Amphenol Corporation |
| Hydro Group |
| BIRNS Inc. |
| TE Connectivity |
| Molex |
| Glenair Inc. |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-month qualification timelines for DNV-ST-F203 certification compress pricing leverage toward incumbent suppliers with existing approvals, while titanium ingot inventory cycles of 90-120 days tether cost structures to Norwegian and Japanese metal exchange fluctuations. Wet-mate connector procurement concentrates among integrated offshore contractors with direct vessel ownership, elevating volume-scale negotiation power and compressing margins for unqualified entrants.
Pricing Analysis
Three-tier pricing structure across MIL-SPEC-qualified, ISO 13628-15-certified, and uncertified commercial tiers separates defense-aerospace crossover demand from North Sea oil and gas retrofit volumes. Price differentiation rests on glass-to-metal hermetic seal traceability and titanium housing alloy grade, with premium tiers commanding substantial uplifts for 6,000-meter depth ratings. Cost compression in the commercial tier intensifies as additive manufacturing enables mid-tier fabricators to bypass five-axis machining capital requirements. Offshore wind developers exhibit highest price sensitivity due to framework agreement bundling of installation and replacement liability, while defense clients demonstrate lowest sensitivity given MIL-STD-810 qualification barriers.
Supply Chain Analysis
Port congestion at Esbjerg and Aberdeen elevates inbound logistics costs for titanium alloy feedstock arriving from Japanese and Russian smelters via Rotterdam transshipment. Manufacturing concentrates in Norway, the United Kingdom, and the United States, with fluoropolymer insulation compound supply drawing from Japanese and European chemical producers. Single-source vulnerability permeates glass-to-metal seal engineering talent pools anchored in legacy aerospace and nuclear suppliers. Distribution runs through integrated offshore contractor procurement desks in Stavanger and Houston, bypassing traditional equipment OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability standards for hybrid optical-electrical penetrators are consolidating around IEEE 802.3 and IEC 61850-9-2LE adaptations, transforming connector selection from component procurement into platform ecosystem positioning with decade-long lock-in effects.
For Market Incumbents: Fortify qualification moats by accelerating additive manufacturing certification for titanium housings under DNV-ST-F203 protocols, while securing backward-compatible interface patents to fragment R&D resources of challengers targeting legacy ROV docking system retrofit markets. Vertical integration into fluoropolymer compound formulation hedges REACH substance restriction exposure. For New Entrants and Emerging Players: Differentiate on rapid-customization agility for seabed mining exploration systems awaiting licensing frameworks, where hybrid optical-electrical convergence creates specification white space outside incumbent oil and gas qualification pathways. Target India's coastal infrastructure modernization under Central Electricity Authority draft standards, leveraging first-mover positioning before domestic qualification protocols solidify. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated marine technology conglomerates seeking to divest non-core connector divisions amid sonar-connector bundling consolidation. Long-term viability hinges on optical-electrical hybrid technology transition completion; the signal to watch is Bureau of Ocean Energy Management seabed mining license issuance velocity as demand inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Certification | DNV-ST-F203 approval for titanium housings fragments machining-dependent supplier bases. |
| Hermetic Seal Engineering Acquisition | Glass-to-metal expertise scarcity constrains production scale-up for qualified manufacturers. |
| Hybrid Technology Platform Development | Optical-electrical convergence serves bandwidth-intensive seabed observation networks. |
| India Market Entry Partnership | Gujarat Maritime Board port modernization creates first-mover qualification positioning. |
| Defense-Aerospace Crossover Qualification | MIL-STD-810 pathways open dual-use revenue streams for pressure-vessel certified vendors. |
Methodological Framework
A standing panel of subsea installation contractors, ROV operations managers, and offshore wind procurement directors provided ongoing calibration, supplemented by regulatory affairs leads at classification societies and titanium alloy procurement specialists. Primary fieldwork combined structured interviews across Stavanger, Aberdeen, and Houston clusters with secondary validation through DNV technical reports, ECHA pre-registration dossiers, and Bureau of Ocean Energy Management licensing records. Bottom-up project pipeline aggregation and top-down macroeconomic scenario testing triangulated volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling spanning wet-mate, hybrid, dry-mate, and specialty connector product types; electromechanical, optical, hybrid, electrical, and RF technology trajectories; and offshore oil and gas, marine research, subsea exploration, and underwater robotics application clusters. CAGRs derived from installation vessel contract award velocity and seabed observation network funding appropriation cycles, with additive manufacturing adoption curves and REACH compliance timelines as industry-specific modifiers.
Decision-makers should treat outputs as directional under sustained North Sea offshore wind capacity addition assumptions and stable fluoropolymer supply allocation; material deviation in seabed mining regulatory frameworks or titanium alloy trade flows would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Canada Connector Market
Connectors
Power Connector Market
Connectors
Press Fit Connector Market
Connectors
PCI-E Connectors Market
Connectors
Underwater Mate Connectors Market
Connectors
Smart Crimper Market
Connectors
Mexico Connector Market
Connectors
Space Grade Connectors Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
AS-Interface Market
Connectors
Latin America Connector Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Circular Waterproof Connector Market
Connectors
USB Type-C Market
Connectors
Connector Market
Connectors
Global Wired Interface Market