
 Electric Submersible Cable Sales Market | 2026-2036
Electric Submersible Cable Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Submersible Cable Sales Market Insights
Saudi Arabia is tilting its manufacturing base toward submersible cable capacity to supply domestic oilfield electrification and Red Sea desalination projects. Prysmian Group leverages integrated compound-to-cable production to sustain margin control across deepwater specifications. Baker Hughes anchors its position through proprietary motor-lead extension systems that reduce splice failure in high-pressure wells. Nexans competes aggressively in the North Sea aftermarket, where platform operators demand rapid-turn replacement cables.
Electric submersible cables are purpose-built power conductors designed for continuous immersion in aggressive fluids, typically employing EPR or XLPE insulation rated for temperatures exceeding 150°C and tensile loads surpassing 50 kN to feed downhole pump motors. Their primary purpose is to transmit three-phase electrical power across thousands of vertical meters while resisting hydrocarbon ingress, gas decompression, and mechanical abrasion in borehole environments. Armored constructions dominate the Oil & Gas application segment due to mandatory crush-resistance requirements in deviated wells, while multi-core configurations capture expanding share in mine pumping as operators consolidate power and monitoring conductors. The Utilities end-user segment maintains the largest installed base, though Mining represents the fastest-growing margin pool as underground water management regulations tighten.
API RP 11S4 guides downhole cable qualification testing in the United States, while the EU F-Gas Regulation indirectly shapes demand by accelerating transitions from gas-lift to electric submersible pump systems in offshore Europe. China's SAMR enforces GB/T 12706 compliance for domestic cable procurement, creating a bifurcated supply landscape where export-grade and local-market products diverge in insulation thickness and testing protocols. Stakeholders must weigh insulation material selection against evolving downhole temperature profiles as operators drill deeper and hotter reservoirs.
Market Dynamics
Deepwater drilling depths and reservoir temperatures are climbing, forcing cable insulation systems to migrate from standard EPR toward high-performance fluoropolymer and PEEK composites rated beyond 200°C continuous operation.
Growth Catalysts
- Permian Basin electrification mandates:Texas shale operators are replacing gas-lift systems with electric submersible pumps to meet flaring reduction targets, pulling armored cable demand upward.
- EU F-Gas Regulation phase-down:Offshore platform operators across Norway and the UK are accelerating ESP conversions away from gas-lift, creating replacement cable procurement cycles.
- EPR-to-XLPE insulation transition:Mining operators in Chile and Australia are specifying cross-linked polyethylene for deeper dewatering boreholes, opening premium cable segments.
Market Restraints
- Copper price volatility:Conductor material costs swing with London Metal Exchange pricing, compressing OEM margins on fixed-price contracts.
- Compound supply concentration:Specialty EPR and fluoropolymer elastomer production clusters in Germany and Japan, exposing cable fabricators to single-source risk.
- Gas-lift persistence in mature fields:Low-cost artificial lift alternatives delay ESP retrofit economics in stripper wells across Oklahoma and Kansas.
Strategic Opportunities
- Red Sea desalination expansion:Saudi Arabia's coastal water projects require submersible power distribution for deep intake pumps, creating non-oilfield demand.
- China's GB/T 12706 upgrade cycle:Domestic oilfield operators must replace legacy cables to meet SAMR enforcement, opening retrofit volume.
- Digital twin integration:Sensor-embedded cable constructions combining power conductors with fiber-optic temperature monitoring are capturing premium positioning in North Sea installations.
Industry Challenges
- Deepwater splicing certification:API RP 11S4 qualification timelines stretch 18-24 months for new motor-lead extension designs, delaying field deployment.
- Compound-to-cable integration complexity:In-house elastomer production requires capital deployment in mixing and curing equipment that smaller fabricators cannot fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Submersible Cable Sales Market |
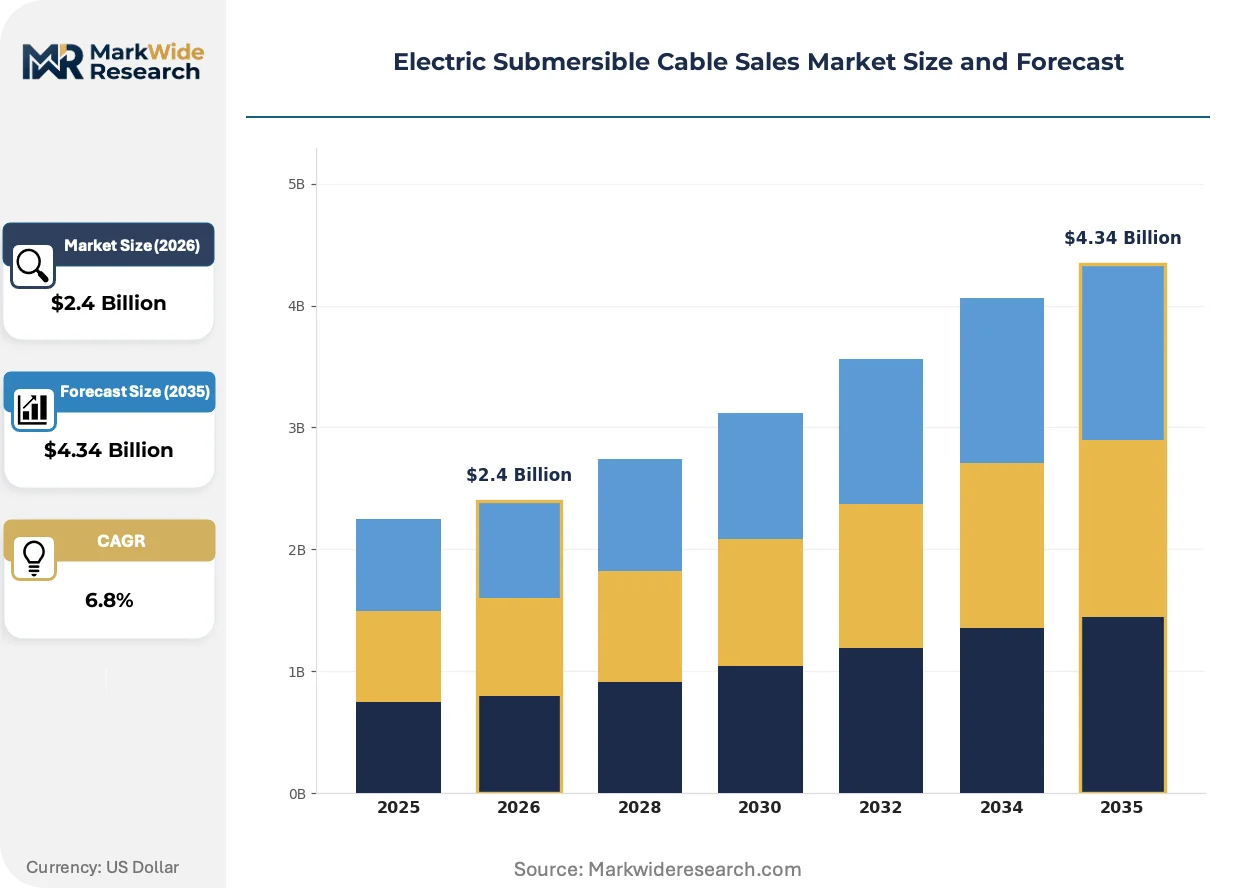
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-core, Multi-core, Armored, Non-armored Insulation Material: XLPE, PVC, Rubber, EPR Application: Oil Extraction, Water Supply, Mine Pumping, Irrigation End User: Utilities, Oil & Gas, Mining, Agriculture |
| Companies Covered | Prysmian Group, Schlumberger Limited, Baker Hughes, Nexans, Halliburton, Borets International, Siemens AG, Hitachi Metals, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Submersible Cable Sales Market Trends and Innovations
Material science advances and digital instrumentation are converging to redefine cable construction standards, while regulatory pressure on hydrocarbon extraction methods accelerates specification upgrades across offshore and unconventional basins.
Downhole cable insulation is migrating from ethylene-propylene rubber toward high-temperature thermoplastic elastomers and PEEK-based composites rated for 230°C continuous exposure. Permian Basin operators drilling hotter laterals are specifying these materials on new pad developments. This migration is compressing the addressable market for conventional EPR constructions while expanding serviceable market value per meter.
The EU F-Gas Regulation is accelerating offshore platform transitions from gas-lift to electric submersible pump systems across the Norwegian Continental Shelf and UK North Sea. Operators face mandated hydrofluorocarbon phase-downs that eliminate artificial lift alternatives. North Sea platform engineering teams are responding with bundled cable and pump procurement packages that compress installation windows.
Buyer concentration among supermajor shale operators is compressing supplier negotiation cycles and unbundling aftermarket service contracts. Integrated independents in the Permian and Eagle Ford are separating cable supply from installation and maintenance, forcing distributors to compete on logistics velocity rather than technical bundling. This pattern is most visible in Texas and New Mexico, where pad drilling density enables just-in-time cable delivery models.
Electric Submersible Cable Sales Market Segmentation
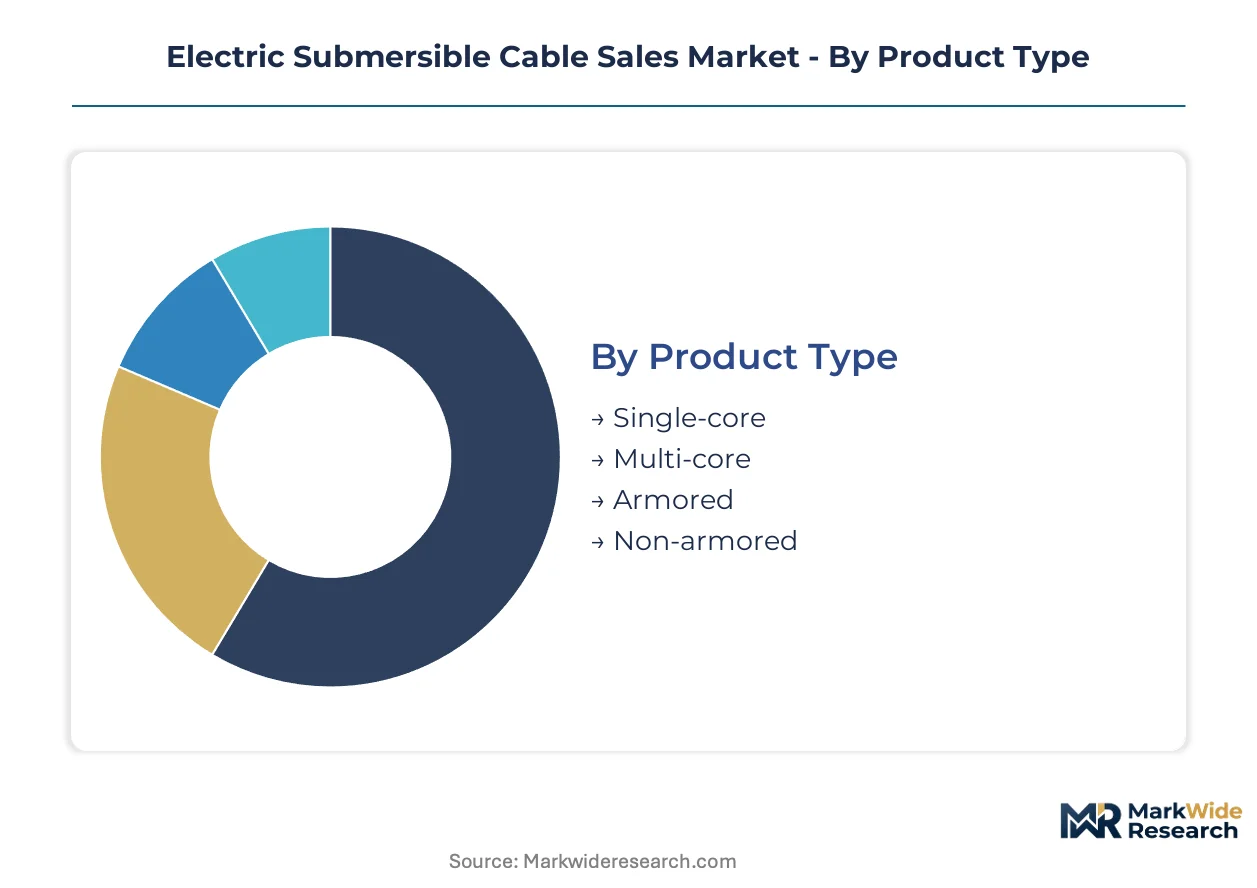
Electric submersible cable specifications diverge sharply across deployment environments, with downhole pressure ratings, fluid chemistry, and mechanical loading dictating material selection and construction geometry. Procurement patterns split between long-cycle infrastructure projects and rapid-turn replacement cycles in mature oilfields.
Product Type:
Armored constructions command the longest replacement cycles in deepwater applications, while non-armored variants turn over fastest in shallow dewatering operations where capital constraints dominate.
- Armored:Steel wire or lead-sheath reinforcement withstands crush loads exceeding 50 kN in deviated wellbores. Permian Basin shale operators specify these for horizontal laterals where cable abrasion against casing walls accelerates failure. Replacement intervals stretch 7-10 years in offshore Brazil pre-salt fields.
- Multi-core:Consolidated power and instrumentation conductors reduce splice points in mine pumping installations. Australian underground coal operators favor these configurations to simplify compliance with water management monitoring mandates. Installation velocity improves 30-40% versus separate cable pulls.
- Single-core:Simplifies motor-lead termination in high-pressure ESP systems. Standard choice for vertical wells with minimal deviation.
- Non-armored:Lightweight construction for vertical water wells and irrigation systems. Cost-sensitive procurement dominates replacement decisions.
Armored dominates installed base. Multi-core is where expansion concentrates.
Insulation Material:
Material cost tiers separate premium fluoropolymer systems from commodity PVC, with EPR and XLPE occupying the contested middle ground where temperature ratings and hydrocarbon resistance trade off against price.
- EPR:Ethylene-propylene rubber maintains flexibility across -40°C to 150°C operating windows. Established specification for North Sea platform ESP retrofits where EU F-Gas Regulation phase-downs eliminate gas-lift alternatives. Compound supply clusters in Germany and Japan.
- XLPE:Cross-linked polyethylene delivers superior dielectric strength for deeper dewatering boreholes. Chilean copper mine operators specify these for 500-meter vertical lifts where EPR thermal limits constrain pump motor sizing. GB/T 12706 compliance in China favors XLPE for domestic procurement.
- Rubber:General-purpose compounds for shallow water supply applications. Price-sensitive segment with minimal specification differentiation.
- PVC:Lowest-cost insulation for irrigation and surface pumping. Temperature ceiling of 70°C restricts downhole deployment.
EPR commands legacy installed base. XLPE is climbing the fastest as operators drill deeper.
Application:
Application segments separate by fluid aggressiveness and duty cycle intensity, with hydrocarbon exposure demanding the most rigorous qualification protocols and water applications permitting faster procurement cycles.
- Oil Extraction:Downhole cables must resist gas decompression, hydrogen sulfide ingress, and mechanical abrasion across thousands of vertical meters. API RP 11S4 qualification timelines stretch 18-24 months for new motor-lead extension designs. Saudi Aramco and Petrobras anchor demand concentration.
- Water Supply:Municipal and industrial intake pumps drive specification toward potable-grade sheathing and simplified installation geometry. Red Sea desalination expansion in Saudi Arabia creates non-oilfield volume with 10-15 year replacement cycles.
- Mine Pumping:Underground dewatering regulations in Australia and Chile tighten monitoring requirements. Multi-core constructions capture share as operators consolidate power and sensor conductors.
- Irrigation:Seasonal duty cycles and surface deployment permit lowest-cost PVC-insulated constructions. Agricultural end-users prioritize capital efficiency over longevity.
Oil Extraction dominates installed base. Mine Pumping is where specification upgrades concentrate.
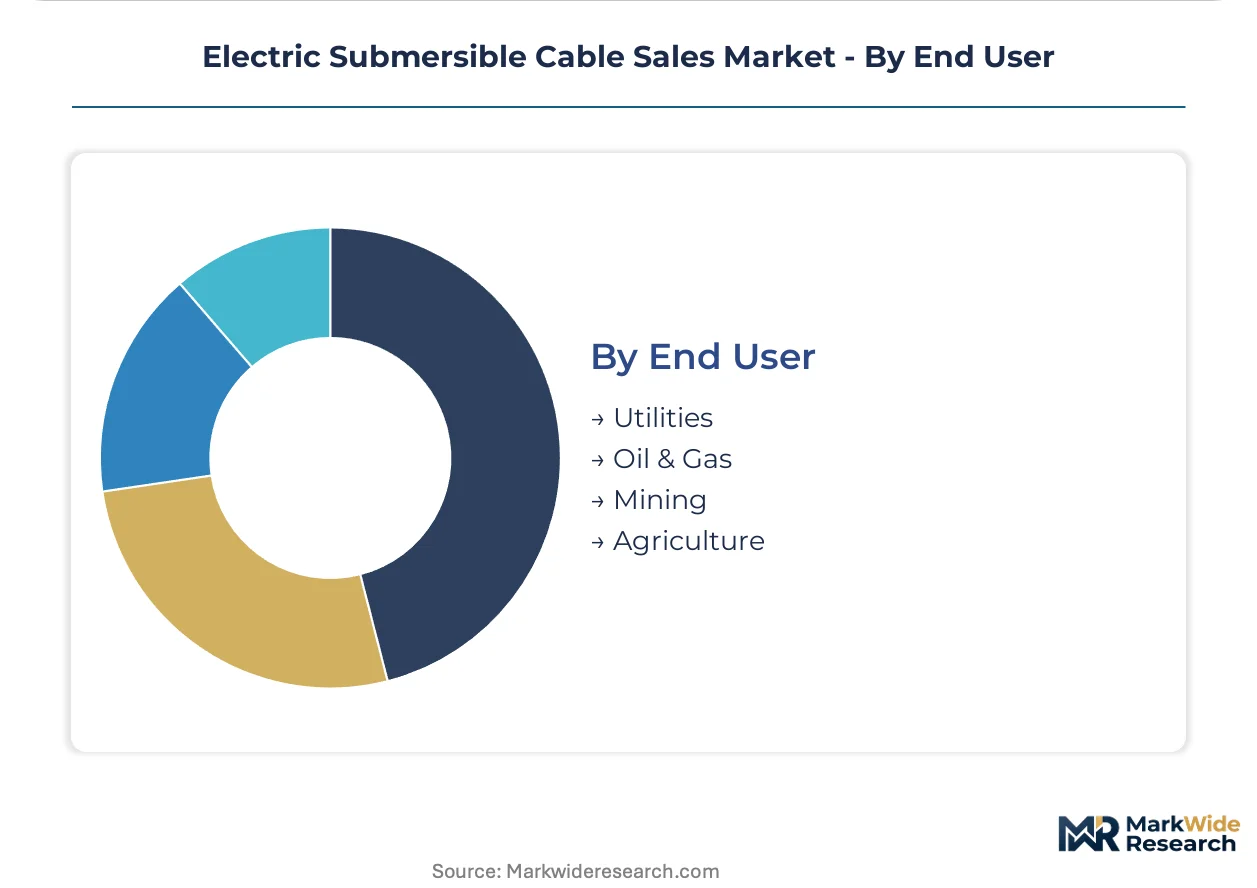
End User:
Customer concentration patterns split between fragmented agricultural procurement and consolidated supermajor oilfield operations, with mining utilities occupying an intermediate position where regulatory compliance drives specification rigidity.
- Oil & Gas:Supermajor and national oil company buyers compress supplier negotiation cycles through bundled cable-pump procurement packages. Permian Basin independents unbundle aftermarket service contracts, forcing distributors to compete on logistics velocity.
- Mining:Underground water management regulations tighten across Australia, Chile, and South Africa. Operators specify higher-temperature-rated cables as dewatering boreholes deepen. Procurement cycles accelerate versus historical norms.
- Utilities:Municipal water authorities maintain the largest installed base globally. Replacement demand follows asset lifecycle patterns with limited specification volatility.
- Agriculture:Fragmented end-user base with price-sensitive procurement. Seasonal demand patterns complicate inventory planning for distributors.
Utilities dominates installed base. Mining is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API RP 11S4 anchors qualification protocols in the United States, where shale operators retrofit aging artificial lift systems. Demand concentrates across five countries where oilfield electrification, mining dewatering, and desalination infrastructure pull cable procurement cycles.
United States
Permian Basin operators replace gas-lift with electric submersible pumps to meet Texas flaring reduction mandates. EPA enforcement tightens methane emissions standards, accelerating ESP conversions. Midland-Odessa cable distributors compete on logistics velocity as independents unbundle supply from installation contracts.
Brazil
Petrobras expands pre-salt field electrification with armored cables rated for 50 kN crush loads. ANP production sharing contracts mandate local content thresholds, pushing cable fabricators toward domestic assembly partnerships. Rio de Janeiro anchors offshore engineering clusters serving Santos Basin deployments.
Saudi Arabia
Saudi Aramco electrifies mature fields while NEOM and Red Sea desalination projects create non-oilfield demand. SFDA procurement guidelines align with SAMR-equivalent technical standards for downhole safety. Dammam manufacturing corridors expand compound-to-cable capacity to supply domestic and export markets.
China
MIIT enforces stricter GB standards for downhole electrical safety as shale operators drill deeper Sichuan Basin laterals. SAMR mandates GB/T 12706 compliance for domestic cable procurement, bifurcating export-grade from local-market specifications. Dongying petrochemical clusters adapt insulation thickness for high-temperature reservoir profiles.
Australia
Underground coal operators specify multi-core cables to consolidate power and water management monitoring conductors. State-level mining regulators tighten dewatering borehole compliance, accelerating replacement cycles. Queensland Bowen Basin procurement favors XLPE insulation for 500-meter vertical lift applications.
Electric Submersible Cable Sales Market Competitive Landscape
Integrated energy service conglomerates and specialized cable fabricators split the market between bundled pump-cable packages and standalone conductor supply. The vendor base concentrates around three strategic archetypes: vertically integrated oilfield service providers controlling motor-lead extension systems, compound-to-cable specialists with in-house elastomer production, and regional distributors competing on logistics velocity. Dominant competitive moves include backward integration into specialty polymer mixing and rapid-turn aftermarket service unbundling.
Among European cable specialists, Prysmian Group and Nexans exemplify the compound-to-cable archetype with integrated production control. Baker Hughes anchors the integrated service provider tier through proprietary downhole system integration. These three occupy positions spanning premium deepwater specifications through rapid-turn North Sea replacement cycles.
| Leading Market Players |
|---|
| Prysmian Group |
| Schlumberger Limited |
| Baker Hughes |
| Nexans |
| Halliburton |
| Borets International |
| Siemens AG |
| Hitachi Metals |
| ABB Ltd. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in German and Japanese specialty elastomer production is tightening compound availability and amplifying pricing leverage for integrated cable fabricators with captive mixing operations. This utilization squeeze transmits through to armored cable premiums in deepwater specifications while compressing margins for distributors without upstream compound control.
Pricing Analysis
Geographic price spreads between North Sea platform retrofits and Permian Basin shale installations reflect divergent certification burdens and logistics complexity. Three-tier pricing structure across API RP 11S4-qualified premium, GB/T 12706-compliant standard, and non-certified economy levels separates offshore supermajors from domestic Chinese operators and agricultural irrigators. Price differentiation hinges on fluoropolymer insulation grade and motor-lead extension certification status. Pricing pressure stems from copper LME volatility and unbundled service contracts in Texas and New Mexico. Agricultural end-users exhibit highest price sensitivity; deepwater operators in Brazil and Norway demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Saudi Aramco and Petrobras are forcing cable fabricators toward supply-chain finance facilities to bridge working capital gaps. Geographic supply concentration centers on Germany and Japan for specialty EPR and fluoropolymer elastomers, China for copper processing and GB-standard cable assembly, and Italy for integrated compound-to-cable production. Raw material dependencies include copper cathode, ethylene-propylene rubber, and PEEK resin. Single-source vulnerability in German and Japanese compound production exposes fabricators to disruption. Distribution runs through oilfield service integrators for bundled pump-cable packages and regional distributors for rapid-turn replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric submersible cable procurement is shifting toward platform-economy dynamics as sensor-embedded constructions merge power transmission with digital twin infrastructure. Interoperability between fiber-optic temperature monitoring and ESP control systems is creating ecosystem lock-in effects that favor integrated suppliers.
For Market Incumbents: Insulate margin position through backward integration into specialty elastomer mixing and curing capacity in Dammam or Dongying corridors. Prioritize API RP 11S4 certification investment to defend against unbundled distributor competition in Permian Basin logistics velocity wars. Lock in long-term copper offtake agreements to neutralize LME volatility exposure on fixed-price platform contracts. For New Entrants and Emerging Players: Red Sea desalination intake pump applications in Saudi Arabia represent the most penetrable entry point for non-oilfield volume with 10-15 year replacement cycles and less stringent qualification timelines. Australian underground coal multi-core specifications offer second-mover opportunity as state regulators tighten dewatering monitoring mandates. Lead with sensor-embedded cable constructions combining power and fiber-optic conductors to differentiate from commodity armored suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compound-to-cable specialists with in-house elastomer production and installed base service contracts in the North Sea aftermarket. Long-term viability favors vertically integrated fabricators controlling motor-lead extension system design rather than pure-play conductor suppliers. Watch for MIIT enforcement acceleration on GB/T 12706 compliance as signal for China retrofit volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Elastomer Production | Prysmian Group's captive compound mixing insulates margins against German and Japanese supply concentration. |
| Sensor-Embedded Cable Platform Development | Fiber-optic temperature monitoring integration captures premium positioning in North Sea digital twin deployments. |
| GB/T 12706 Compliance Certification Investment | SAMR enforcement bifurcation creates retrofit volume capture opportunity for export-grade specification adapters. |
| Red Sea Desalination Supply Agreement | NEOM and coastal water projects diversify revenue beyond oilfield cyclicality for Saudi-based fabricators. |
| Permian Basin Logistics Velocity Partnership | Just-in-time delivery models align with unbundled procurement patterns among Texas and New Mexico independents. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oilfield procurement directors, ESP system engineers, cable fabrication plant managers, and mining dewatering compliance officers. Secondary validation drew from API RP 11S4 technical documentation, SAMR GB standard filings, ANP local content regulations, and customs trade data for copper and elastomer flows. Bottom-up volume modeling triangulated against top-down energy service company capex disclosures.
Calibration against historical replacement cycles in the North Sea and Permian Basin anchored growth trajectory assumptions across the analysis window. Segmentation dimensions included armored versus non-armored construction, EPR versus XLPE versus fluoropolymer insulation, oil extraction versus mine pumping versus water supply application, and supermajor versus independent versus utility end-user archetype. CAGRs derived from weighted average of operator deployment schedules and regulatory phase-down timelines. Forecast inputs incorporated reservoir temperature profiles from Santos Basin and Sichuan Basin drilling records.
Practitioners should monitor copper LME volatility, EU F-Gas Regulation enforcement acceleration, and MIIT GB standard upgrade timelines for early signals of forecast deviation. Forecasts reflect assumptions about shale electrification mandate continuity and deepwater drilling depth progression. Macroeconomic commodity shock, regulatory enforcement delay, or breakthrough in gas-lift alternative technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Patch Cable Market
Cables
Data Center Wire and Cable Market
Cables
High Voltage Cables Market
Cables
Aluminum Cable Market
Cables
Latin America Wire and Cable Market
Cables
Flat Flexible Cables Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
Premise Cable Market
Cables
Instrumentation Cables Market
Cables
Magnetic Charging Cable Market
Cables
Cable Management System Market
Cables
Copper Stranded Wire Market
Cables
North America Patch Cable Market
Cables
Cable Flange Market
Cables
North America HVAC Cables Market
Cables
Cable Drum Market