
 Europe Logic Integrated Circuit (IC) Market | 2026-2036
Europe Logic Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Logic Integrated Circuit (IC) Market Insights
CE marking under the EU Radio Equipment Directive is reorganizing which logic IC suppliers can serve European telecommunications and automotive OEMs. Infineon Technologies AG leverages its vertical integration into power management logic to dominate industrial automation sockets across Germany. STMicroelectronics NV anchors its position through R&D intensity in CMOS and mixed-signal architectures for automotive ECUs. NXP Semiconductors differentiates by controlling channel access to Tier-1 suppliers in France and the Netherlands.
Logic integrated circuits are semiconductor devices that perform Boolean operations using transistor arrays fabricated through photolithography on silicon wafers, typically operating at supply voltages from sub-1V to 5V depending on the process node; their primary purpose is to process, store, and route digital signals in electronic systems. Digital IC and mixed-signal IC categories capture the dominant margin pools as automotive OEMs and telecommunications infrastructure builders demand higher gate densities with integrated analog front-ends. CMOS technology leads in volume production while SOI processes extend into power-sensitive aerospace and satellite applications where leakage current demands stricter control.
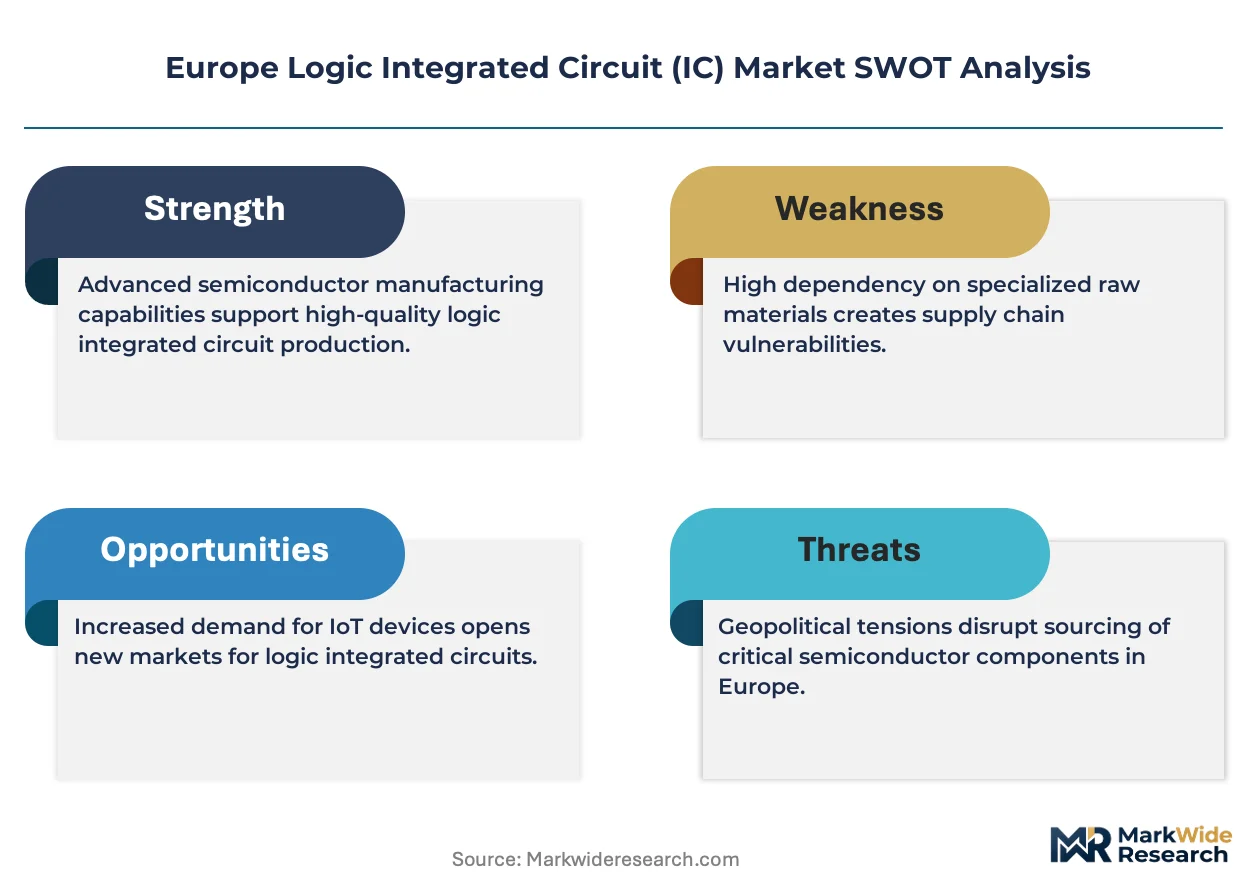
The EU Chips Act and REACH compliance requirements are tightening material traceability and chemical restrictions for logic IC fabrication facilities operating in Europe. ECHA substance-of-very-high-concern listings are forcing foundries to reformulate etching chemistries and substrate doping processes. The CE marking and MDR frameworks further constrain how medical device OEMs qualify logic IC suppliers. Stakeholders must monitor how DGFT export control alignments and EU AI Act chip transparency rules reshape procurement criteria for system integrators serving regulated end markets.
Market Dynamics
German automotive OEMs are internalizing logic IC design teams to bypass foundry bottlenecks while ECHA substance restrictions force reformulation of etching chemistries across European fabrication facilities. These dual pressures—supply security mandates and chemical compliance—are compressing vendor qualification timelines and reshaping procurement hierarchies.
Growth Catalysts
- EU Chips Act capital deployment:Public funding streams are accelerating domestic wafer fabrication investments in Dresden and Leuven, reducing import dependency for 28nm and above process nodes.
- Automotive ECU consolidation:German and French OEMs are integrating powertrain, chassis, and ADAS functions onto fewer logic IC platforms, driving demand for higher gate density with embedded non-volatile memory.
- CE marking reorganization under RED:Telecommunications infrastructure builders must now qualify logic IC suppliers against stricter electromagnetic compatibility and cybersecurity baselines, favoring vendors with pre-certified design libraries.
Market Restraints
- Fluorinated gas supply constraints:F-Gas Regulation phase-down schedules are restricting access to etching gases essential for advanced logic node production, elevating input cost volatility for European foundries.
- Single-source lithography equipment:Extreme ultraviolet scanner availability concentrates with one Dutch supplier, creating capex scheduling bottlenecks for logic IC manufacturers targeting sub-7nm geometries.
- Silicon carbide substitution in power electronics:Wide-bandgap semiconductors are capturing sockets in electric vehicle inverters that silicon-based logic ICs previously addressed through complex gate driver integration.
Strategic Opportunities
- Netherlands embedded logic clusters:ASML ecosystem concentration around Veldhoven creates co-location advantages for fabless logic IC designers seeking proximity to lithography roadmapping and process development partnerships.
- EU AI Act chip transparency mandates:System integrators serving regulated AI applications must document compute performance and energy consumption metrics, creating service revenue streams for logic IC vendors with embedded telemetry capabilities.
- FD-SOI and CMOS convergence:Aerospace and satellite OEMs in France are qualifying hybrid process flows combining fully depleted silicon-on-insulator leakage control with standard CMOS design portability for radiation-hardened applications.
Industry Challenges
- Compound semiconductor integration complexity:Logic IC design teams lack validated simulation models for gallium nitride and silicon carbide co-packaging, delaying heterogeneous integration timelines for power management units.
- REACH compliance timeline compression:ECHA substance-of-very-high-concern listings are forcing foundries to requalify substrate doping chemistries within 18-month windows, disrupting production ramps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Logic Integrated Circuit (IC) Market |
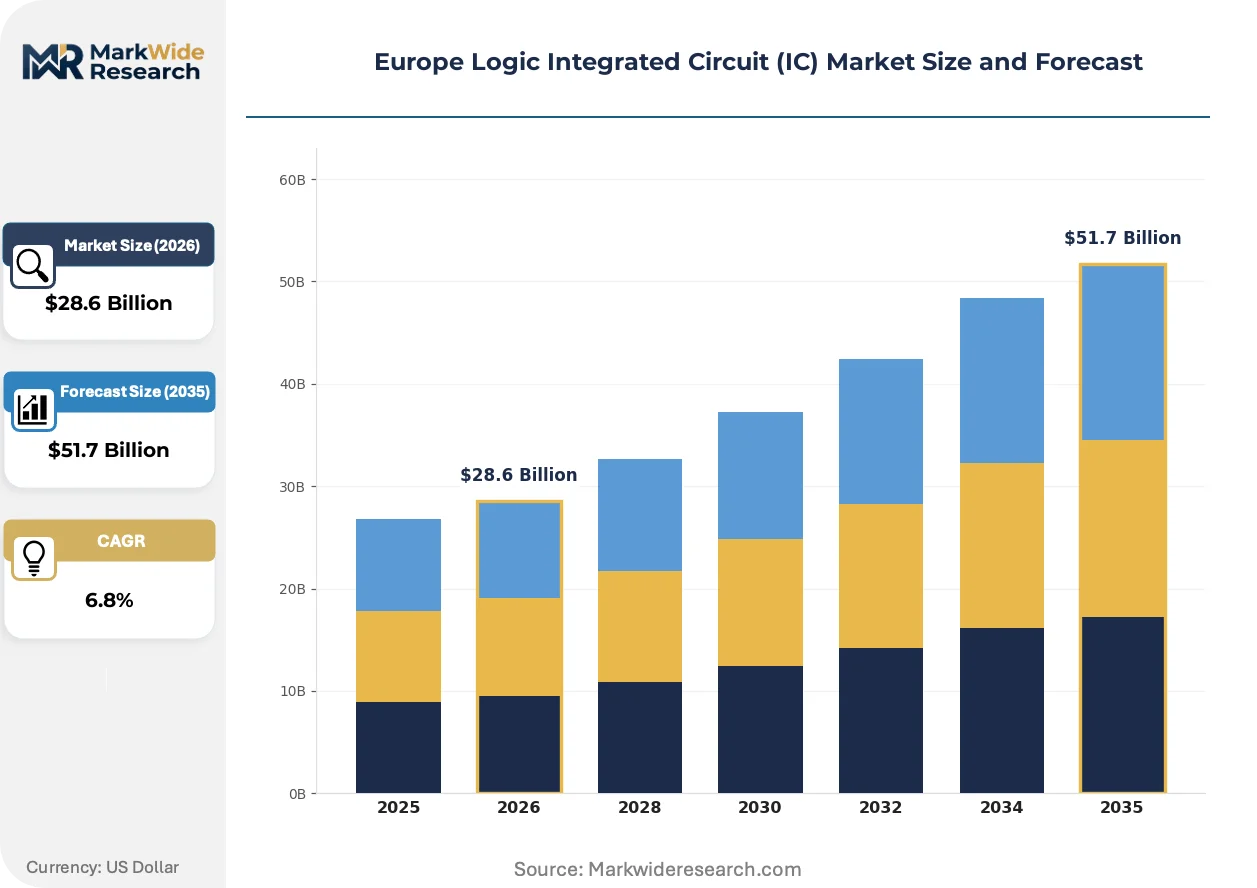
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog IC, Digital IC, Mixed-Signal IC, Power Management IC Technology: CMOS, Bipolar, BiCMOS, SOI Application: Consumer Electronics, Automotive, Telecommunications, Industrial Automation End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators |
| Companies Covered | Infineon Technologies AG, Arm Limited, STMicroelectronics NV, Samsung Electronics Co., Ltd., Dialog Semiconductor, Analog Devices, Inc., Renesas Electronics Corporation, Texas Instruments Incorporated, NXP Semiconductors, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Logic Integrated Circuit (IC) Market Trends and Innovations
Logic IC architectures are fragmenting across application-specific optimization paths, with process node selection diverging sharply between automotive reliability requirements and telecommunications throughput demands. This specialization is compressing design reuse economics while elevating R&D intensity.
Gate-all-around transistor architectures are supplanting finFET structures at 3nm and below process nodes. European telecommunications infrastructure builders are accelerating qualification timelines for these geometries to support 5G-Advanced baseband processing density requirements. The shift is supplanting incumbent planar transistor IP libraries and forcing EDA tool vendors to recalibrate parasitic extraction algorithms.
CSRD sustainability disclosure requirements are mandating scope 3 emissions reporting across logic IC supply chains. European OEMs must now document embodied carbon in purchased semiconductors, pushing foundries to publish process-specific energy consumption data. Automotive Tier-1 suppliers in Germany are responding by inserting emissions clauses into logic IC procurement contracts with 2027 compliance deadlines.
Long-term supply agreements are displacing spot market purchasing for automotive-grade logic ICs. French and Dutch OEMs are locking 36- to 60-month foundry allocations to secure capacity at 22nm and 28nm nodes for chassis control modules. This contractual pivot is most visible in Germany, where Volkswagen and BMW procurement teams have abandoned quarterly price negotiations in favor of volume-commitment frameworks with penalty clauses for demand forecast deviations.
Europe Logic Integrated Circuit (IC) Market Segmentation
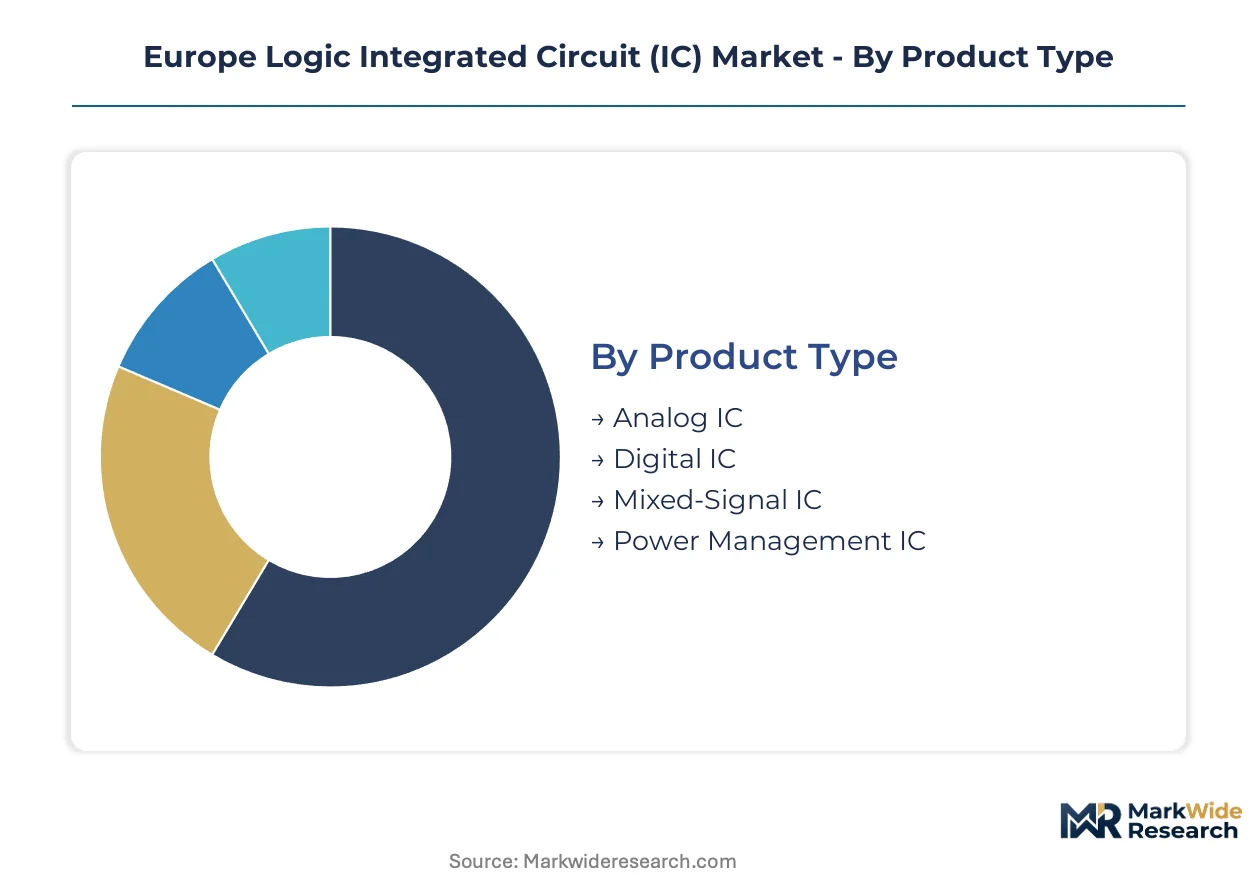
Logic IC procurement in Europe fragments across incompatible performance specifications, with automotive ECU consolidation and telecommunications infrastructure builds pulling demand toward distinct process node clusters. Segmentation reveals where substitution threats from compound semiconductors and wide-bandgap materials concentrate pressure.
Product Type:
Substitution pressure from silicon carbide and gallium nitride power electronics weighs heaviest on segments handling voltage regulation and signal conversion, forcing repositioning toward integrated analog-digital boundaries.
- Digital IC:Boolean operation devices fabricated at 28nm to 3nm nodes serve high-throughput computing in telecommunications baseband processors and ADAS compute platforms. German automotive OEMs are internalizing design teams for these devices to bypass foundry allocation bottlenecks. Digital IC retains volume leadership; Mixed-Signal IC holds the steepest expansion curve.
- Mixed-Signal IC:Architectures combining analog front-ends with digital signal processing on single die address sensor fusion and RF transceiver requirements. STMicroelectronics NV concentrates R&D investment here for automotive ECU consolidation in France and Italy. These devices capture premium positioning where electromagnetic compatibility under CE marking RED creates qualification barriers.
- Analog IC:Continuous signal processing components for power regulation and audio amplification face margin compression from discrete component substitution in consumer electronics.
- Power Management IC:Voltage regulators and battery charging controllers encounter direct competition from integrated gallium nitride solutions in electric vehicle inverter sockets.
Digital IC retains volume leadership; Mixed-Signal IC holds the steepest expansion curve.
Technology:
Cost tier stratification separates volume production at mature nodes from radiation-hardened and power-sensitive applications requiring specialized substrate engineering.
- CMOS:Complementary metal-oxide-semiconductor dominates wafer starts through 22nm and above geometries, serving cost-sensitive consumer electronics and industrial automation controllers. Dresden and Leuven foundry investments under the EU Chips Act target CMOS capacity expansion for automotive qualification. CMOS commands the broadest foundry allocation; SOI shows the most rapid qualification expansion.
- SOI:Silicon-on-insulator substrates eliminate latch-up and reduce leakage for aerospace and satellite applications. French OEMs are qualifying FD-SOI variants for radiation-hardened logic in defense and space programs. These processes carry 40-60% wafer cost premiums but enable operation across wider temperature ranges.
- Bipolar:Junction transistor architectures persist in precision analog and high-current switching where carrier mobility advantages outweigh density limitations.
- BiCMOS:Hybrid processes merge bipolar linear performance with CMOS density for RF power amplifiers and high-speed interface circuits.
CMOS commands the broadest foundry allocation; SOI shows the most rapid qualification expansion.
Application:
Customer type divergence separates spot-market procurement from long-term volume commitments with penalty structures for demand forecast deviations.
- Automotive:Chassis control, powertrain management, and ADAS compute modules drive qualification toward AEC-Q100 Grade 1 standards. Volkswagen and BMW procurement teams have abandoned quarterly negotiations for 36-60 month foundry allocation contracts. Gate-all-around transistor architectures at 3nm face accelerated timelines for 5G-Advanced baseband density.
- Telecommunications:5G-Advanced baseband processing and optical transport infrastructure demand sub-7nm geometries with embedded telemetry for EU AI Act compliance documentation. CE marking RED reorganization favors vendors with pre-certified electromagnetic compatibility libraries.
- Consumer Electronics:Smartphone and wearable applications face margin pressure from Asian fabless competition and shorter product lifecycles.
- Industrial Automation:Programmable logic controllers and motor drives prioritize reliability over leading-edge density, sustaining demand at 40nm and above nodes.
Automotive anchors committed-volume procurement; Telecommunications drives the most aggressive node migration.
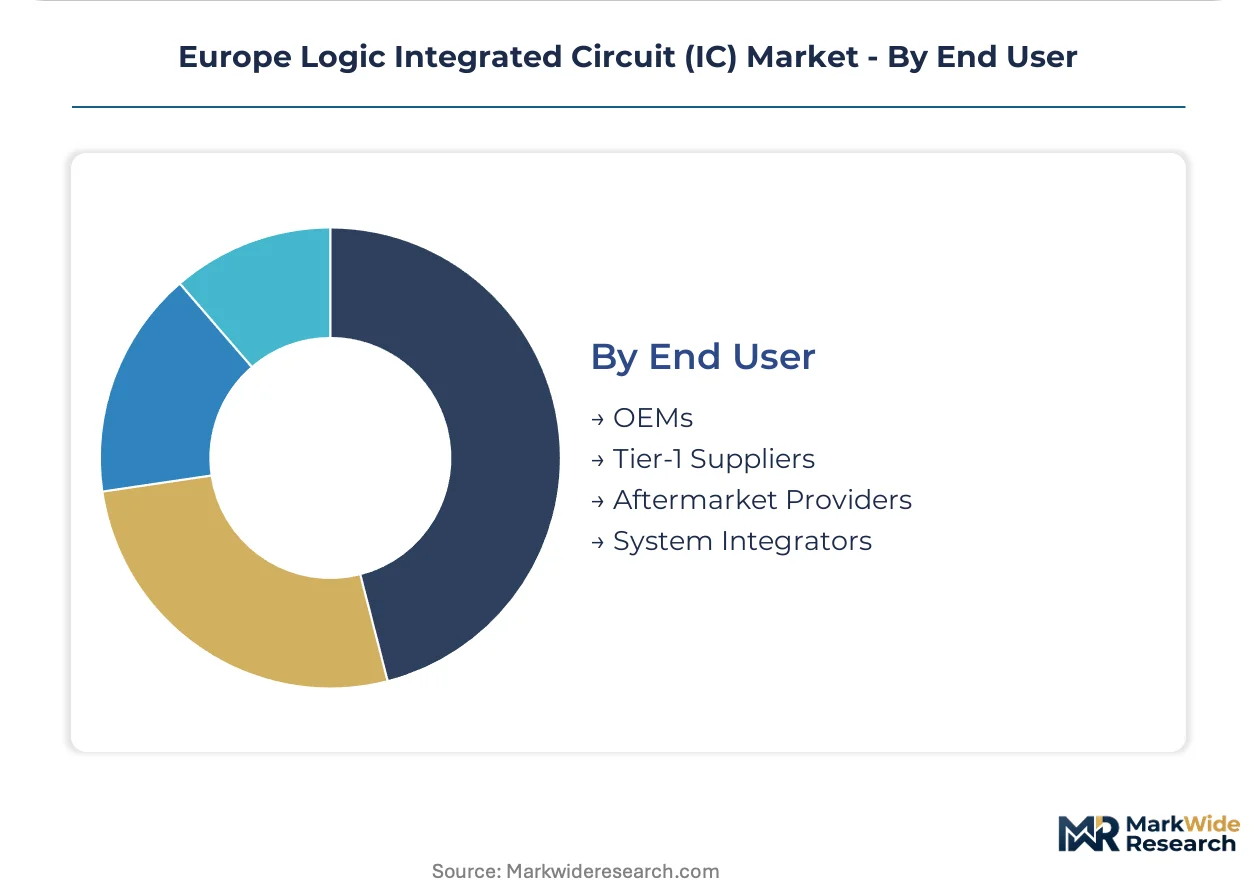
End User:
Supply concentration among Dutch lithography equipment creates capex scheduling bottlenecks that propagate differentially through procurement hierarchies.
- OEMs:German automotive manufacturers are expanding captive design capabilities and securing direct foundry relationships to reduce Tier-1 supplier dependency. These organizations insert emissions clauses into logic IC contracts with 2027 CSRD compliance deadlines.
- Tier-1 Suppliers:Continental and Bosch procurement organizations face margin compression as OEMs internalize design authority while retaining Tier-1 integration responsibility.
- System Integrators:European telecommunications infrastructure builders must document compute performance and energy consumption under EU AI Act transparency mandates, creating service revenue opportunities.
- Aftermarket Providers:Replacement module suppliers encounter qualification barriers from encrypted component authentication and software-locked spare part strategies.
OEMs capture the most direct foundry access; System Integrators face the most complex compliance documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underpins Central European semiconductor logistics, connecting Dresden fabrication clusters to North Sea ports and enabling just-in-time wafer shipments for automotive Tier-1 suppliers.
Germany
Automotive ECU consolidation at Volkswagen and BMW drives captive logic IC design teams in Munich and Stuttgart. The KBA enforces AEC-Q100 automotive qualification standards that compress vendor approval timelines. Dresden anchors the EU Chips Act wafer fabrication investments, with Bosch and Infineon expanding 28nm CMOS capacity for powertrain controllers.
France
Aerospace OEMs in Toulouse and defense contractors around Paris qualify FD-SOI processes for radiation-hardened satellite applications. ANSM medical device regulations intersect with CE marking MDR requirements to constrain logic IC supplier selection for implantable electronics. Grenoble hosts embedded logic R&D clusters serving STMicroelectronics mixed-signal development.
Netherlands
ASML's Veldhoven lithography ecosystem concentrates extreme ultraviolet scanner availability, creating co-location advantages for fabless designers seeking process development partnerships. The Dutch Authority for Digital Infrastructure enforces EU AI Act chip transparency mandates for system integrators. Eindhoven's Brainport region anchors embedded logic clusters serving telecommunications infrastructure builders.
Italy
Industrial automation manufacturers in Milan and Turin sustain demand for 40nm and above CMOS nodes in programmable logic controllers. The National Institute for Insurance against Accidents at Work enforces machinery safety standards that elevate logic IC reliability requirements. STMicroelectronics maintains mixed-signal design centers in Agrate Brianza serving automotive ECU consolidation.
United Kingdom
Arm Limited's Cambridge architecture licensing underpins fabless logic IC design across European telecommunications and automotive sectors. The UK National Cyber Security Centre mandates supply chain security assessments for critical infrastructure semiconductors. Bristol and Cambridge host embedded systems clusters developing low-power logic for IoT applications.
Europe Logic Integrated Circuit (IC) Market Competitive Landscape
Listed leaders compete with private specialists across intellectual property licensing and captive fabrication capacity. The vendor base clusters around three tiers: integrated device manufacturers with in-house wafer production, fabless designers reliant on foundry partnerships, and architecture licensors controlling instruction set ecosystems. Strategic differentiation hinges on backward integration into substrate manufacturing and geographic proximity to ASML lithography roadmapping.
Among Germany-based integrated device manufacturers, Infineon Technologies AG exemplifies the vertical fabrication archetype, while Netherlands-anchored NXP Semiconductors occupies a position bridging automotive channel access with mixed-signal R&D intensity. STMicroelectronics NV represents the Franco-Italian transnational model combining CMOS volume production with aerospace-qualified SOI specialization.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Arm Limited |
| STMicroelectronics NV |
| Samsung Electronics Co., Ltd. |
| Dialog Semiconductor |
| Analog Devices, Inc. |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Fab utilization rates above 90% at Dresden and Leuven foundries are compressing marginal cost curves for 28nm CMOS wafers while elevating price floors for automotive-grade logic ICs. This scale concentration grants incumbent integrated device manufacturers asymmetric bargaining power against fabless competitors seeking foundry allocation.
Pricing Analysis
Three-tier pricing structure across automotive-qualified, industrial-grade, and commercial-off-the-shelf levels dominates procurement contracts. Price differentiation rests on AEC-Q100 certification tier and volume commitment scale, with German OEMs locking 36-60 month allocations at penalty-structured terms. Cost compression in commercial-grade segments is intensifying because Asian fabless competition floods consumer electronics sockets. Tier-1 suppliers face the steepest price sensitivity due to OEM design internalization, while aerospace OEMs exhibit lowest sensitivity given radiation-hardened qualification barriers.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg is elevating inbound logistics costs for silicon wafer feedstock arriving from East Asian polishing facilities. Geographic supply concentration centers on Taiwan for leading-edge foundry capacity, South Korea for memory-logic integration, and the Netherlands for extreme ultraviolet lithography equipment. Raw material dependencies span high-purity silicon ingots, fluorinated etching gases, and photoresist chemistries. Single-source vulnerability concentrates at ASML for sub-7nm scanner availability. Distribution runs through authorized distributors serving automotive Tier-1 clusters around Stuttgart and Munich.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as automotive OEMs consolidate ECU architectures around fewer logic IC suppliers, creating winner-take-most dynamics in embedded software ecosystems. Interoperability requirements under EU AI Act transparency mandates are forcing telemetry-capable vendors into de facto standard-setting roles.
For Market Incumbents: Fortify backward integration into substrate manufacturing to secure supply against ECHA substance restriction volatility. Expand captive 28nm CMOS capacity at Dresden under EU Chips Act funding envelopes. Defend channel access by embedding firmware authentication that locks out aftermarket substitution.
For New Entrants and Emerging Players: Lead with FD-SOI specialization for French aerospace and satellite programs where radiation-hardened qualification creates incumbent displacement opportunities. Target embedded logic clusters around Eindhoven for ASML ecosystem proximity. Pursue fabless partnerships with Leuven research foundries to bypass capital-intensive fabrication barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among logic IC vendors with long-term automotive allocation contracts and embedded software service streams. Five-to-ten year viability favors mixed-signal specialists with CMOS-SOI hybrid process portfolios. Monitor EU AI Act implementation velocity as inflection indicator for telemetry-enabled vendor premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Chips Act Capacity Expansion | Dresden and Leuven fab investments reduce import dependency for automotive-qualified nodes. |
| FD-SOI Process Qualification | French aerospace OEMs are adopting radiation-hardened variants for satellite payload electronics. |
| Long-Term Supply Agreements | Volkswagen and BMW procurement teams have abandoned spot purchasing for volume-commitment frameworks. |
| Embedded Telemetry Integration | EU AI Act mandates are creating service revenue streams for compute-performance documentation. |
| Gate-All-Around Architecture Migration | Telecommunications infrastructure builders accelerate 3nm qualification for 5G-Advanced baseband density. |
Research Methodology
A standing panel of automotive platform engineers, foundry operations directors, telecommunications procurement leads, and EDA tool vendors provided ongoing calibration throughout data collection. Primary interviews with Tier-1 supplier sourcing managers and semiconductor distribution channel heads were cross-validated against secondary sources including SEC semiconductor filings, EU Chips Act implementation progress reports, ECHA substance restriction updates, and customs trade flow data. Bottom-up wafer demand modeling was triangulated with top-down OEM production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, process technology, application vertical, and end-user procurement tier. CAGRs were derived from fitted growth curves applied to foundry capacity expansion schedules and OEM platform consolidation roadmaps. Forecast inputs incorporated EU regulatory implementation timelines and automotive ECU integration trajectories.
The analysis sits within stated boundaries; outcomes outside EU Chips Act funding continuity or ECHA substance restriction severity assumptions would require recalibration. Forecasts reflect documented assumptions regarding foundry yield improvements and automotive production stability. Semiconductor cycle downturns, geopolitical export control escalations, or compound semiconductor substitution acceleration could revise trajectory projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Automotive IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market