
 Power and Signal Cables Market | 2026-2036
Power and Signal Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Power and Signal Cables Market Outlook
Data center power architecture is decoupling from traditional copper-dense designs as hyperscale operators prioritize higher amperage trunking and structured signal paths. Prysmian Group leverages its submarine and land cable integration to anchor large-scale offshore wind interconnection projects across multiple continents. Nexans competes through advanced alloy conductor R&D and localized manufacturing footprints that reduce logistics exposure for European infrastructure clients.
Power and signal cables are engineered conductors with metallic cores—typically copper or aluminum—surrounded by dielectric insulation layers such as XLPE or PVC, designed to transmit electrical energy or encoded information across fixed installations with specified voltage ratings and shielding performance. Low voltage cables dominate residential and commercial volume, while high voltage cables command concentrated margin pools in grid modernization and renewable export corridors. Data cables represent the fastest-expanding structural segment, driven by 5G backhaul expansion and fiber-to-the-premises programs that require hybrid power-signal bundles.
The EU Green Deal and REACH frameworks restrict halogenated flame retardants in cable sheathing, compelling compound reformulation across European supply chains. China's GB standards and dual carbon goals enforce stricter energy efficiency benchmarks for conductor losses in new transmission assets. Stakeholders must monitor evolving material compliance timelines and conductor efficiency thresholds to avoid stranded inventory and qualify for public procurement tenders.
Market Dynamics
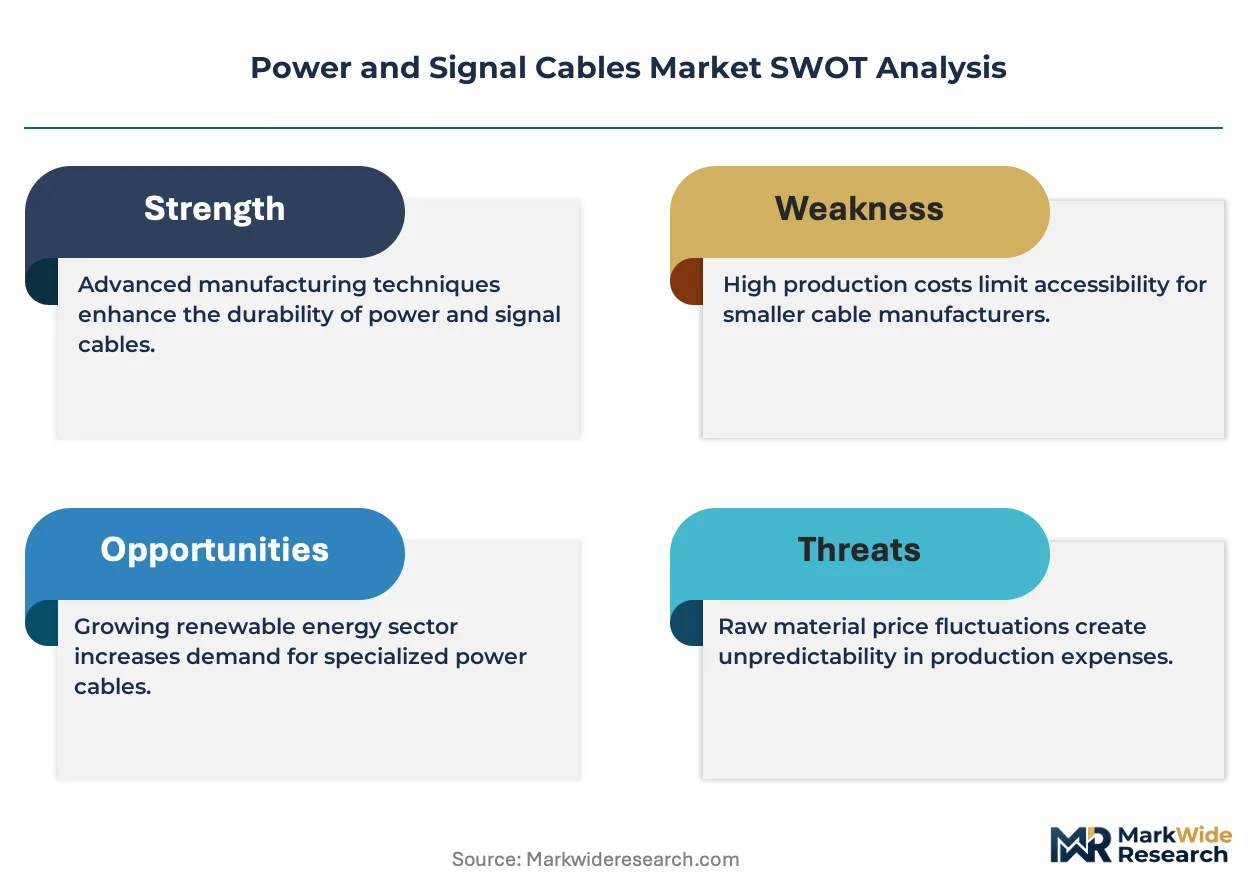
Offshore wind interconnection buildouts are forcing cable manufacturers to reconfigure production footprints around deep-water installation capabilities and high-voltage direct current expertise. This structural pivot concentrates investment in submarine cable facilities and specialized vessel access.
Growth Catalysts
- EU Green Deal fire-safety mandates:REACH restrictions on halogenated flame retardants are accelerating compound reformulation toward recyclable insulation systems.
- Data center power architecture:Hyperscale operators are deploying higher amperage trunking that favors structured signal path designs over copper-dense legacy layouts.
- Vietnam manufacturing zone electrification:Industrial park expansion across Southeast Asia is pulling medium-voltage distribution cable procurement.
Market Restraints
- Copper price volatility:LME copper swings compress margin predictability for conductor-heavy product lines.
- Submarine cable supply concentration:Installation vessel availability bottlenecks in North Sea and Baltic clusters limit project pacing.
- XLPE compound technical ceiling:Dielectric performance constraints at 500kV+ restrict ultra-high voltage cable yield rates.
Strategic Opportunities
- Indonesia urban grid densification:Jakarta and Surabaya metro rail electrification programs lack localized cable manufacturing capacity.
- Solar farm AC-DC hybrid bundles:Utility-scale photovoltaic installations require integrated power-signal cable systems.
- China dual carbon efficiency benchmarks:GB standards for conductor loss reduction create premium tier qualification pathways.
Industry Challenges
- Submarine cable installation engineer scarcity:Deep-water jointing and burial expertise pools concentrate among aging specialist crews.
- Multi-standard certification timelines:IEC, IEEE, and GB type-test sequencing extends product launch cycles.
- Legacy grid integration complexity:New HVDC links must interface with aging AC infrastructure without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power and Signal Cables Market |
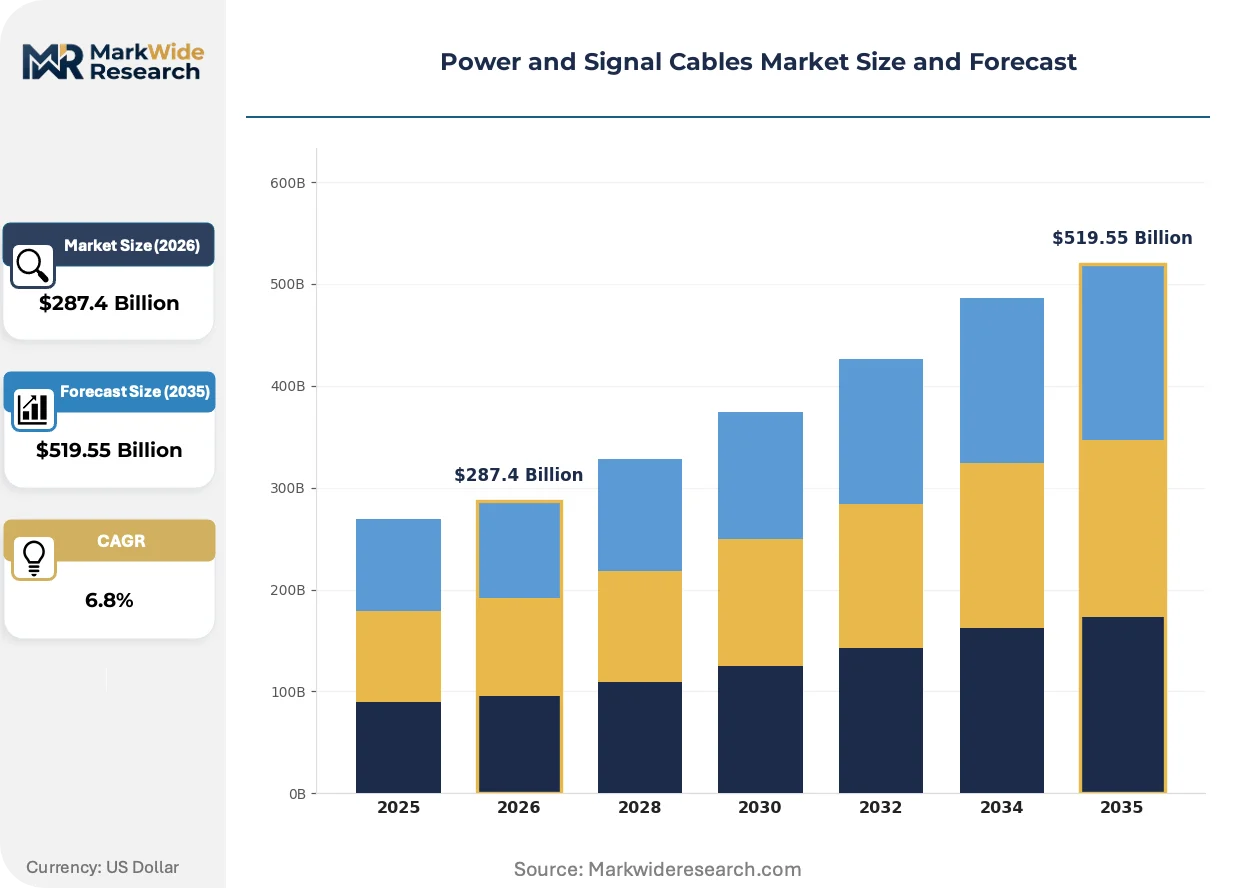
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $519.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage Cables, High Voltage Cables, Control Cables, Data Cables Installation Type: Indoor, Outdoor, Direct Burial, Aerial Application: Telecommunications, Industrial, Automotive, Residential Material: Copper, Aluminum, XLPE, PVC |
| Companies Covered | Prysmian Group, Nexans, Belden, Sumitomo Electric Industries, NKT, LS Cable & System, Southwire Company, Fujikura, General Cable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power and Signal Cables Market Strategic Shifts
Material science breakthroughs and procurement model compression are restructuring how cable specifications get written and who controls supplier relationships. Three forces dominate this transformation.
Aluminum alloy conductor formulations are rewriting transmission economics for renewable export corridors. Grid operators in Spain and Morocco are specifying AA-8030 series alloys for 400kV overhead lines to reduce weight-per-span and foundation costs. This substitution is compressing copper demand intensity in long-distance interconnection projects.
REACH SVHC candidate list expansion is forcing sheathing compound redesigns across European supply chains. ECHA scrutiny of medium-chain chlorinated paraffins is pushing manufacturers toward magnesium hydroxide-based alternatives. Low-smoke zero-halogen cable categories are capturing specification share in French and German public infrastructure tenders.
Utility procurement desks are consolidating vendor panels and unbundling installation services from material supply. State grid operators in China and regional utilities in Germany now separate cable procurement from jointing and commissioning contracts. This bifurcation is visible most acutely in offshore wind offtake agreements where developers retain installation risk.
Power and Signal Cables Market Segmentation
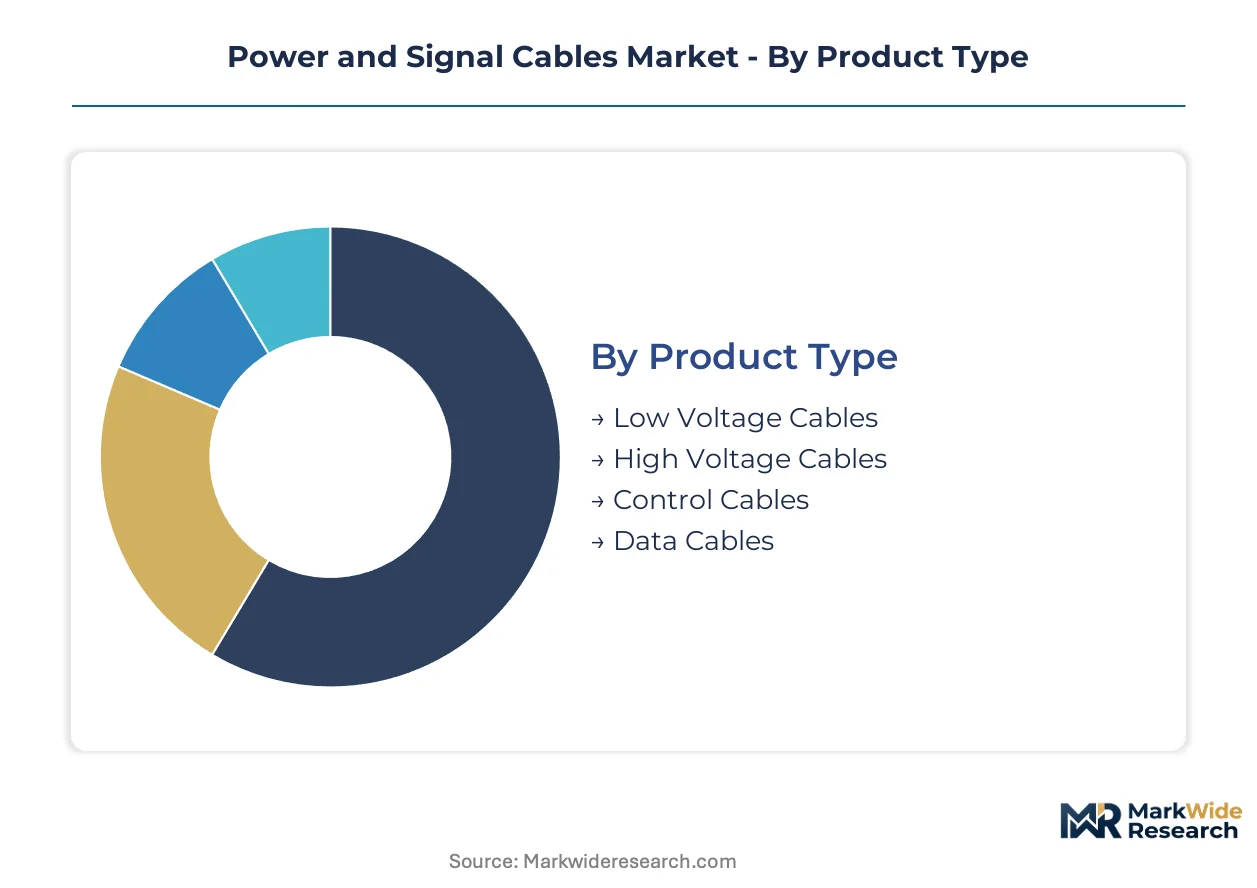
Cable segmentation determines procurement protocols across voltage classes and installation environments. Certification requirements vary sharply by product type and application, dictating supplier qualification pathways and tender eligibility.
Product Type:
Low voltage cables carry IEC 60502-1 certification burdens for residential and commercial distribution, while high voltage products face extended type-test sequences under IEC 60840 and GB/T 11017. Data cables must satisfy hybrid electromagnetic compatibility and transmission performance standards.
- Low Voltage Cables:Copper or aluminum conductors insulated with PVC or XLPE, rated up to 1kV for building distribution and appliance connection. Demand clusters in Vietnam's manufacturing zone electrification and Indonesia's urban grid densification as industrial park developers specify IEC-compliant armored variants for medium-density distribution.
- High Voltage Cables:XLPE-insulated extruded dielectric systems rated 66kV to 500kV for transmission backbone and renewable export corridors. Procurement concentrates in offshore wind interconnection projects across the North Sea and Baltic Sea where developers require submarine-qualified, factory-jointed lengths with HVDC compatibility.
- Control Cables:Multi-conductor flexible assemblies with screened pairs for instrumentation and automation signal transmission.
- Data Cables:Twisted-pair copper or fiber-optic cores with integrated power conductors for 5G backhaul and fiber-to-the-premises deployment.
Leading the category by volume: Low Voltage Cables. Growing fastest: Data Cables.
Installation Type:
Cost tiers separate buried and submarine installations from aerial and indoor routing, with labor intensity and specialized equipment requirements driving total project economics.
- Indoor:Halogen-free sheathed cables for commercial building risers and data center trunking, specified under EN 50575 CPR fire performance classes.
- Outdoor:UV-resistant polyethylene jackets for exposed tray and conduit runs in utility substations.
- Direct Burial:Armored steel-wire or corrugated aluminum sheathed cables for underground distribution networks in German municipal grid upgrades and Chinese smart city programs, requiring water-blocking compounds and radial moisture barriers.
- Aerial:Self-supporting or messenger-hung configurations for rural electrification and temporary construction power in Southeast Asian infrastructure corridors.
Dominating project value: Direct Burial. Steepest expansion trajectory: Indoor (data center density).
Application:
Customer type fragmentation splits procurement between utility capital programs, automotive OEM wire harness specifications, and hyperscale operator custom designs.
- Telecommunications:Hybrid fiber-copper bundles for 5G fronthaul and central office power-feed architectures, with Telcordia GR-20 and ITU-T G.652 compliance mandatory for carrier qualification.
- Industrial:Oil-resistant and torsion-flexible cables for robotics, mining, and petrochemical processing, specified under VDE 0250 and UL 1277 for European and North American heavy industry respectively.
- Automotive:Thin-wall copper conductors with cross-linked polyethylene insulation for electric vehicle high-voltage harnesses, facing ISO 6722 and LV 112 qualification timelines.
- Residential:PVC-insulated building wire for single-family and multi-unit construction, governed by national electrical codes with localized approval marks.
Highest volume concentration: Residential. Fastest specification change: Automotive (voltage class escalation).
Material:
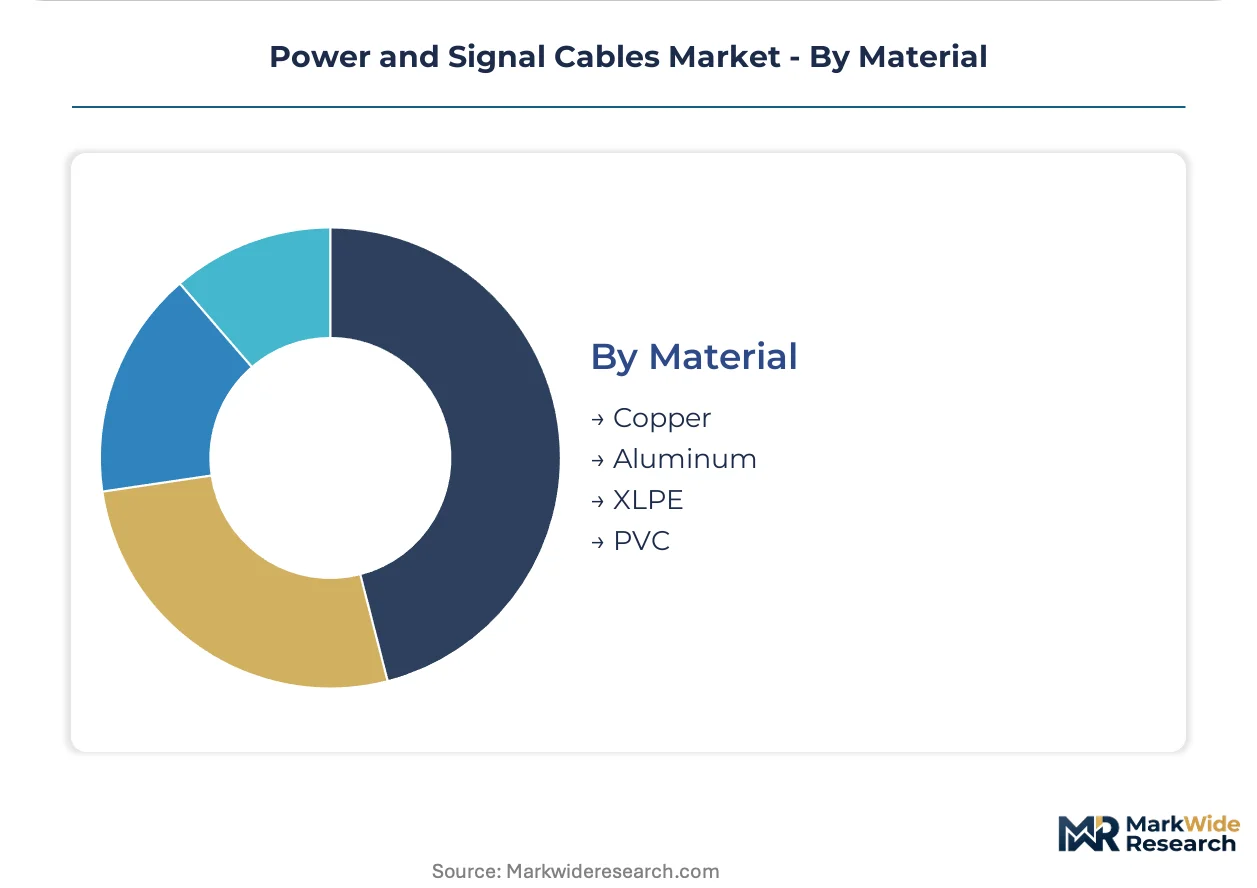
Supply concentration and price volatility differentiate conductor metals from insulation compounds, with aluminum substitution disrupting traditional copper economics in long-distance transmission.
- Copper:Primary conductor for low and medium voltage cables where conductivity and ductility justify premium pricing, though LME price swings compress margin predictability for OEM customers.
- Aluminum:AA-8030 and AA-8176 alloy conductors for 400kV overhead lines and large-gauge distribution, gaining share in Spanish and Moroccan renewable interconnection projects through weight-per-span advantages.
- XLPE:Cross-linked polyethylene insulation for medium and high voltage cables, with tree-retardant formulations extending service life in wet environments.
- PVC:Cost-compound sheathing and bedding layers facing REACH SVHC scrutiny on plasticizer and stabilizer chemistries.
Volume leadership: Copper. Fastest substitution pressure: Aluminum (transmission).
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial park electrification across Vietnam's northern economic zones and Indonesia's Batang industrial corridor is concentrating medium-voltage cable procurement. Special economic zones in Thailand's Eastern Economic Corridor and China's Yangtze River Delta anchor manufacturing capacity expansion.
China
Dual carbon targets and GB/T 11017 efficiency standards are accelerating conductor loss reduction in new transmission assets. The State Grid Corporation's ultra-high voltage corridor buildouts favor domestic manufacturers with integrated HVDC jointing capabilities. Jiangsu and Zhejiang provinces host the densest submarine cable production clusters serving offshore wind interconnection.
Germany
REACH SVHC restrictions on halogenated flame retardants are compelling sheathing compound reformulation across industrial supply chains. The country's national electrical regulator enforces EN 50575 fire performance classes for commercial building installations. North Rhine-Westphalia and Bavaria concentrate armored cable fabrication for municipal grid modernization programs.
United States
FERC interconnection queue reforms are streamlining transmission project approvals for renewable export corridors. The EPA oversees environmental compliance for cable manufacturing facilities under Clean Air Act provisions. Texas and California anchor data center power trunking demand as hyperscale operators deploy higher amperage infrastructure.
Vietnam
Industrial zone electrification in Bac Ninh and Hai Phong special economic zones is pulling medium-voltage distribution cable procurement. The country's national standards body enforces IEC 60502-1 compliance for building wire imports. Northern provinces concentrate manufacturing demand as electronics assembly clusters expand power distribution networks.
Indonesia
Jakarta and Surabaya metro rail electrification programs lack localized high-voltage cable manufacturing capacity. The national infrastructure regulator mandates SNI certification for public procurement tenders. Batang industrial corridor and Cikarang manufacturing zones are driving import dependency for armored distribution cables.
Power and Signal Cables Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The market structures around three tiers: integrated multinationals with submarine capabilities, regional champions focused on land-based transmission, and specialized data cable fabricators. Consolidation pressure concentrates in offshore wind interconnection where installation vessel access limits viable bidders. Strategic moves center on backward integration into conductor smelting and compound formulation to offset copper price volatility.
Among European-integrated cable groups, Prysmian Group and Nexans occupy positions exemplifying the multinational archetype with combined land and submarine capabilities. Sumitomo Electric Industries represents the Asia-Pacific specialist tier with integrated optical and power cable expertise. These three anchors illustrate how geographic footprint breadth and installation service bundling determine qualification for large-scale renewable interconnection tenders.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Belden |
| Sumitomo Electric Industries |
| NKT |
| LS Cable & System |
| Southwire Company |
| Fujikura |
| General Cable |
| Others |
Value Chain & Pricing Dynamics
Aluminum alloy conductor adoption for 400kV transmission corridors is compressing copper demand intensity while simultaneously redrawing supplier qualification tiers around metallurgical R&D capabilities and regional smelter access. This substitution dynamic concentrates pricing power among integrated producers with captive alloy formulation expertise and fragments margin pools for pure copper cable fabricators.
Pricing Analysis
Lead-time-driven pricing stratification separates premium tiers for submarine cable projects requiring factory-jointed HVDC lengths from spot-market discounts for standard low-voltage building wire inventory. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with IEC 60840-qualified submarine products commanding substantial premiums over IEC 60502-1 building wire. Price erosion runs through copper-intensive product lines as LME volatility compresses OEM margin predictability. Data center operators exhibit lowest price sensitivity due to reliability-critical procurement protocols, while residential construction distributors face acute cost compression pressure.
Supply Chain Analysis
Single-source vulnerability sits with submarine cable installation vessel operators concentrated in North Sea and Baltic Sea corridors, where specialized burial and jointing expertise pools among aging specialist crews. Geographic supply concentration centers on China for XLPE compound production and conductor smelting, Germany for armored cable fabrication serving EN 50575 fire performance mandates, and Vietnam for medium-voltage distribution assembly feeding Southeast Asian industrial zones. Raw material dependencies draw from Chilean copper cathode, Saudi petrochemical feedstock for polyethylene insulation, and Chinese rare earth elements for high-performance alloy additives. Tariff exposure on aluminum ingot imports threatens margin stability for European transmission cable producers. Distribution runs through utility procurement desks consolidating vendor panels and unbundling installation services from material supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power and signal cables are transitioning from copper-dense legacy designs toward aluminum alloy and hybrid fiber-copper architectures, with HVDC submarine expertise and data center trunking capabilities determining competitive survival.
For Market Incumbents: Deploy backward integration into conductor smelting to offset copper price volatility and secure alloy formulation IP. Prysmian Group and Nexans exemplify this model through captive XLPE compound production and submarine cable vessel fleets. Incumbents must defend against aluminum substitution threats in transmission corridors by anchoring premium positioning around HVDC jointing capabilities and installation service bundling. Certification investment in GB/T 11017 efficiency benchmarks and REACH-compliant sheathing compounds preserves tender eligibility for Chinese and European utility procurement. For New Entrants and Emerging Players: EPC contractors and industrial park developers in Indonesia's Batang corridor and Vietnam's Bac Ninh zone represent the most penetrable channel partner type for medium-voltage distribution cable qualification. New entrants should target Indonesia's localized manufacturing gap for armored cables serving Jakarta metro rail electrification, where SNI certification requirements have constrained import competition. A white-space opportunity exists in solar farm AC-DC hybrid bundles for utility-scale photovoltaic installations requiring integrated power-signal systems. Go-to-market positioning as a REACH-compliant specialty compound supplier to European cable fabricators bypasses capital-intensive submarine cable vessel requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated multinationals seeking HVDC submarine capabilities and Southeast Asian manufacturing footprints. Long-term viability favors targets with dual competence in optical fiber and power cable production, enabling 5G backhaul and fiber-to-the-premises hybrid bundles. Acquisition archetypes include regional champions with localized SNI or GB certification pathways and specialized data cable fabricators serving hyperscale operator custom designs. The signal to watch is FERC interconnection queue clearance rates for renewable export corridors, which dictate submarine cable procurement pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductor Smelting | Captive copper and aluminum supply secures margin stability against LME volatility. |
| Submarine Cable Vessel Fleet Expansion | Installation capacity access qualifies bidders for North Sea offshore wind tenders. |
| REACH-Compliant Compound Reformulation | Magnesium hydroxide sheathing alternatives preserve European utility procurement eligibility. |
| Data Center Trunking Certification | Higher amperage structured signal path qualification captures hyperscale operator demand. |
| Southeast Asian Manufacturing Footprint | Localized production in Vietnam and Thailand reduces logistics exposure for regional infrastructure clients. |
Study Parameters
Trade databases, utility procurement registries, and cable industry association filings formed the secondary backbone for demand quantification and supplier mapping. Primary interviews with submarine cable project engineers, utility procurement officers, EPC contractor material managers, and compound formulation specialists provided installation cost structures and qualification pathway validation. The analysis triangulated bottom-up project pipeline aggregation against top-down transmission investment forecasts.
Historical trendline analysis of voltage class migration and conductor material substitution informed the projection framework across the analysis window. Segmentation modeling incorporated product type, installation environment, application, and material composition dimensions. CAGRs derived from regression analysis of renewable interconnection buildouts, data center power architecture shifts, and industrial zone electrification programs. Forecast inputs included FERC interconnection queue depth, EU Green Deal implementation timelines, and China's dual carbon policy enforcement intensity.
Caveats apply where copper price volatility, submarine vessel availability bottlenecks, or multi-standard certification delays could materially shift the outlook. Forecasts reflect assumptions around REACH SVHC list expansion pace and GB efficiency benchmark adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Aluminium Battery Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
GCC Cable Accessories Market
Cables
USB Cable Market
Cables
Magnetic Charging Cable Market
Cables
XLPE Cables Market
Cables
Fiber Optic Cable Accessories Market
Cables
Global Low Voltage Cable Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
SATA Power Cable Market
Cables
Europe Cable Joints Market
Cables
Cable Market
Cables
Cable Drum Market
Cables
Wire and Cable Label Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Medium Voltage Cables Accessories Market