
 Battery Testing Market | 2026-2036
Battery Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Testing Market Insights
Aftermarket service revenue is narrowing as original equipment manufacturers internalize validation protocols for next-generation cells. Arbin Instruments leverages its high-precision cycling systems to sustain leadership in laboratory-grade equipment. Maccor anchors its position through deep specialization in custom test fixture design for pouch and cylindrical formats. Chroma ATE competes aggressively on power electronics integration, extending its reach into integrated battery management system validation.
Battery testing encompasses electrochemical characterization, thermal abuse simulation, and impedance spectroscopy performed under controlled environmental conditions to verify safety, performance, and longevity parameters. The practice serves to qualify cells and packs against IEC 62133 and UL 2054 before commercial deployment in mobility and stationary storage systems. Cycle life testing commands premium pricing due to extended duration protocols and specialized chamber requirements, while lithium-ion chemistry validation absorbs the dominant share of equipment utilization. Performance testing for sodium-ion cells is gaining equipment hours as manufacturers diversify chemistry portfolios beyond dominant lithium-ion architectures.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that force testing providers to expand lifecycle analysis capabilities. China's SAMR enforces GB/T standards for thermal propagation resistance that require upgraded abuse testing infrastructure. The FAA and NHTSA maintain distinct cell qualification pathways for aviation and automotive applications, fragmenting certification requirements across jurisdictions. Stakeholders must decide whether to build multi-standard testing platforms or specialize in single-jurisdiction compliance given diverging regulatory timelines.
Market Dynamics
Electric vehicle manufacturers are internalizing validation protocols as cell energy densities exceed 300 Wh/kg, forcing independent testing providers to retool for higher-voltage abuse chambers and faster cycle protocols.
Growth Catalysts
- EU Battery Regulation:Mandates for carbon footprint declarations and recycled content thresholds compel manufacturers to expand lifecycle analysis capabilities, creating sustained equipment demand.
- Sodium-ion chemistry diversification:Chinese cell producers are qualifying alternative chemistries beyond lithium-ion architectures, requiring new electrochemical characterization protocols and specialized test fixtures.
- Aviation qualification pathways:The FAA maintains distinct cell certification requirements for electric aircraft applications, fragmenting standards and multiplying testing volumes for dual-use suppliers.
Market Restraints
- Neodymium and cobalt price volatility:Rare earth magnet costs in thermal chamber circulation systems create margin compression for equipment manufacturers.
- Single-source dependency:German automotive testing corridors around Stuttgart and Munich concentrate demand, exposing providers to regional demand shocks.
- GB/T standard divergence:China's SAMR enforces thermal propagation resistance thresholds incompatible with IEC 62133, forcing redundant capital expenditure for multi-jurisdiction compliance.
Strategic Opportunities
- Stationary storage qualification:Grid-scale battery deployments in India lack mature testing infrastructure, creating first-mover advantage for providers establishing local facilities.
- Integrated BMS validation:Convergence of power electronics and battery management systems enables single-platform testing contracts with tier-one automotive suppliers.
- US Inflation Reduction Act:Domestic content bonuses for battery manufacturing incentivize North American testing capacity expansion near cell production sites.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in impedance spectroscopy interpretation commands premium compensation, constraining laboratory expansion timelines.
- Abuse chamber capex intensity:Arc flash containment and gas suppression systems for thermal runaway simulation require seven-figure capital commitments per installation.
- Multi-standard certification lag:Simultaneous UL 2054 and GB/T qualification extends product launch timelines by 8-14 months for cell manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Testing Market |
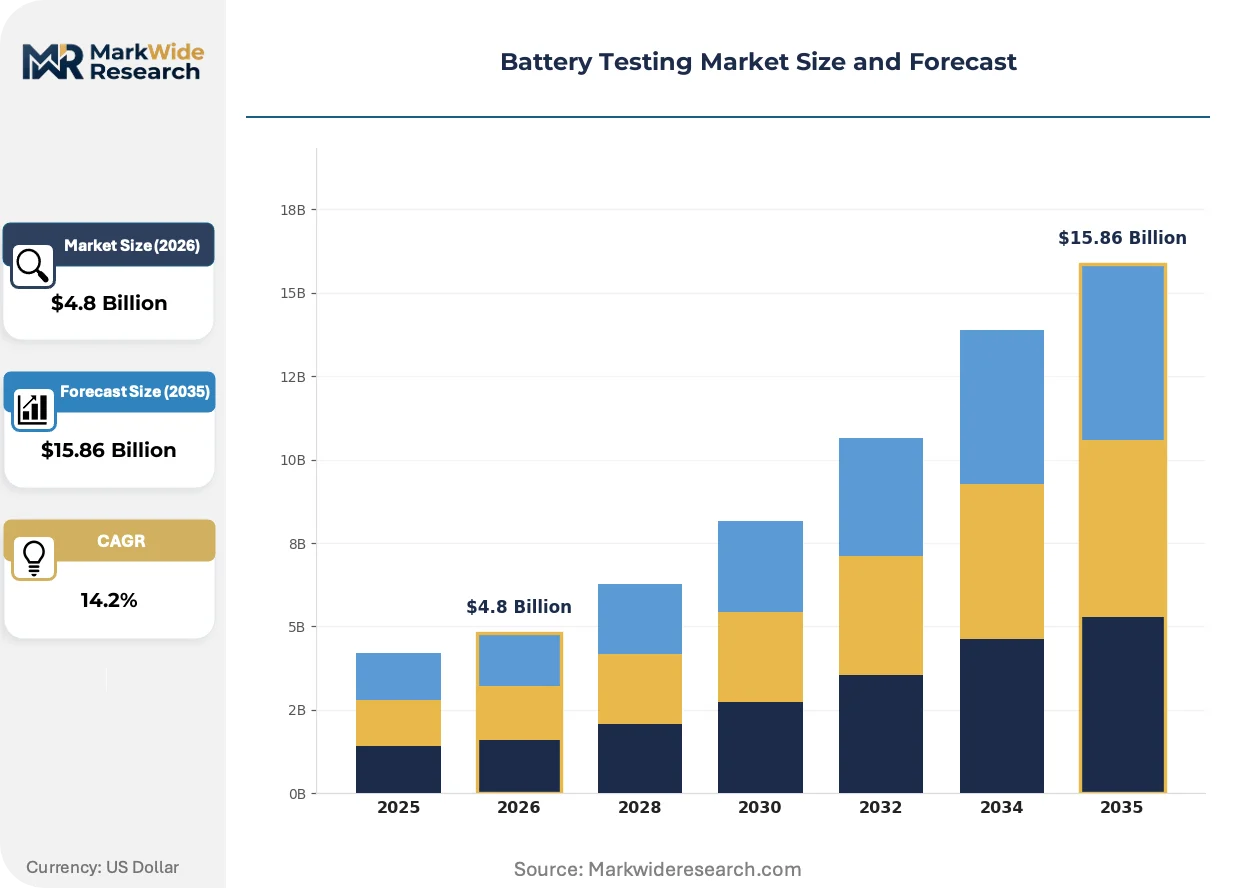
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Charge Testing, Discharge Testing, Cycle Life Testing, Performance Testing Battery Chemistry: Lithium-ion, Nickel-metal Hydride, Lead-acid, Sodium-ion End User: Automotive Manufacturers, Consumer Electronics, Renewable Energy, Aerospace Testing Standard: IEC 62133, UL 2054, ISO 9001, IEEE 1725 |
| Companies Covered | Arbin Instruments, Maccor, Chroma ATE, Neware Technology, Bitrode, DIGATRON, Midtronics, National Instruments, Ametek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Testing Market Trends and Innovations
Artificial intelligence is compressing test interpretation cycles while solid-state cell architectures demand entirely new abuse protocols, reshaping equipment specifications and service delivery models simultaneously.
Digital twin platforms are digitizing battery degradation modeling by simulating electrochemical performance across temperature and load profiles without physical cycling. Tier-one automotive suppliers in Germany are deploying these systems for pre-qualification screening, reducing physical test volumes by half for initial cell downselection. This compression is forcing traditional equipment vendors to bundle software subscriptions with hardware sales.
The EU Battery Regulation's digital passport requirements are mandating blockchain-traceable test records for every cell sold in European markets. Industrial consequence includes mandatory third-party audit trails for cycle life data, eliminating self-certified manufacturer claims. Pouch cell producers targeting electric bus contracts face the steepest compliance burden due to extended warranty documentation requirements.
Automotive OEMs are consolidating validation contracts with full-service testing houses rather than distributing across specialized boutiques. Tier-one suppliers in Japan and South Korea now prefer single-source accountability covering electrochemical, thermal, and system-level validation. This concentration is most visible in South Korea's battery cluster, where LG Energy Solution and Samsung SDI have reduced qualified vendor lists from twelve to four providers since 2023.
Battery Testing Market Segmentation
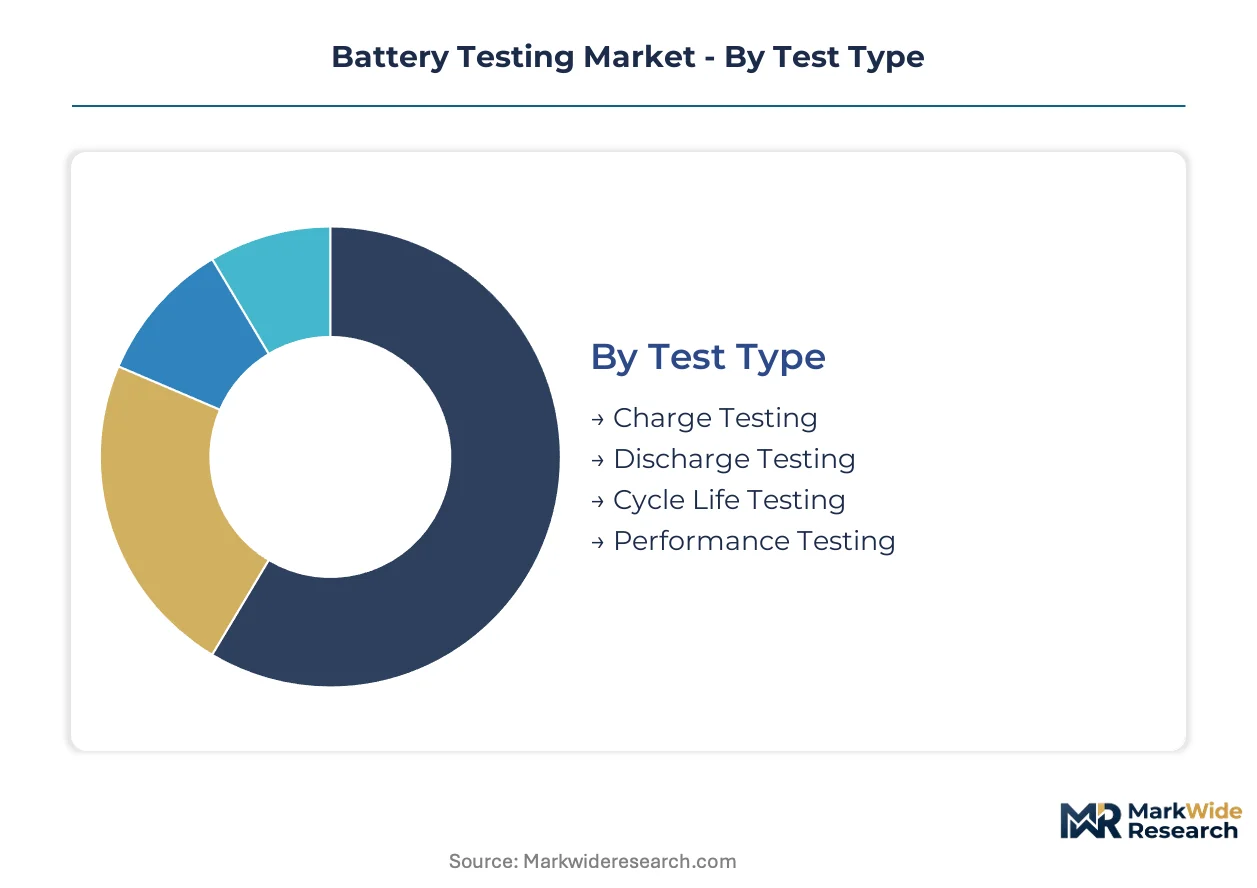
Segmentation in battery testing reveals how equipment utilization and service pricing diverge across technical protocols, chemistry platforms, and regulatory jurisdictions. Understanding these fault lines enables providers to allocate capital toward chambers and competencies commanding premium utilization rates.
Test Type:
Mature protocols dominate equipment hours while emerging methodologies reshape capacity planning.
- Cycle Life Testing:Extended-duration protocols simulating thousands of charge-discharge cycles under controlled temperature and current profiles. German automotive corridors around Stuttgart absorb the majority of chamber capacity as OEMs validate 10-year warranty claims for electric vehicle packs.
- Performance Testing:Characterization of energy density, power delivery, and efficiency across operational envelopes. Sodium-ion qualification programs at Chinese cell producers are expanding equipment hours faster than any other test category as manufacturers diversify beyond lithium-ion architectures.
- Charge Testing:Verification of charging efficiency, heat generation, and protocol compatibility.
- Discharge Testing:Assessment of capacity retention and voltage stability under load conditions.
Cycle Life Testing handles the majority of throughput; Performance Testing is the fastest mover on share.
Battery Chemistry:
Cost tiers separate mass-market validation from specialized qualification programs.
- Lithium-ion:Dominant chemistry requiring comprehensive electrochemical, thermal abuse, and impedance spectroscopy protocols. NMC and LFP variants each demand distinct cycling parameters, with European OEMs driving premium pricing for high-nickel cell validation under EU Battery Regulation carbon footprint rules.
- Sodium-ion:Alternative chemistry gaining commercial traction as Chinese manufacturers scale production. Test fixture redesigns accommodate different voltage plateaus and thermal profiles, with early adopters securing first-mover pricing power before standardization commoditizes the segment.
- Nickel-metal Hydride:Mature chemistry with declining but stable demand from hybrid vehicle programs.
- Lead-acid:Established chemistry serving stationary backup and automotive starter applications with standardized, lower-margin test protocols.
Lithium-ion commands the deepest investment in multi-standard chambers; Sodium-ion is expanding most quickly as qualification volumes accelerate.
End User:
Application-specific requirements fragment equipment specifications and contract structures.
- Automotive Manufacturers:Most demanding customer segment requiring integrated electrochemical, thermal, and system-level validation. Tier-one suppliers in South Korea's battery cluster have consolidated vendor lists from twelve to four providers since 2023, concentrating contract value with full-service testing houses.
- Renewable Energy:Grid-scale storage deployments in India lack mature local infrastructure, creating first-mover opportunities for providers establishing regional facilities. Extended cycle protocols for 20-year asset life dominate procurement specifications.
- Consumer Electronics:High-volume, lower-margin segment with standardized IEC 62133 qualification pathways.
- Aerospace:FAA maintains distinct certification requirements for electric aircraft applications, fragmenting standards and multiplying testing volumes for dual-use suppliers.
Automotive Manufacturers represent the largest contract value concentration; Renewable Energy is climbing the fastest on infrastructure investment.
Testing Standard:
Regulatory geography determines capital allocation for multi-jurisdiction compliance.
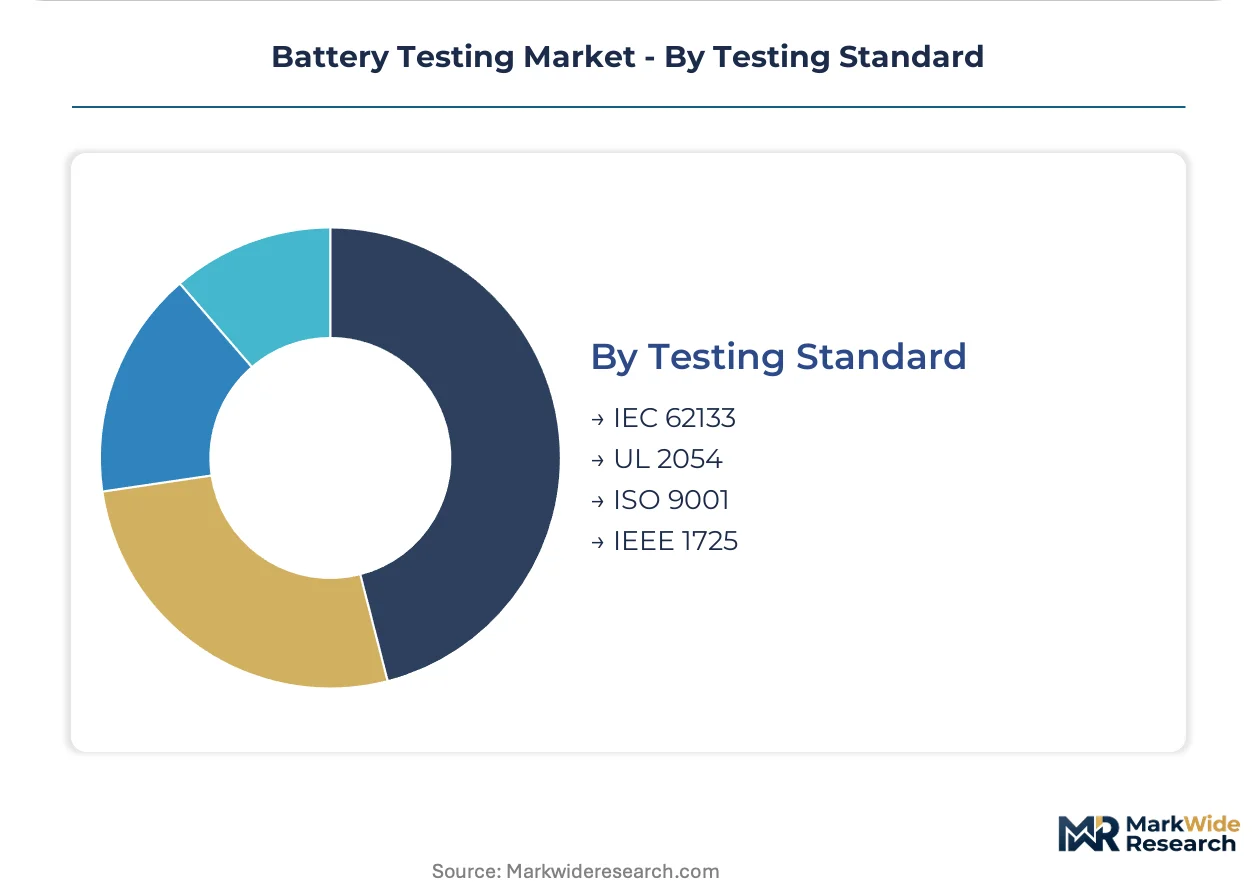
- IEC 62133:International baseline for portable and industrial cell safety. European testing houses bundle this with EU Battery Regulation lifecycle analysis requirements, creating bundled service offerings.
- UL 2054:North American safety standard for household and commercial batteries. US Inflation Reduction Act domestic content bonuses incentivize North American testing capacity expansion near cell production sites.
- ISO 9001:Quality management system certification applied to testing laboratory operations rather than cell-specific protocols.
- IEEE 1725:Rechargeable battery standard for cellular telephone applications with specialized thermal and electrical abuse requirements.
IEC 62133 anchors the most cross-referenced qualification pathways; UL 2054 is gaining share fastest on North American manufacturing reshoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes battery testing equipment at scale for manufacturing qualification, while Germany and the United States concentrate demand around automotive validation and regulatory compliance respectively. This consumption-mix differential shapes equipment specifications and service delivery models across geographies.
China
Sodium-ion cell qualification programs at CATL and BYD are absorbing chamber capacity faster than any other chemistry segment. SAMR enforces GB/T thermal propagation standards that require upgraded abuse testing infrastructure incompatible with IEC protocols. The Yangtze River Delta around Shanghai hosts the densest concentration of test fixture manufacturers serving domestic cell producers.
Germany
Ten-year warranty validation for electric vehicle packs drives premium pricing for cycle life protocols. The EU Battery Regulation mandates carbon footprint declarations that force testing houses to expand lifecycle analysis capabilities. Stuttgart and Munich anchor Europe's automotive testing corridor, with OEMs consolidating vendor lists from twelve to four full-service providers since 2023.
United States
The FAA maintains distinct certification requirements for electric aircraft applications, fragmenting standards and multiplying testing volumes for dual-use suppliers. The Inflation Reduction Act's domestic content bonuses incentivize North American testing capacity expansion near cell production sites. Michigan and Ohio are attracting validation facility investments from tier-one automotive suppliers.
South Korea
LG Energy Solution and Samsung SDI have reduced qualified testing vendor lists from twelve to four providers, concentrating contract value with full-service houses. MFDS-aligned standards for stationary storage create additional qualification pathways beyond automotive protocols. The Seoul Capital Area hosts the densest cluster of integrated electrochemical and thermal validation facilities.
India
Grid-scale battery deployments lack mature local testing infrastructure, creating first-mover advantage for providers establishing regional facilities. BIS is developing indigenous standards for lithium-ion cell safety that will diverge from IEC 62133 baselines. Maharashtra and Gujarat are attracting initial investments from European testing houses seeking early positioning.
Battery Testing Market Competitive Landscape
Capability concentration sits with laboratory-grade specialists; scale advantage sits with power electronics integrators. The market structures around three tiers: precision cycling equipment vendors, custom fixture designers, and integrated system providers. Two strategic archetypes dominate competitive positioning: high-precision specialists defending margin through technical differentiation, and platform players capturing volume through bundled hardware-software offerings. M&A activity concentrates on acquiring impedance spectroscopy expertise, while capacity expansion targets multi-standard chambers for simultaneous UL and GB/T qualification.
Among precision cycling specialists, Arbin Instruments and Maccor occupy positions at the laboratory-grade tier, with the former representing high-precision system capabilities and the latter exemplifying deep specialization in custom test fixture architectures. Chroma ATE anchors the power electronics integration archetype, competing on converged battery management system validation platforms. These three companies collectively span the capability spectrum from discrete cell characterization through integrated pack-level testing, with each representing a distinct strategic vector in equipment specification and service delivery.
| Leading Market Players |
|---|
| Arbin Instruments |
| Maccor |
| Chroma ATE |
| Neware Technology |
| Bitrode |
| DIGATRON |
| Midtronics |
| National Instruments |
| Ametek |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's automotive testing corridor concentrates high-precision cycling chamber capacity, concentrating pricing power with full-service validation houses that bundle electrochemical, thermal, and system-level protocols for German OEMs qualifying ten-year warranty claims.
Pricing Analysis
Long-term offtake contracts dominate the automotive segment, with tier-one suppliers locking multi-year validation agreements at fixed rates. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62133-plus-EU Battery Regulation bundled services from basic safety certification and commodity cycle-life protocols. Cost compression in standard-tier chamber hours is intensifying because Chinese equipment vendors are exporting competitive cycling systems. Consumer electronics manufacturers exhibit highest price sensitivity, while aviation qualification programs show lowest sensitivity due to FAA-mandated redundancy requirements.
Supply Chain Analysis
Export-control regimes on high-precision current sourcing electronics limit flows from US and German component suppliers to Chinese chamber manufacturers. Equipment assembly concentrates in China, Germany, and South Korea, with the Yangtze River Delta hosting densest test fixture manufacturing clusters. Raw material dependencies include neodymium for thermal chamber circulation systems, high-purity copper for current collectors, and specialized ceramics for arc flash containment. Single-source vulnerability in precision current measurement modules creates supply risk. Distribution runs through direct OEM sales teams for automotive accounts and regional distributor networks for laboratory equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery testing is shifting toward platform economics as digital twin software bundles with hardware sales, creating interoperability standards that favor integrated system providers over discrete equipment vendors.
For Market Incumbents: Build switching-cost moats through embedded software subscriptions that digitize degradation modeling and pre-qualification screening. Arbin Instruments and Maccor should deepen backward integration into custom test fixture production to defend margin position against Chroma ATE's power electronics convergence. Threat from AI-compressed test interpretation cycles demands counter-investment in proprietary impedance spectroscopy databases. For New Entrants and Emerging Players: Pursue white-space opportunities in India's grid-scale storage qualification infrastructure, where BIS standards development creates first-mover positioning ahead of IEC 62133 divergence. Target sodium-ion electrochemical characterization as the fastest-expanding test category with limited established protocol standardization. Go-to-market angle should emphasize rapid GB/T certification turnaround for Chinese cell producers seeking dual-standard qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-service testing houses with integrated BMS validation platforms, suggesting superior cash flow quality versus discrete equipment vendors. Long-term viability favors providers with multi-standard chamber assets spanning UL 2054, IEC 62133, and GB/T protocols. Acquisition target archetype: impedance spectroscopy specialists with FAA aviation qualification credentials. Signal to watch is consolidation velocity in South Korea's battery cluster, where vendor lists have compressed from twelve to four providers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Chamber Investment | Simultaneous UL 2054 and GB/T qualification capability captures dual-jurisdiction contract flow from CATL and BYD expansion. |
| Digital Twin Platform Integration | Software bundling with hardware sales responds to German OEM deployment of pre-qualification screening systems. |
| Aviation Certification Pathway Development | FAA-distinct requirements for electric aircraft create premium pricing tier inaccessible to standard automotive-focused competitors. |
| India Regional Facility Establishment | Grid-scale storage deployments in Maharashtra and Gujarat lack mature local infrastructure for lifecycle analysis. |
| Impedance Spectroscopy Expertise Acquisition | Talent scarcity in electrochemical engineering interpretation commands premium compensation and constrains laboratory expansion. |
Research Methodology
Cross-validation between primary interviews with validation laboratory directors, OEM platform engineers, and thermal chamber procurement managers anchors the qualitative findings against secondary sources including SEC filings from listed equipment vendors, SAMR GB/T standard drafts, and EU Battery Regulation implementation guidance. Bottom-up triangulation aggregates equipment shipment data by chemistry segment and test protocol, while top-down verification cross-checks against automotive production forecasts and stationary storage deployment pipelines.
Calibration against historical capacity utilization rates at Stuttgart and Munich testing corridors informs the projection framework across the analysis window. Segmentation dimensions modeled include battery chemistry platform, test type protocol, end-user application, and regulatory jurisdiction cluster. CAGRs derive from slope analysis of equipment demand curves against cell production capacity announcements. Industry-specific inputs incorporate sodium-ion qualification program timelines and FAA electric aircraft certification pathway development.
Macroeconomic conditions sit as an overlay; deviation in rare earth magnet pricing and German automotive capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions on regulatory timeline adherence and standard harmonization velocity. Material shifts in GB/T-IEC protocol divergence or solid-state cell commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
Metrology and Inspection Equipment Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Scratch Testers Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Inline Metrology Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market