
 Mineral Insulated (MI) Cable Market | 2026-2036
Mineral Insulated (MI) Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Insulated (MI) Cable Market Analysis
Aftermarket service revenue for MI cable system inspection and replacement is rewriting how suppliers capture lifetime value from industrial accounts. KME leverages its integrated copper smelting and cable drawing operations to control raw material costs across European utility projects. Watlow anchors its position through specialized mineral insulated thermocouple cable for precision temperature sensing in semiconductor fabrication. Emerson competes by extending its automation platform compatibility into MI cable termination and junction hardware.
Mineral insulated cable consists of copper conductors embedded within a compressed magnesium oxide insulation and sheathed in a seamless metal tube, typically copper or stainless steel, providing fire resistance beyond 1000°C and immunity to moisture, chemicals, and radiation. Its primary purpose is to maintain circuit integrity during catastrophic fire events in critical infrastructure. Fire resistant product types dominate specification sheets for building safety codes, while flexible MI cable segments capture faster growth in robotic welding and moving equipment applications. Oil and gas application demand concentrates on offshore platform power and heat tracing, where salt corrosion and explosion risks exclude conventional polymer-insulated alternatives.
BS 6387 and IEC 60331 cable fire survival standards shape product certification requirements across European building and infrastructure projects, while NFPA 70 National Electrical Code articles govern MI cable installation methods in US commercial and industrial construction. The EU Construction Products Regulation's CPR classification system is tightening fire performance labeling, pushing manufacturers toward third-party testing investments. Stakeholders must monitor how evolving fire safety codes in emerging industrial clusters affect specification thresholds and testing cost structures.
Market Dynamics
Fire safety code harmonization across industrialized economies is compressing specification timelines and forcing manufacturers to maintain parallel certification portfolios for BS 6387, IEC 60331, and NFPA 70 compliance.
Growth Catalysts
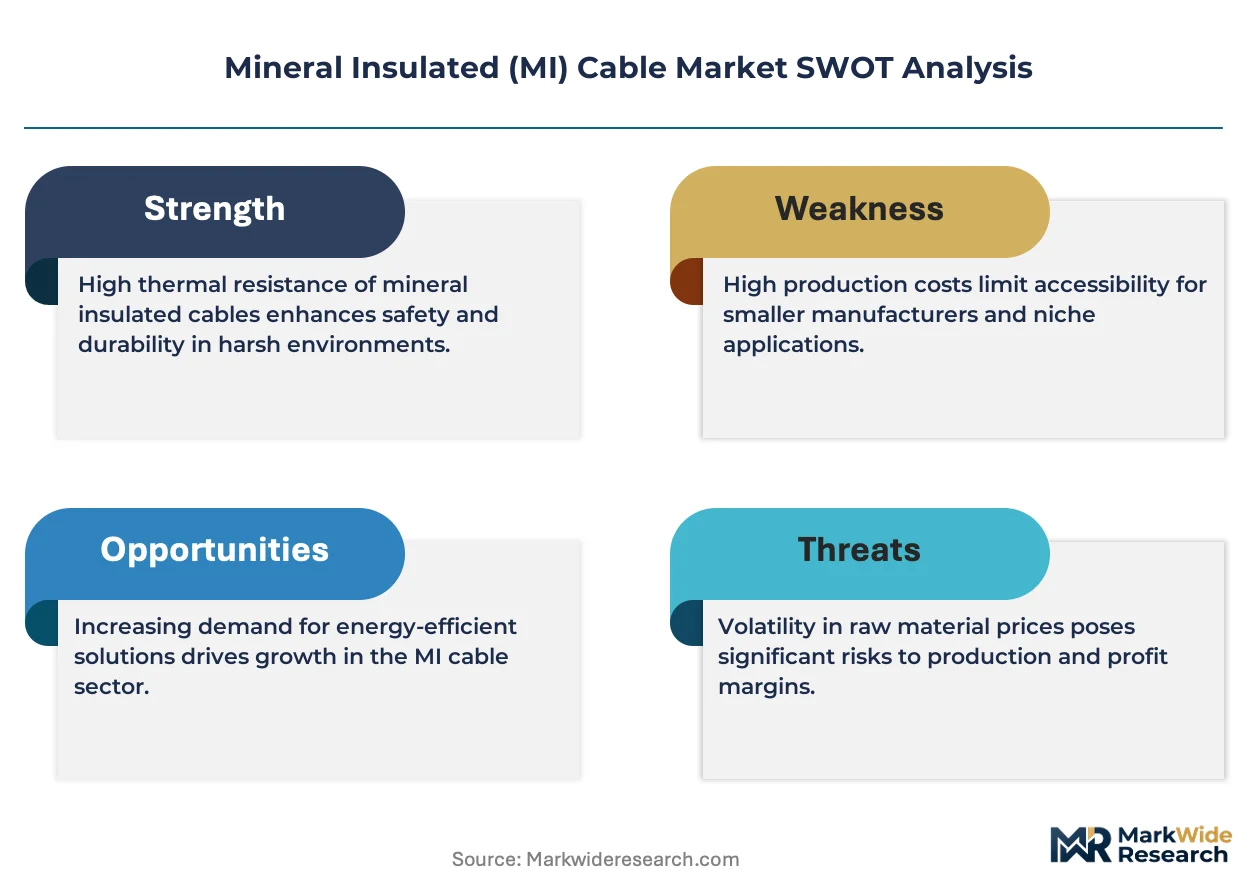
- EU Green Deal building renovation mandates:Commercial infrastructure retrofit programs across member states are mandating fire-resistant wiring upgrades, creating specification pull for MI cable in hospitals, data centers, and transit hubs.
- Nuclear plant instrumentation cable replacement cycles:Aging reactor fleets in France, the United States, and South Korea are entering scheduled cable renewal windows, with MI cable specified for radiation-hardened sensor circuits.
- Semiconductor fabrication expansion:Precision temperature sensing requirements in EUV lithography and wafer processing equipment are accelerating demand for mineral insulated thermocouple cable with sub-degree accuracy.
Market Restraints
- Copper price volatility:Raw material cost swings in London Metal Exchange copper contracts compress margin predictability for cable manufacturers lacking smelter integration.
- Specialized installation labor scarcity:MI cable termination requires certified technicians trained in magnesium oxide handling and compression sealing, creating project timeline risk in understaffed construction markets.
- Polymer-insulated fire-resistant cable substitution:Advances in mica tape and silicone-based alternatives are capturing specification share in lower-temperature commercial building applications.
Strategic Opportunities
- Offshore wind farm inter-array cabling:North Sea and Baltic Sea projects are specifying MI cable for nacelle fire protection and subsea junction box integrity where salt corrosion excludes standard insulation.
- Robotic welding equipment integration:Flexible MI cable variants are penetrating automotive manufacturing lines in Germany and Japan, replacing festooned power cables subject to flex fatigue failure.
- EU Construction Products Regulation Class A labeling:Tightened CPR fire performance classifications are pushing building specifiers toward third-party certified MI cable for liability protection.
Industry Challenges
- Multi-standard testing backlog:Parallel BS 6387, IEC 60331, and NFPA 70 certification requirements extend product launch timelines and multiply laboratory coordination costs.
- Legacy control system integration:MI cable termination hardware must interface with decades-old junction box standards, forcing custom adapter engineering for plant retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Insulated (MI) Cable Market |
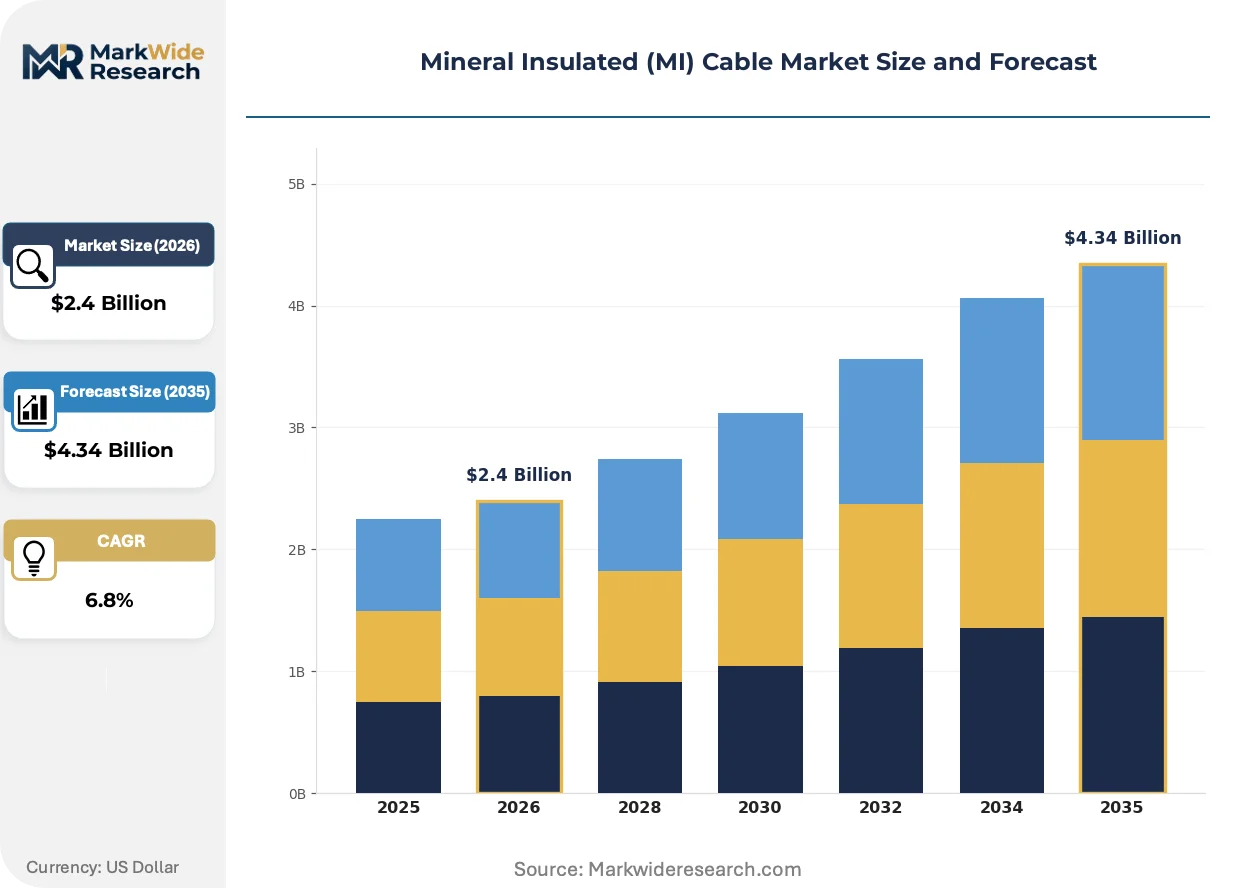
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Resistant, Flexible, Rigid, Specialty Application: Power Generation, Oil & Gas, Marine, Industrial Installation: Indoor, Outdoor, Underground, Above Ground End User: Utilities, Manufacturers, Contractors, Transport |
| Companies Covered | KME, Baosheng, Raychem HTS, Conax Technologies, M.I. Cable Technologies, Inc., Emerson, TEC, Watlow, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Insulated (MI) Cable Market Emerging Trajectories
Distributed sensing architectures and predictive maintenance platforms are digitizing how MI cable systems are monitored, shifting value capture from hardware sales toward lifetime performance contracts.
Smart MI cable with embedded fiber optic temperature monitoring is digitizing circuit integrity verification in real time. Offshore oil platform operators in the North Sea are piloting these systems for heat tracing fault anticipation. The technology is digitizing maintenance scheduling from calendar-based to condition-based intervals, compressing unplanned downtime costs.
REACH restrictions on halogenated flame retardants are accelerating magnesium oxide insulation preference in EU industrial projects. The regulation is pushing cable specifiers toward inorganic insulation systems with pre-existing toxicity clearance. German chemical processing facilities are responding fastest, embedding MI cable into plant safety system upgrade tenders.
Buyers are consolidating procurement around integrated fire safety system vendors rather than component-level cable sourcing. European engineering-procurement-construction firms are bundling MI cable specification into turnkey fire protection contracts, marginalizing standalone distributors. This concentration is most visible in French nuclear maintenance consortia, where single-source accountability is displacing multi-vendor cable sourcing.
Mineral Insulated (MI) Cable Market Segmentation
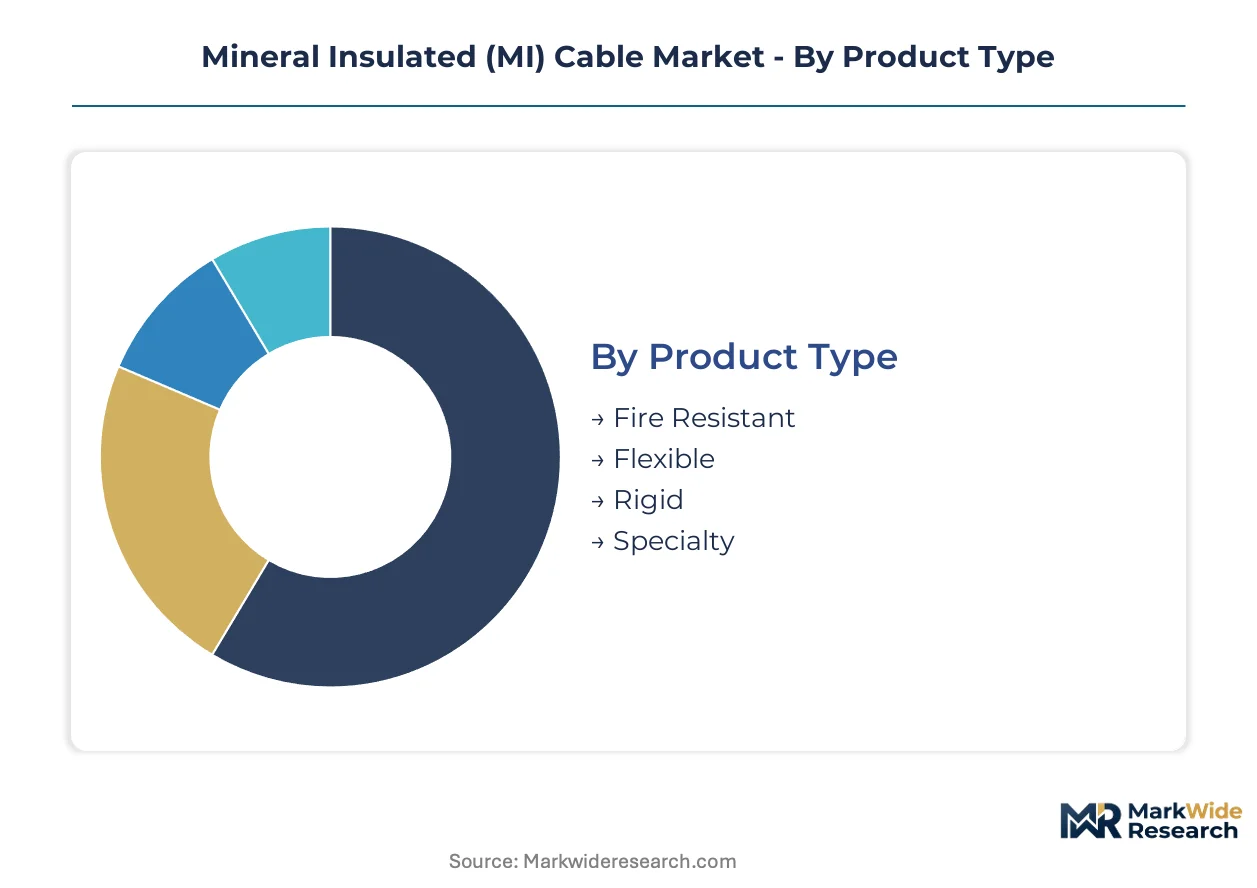
MI cable specification diverges sharply across fire safety mandates, mechanical flexibility needs, and environmental exposure conditions. Procurement patterns cluster around four distinct category systems that shape vendor positioning and certification investments.
Product Type:
Fire resistance ratings and mechanical flexibility requirements span a spectrum from fixed infrastructure to dynamic equipment integration.
- Fire Resistant:Compressed magnesium oxide insulation within seamless copper or stainless steel sheathing maintains circuit integrity beyond 1000°C. European hospital and data center retrofit programs under EU Green Deal mandates are concentrating procurement volumes here, though polymer-insulated alternatives are capturing lower-temperature commercial specifications.
- Flexible:Stranded conductor variants with reduced-diameter sheathing accommodate robotic welding equipment and moving machinery without flex fatigue failure. German automotive manufacturing lines are accelerating adoption fastest as festooned power cable replacements.
- Rigid:Solid conductor construction with heavy-wall metal sheathing for fixed installations in nuclear containment and chemical processing environments where mechanical protection outweighs flexibility needs.
- Specialty:Custom-engineered configurations including multi-pair instrumentation and radiation-hardened variants for reactor sensor circuits and semiconductor fabrication thermocouple applications.
Established volume favors Fire Resistant; emerging adoption favors Flexible.
Application:
End-use environments impose distinct corrosion, temperature, and regulatory compliance requirements that filter product specification.
- Power Generation:Nuclear plant instrumentation cable replacement cycles in France, the United States, and South Korea are driving radiation-hardened MI cable procurement for safety-critical sensor circuits. REACH restrictions on halogenated flame retardants are accelerating magnesium oxide preference over polymer alternatives in EU installations.
- Oil & Gas:Offshore platform power distribution and heat tracing applications specify MI cable for salt corrosion immunity and explosion risk mitigation where standard insulation fails. North Sea operators are piloting fiber optic-embedded smart variants for predictive maintenance.
- Marine:Shipboard emergency power and engine room wiring requiring Lloyd's Register and DNV certification for fire survival in salt-laden atmospheres.
- Industrial:Steelmaking and chemical processing facilities in Germany's industrial corridor drive specialty high-temperature instrumentation cable volumes.
Power Generation concentrates procurement scale; Oil & Gas commands premium pricing for subsea and offshore specifications.
Installation:
Environmental exposure determines sheathing material selection and sealing complexity across fixed and transient routing configurations.
- Indoor:Controlled-environment commercial and industrial building wiring where BS 6387 and IEC 60331 fire survival certification governs specification. EU Construction Products Regulation Class A labeling is tightening third-party testing requirements.
- Outdoor:Weather-exposed infrastructure requiring UV-stable metal sheathing and enhanced moisture sealing for substation and transit hub applications.
- Underground:Direct-buried utility tunnel and subway system installations where magnesium oxide moisture immunity eliminates the need for supplementary water-blocking tapes.
- Above Ground:Exposed conduit and cable tray routing in process plants where mechanical damage risk dictates rigid sheathing selection.
Indoor specifications dominate tender volumes; Underground commands specialized engineering for moisture-sealed terminations.
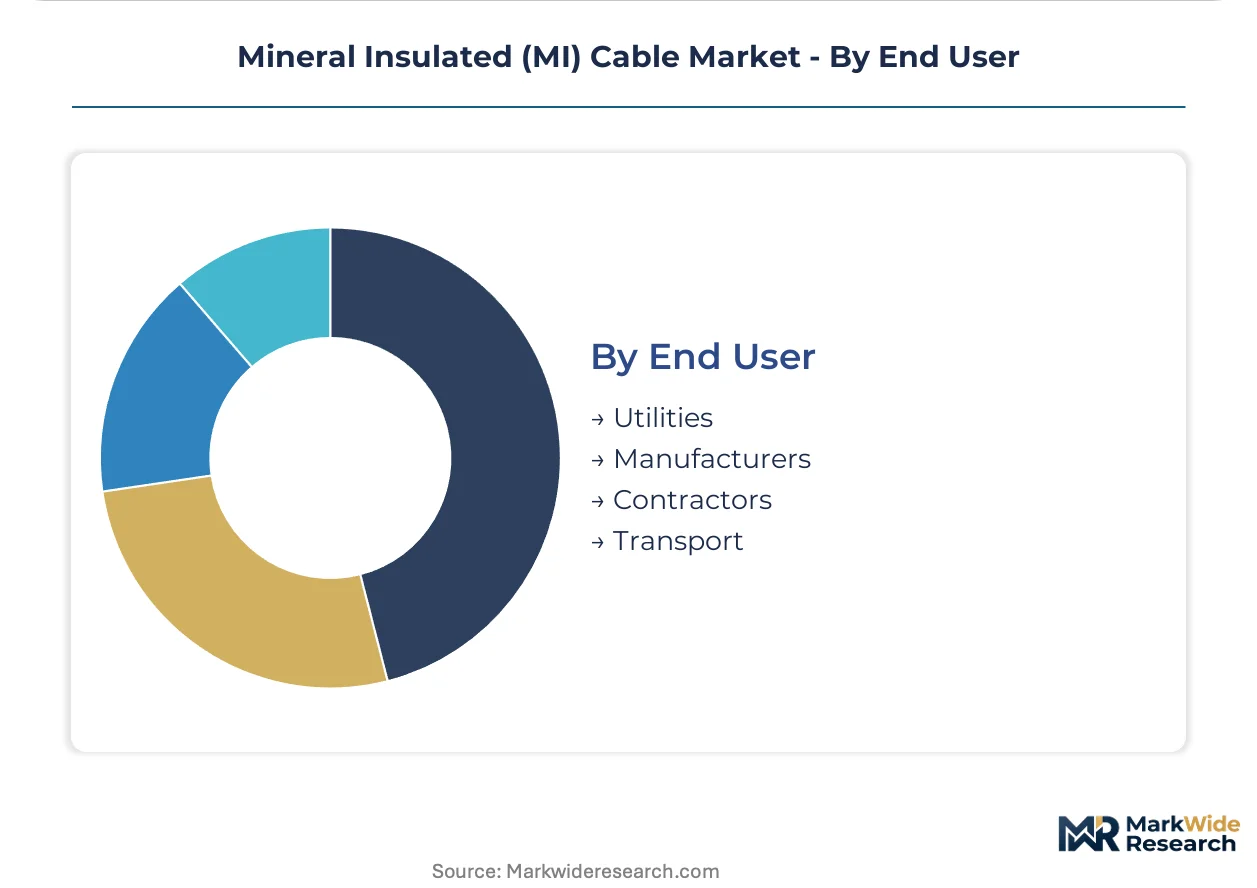
End User:
Procurement authority and technical specification control vary across asset ownership models and contracting structures.
- Utilities:Nuclear and conventional power plant owner-operators with direct cable specification authority and long-term replacement cycle planning. French maintenance consortia are consolidating procurement around integrated fire safety system vendors.
- Manufacturers:OEM equipment builders integrating MI cable into semiconductor fabrication tools, robotic welding systems, and industrial heating equipment where precision thermocouple accuracy is specified.
- Contractors:Engineering-procurement-construction firms bundling cable specification into turnkey fire protection contracts, marginalizing standalone distributors.
- Transport:Railway and airport infrastructure operators mandating fire-resistant wiring for tunnel emergency systems and terminal building safety circuits.
Utilities anchor long-term contract value; Manufacturers drive flexible variant specification for equipment integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MI cable consumption patterns diverge sharply across geographies: European procurement centers on fire safety retrofit mandates, while Asian demand concentrates on semiconductor fabrication expansion and nuclear instrumentation replacement cycles.
United States
Nuclear plant cable replacement programs at aging reactor sites in Illinois and South Carolina are accelerating radiation-hardened MI cable procurement. NFPA 70 National Electrical Code articles govern installation methods in commercial construction. Houston's petrochemical corridor drives offshore platform heat tracing specifications where salt corrosion immunity is mandatory.
Germany
Steelmaking facilities in Duisburg and chemical processing plants in Ludwigshafen anchor specialty high-temperature instrumentation demand. REACH restrictions on halogenated flame retardants are accelerating magnesium oxide preference over polymer alternatives. Bavaria's automotive manufacturing lines are adopting flexible MI variants for robotic welding integration.
France
Aging nuclear fleets at Flamanville and Gravelines are entering scheduled instrumentation cable renewal windows. EU Green Deal building renovation targets are mandating fire-resistant wiring upgrades in Paris hospital and data center retrofits. French nuclear maintenance consortia are consolidating procurement around integrated fire safety system vendors.
China
Semiconductor fabrication expansion in Shanghai and Hefei is accelerating demand for precision thermocouple cable with sub-degree accuracy. GB standards and dual carbon goals are tightening industrial fire safety requirements. Yangtze River Delta chemical processing clusters are specifying MI cable for plant safety system upgrades.
South Korea
Nuclear instrumentation cable replacement at Kori and Hanul reactor complexes is driving radiation-hardened procurement. MFDS and national industrial safety regulations are tightening fire performance mandates in pharmaceutical manufacturing. Busan shipyards are specifying Lloyd's Register-certified MI cable for engine room emergency power systems.
Mineral Insulated (MI) Cable Market Vendor Landscape
Capability concentration sits with integrated metal producers possessing captive copper smelting and cable drawing operations; scale advantage sits with diversified industrial conglomerates leveraging cross-selling into automation platforms. The vendor base stratifies across three tiers: vertically integrated specialty metal processors, diversified electrical equipment multinationals, and focused thermocouple cable specialists. M&A activity targets regional certification capabilities, while capacity expansion concentrates on flexible variant production lines for robotic equipment integration.
Among European-integrated metal processors, KME exemplifies the smelter-to-cable backward integration archetype. Watlow and Emerson occupy positions within the diversified industrial tier, anchoring their market presence through platform-level integration rather than component specialization. These three represent the dominant competitive anchors across capability concentration and scale advantage vectors respectively.
| Leading Market Players |
|---|
| KME |
| Baosheng |
| Raychem HTS |
| Conax Technologies |
| M.I. Cable Technologies, Inc. |
| Emerson |
| TEC |
| Watlow |
| ABB |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European copper smelting and cable drawing operations is tightening supplier discipline and amplifying pricing leverage for integrated producers serving nuclear and offshore wind procurement channels.
Pricing Analysis
Long-term offtake contracts dominate utility and nuclear sector procurement, insulating integrated suppliers from London Metal Exchange copper volatility while project-based spot purchases in commercial construction expose distributors to margin compression. Three-tier pricing structure across premium radiation-hardened, standard fire-resistant, and economy flexible variants reflects certification burden and sheathing material costs. Cost compression in the flexible segment is intensifying because polymer-insulated alternatives are capturing lower-temperature specifications. Contractors and EPC firms exhibit highest price sensitivity due to bundled tender economics, whereas nuclear owner-operators prioritize supply security over unit cost.
Supply Chain Analysis
Copper cathode feedstock draws from Chilean mining operations, German smelter complexes, and Chinese refining capacity, with magnesium oxide powder sourcing concentrated in Austrian and Turkish mineral processing facilities. Critical dependencies include seamless metal tube extrusion equipment, precision annealing furnaces, and certified termination hardware. Single-source vulnerability in radiation-hardened thermocouple cable creates procurement risk for semiconductor equipment builders. Distribution runs through integrated fire safety system vendors in French nuclear maintenance consortia, displacing standalone cable distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity and multi-standard testing bottlenecks are constraining supply response, creating durable margin pools for operators with captive laboratory capacity and trained installation networks.
For Market Incumbents: Harden position by deepening backward integration into copper smelting and magnesium oxide powder processing to offset raw material volatility, while expanding third-party certification laboratory capacity to reduce BS 6387 and IEC 60331 testing backlog delays that stall competitor product launches. For New Entrants and Emerging Players: Southeast Asian semiconductor fabrication clusters present underpenetrated demand for precision thermocouple cable where sub-degree accuracy specifications exclude established polymer-insulated suppliers. Target equipment OEM procurement teams with bundled sensor-cable-termination packages that shortcut legacy control system integration challenges. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across flexible variant production lines for robotic welding applications, favoring scaled operators with automated drawing and annealing equipment. Acquisition candidates should demonstrate captive certification capabilities and established technician training programs. Watch for REACH restriction expansions on halogenated flame retardants as demand inflection signal for inorganic insulation systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelting | KME's captive cathode supply secures margin stability against LME price swings in utility tenders. |
| Multi-Standard Certification Laboratory Expansion | Parallel BS 6387 and IEC 60331 testing capacity compresses product launch timelines for European building retrofit programs. |
| Flexible Variant Production Line Automation | Automated drawing equipment reduces unit costs for German automotive robotic welding cable specifications. |
| Technician Training Academy Partnerships | Certified installation labor pipelines mitigate project timeline risk in understaffed construction markets. |
| Smart Cable Fiber Optic Integration | Embedded temperature monitoring shifts value capture from hardware sales to predictive maintenance contracts for North Sea operators. |
Methodological Framework
Cross-validation between primary interviews with nuclear procurement officers, EPC contract managers, semiconductor equipment engineers, and certified cable installation technicians anchors the qualitative findings against secondary validation from IEC certification registries, EU Construction Products Regulation databases, and London Metal Exchange copper contract data. Bottom-up segment sizing triangulates against top-down utility capital expenditure tracking.
Calibration against historical nuclear cable replacement cycles and semiconductor fabrication equipment shipment data informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type rigidity, application environment severity, installation exposure conditions, and end-user procurement authority structure. CAGRs derive from installed base replacement scheduling and regulatory mandate implementation pacing, with offshore wind inter-array cabling specifications and REACH regulatory expansion timelines as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed copper processors or accelerated polymer-insulated fire-resistant cable substitution would shift outcomes. Cross-checking against IEA nuclear maintenance expenditure benchmarks and SEMI semiconductor equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
High Voltage Cable Termination Market
Cables
Cable Testing and Certification Market
Cables
High-Temperature Superconducting Cables Market
Cables
Submarine Cables Market
Cables
US Cables Market
Cables
Patch Cable Market
Cables
Cable Fault Locator Market
Cables
Cable Tray Market
Cables
Military Fiber Optic Cables Market
Cables
Europe Wire and Cable Market
Cables
Copper Cabling Systems Market
Cables
Low Voltage Cable Accessories Market
Cables
Coaxial Cable Market
Cables
Audio and Video Cables Market
Cables
Electric Vehicle Cables Market
Cables
Copper Stranded Wire Market