
 Global Cable Blowing Equipment Market | 2026-2036
Global Cable Blowing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cable Blowing Equipment Market Analysis
The EU F-Gas Regulation is consolidating the competitive landscape for cable blowing equipment across Europe by restricting hydrofluorocarbon-based pneumatic systems and elevating compliance costs for smaller entrants. Plumettaz S.A. leverages its Swiss manufacturing heritage to sustain premium positioning in high-precision fiber optic cable blowers for dense metropolitan networks. Condux International anchors North American supply through integrated production of duct rods and pulling accessories. Fremco A/S differentiates via Danish-engineered air blowing machines optimized for harsh-climate installations.
Cable blowing equipment comprises pneumatic and hydraulic machinery engineered to install fiber optic and copper cables into pre-installed ducts at controlled pressures typically ranging from 10 to 15 bar, with feed rates calibrated to prevent sheath damage during high-speed deployment. The primary commercial purpose centers on minimizing civil excavation costs while maximizing linear footage of cable placed per labor hour in telecommunications and utility infrastructure builds. Air blowing machines dominate product type revenue due to universal compatibility with standard polyethylene ducting, while fiber optic cable blowers capture accelerated growth from 5G backhaul and data center interconnect projects. Indoor installation types maintain stable replacement demand, whereas underground segments concentrate margin pools through specialized waterproofing and pressure-sealing requirements.
The European Telecommunications Standards Institute, the US Federal Communications Commission, and India's Telecom Regulatory Authority each impose distinct mechanical safety and electromagnetic compatibility standards that fragment certification requirements for cross-border equipment vendors. REACH compliance in Europe and RoHS substance restrictions further constrain material selections for seals, lubricants, and pneumatic hoses, effectively filtering out non-compliant manufacturers from premium procurement channels. Stakeholders must monitor evolving national broadband subsidy programs and associated technical specifications to anticipate which installation types and product configurations will command priority allocation in public-funded fiber deployments.
Market Dynamics
The EU F-Gas Regulation is compressing the competitive landscape by eliminating hydrofluorocarbon-based pneumatic systems and forcing capital reallocation toward compressed air and electric alternatives. Equipment manufacturers face divergent compliance timelines across jurisdictions while telecom operators accelerate fiber-to-the-home procurement.
Growth Catalysts
- REACH and RoHS substance mandates:European material restrictions are filtering out non-compliant seal and lubricant suppliers, concentrating procurement among certified equipment vendors with verified supply chains.
- Fiber-to-the-home deployment acceleration:Telecommunications operators in Germany, India, and the United States are expanding linear footage targets for residential broadband infrastructure.
- Compressed air system advancement:Pneumatic blowing machinery optimized for standard polyethylene ducting is capturing replacement demand from phased-out fluorinated gas systems.
Market Restraints
- Specialized component supply concentration:Precision pressure valves and high-durometer seals source predominantly from German and Swiss industrial suppliers, creating input bottlenecks.
- Technical performance ceiling:Current pneumatic systems face physical limits at 15 bar operating pressure for fragile fiber optic sheath protection.
- Regulatory fragmentation:Divergent electromagnetic compatibility standards between ETSI, FCC, and TRAI multiply certification costs for cross-border equipment vendors.
Strategic Opportunities
- Rural broadband subsidy programs:India's BharatNet initiative and USDA Rural Utilities Service grants are opening public-funded procurement channels for underground installation equipment.
- Data center interconnect demand:Hyperscale facility construction is creating specialized requirements for high-feed-rate fiber optic cable blowers in campus environments.
- Electric-hydraulic hybrid convergence:Battery-powered blowing units combined with intelligent pressure feedback systems are enabling deployment in grid-constrained locations.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction electromagnetic compatibility testing for ETSI, FCC, and TRAI standards extends product launch cycles by 8-14 months.
- Legacy duct infrastructure incompatibility:Decades-old asbestos-cement and unlined steel ducts in European urban cores resist standard polyethylene-optimized blowing techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cable Blowing Equipment Market |
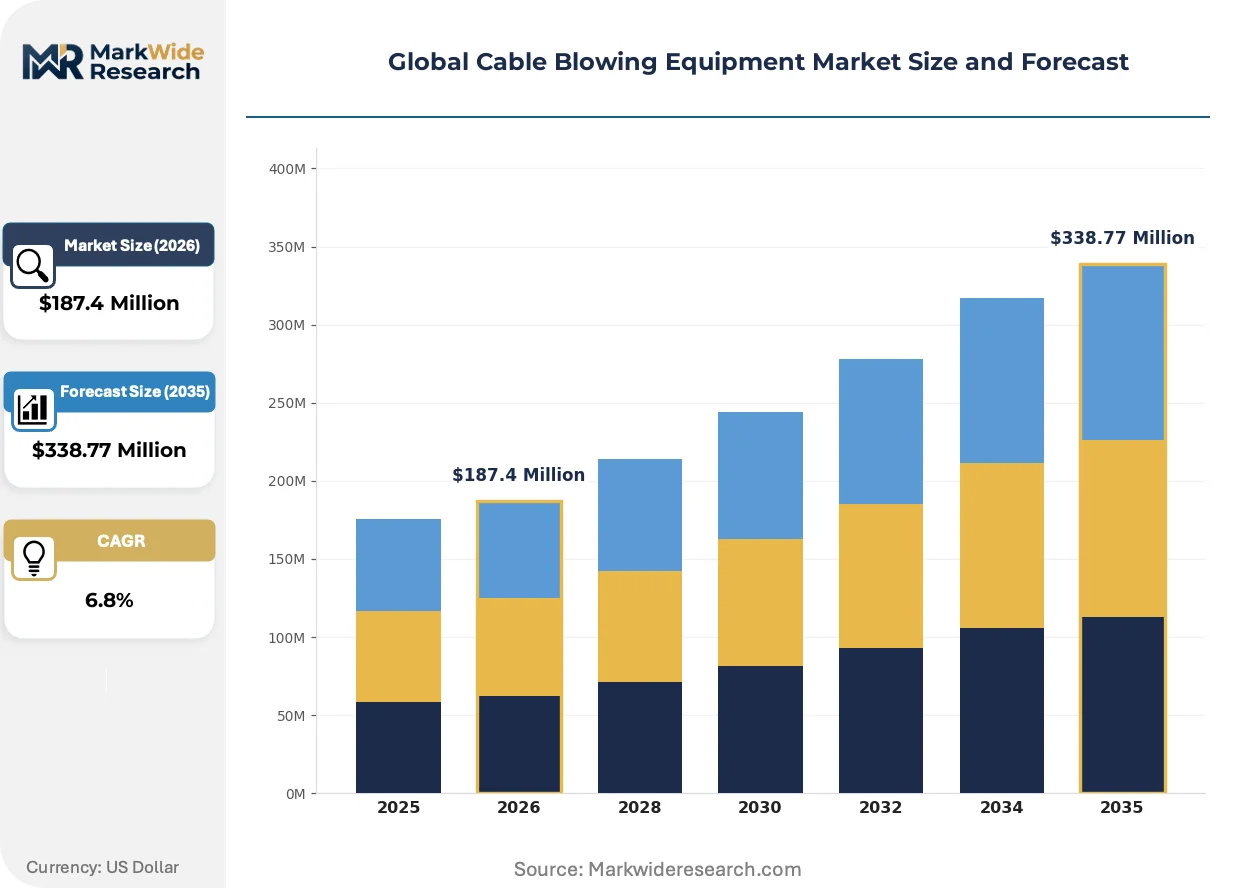
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
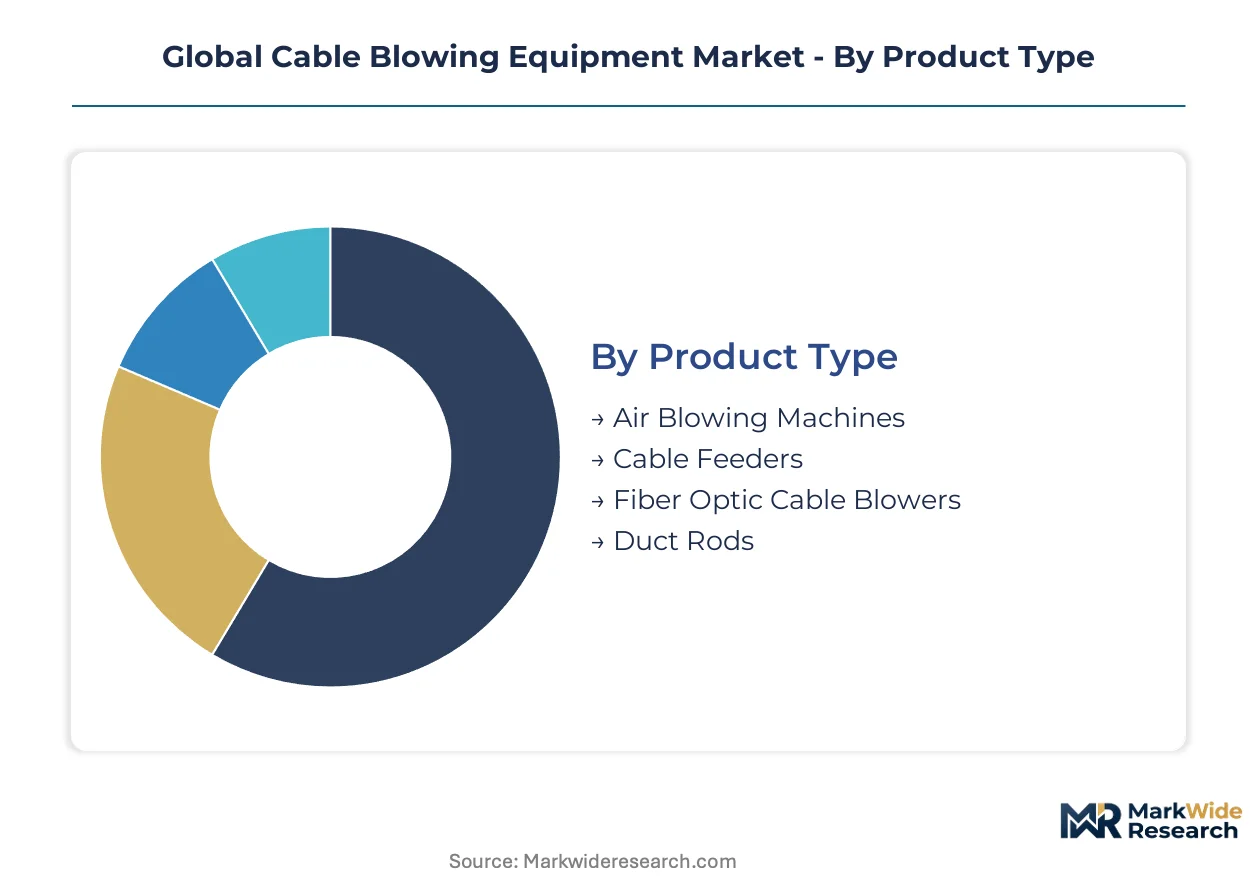
| Segmentation | Product Type: Air Blowing Machines, Cable Feeders, Fiber Optic Cable Blowers, Duct Rods End User: Telecommunications, Utilities, Construction, Data Centers Installation Type: Indoor, Outdoor, Underground, Aerial Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Plumettaz S.A., Condux International, Inc., Fremco A/S, Lancier Cable GmbH, Stanlay, Upcom Telekomunikasyon, Ningbo Marshine Power Technology Co., Ltd., CBS Products, Jakob Thaler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cable Blowing Equipment Market Emerging Trajectories
Equipment intelligence and pressure-feedback automation are displacing manual calibration protocols. Manufacturers are embedding sensor arrays directly into blowing heads to prevent sheath damage during high-speed fiber deployment.
Digital twin simulation software is unifying pre-deployment route planning with real-time pressure monitoring. German telecom contractors are adopting these integrated platforms for dense metropolitan fiber rollouts. The technology is compressing trial-and-error installation cycles and reducing cable waste rates in complex duct geometries.
The EU F-Gas Regulation is mandating complete phase-out of hydrofluorocarbon refrigerants in pneumatic systems by 2030. Equipment manufacturers are reengineering compressor architectures around compressed air and electric drive alternatives. Underground installation product lines face the steepest redesign costs, while indoor equipment categories adapt more rapidly to lighter regulatory thresholds.
Telecom operators are consolidating vendor relationships around full-service equipment-leasing arrangements. Traditional equipment purchase models are losing share to bundled maintenance and training contracts in European and North American markets. German municipal fiber utilities have pioneered this shift, with Indian state broadband agencies now piloting similar structures.
Global Cable Blowing Equipment Market Segmentation
Cable blowing equipment procurement varies sharply by technical environment and regulatory exposure. Equipment specifications must align with duct material compatibility, pressure tolerances, and electromagnetic compliance thresholds that differ across installation contexts.
Product Type:
ETSI electromagnetic compatibility certification applies universally, while FCC testing becomes mandatory for North American deployments and TRAI standards govern Indian procurement. REACH substance restrictions constrain seal and lubricant selections across all pneumatic variants.
- Air Blowing Machines:Pneumatic systems utilizing compressed air at 10-15 bar pressure for polyethylene duct compatibility. Demand concentrates in Germany where municipal fiber utilities prioritize standardized duct infrastructure and rapid linear footage deployment.
- Fiber Optic Cable Blowers:Precision-engineered units with sensor-integrated pressure feedback to prevent sheath damage during high-speed installation. Growth accelerates in hyperscale data center interconnect projects across the United States and campus fiber builds in India.
- Cable Feeders:Mechanized feeding mechanisms that synchronize cable advancement with airflow velocity.
- Duct Rods:Rigid push-pull tools for pre-installation duct proving and short-distance cable placement in legacy infrastructure.
Leading the category by volume: Air Blowing Machines. Growing fastest: Fiber Optic Cable Blowers.
End User:
Capital intensity and procurement scale diverge dramatically across customer types, with public subsidy programs reshaping equipment sourcing patterns.
- Telecommunications:Tier-one operators deploy fleet-scale blowing systems for fiber-to-the-home rollouts. German carriers and Indian state broadband agencies drive volume through multi-year equipment leasing arrangements.
- Data Centers:Hyperscale facility operators demand high-feed-rate blowers for campus interconnects with stringent latency requirements. Specifications emphasize rapid deployment cycles over cost minimization.
- Utilities:Power and water infrastructure operators deploy cable blowing for smart grid communications and SCADA network expansion.
- Construction:General contractors acquire portable units for subcontracted telecom infrastructure work with intermittent utilization patterns.
Telecommunications commands the largest installed base. Data Centers exhibits the steepest expansion trajectory.
Installation Type:
Environmental sealing requirements and pressure containment standards escalate with exposure to moisture, temperature fluctuation, and mechanical stress.
- Underground:Waterproofed blowing heads and pressure-sealed compressor units engineered for subterranean duct environments. Margin pools concentrate here due to specialized component requirements and extended service intervals.
- Indoor:Compact electric and pneumatic systems for building riser and data hall deployments. Replacement demand remains stable across European and North American markets with established fiber penetration.
- Outdoor:Weather-resistant enclosures for aerial and surface-mounted duct installations.
- Aerial:Lightweight portable units for messenger wire and pole-mounted fiber deployment with limited adoption.
Underground captures premium pricing. Indoor sustains replacement volume.
Distribution Channel:
Channel selection reflects equipment complexity, training requirements, and aftermarket service intensity.
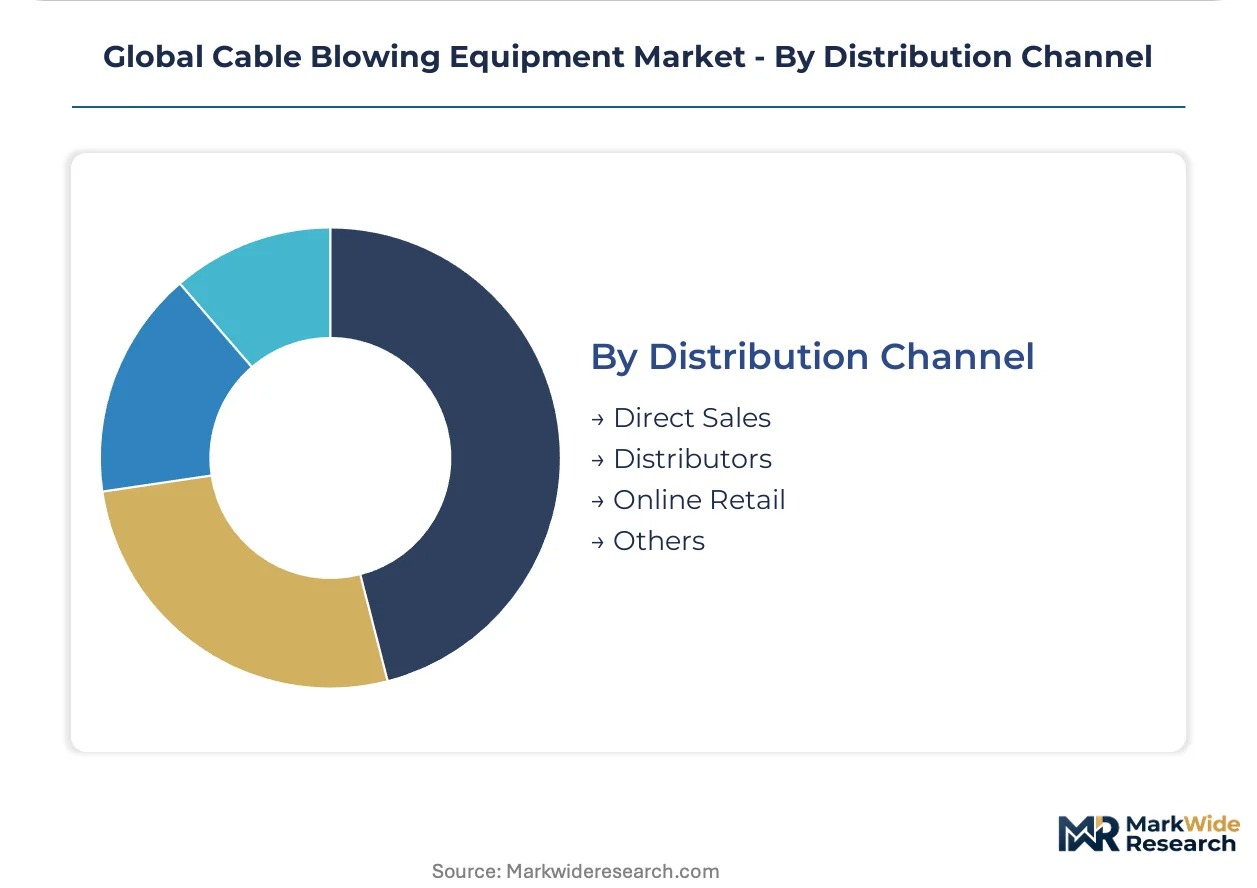
- Direct Sales:Manufacturer-direct relationships for large fleet procurement with bundled maintenance contracts and operator certification programs. German municipal utilities pioneered this structure.
- Distributors:Regional industrial equipment networks providing local inventory and technical support for mid-scale contractors.
- Online Retail:E-commerce platforms for standardized accessories, replacement seals, and consumable components.
- Others:Equipment leasing specialists and rental fleets serving project-based demand.
Direct Sales dominates value capture. Distributors sustain broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's Ruhr industrial corridor concentrate cable blowing equipment procurement through municipal fiber utilities leveraging EU cohesion fund subsidies. Dense urban duct infrastructure across the region sustains premium machinery demand. Cross-border equipment certification under ETSI standards facilitates seamless supply chain integration.
United States
Rural broadband expansion through USDA Rural Utilities Service grants drives underground installation equipment procurement across the Midwest and Southeast. FCC electromagnetic compatibility standards govern interstate equipment certification. Dallas-Fort Worth metroplex contractors deploy fleet-scale blowing systems for regional fiber-to-the-home rollouts.
Germany
Municipal fiber utilities in Bavaria and North Rhine-Westphalia prioritize high-feed-rate pneumatic systems for standardized polyethylene duct networks. REACH substance restrictions filter seal and lubricant suppliers from equipment supply chains. Stuttgart industrial cluster manufacturers supply precision pressure valves to domestic blowing equipment assemblers.
India
BharatNet initiative subsidies channel public procurement toward underground cable blowing machinery for rural broadband infrastructure. TRAI technical specifications mandate electromagnetic compliance testing for imported equipment. Tamil Nadu state broadband agencies pilot equipment-leasing arrangements modeled on European structures.
China
Dual carbon policy targets accelerate electric-hydraulic hybrid blowing system development for grid-constrained deployment scenarios. MIIT equipment certification requirements fragment cross-border vendor market access. Yangtze River Delta manufacturing bases produce compressed air compressor units for domestic and export markets.
Switzerland
Alpine terrain fiber deployments demand specialized harsh-climate blowing machinery with enhanced waterproofing specifications. Swissmedic-equivalent industrial equipment standards align with EU F-Gas Regulation phase-out timelines. Zurich metropolitan fiber utilities consolidate vendor relationships around full-service maintenance contracts.
Global Cable Blowing Equipment Market Vendor Landscape
Swiss and Danish producers anchor one tier; German specialists hold precision component supply. The vendor base stratifies around three strategic archetypes: heritage manufacturers with municipal utility relationships, regional fabricators serving price-sensitive contractors, and component specialists supplying precision pressure systems. Competitive positioning hinges on backward integration into seal and valve manufacturing alongside geographic expansion through distributor networks.
Among European heritage manufacturers, Plumettaz S.A. and Fremco A/S occupy positions exemplifying premium-tier positioning through Swiss and Danish engineering origins respectively. Condux International, Inc. represents the North American supply anchor with integrated production capabilities. These three entities illustrate how geographic manufacturing heritage translates into distinct competitive positioning across municipal utility, regional contractor, and component supply vectors.
| Leading Market Players |
|---|
| Plumettaz S.A. |
| Condux International, Inc. |
| Fremco A/S |
| Lancier Cable GmbH |
| Stanlay |
| Upcom Telekomunikasyon |
| Ningbo Marshine Power Technology Co., Ltd. |
| CBS Products |
| Jakob Thaler GmbH |
| Others |
Supply Flow & Price Mechanics
Steel price indices and aluminum alloy benchmarks cascade through cable blowing equipment manufacturing, compressing margins for pneumatic compressor housings while elevating premium positioning for Swiss and German precision-engineered systems serving municipal fiber utilities.
Pricing Analysis
Short lead-time premiums command substantial markups for certified air blowing machines with ETSI electromagnetic compatibility documentation, while spot inventory of standard indoor units trades at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated fiber optic cable blowers from basic pneumatic systems and unbranded Asian imports. Price differentiation hinges on REACH-compliant seal certifications and bundled maintenance contracts. Cost compression in economy tiers is intensifying because Indian state broadband agencies prioritize volume procurement over performance specifications. Municipal utilities in Germany exhibit lowest price sensitivity, whereas Southeast Asian construction contractors demonstrate acute responsiveness to unit cost fluctuations.
Supply Chain Analysis
ETSI certification and FCC electromagnetic compatibility testing create qualification gates that filter out non-compliant component suppliers from premium equipment supply chains. Manufacturing concentrates in Germany, Switzerland, and Denmark for precision pressure valves and high-durometer seals, while China dominates compressed air compressor unit fabrication. Raw material dependencies include specialty aluminum alloys for housing castings, fluoropolymer compounds for pressure seals, and precision-machined steel for valve assemblies. Single-source vulnerability concentrates in German industrial suppliers for critical pressure regulation components. Distribution runs through manufacturer-direct channels for fleet-scale municipal procurement and regional industrial distributors for mid-scale contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cable blowing equipment markets are navigating a technology-transition phase as electric-hydraulic hybrid systems displace legacy hydrofluorocarbon-based pneumatic machinery under EU F-Gas Regulation mandates.
For Market Incumbents: Acquire precision pressure valve manufacturing capabilities to secure captive supply of critical components facing German supplier bottlenecks. Deepen backward integration into REACH-compliant seal production to defend margin position against regulatory compliance cost escalation. Consolidate municipal utility relationships through full-service leasing arrangements that bundle maintenance contracts and operator certification programs, neutralizing emerging Danish and Swiss competitors. For New Entrants and Emerging Players: Battery-powered blowing units with intelligent pressure feedback systems offer a technology-first wedge into grid-constrained rural broadband deployments across India and USDA-subsidized American markets. Target BharatNet initiative procurement channels with electric-hydraulic hybrid systems optimized for harsh-climate underground installations. Pursue equipment-leasing partnerships with Tamil Nadu state broadband agencies as the most penetrable entry point for European-derived business models. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision component specialists in Stuttgart industrial clusters facing temporary margin compression from REACH substance restriction compliance costs. Long-term viability over a multi-year horizon rests on exposure to data center interconnect demand and 5G backhaul fiber deployment acceleration. Monitor F-Gas Regulation phase-out enforcement intensity as the critical inflection indicator for compressed air system replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | REACH compliance costs filter non-captive suppliers from German municipal utility procurement channels. |
| Electric-Hydraulic Hybrid System Development | EU F-Gas Regulation mandates accelerate R&D allocation toward battery-powered compressor architectures. |
| Equipment-Leasing Contract Expansion | German municipal fiber utilities pioneered bundled maintenance structures now piloted by Indian state agencies. |
| ETSI Certification Investment | Cross-border European supply chain integration requires electromagnetic compatibility documentation for premium positioning. |
| Data Center Interconnect Product Line | Hyperscale facility construction in the United States demands high-feed-rate blowers with rapid deployment cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fiber deployment contractors, municipal utility procurement officers, and precision component manufacturing executives. Secondary validation drew from ETSI technical specifications, FCC equipment authorization databases, TRAI technical standards publications, and REACH substance restriction compliance registries. Bottom-up triangulation across equipment shipment volumes and top-down reconciliation against broadband infrastructure investment disclosures ensured methodological rigor.
Data-stream reconciliation across manufacturer production records, distributor inventory movements, and end-user procurement disclosures informed the analytical framework. Segmentation modeling spanned product type, installation environment, end-use sector, and regional regulatory cluster dimensions across the analysis window. CAGRs were derived from least-squares fitting of annual value estimates, with sensitivity analysis around fiber-to-the-home deployment acceleration scenarios and F-Gas Regulation compliance timeline assumptions.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting German-Swiss component trade, technological discontinuities in fiber optic cable sheathing materials, and unanticipated BharatNet subsidy suspension. Forecasts reflect documented assumptions about regulatory enforcement consistency and raw material price trajectory stability. A model refresh is warranted upon material change in EU F-Gas Regulation phase-out scheduling or major rural broadband program reauthorization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Hybrid Cables Market
Cables
High Voltage Cable Termination Market
Cables
Flexible Cables Market
Cables
Flat Flexible Cables Market
Cables
FFC/FPC Jumper Cables Market
Cables
Submarine Optical Fiber Cables Market
Cables
Copper Cabling Systems Market
Cables
Submarine Cable System Market
Cables
Asia-Pacific Premise Cable Market
Cables
Fiber Optic Cable Accessories Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Cable Racks Market
Cables
High-Temperature Superconducting Cables Market
Cables
Submarine Data Cables Market