
 Artisanal Ice Cream Market | 2026-2036
Artisanal Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Artisanal Ice Cream Market Intelligence
Single-source dairy procurement is hardening into a competitive norm as artisanal makers seek traceable cream and milk supplies. Jeni's Splendid Ice Creams leverages direct farm partnerships across the Midwest to secure consistent butterfat profiles. Van Leeuwen Ice Cream anchors its Brooklyn operations with a vertically integrated kitchen that controls mix-in quality from base to pint. Salt & Straw differentiates through hyperlocal flavor collaborations with regional producers in each city it enters.
Artisanal ice cream denotes small-batch frozen dessert produced in limited quantities with premium dairy, natural stabilizers, and minimal overrun typically below 30 percent air content, yielding denser texture and intensified flavor concentration for premium consumer and foodservice channels. Gelato formulations command the deepest margin pools due to lower fat content and shorter ingredient lists that reduce input costs while preserving price premiums. Dairy-Free segments register the fastest structural expansion as oat and coconut bases displace traditional cream in health-conscious households. Distribution through food trucks and dedicated retail stores captures the highest per-unit economics by eliminating wholesale markups.
FDA dairy plant inspection protocols and EFSA hygiene requirements for frozen dessert production govern facility standards and labeling claims across major production jurisdictions. The EU Green Deal's Farm to Fork strategy pressures ingredient provenance documentation while California's Proposition 65 enforcement tightens contaminant thresholds for caramel colorants and flavor additives. Stakeholders must monitor evolving clean-label enforcement intensity and alternative protein certification pathways to preserve market access and premium positioning.
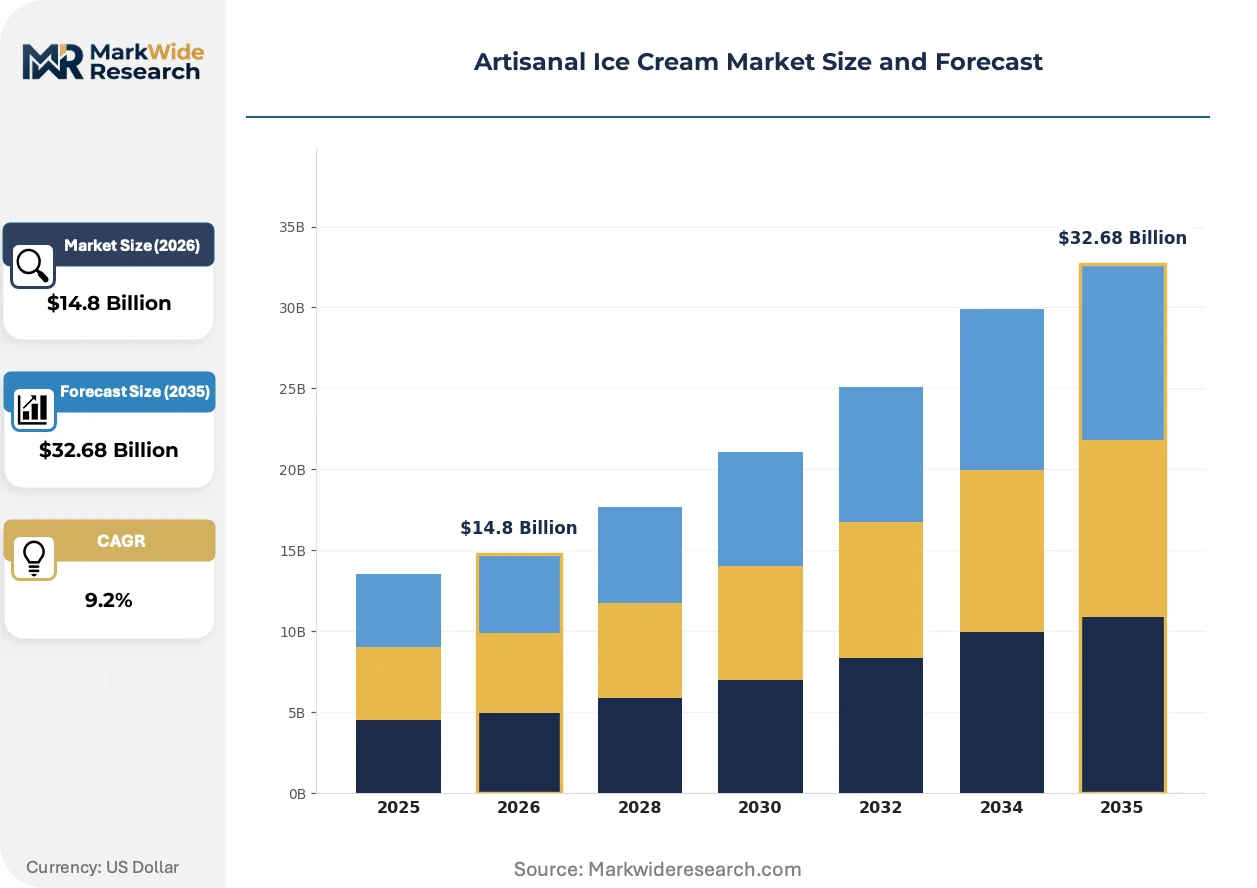
Market Dynamics
Clean-label enforcement intensity under FDA and EFSA frameworks is forcing artisanal producers to reconfigure supply chains around traceable dairy inputs and natural stabilizer systems, compressing formulation flexibility while elevating compliance costs.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory ingredient provenance documentation creates competitive moat for early-compliant producers with documented farm partnerships.
- Specialty grocery channel expansion:Boutique retail chains in the United States and Italy are dedicating freezer case space to small-batch producers with verified butterfat sourcing.
- Oat and coconut base technologies:Alternative protein fermentation advances are lowering dairy-free formulation costs while preserving premium mouthfeel standards.
Market Restraints
- Cream supply concentration:Midwest United States dairy cooperative consolidation limits independent artisanal access to consistent A2 protein milk volumes.
- California Proposition 65 enforcement:Tightened contaminant thresholds for caramel colorants force reformulation of classic flavor profiles.
- Natural stabilizer performance gaps:Locust bean and guar gum substitutes fail to match carrageenan texture retention through freeze-thaw cycles.
Strategic Opportunities
- Japan's aging premium consumer base:Underpenetrated Hokkaido dairy corridor offers untapped single-source milk partnerships for density-focused gelato formats.
- Food truck direct distribution:Mobile retail eliminates wholesale markups while capturing experiential consumption moments in urban clusters.
- EFSA clean-label certification pathways:Emerging natural additive approval frameworks reward early filers with 18-month competitive exclusivity windows.
Industry Challenges
- Artisan dairy microbiology expertise:Shortage of trained culture specialists delays new facility commissioning by 8-14 months.
- FDA dairy plant inspection backlogs:Pre-approval queue congestion stalls market entry for emerging regional brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artisanal Ice Cream Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelato, Sorbet, Soft Serve, Dairy-Free Flavor Profile: Chocolate, Vanilla, Fruit, Spiced Distribution Channel: Retail Stores, Food Trucks, Online, Restaurants Customer Segment: Families, Young Adults, Foodies, Health-Conscious Consumers |
| Companies Covered | Graeter's Ice Cream, Bi-Rite Creamery, Jeni's Splendid Ice Creams, High Road Craft Ice Cream, Ample Hills Creamery, Van Leeuwen Ice Cream, McConnell's Fine Ice Creams, Talenti Gelato, Salt & Straw, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artisanal Ice Cream Market Strategic Shifts & Innovations
Production technology and sourcing transparency are converging to reshape competitive differentiation, with equipment miniaturization and blockchain traceability systems penetrating mid-scale operations.
Continuous freezer technology is modularizing production economics for 500-2,000 liter batch artisans. Equipment manufacturers in Northern Italy are shipping plug-and-play micro-processing lines that slash capital requirements by half. This is modularizing entry barriers and enabling geographic expansion without centralized commissary investments.
EFSA hygiene requirements for frozen dessert production are tightening documentation standards for environmental pathogen monitoring. Small-batch facilities must now implement automated HACCP logging systems previously reserved for industrial plants. Gelato specialists in Emilia-Romagna are responding by pooling third-party audit costs through regional producer associations.
Hyperlocal flavor collaborations are displacing standardized national product lines as the primary customer acquisition mechanism. Boutique hospitality groups in Portland and Los Angeles now require city-specific ingredient stories for menu placement. This pattern concentrates in coastal United States markets where provenance narrative drives repeat purchase frequency.
Artisanal Ice Cream Market Segmentation
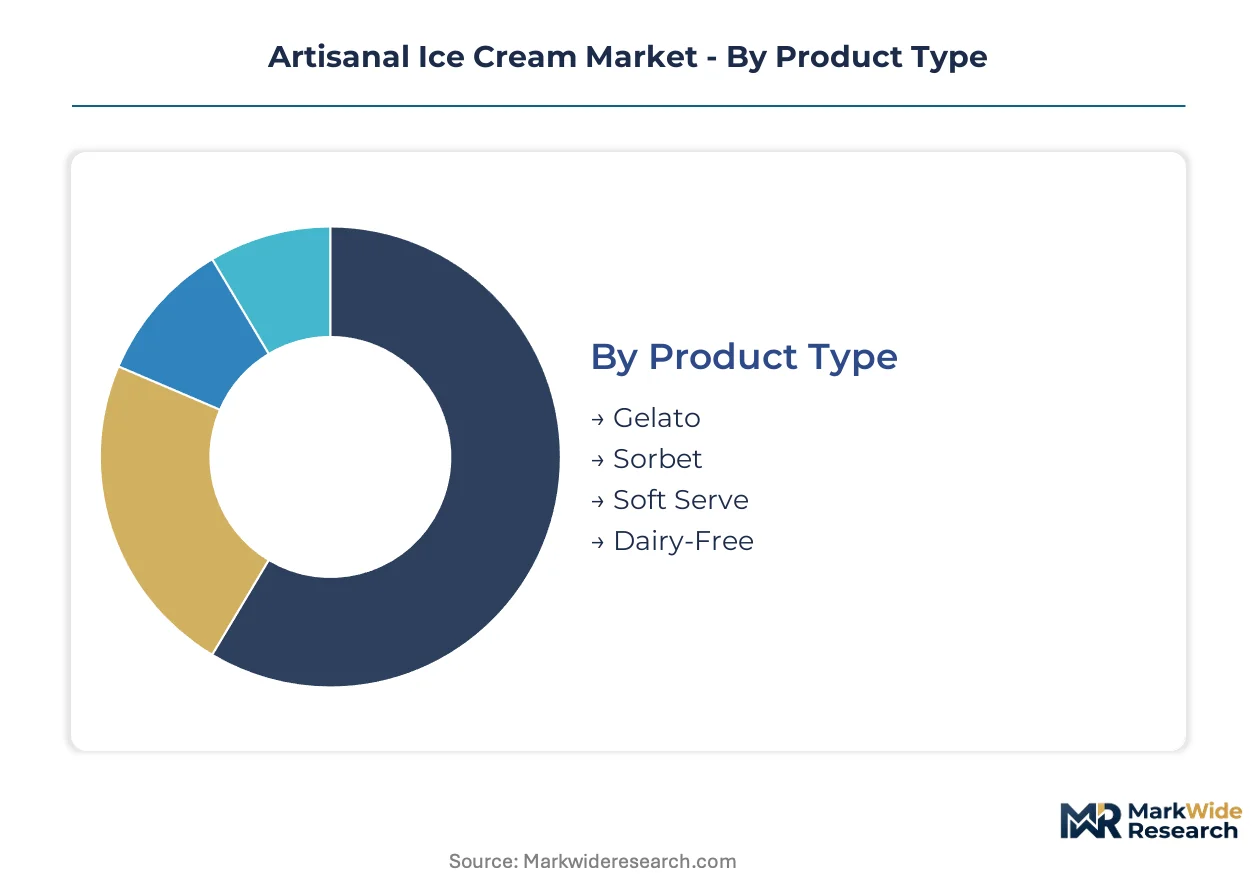
Artisanal ice cream segmentation reflects divergent paths between craft authenticity and scalable reach. Product format and distribution channel choices determine capital intensity, margin structure, and regulatory exposure for producers entering this market.
Product Type:
Customization intensity spans from standardized soft-serve formats to highly variable gelato recipes requiring culture-specific expertise.
- Gelato:Lower fat content and minimal overrun below 25 percent air yield dense texture prized in Italian and Japanese premium channels. Demand concentrates in boutique hospitality groups across Emilia-Romagna and Hokkaido where butterfat precision commands menu placement premiums. EFSA hygiene documentation requirements favor established producers with automated HACCP systems.
- Dairy-Free:Oat and coconut base technologies displace traditional cream in health-conscious households seeking clean-label alternatives. Demand clusters in coastal United States cities where Proposition 65 enforcement has tightened contaminant thresholds for caramel colorants. Alternative protein fermentation advances are lowering formulation costs while preserving mouthfeel standards.
- Sorbet:Fruit-puree formulations without dairy appeal to lactose-intolerant consumers and summer seasonal markets.
- Soft Serve:Higher overrun and faster production cycles suit high-traffic food trucks and quick-service restaurant attachments.
Leading the category by volume: Gelato. Growing fastest: Dairy-Free.
Flavor Profile:
Margin structure varies sharply between commodity base flavors and proprietary spiced formulations requiring specialized sourcing.
- Chocolate:Single-origin cacao partnerships differentiate premium positioning but concentrate supply risk around West African and Latin American cooperatives. FDA dairy plant inspection protocols govern allergen labeling for cocoa butter formulations.
- Vanilla:Madagascar and Tahitian bean provenance drives price tiering in specialty grocery freezer cases.
- Fruit:Hyperlocal berry and stone fruit collaborations generate city-specific menu stories for Portland and Los Angeles hospitality groups.
- Spiced:Cardamom, saffron, and chili infusions command the steepest premiums through limited-batch scarcity positioning.
Vanilla and Chocolate anchor volume throughput. Spiced variants gain share fastest among experiential consumption occasions.
Distribution Channel:
Capital requirements and per-unit economics diverge dramatically between fixed retail and mobile formats.
- Retail Stores:Dedicated freezer cases capture highest margins by eliminating wholesale markups but demand 18-24 month location payback periods. United States specialty grocery chains now dedicate linear footage to verified single-source producers.
- Food Trucks:Mobile distribution slashes real estate overhead while capturing urban consumption moments, though FDA dairy plant inspection backlogs delay commissioning for new entrants.
- Online:Direct-to-consumer shipping requires dry-ice logistics investment and faces compressed delivery windows for texture integrity.
- Restaurants:Boutique hospitality procurement demands city-specific ingredient provenance documentation and hyperlocal flavor collaborations.
Retail Stores dominate revenue concentration. Food Trucks expand most quickly among capital-constrained regional entrants.
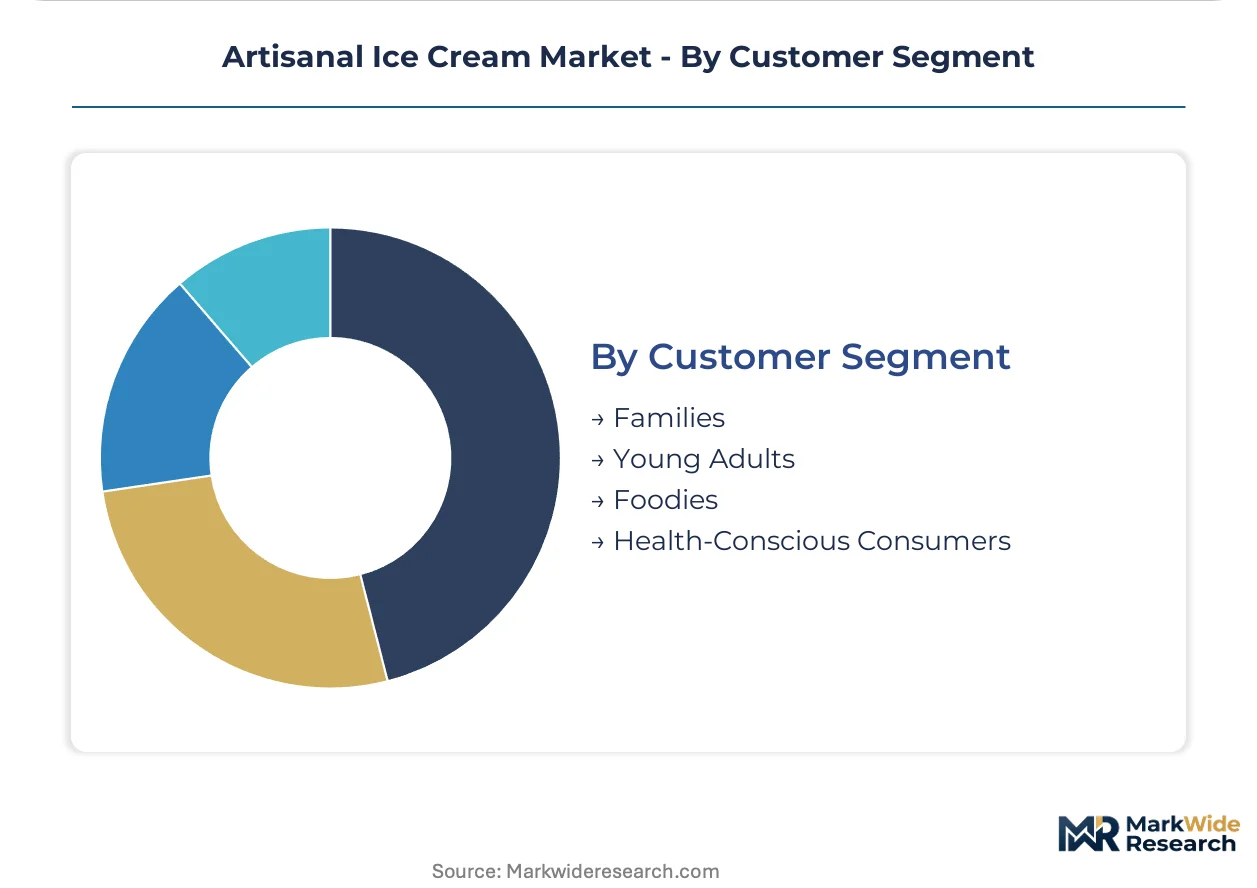
Customer Segment:
Purchase frequency and price elasticity separate occasion-driven buyers from habitual premium consumers.
- Families:Multi-pint purchases favor value-oriented formats with clean-label certification for child-focused households.
- Young Adults:Social-media-visible consumption drives demand for limited-drop collaborations and photogenic packaging.
- Foodies:Flavor complexity tolerance supports experimental ingredient combinations and fermentation-derived profiles.
- Health-Conscious Consumers:Macro-nutrient transparency and alternative protein bases displace indulgence positioning in California and Northeast United States markets.
Families represent the largest addressable base. Health-Conscious Consumers show the steepest expansion trajectory as oat-base technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hokkaido's dairy corridor supplies the high-butterfat milk that defines Japanese gelato density standards. Wisconsin and Vermont creameries anchor North American small-batch production. Emilia-Romagna's gelato equipment manufacturers export continuous freezer technology worldwide.
United States
Specialty grocery chains in Brooklyn and Portland dedicate linear freezer footage to verified single-source producers. FDA dairy plant inspection protocols govern allergen labeling and environmental pathogen monitoring for all facilities. California's Proposition 65 enforcement tightens contaminant thresholds for caramel colorants, forcing reformulation of classic flavor profiles in Los Angeles and San Francisco operations.
Italy
Boutique hospitality groups across Emilia-Romagna and Lombardy demand city-specific ingredient provenance documentation for menu placement. EFSA hygiene requirements mandate automated HACCP logging systems previously reserved for industrial plants. Bologna-based equipment manufacturers ship plug-and-play micro-processing lines that slash capital requirements for mid-scale artisans entering the market.
Japan
Hokkaido's aging premium consumer base sustains demand for density-focused gelato formats with minimal overrun. METI standards govern frozen dessert production facility certifications and labeling claims. Sapporo and Asahikawa dairy cooperatives supply single-source A2 protein milk partnerships that command menu placement premiums in Tokyo and Osaka hospitality channels.
United Kingdom
London's boutique retail chains expand procurement of small-batch producers with clean-label certification. The country's national food safety regulator enforces hygiene documentation standards for environmental pathogen monitoring. Cornwall and Devon creameries leverage direct farm partnerships to secure consistent butterfat profiles for premium positioning in Southeast England hospitality clusters.
Canada
Toronto and Vancouver specialty grocers dedicate freezer case space to regional artisans with verified dairy sourcing. Health Canada standards govern frozen dessert production facility inspections and contaminant thresholds. Quebec's dairy cooperative network supplies traceable cream volumes that enable small-batch production economics for Ontario and British Columbia entrants.
Artisanal Ice Cream Market Key Industry Players
Global majors compete with regional champions across distribution channel access and single-source dairy procurement relationships. The vendor base clusters around three strategic tiers: vertically integrated kitchen operators controlling mix-in quality, hyperlocal flavor collaboration specialists, and direct farm partnership anchor brands. Market structure favors consolidation through strategic partnerships between equipment manufacturers and emerging regional brands, alongside portfolio diversification into dairy-free oat and coconut base formulations.
Among Midwest-based direct farm partnership specialists, Jeni's Splendid Ice Creams exemplifies the traceable supply chain archetype through its documented cream sourcing relationships. Van Leeuwen Ice Cream occupies a position within the vertically integrated tier, representing kitchen-controlled production economics. Salt & Straw sits within the hyperlocal collaboration vector, anchoring city-specific ingredient narrative strategies for boutique hospitality procurement.
| Leading Market Players |
|---|
| Graeter's Ice Cream |
| Bi-Rite Creamery |
| Jeni's Splendid Ice Creams |
| High Road Craft Ice Cream |
| Ample Hills Creamery |
| Van Leeuwen Ice Cream |
| McConnell's Fine Ice Creams |
| Talenti Gelato |
| Salt & Straw |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between EFSA-clean-label and conventional formulations splits pricing power along compliance investment lines, with documented farm partnerships commanding shelf-space premiums while commodity dairy inputs face margin compression from natural stabilizer cost inflation.
Pricing Analysis
Service-bundling separates experiential retail formats from stripped-down wholesale channels. Three-tier pricing structure across premium single-origin, standard verified-sourcing, and economy private-label levels anchors tier placement to butterfat documentation depth. Price differentiation rests on HACCP automation levels and hyperlocal collaboration exclusivity. Pricing pressure intensifies in mid-tier gelato as continuous freezer technology democratizes production economics. Food trucks and direct retail show lowest price elasticity; commodity wholesale buyers exhibit highest sensitivity to overrun and stabilizer cost swings.
Supply Chain Analysis
Domestic-content rules under EU Green Deal Farm to Fork strategy and California Proposition 65 enforcement are reshaping sourcing toward traceable regional dairy corridors. Supply concentrates in United States Midwest dairy cooperatives, Hokkaido A2 protein networks, and Emilia-Romagna equipment manufacturing clusters. Raw material dependencies center on Madagascar vanilla bean provenance, West African single-origin cacao, and locust bean gum natural stabilizer supplies. Single-source vulnerability in A2 protein milk volumes creates bottleneck risk for density-focused gelato formats. Distribution runs through specialty grocery freezer case dedication, food truck mobile retail, and boutique hospitality procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
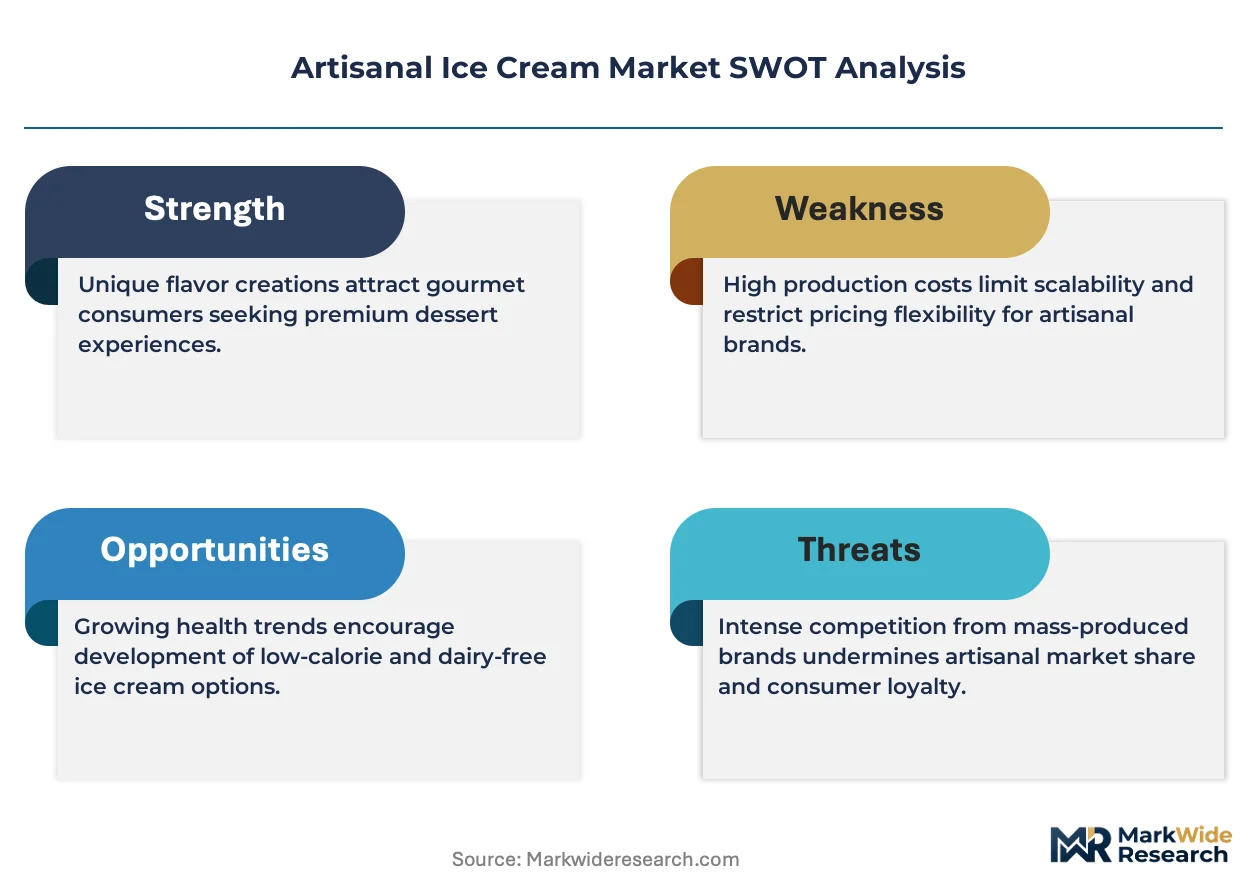
This market operates as a cost-of-compliance story where EFSA hygiene documentation requirements and FDA dairy plant inspection protocols erect barrier-to-entry moats favoring early-compliant producers with automated HACCP systems and verified farm partnerships.
For Market Incumbents: Anchor market position through backward integration into Hokkaido or Midwest single-source dairy partnerships that lock in A2 protein volumes. Deepen channel control by expanding dedicated freezer case commitments with United States specialty grocery chains before equipment miniaturization enables regional competitor entry. Certification investment in EFSA clean-label pathways secures 18-month exclusivity windows against reformulating challengers.
For New Entrants and Emerging Players: The mid-tier price-point gap between Van Leeuwen-tier vertical integration and commodity private-label offers white-space for modular continuous freezer operations in underserved urban clusters. Target food truck direct distribution in coastal United States cities where Proposition 65 enforcement has displaced conventional caramel formulations. Pursue hyperlocal flavor collaboration strategies with regional producers as the primary customer acquisition mechanism.
For Investors and Strategic Acquirers: Re-rating potential sits with established regional brands possessing documented farm partnerships given accelerating FDA inspection backlog congestion that stalls competitor commissioning. Long-term viability favors producers with captive supply of traceable cream and in-house stabilizer formulation capability. Watch EFSA natural additive approval timelines as inflection indicator for competitive exclusivity value realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Single-Source Dairy | Captive A2 protein milk supply secures butterfat consistency for gelato density standards. |
| EFSA Clean-Label Certification Filing | Early natural additive approval locks 18-month competitive exclusivity in European markets. |
| Hyperlocal Flavor Collaboration Network | City-specific ingredient stories drive repeat purchase frequency in Portland and Los Angeles hospitality. |
| Continuous Freezer Technology Deployment | Modular micro-processing lines from Bologna manufacturers halve capital requirements for geographic expansion. |
| Dairy-Free Base Formulation Investment | Oat and coconut fermentation advances capture health-conscious household expansion in California and Northeast markets. |
Research Approach
Trade databases, FDA facility inspection records, and EFSA additive approval filings formed the secondary backbone, cross-referenced with primary interviews involving artisanal creamery operations directors, specialty grocery category buyers, boutique hospitality procurement managers, and dairy cooperative supply planners. Bottom-up and top-down triangulation validated volume estimates against equipment manufacturer shipment data and regional production capacity assessments.
Bottom-up modeling anchored forecasts to continuous freezer installation rates and single-source dairy partnership formation velocity across the projection horizon. Segmentation dimensions spanned product format, flavor profile complexity, distribution channel capital intensity, and customer segment price elasticity. CAGRs derived from equipment miniaturization adoption curves and clean-label enforcement intensity trajectories. Industry-specific inputs included HACCP automation penetration rates and hyperlocal collaboration frequency by metropolitan market.
Underlying measurement precision varies by segment; gelato and dairy-free categories carry tighter precision than soft-serve given clearer production volume tracking through equipment manufacturer disclosures. Forecasts reflect assumptions around FDA inspection queue clearance timelines and EFSA natural additive approval velocity, with regulatory backlog extension or accelerated clean-label enforcement representing primary revision vectors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Soup Market
Processed Foods
Processed Mango Products Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Processed Vegetable Market
Processed Foods
Apple Butter Market
Processed Foods
Butter Crisco Market
Processed Foods
Spreadable Fats Market
Processed Foods
Coffee Creamer Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
Pizza Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Fermented Foods Market
Processed Foods
Broth Market
Processed Foods
Fruit Processing Market