
 Low Fat Chicken Soup Market | 2026-2036
Low Fat Chicken Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Chicken Soup Market Analytics
Private-label formulation services is fragmenting as branded manufacturers reclaim control over recipe development and nutritional certification. Campbell Soup Company leverages its in-house R&D infrastructure to sustain proprietary low-fat broth technologies. Nestlé S.A. anchors European distribution through dedicated health-food channel partnerships. Conagra Brands, Inc. competes on frozen soup line extensions that target calorie-specific dietary protocols.
Low fat chicken soup is a processed food product containing reduced lipid content, typically achieved through skimming, lean-muscle selection, or enzymatic fat separation, with primary commercial purpose of delivering protein-rich nourishment within controlled caloric frameworks. Canned soup occupies the largest volume position due to shelf stability and established retail placement, though instant soup segments are gaining velocity among single-serve convenience seekers. Organic ingredient classifications command premium positioning as consumers scrutinize supply chain transparency and antibiotic-free poultry sourcing claims.
The FDA governs nutritional labeling and health-claim substantiation for low-fat designations in the United States, while EFSA oversees parallel standards across European markets, collectively pressuring manufacturers to reformulate sodium profiles and validate protein-content assertions. The USDA Organic seal and EU Organic Regulation further constrain ingredient sourcing, limiting domestic poultry suppliers who can meet dual-continent certification requirements. Stakeholders must monitor evolving clean-label enforcement thresholds and preemptive reformulation costs before regulatory deadlines compress margin structures.
Market Dynamics
FDA sodium-reduction mandates and EFSA clean-label enforcement are forcing simultaneous reformulation across US and European manufacturing lines, compressing development timelines while elevating R&D spend requirements.
Growth Catalysts
- Clean-label certification thresholds:EFSA tightened additive disclosure rules in 2023, compelling manufacturers to remove artificial stabilizers and driving premium positioning for compliant formulations.
- Single-serve convenience formats:Urban consumers in Germany and the United States are accelerating purchases of microwave-ready cups that reduce preparation time to under 90 seconds.
- Functional nutrition protocols:Calorie-specific dietary programs from institutional healthcare and corporate wellness providers are embedding low-fat chicken soup as a standardized meal component.
Market Restraints
- Antibiotic-free poultry supply concentration:USDA Organic and EU Organic Regulation compliance limits eligible domestic suppliers to under 15% of conventional poultry volume in key producing states.
- Enzymatic fat separation cost volatility:Lipase enzyme prices fluctuate with microbial fermentation feedstock costs, squeezing margin on premium-positioned skimming-alternative products.
- Refrigerated fresh soup substitution:Chilled clean-label alternatives with shorter ingredient lists are capturing shelf-space allocations from shelf-stable canned formats in premium retail channels.
Strategic Opportunities
- Direct-to-subscription channel development:Health-focused meal-kit platforms in the United States are creating dedicated soup subscription tiers with monthly delivery cadences.
- Senior nutrition program integration:Medicare Advantage supplemental benefit expansions are opening institutional procurement pathways for protein-fortified, low-sodium formulations.
- Biodegradable packaging convergence:Plant-based barrier films combined with modified atmosphere sealing are enabling shelf-stable formats to shed aluminum and plastic laminate structures.
Industry Challenges
- Dual-continent certification synchronization:USDA Organic and EU Organic Regulation audit timelines rarely align, forcing manufacturers to maintain parallel documentation systems and duplicate facility inspections.
- Sodium-reduction taste engineering:Flavor chemists with cross-functional expertise in both salt-replacement technologies and thermal processing stability remain scarce relative to open positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Chicken Soup Market |
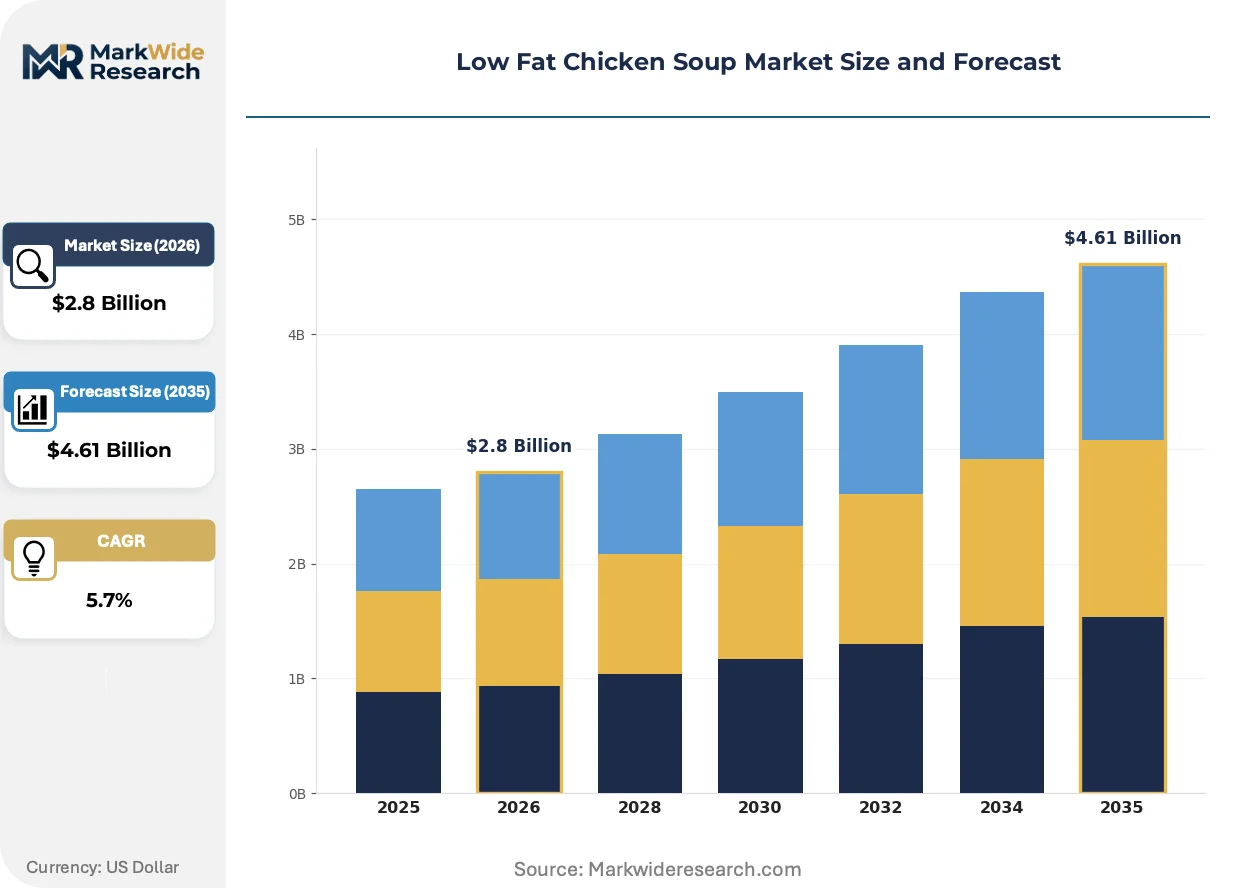
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Frozen Soup, Instant Soup, Packaged Soup Ingredient Type: Organic, Gluten-Free, Low Sodium, Vegan Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Shops End User: Health-Conscious Individuals, Diabetics, Athletes, Families |
| Companies Covered | Campbell Soup Company, Conagra Brands, Inc., General Mills, Nestlé S.A., The Kraft Heinz Company, Baxters Food Group Limited, Blount Fine Foods, Amy's Kitchen, Inc., The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Chicken Soup Market Evolving Landscape
Formulation science and packaging engineering are converging to address the tension between extended shelf stability and clean-ingredient transparency, with manufacturers racing to validate next-generation preservation methods before regulatory deadlines.
Membrane filtration technology is migrating from dairy processing into poultry broth clarification, enabling precise lipid reduction without thermal degradation of protein structures. European manufacturers in Germany and the Netherlands are piloting ceramic microfiltration systems at commercial scale. This migration from traditional skimming is compressing the cost gap between conventional and premium low-fat positioning.
EFSA updated its guidance on nutrition and health claims in late 2023, tightening evidentiary standards for protein-content assertions on soup labels. Manufacturers must now submit clinical or controlled dietary intervention data rather than compositional analysis alone. The chilled soup segment faces the steepest compliance burden, as fresh-positioned products rely heavily on protein claims to justify price premiums against shelf-stable alternatives.
Healthcare procurement departments are consolidating vendor lists around suppliers who can deliver both USDA Organic certification and documented sodium profiles below 480mg per serving. Hospital systems in California and Massachusetts are piloting exclusive supply agreements that lock in three-year pricing in exchange for volume commitments. This consolidation is most visible in the United States, where Medicare reimbursement incentives reward institutional nutrition standardization.
Low Fat Chicken Soup Market Segmentation
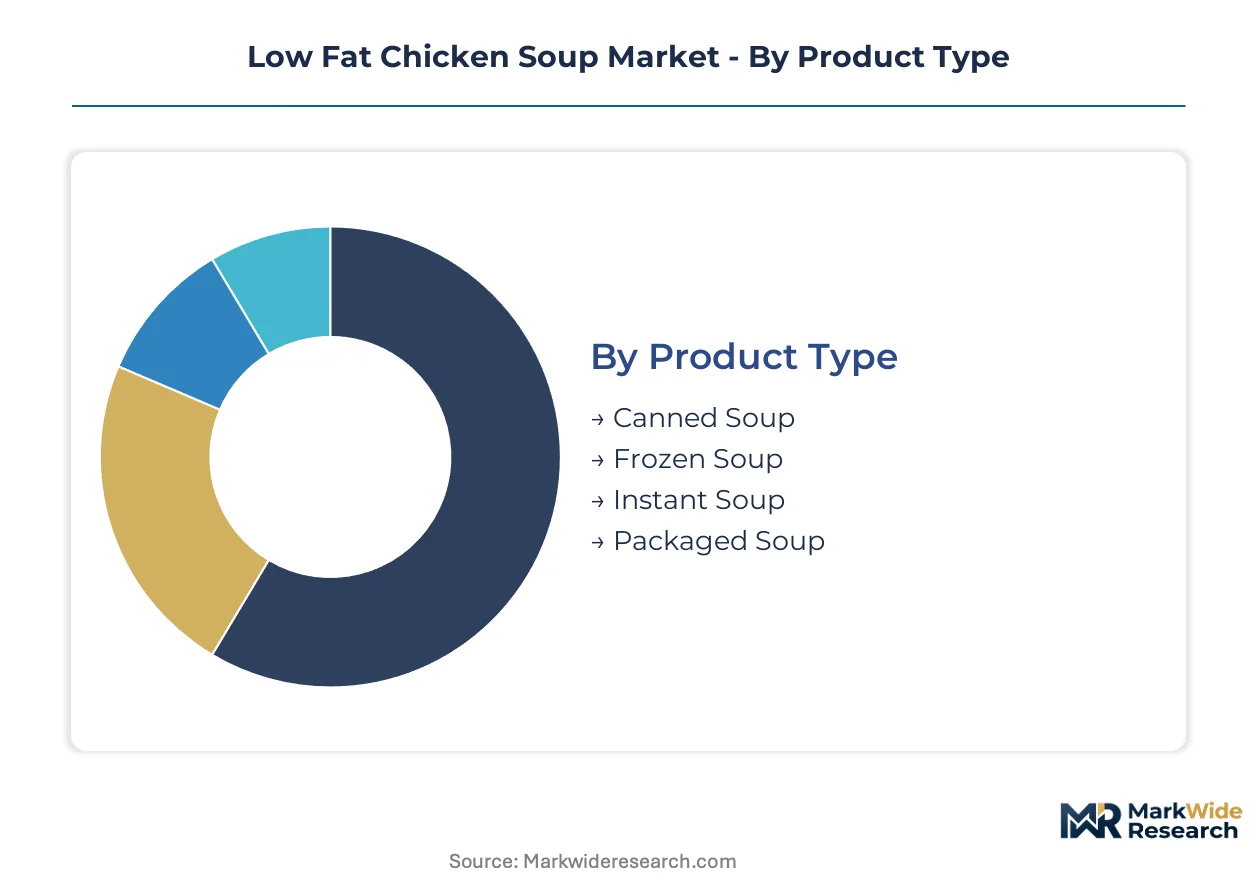
Segmentation in the low fat chicken soup market determines formulation priorities, packaging investments, and channel economics. Manufacturers calibrate fat-reduction techniques, sodium profiles, and protein fortification levels against distinct consumer health protocols and preparation convenience requirements.
Product Type:
Preparation time constraints and storage infrastructure availability across residential, institutional, and foodservice settings create divergent product format demand.
- Canned Soup:Thermal processing in aluminum or steel containers delivers shelf stability exceeding 24 months without refrigeration. Health-Conscious Individuals in the United States sustain volume concentration through established supermarket placement and Medicare Advantage institutional procurement programs.
- Instant Soup:Dehydrated or freeze-dried formulations reconstitute with hot water in under 90 seconds. Urban consumers in Germany are accelerating adoption through dedicated health-food channel partnerships and single-serve convenience positioning.
- Frozen Soup:Blast-frozen formulations preserve flavor compounds and protein structures without thermal degradation. Cold-chain distribution requirements limit geographic reach relative to shelf-stable alternatives.
- Packaged Soup:Aseptic cartons and retort pouches bridge shelf stability and refrigerated freshness perceptions. Flexible packaging formats are gaining shelf-space allocations in European premium retail channels.
Established volume favors Canned Soup; emerging adoption favors Instant Soup.
Ingredient Type:
Certification premiums and regulatory compliance thresholds stratify ingredient sourcing costs and label claim substantiation burdens.
- Organic:USDA Organic and EU Organic Regulation compliance mandates antibiotic-free poultry sourcing and additive-free processing. Supply concentration limits eligible domestic suppliers to under 15% of conventional poultry volume in key producing states.
- Low Sodium:FDA sodium-reduction mandates and EFSA clean-label enforcement compel reformulation below 480mg per serving. Hospital systems in California and Massachusetts are consolidating vendor lists around documented sodium profile compliance.
- Gluten-Free:Elimination of wheat-based thickeners requires alternative stabilizer systems. Celiac disease prevalence and non-celiac gluten sensitivity are driving specialty shop placement.
- Vegan:Plant-based protein substitutes replace poultry entirely, targeting ethical consumption protocols and allergen avoidance. Formulation science challenges include amino acid profile completeness and mouthfeel replication.
Certification premiums concentrate in Organic; dietary protocol integration expands fastest in Low Sodium.
Distribution Channel:
Purchase occasion frequency and basket composition economics determine channel investment priority and promotional calendar alignment.
- Supermarkets:Mass-market placement captures routine grocery trip inclusion and promotional discount responsiveness. Shelf-stable formats dominate center-store placement with established facings.
- Online Retailers:Subscription cadences and direct-to-consumer fulfillment enable health-focused meal-kit platform integration. Monthly delivery tiers are creating dedicated soup subscription categories.
- Convenience Stores:Immediate consumption occasions and travel-related purchases favor single-serve microwave-ready cups. Urban density and commuter patterns drive location-specific assortment.
- Specialty Shops:Curated health-food positioning and educated staff consultation support premium pricing for certified organic and functional nutrition claims.
Volume gravity centers on Supermarkets; subscription economics are reshaping Online Retailer investment.
End User:
Health condition specificity, athletic performance targets, and household composition determine nutritional formulation requirements and portion sizing.
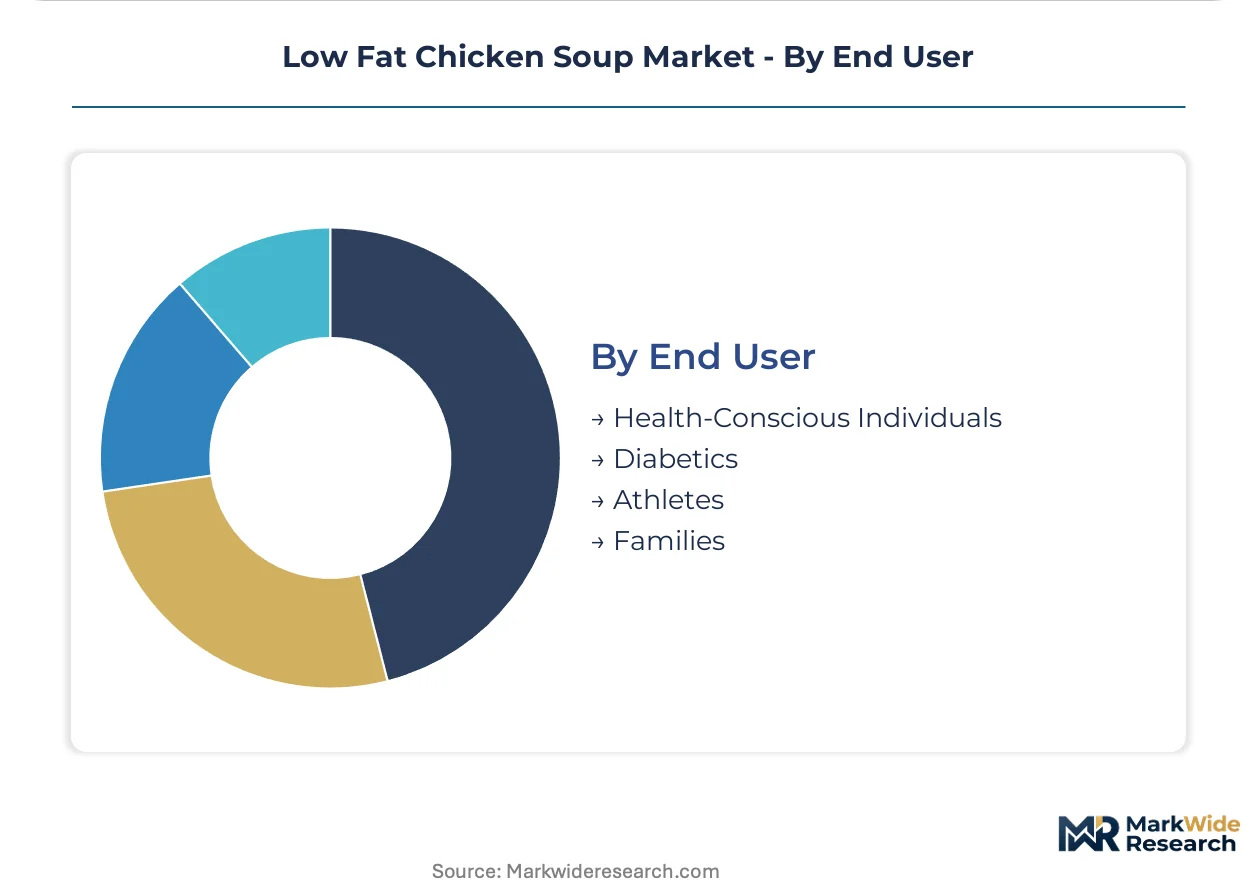
- Health-Conscious Individuals:Proactive wellness maintenance drives clean-label scrutiny and supply chain transparency demands. Calorie-specific dietary programs embed low-fat chicken soup as standardized meal components.
- Diabetics:Glycemic control protocols require carbohydrate monitoring and sodium limitation. Medicare Advantage supplemental benefit expansions are opening institutional procurement pathways.
- Athletes:Protein-to-calorie ratio optimization and rapid glycogen recovery targets influence fortification levels and serving timing recommendations.
- Families:Multi-generational palatability acceptance and cost-per-serving calculations favor larger format packaging and milder flavor profiles.
Programmatic procurement anchors Health-Conscious Individuals; condition-specific formulation is expanding fastest among Diabetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor instant formats for workplace consumption, while United States households rely on canned varieties for Medicare Advantage meal programs. This consumption-mix differential shapes distinct supply chain configurations across markets.
United States
Medicare Advantage supplemental benefit expansions are embedding low-fat chicken soup as standardized meal components for senior nutrition programs. FDA sodium-reduction mandates compel reformulation below 480mg per serving for institutional procurement eligibility. Hospital systems in California and Massachusetts are piloting exclusive three-year supply agreements that consolidate vendor lists around USDA Organic certification.
Germany
Urban professionals in Berlin and Munich are accelerating purchases of microwave-ready single-serve cups that reconstitute in under 90 seconds. EFSA tightened additive disclosure rules in 2023, compelling manufacturers to remove artificial stabilizers from health-food channel formulations. The Netherlands-border industrial corridor hosts ceramic microfiltration pilot facilities migrating from dairy processing into poultry broth clarification.
United Kingdom
Corporate wellness providers are embedding calorie-specific dietary protocols that designate low-fat chicken soup as standardized lunch components. EFSA clean-label enforcement pressures simultaneous reformulation across shared US-European manufacturing lines. Greater London retail channels are allocating expanded shelf space to aseptic carton formats bridging shelf stability and refrigerated freshness perceptions.
Japan
Aging demographics and single-person household growth are driving demand for protein-fortified, portion-controlled soup formats. METI guidelines on functional food labeling influence protein-content substantiation requirements for health claims. The Kanto region around Tokyo concentrates R&D investment in membrane filtration technologies for precise lipid reduction without thermal degradation.
Canada
Health Canada nutrition labeling regulations align with FDA standards, enabling cross-border manufacturing efficiency for North American production networks. Provincial healthcare procurement in Ontario and Quebec is consolidating vendor lists around documented sodium profile compliance. The Pacific Northwest supply corridor integrates British Columbia poultry sourcing with Washington State processing infrastructure.
Low Fat Chicken Soup Market Competitive Landscape
Capability concentration sits with specialized clean-label formulators; scale advantage sits with diversified packaged food conglomerates. The market exhibits tiered structure with branded manufacturers reclaiming recipe development control from private-label service providers. Three archetypes dominate: legacy soup specialists with in-house R&D infrastructure, diversified food conglomerates leveraging health-food channel partnerships, and emerging clean-label challengers targeting subscription economics. Competitive moves center on portfolio diversification into functional nutrition segments and strategic partnerships with meal-kit platforms.
Among legacy specialists, Campbell Soup Company exemplifies the in-house R&D archetype, while Nestlé S.A. represents diversified European market anchoring through health-food channel positioning. Conagra Brands, Inc. occupies the scale-driven tier with frozen line extension capabilities targeting calorie-specific dietary protocols.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Conagra Brands, Inc. |
| General Mills |
| Nestlé S.A. |
| The Kraft Heinz Company |
| Baxters Food Group Limited |
| Blount Fine Foods |
| Amy's Kitchen, Inc. |
| The Hain Celestial Group |
| Others |
Value Network & Pricing Analysis
The Pacific Northwest poultry processing corridor stretching from British Columbia to Washington State anchors North American organic chicken supply, concentrating antibiotic-free sourcing capacity that translates directly into premium pricing power for certified low-fat soup manufacturers serving Medicare Advantage procurement programs.
Pricing Analysis
Contract-based long-term offtake agreements dominate institutional procurement, with hospital systems in California and Massachusetts locking three-year pricing in exchange for volume commitments and documented sodium profile compliance. Three-tier pricing structure across premium organic, standard clean-label, and economy conventional levels differentiates based on USDA Organic certification and EFSA additive disclosure thresholds. Pricing pressure stems from lipase enzyme cost volatility in enzymatic fat separation processes. Institutional buyers exhibit lowest price sensitivity due to Medicare reimbursement standardization, while convenience-oriented urban consumers in Germany show highest responsiveness to promotional discounting.
Supply Chain Analysis
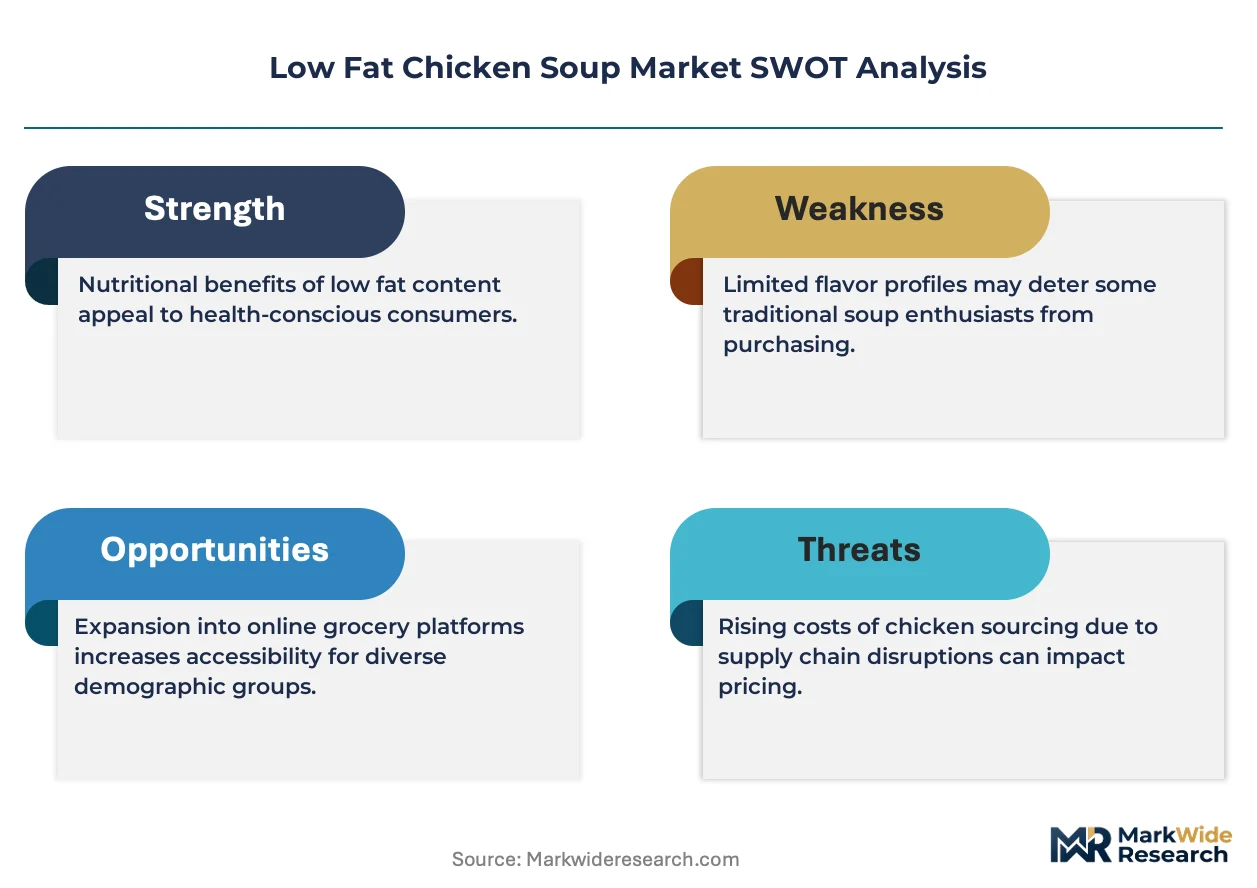
Tariff exposure between the United States and Canada disrupts cross-border organic poultry flows through the Pacific Northwest supply corridor, forcing redundant certification maintenance. Raw material dependencies center on antibiotic-free chicken sourcing, lipase enzyme feedstocks, and plant-based barrier films for biodegradable packaging. Single-source vulnerability concentrates in ceramic microfiltration equipment supply from the Netherlands-border industrial cluster. Distribution runs through supermarket center-store placement for volume, with online retailer subscription tiers capturing fastest-growing health-conscious consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based meal delivery represents the fastest-expanding recurring-revenue layer in low-fat chicken soup, outpacing hardware-equivalent product sales as health-focused platforms introduce dedicated monthly soup tiers with automated replenishment cadences.
For Market Incumbents: Build certification moats through simultaneous USDA Organic and EU Organic Regulation compliance that new entrants cannot replicate without parallel audit systems and duplicate facility inspection costs. Deepen backward integration into antibiotic-free poultry sourcing to defend against supply concentration limiting eligible domestic suppliers to under 15% of conventional volume. Anchor health-food channel partnerships in Germany to preempt emerging clean-label challengers from securing shelf-space allocations. For New Entrants and Emerging Players: Pursue direct-to-subscription channel development through health-focused meal-kit platforms in the United States, where monthly delivery tiers remain underpenetrated relative to established supermarket dominance. Target senior nutrition program integration as Medicare Advantage supplemental benefits expand institutional procurement pathways with less entrenched vendor relationships. Lead with biodegradable packaging convergence positioning to differentiate against aluminum-dependent legacy manufacturers facing EFSA clean-label enforcement pressures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized clean-label formulators with membrane filtration capabilities over diversified packaged food conglomerates reliant on conventional skimming processes. Five-to-ten year viability hinges on ceramic microfiltration migration from dairy processing into poultry broth clarification achieving commercial scale. Watch for hospital system vendor list consolidation signals in California and Massachusetts as inflection indicators for institutional procurement pathway maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Scale-Up | Ceramic microfiltration migration from dairy enables precise lipid reduction without thermal protein degradation. |
| Dual-Certification Investment | Parallel USDA Organic and EU Organic Regulation compliance opens Medicare Advantage and European health-food channel access. |
| Subscription Platform Partnership | Health-focused meal-kit monthly tiers create recurring revenue streams beyond conventional retail promotional cycles. |
| Biodegradable Packaging Transition | Plant-based barrier films with modified atmosphere sealing satisfy EFSA clean-label enforcement while shedding aluminum laminates. |
| Senior Nutrition Program Integration | Medicare Advantage supplemental benefit expansions embed low-fat chicken soup as standardized institutional meal components. |
Research Methodology
A standing panel of R&D directors at legacy soup manufacturers, procurement managers at hospital systems, health-food channel buyers in Germany, and regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with formulation scientists and thermal processing engineers combined with secondary validation from FDA guidance documents, EFSA additive disclosure updates, USDA Organic certification databases, and Nielsen retail audit data. Bottom-up volume modeling across product type and ingredient type segments triangulated against top-down category spend estimates from institutional procurement databases.
Scenario-bracketing around regulatory enforcement timelines and membrane filtration adoption curves bounded the projection horizon. Segmentation dimensions modeled include preparation format, certification tier, distribution channel, and end-user health protocol. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and healthcare procurement trend analysis. Industry-specific forecast inputs incorporated Medicare Advantage supplemental benefit expansion trajectories and EFSA clean-label compliance cost curves.
Sensitivities concentrate around FDA sodium-reduction mandate implementation pacing and ceramic microfiltration equipment supply bottlenecks from the Netherlands-border industrial cluster. Forecasts reflect assumptions regarding antibiotic-free poultry supply concentration persistence and lipase enzyme feedstock cost stabilization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Europe Egg Powder Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Ready to Cook Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Fat Free Soup Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Spray Cheese Market
Processed Foods
Egg Powder Market
Processed Foods
Coffee Creamer Market
Processed Foods
Pates Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
Soup Market
Processed Foods
Global Malted Milk Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Egg White Cubes Market
Processed Foods
North America Ice Cream Market