
 Citrus Flavors Market | 2026-2036
Citrus Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Flavors Market Analysis
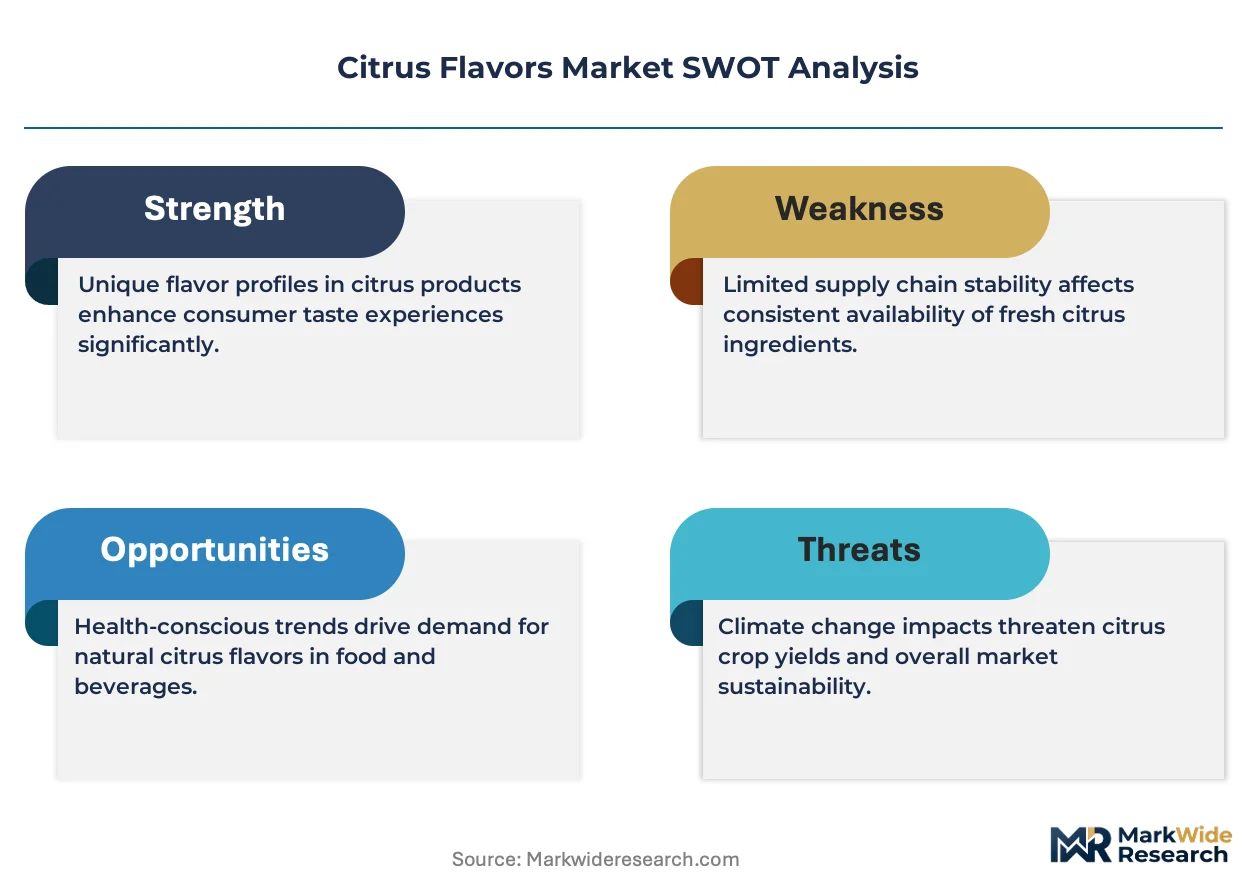
FSSC 22000 certification is redrawing competitive boundaries in the citrus flavors supply chain. Givaudan SA leverages captive botanical sourcing to sustain margin control across Mediterranean citrus belts. Kerry Group plc anchors its position through deep backward integration into cold-pressed oil extraction. Symrise AG differentiates via biotechnology-driven terpene recovery systems that reduce raw material waste.
Citrus flavors comprise volatile and non-volatile compounds—primarily limonene, citral, and linalool—extracted through cold-pressing, steam distillation, or solvent methods, then standardized for flavor intensity measured in fold concentration. These formulations deliver taste, aroma, and masking functions across food and beverage matrices. The concentrates category dominates value capture due to high potency and reduced logistics costs, while essences gain traction in premium beverage applications where top-note authenticity commands price premiums. Liquid form leads volume throughput in industrial batching, though powder form expands in confectionery and savory seasoning blends where moisture control determines shelf stability.
The FDA governs GRAS self-affirmation pathways for citrus-derived flavorants in the United States, while EFSA enforces purity specifications under EU flavoring regulation 1334/2008, and the FSSAI mandates additive labeling thresholds for India. These frameworks elevate compliance costs for synthetic-adjacent formulations while accelerating demand for extraction methods that meet natural-status definitions. Stakeholders must monitor evolving natural-flavor jurisprudence across jurisdictions to protect formulation investments and market access.
Market Dynamics
FSSC 22000 certification requirements are compressing supplier margins while concentrating procurement authority among certified extractors across Mediterranean citrus belts.
Growth Catalysts
- EU Green Deal compliance mandates:Beverage manufacturers accelerate natural flavor sourcing to meet carbon-neutral extraction standards, pulling demand toward cold-pressed oil suppliers.
- Clean-label portfolio expansion:Food producers eliminate synthetic terpenes from ingredient decks, creating volume pull for standardized citrus concentrates.
- Germany:Natural extraction clusters around Hamburg and Bavaria serve Central European food manufacturers with reduced logistics friction.
Market Restraints
- Raw material volatility:Citrus crop yields fluctuate with Mediterranean climate patterns, compressing extractor margins during poor harvest seasons.
- Supply concentration risk:Spain and Italy control over 60% of European cold-pressed oil output, creating geographic vulnerability for buyers.
- Regulatory friction:EFSA purity specifications under EU flavoring regulation 1334/2008 extend certification timelines for new market entrants.
Strategic Opportunities
- Biotechnology convergence:Terpene recovery systems combined with enzymatic extraction reduce waste while capturing high-value aroma compounds.
- India:FSSAI labeling thresholds for natural additives create first-mover advantage for extraction specialists establishing local production.
- Powder form expansion:Confectionery and savory seasoning manufacturers adopt spray-dried citrus formulations for moisture-controlled shelf stability.
Industry Challenges
- FSSC 22000 certification timelines:Small and mid-sized extractors face 12-18 month compliance windows, delaying market access.
- Cold-pressed oil extraction capex:Industrial-scale pressing equipment requires substantial capital deployment, favoring incumbent players with balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Flavors Market |
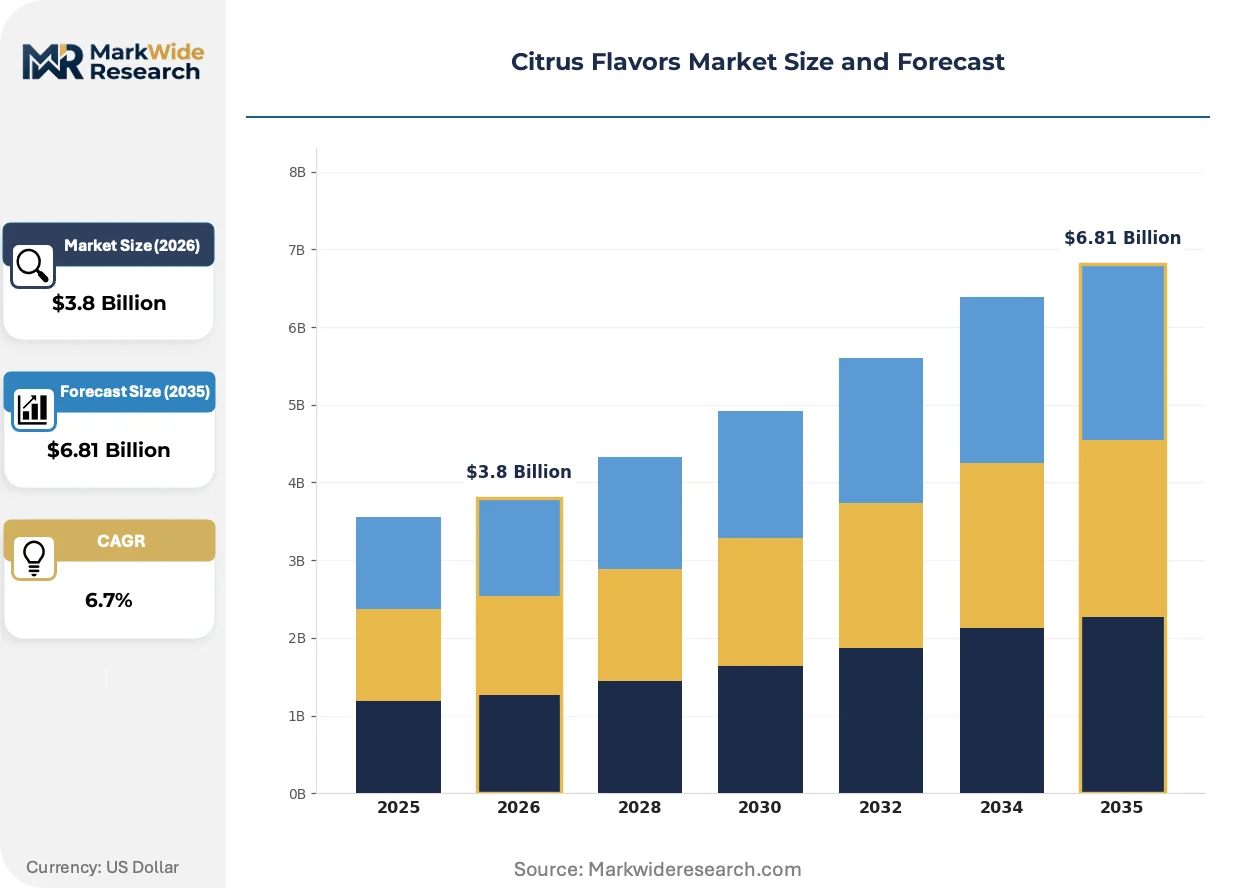
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Essences, Extracts, Zest Application: Beverages, Baked Goods, Confectionery, Dairy Products Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Beverage Producers, Snack Companies, Retailers |
| Companies Covered | Symrise AG, Kerry Group plc, Givaudan SA, Döhler GmbH, Sensient Technologies Corporation, International Flavors & Fragrances Inc., Takasago International Corporation, MANE & CIE, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Flavors Market Emerging Trajectories
Biotechnology-driven extraction methods are compressing traditional solvent-based processes while regulatory tightening accelerates natural-status verification protocols across supply chains.
Enzymatic terpene recovery systems extract higher yields from citrus peel waste streams. Premium beverage manufacturers adopt these methods fastest, seeking top-note authenticity for price-differentiated portfolios. This precision extraction is displacing conventional steam distillation in high-margin applications.
EU F-Gas Regulation tightens solvent recovery requirements for extraction facilities. Industrial operators must retrofit closed-loop systems or face operational restrictions. Cold-pressed oil producers in Spain and Italy face the steepest compliance costs, accelerating consolidation among smaller processors.
Buyer procurement patterns favor certified natural-status suppliers with documented chain-of-custody. Large beverage manufacturers consolidate supplier rosters, awarding multi-year contracts to FSSC 22000-certified extractors with captive botanical sourcing. This concentration is most visible in Germany, where clean-label mandates from retail chains cascade through formulation supply chains.
Citrus Flavors Market Segmentation
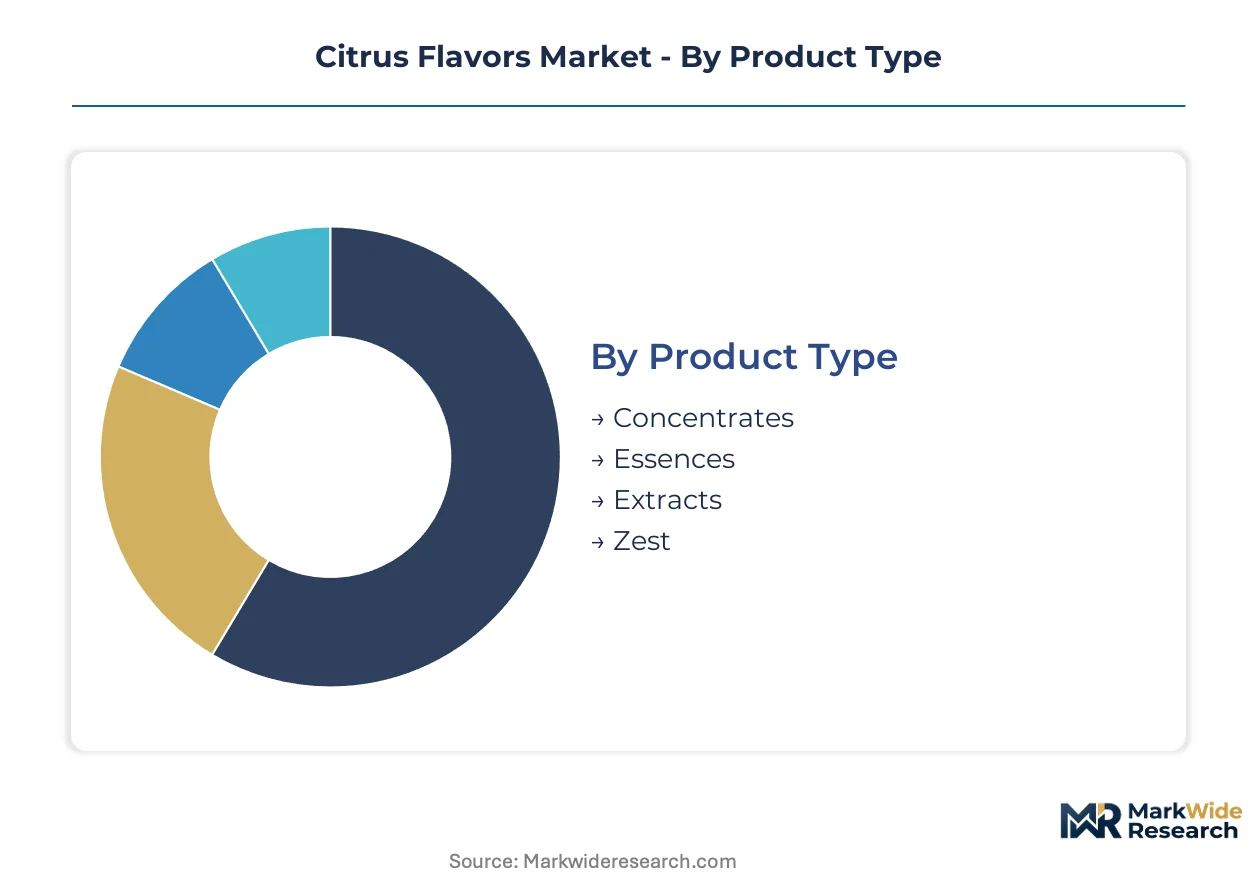
Citrus flavors segment across four dimensions that determine formulation economics and procurement strategy. Product type governs potency-to-cost ratios, while form selection locks in shelf-stability parameters for specific manufacturing environments.
Product Type:
Margin pools concentrate in high-fold concentrates where reduced logistics costs compound with premium pricing power.
- Concentrates:Standardized formulations delivering intensified flavor impact through reduced water content, typically measured in fold concentration. Beverage producers in Germany source these for carbon-neutral extraction compliance under EU Green Deal mandates, compressing supplier rosters toward FSSC 22000-certified extractors.
- Essences:Top-note aromatic fractions capturing volatile terpene profiles for premium authenticity. Sparkling water and craft beverage manufacturers adopt these fastest where price premiums justify cold-pressed oil sourcing from Mediterranean suppliers.
- Extracts:Solvent-based or cold-pressed full-spectrum preparations retaining broader compound matrices. These serve savory seasoning applications requiring deeper flavor persistence through thermal processing.
- Zest:Physical peel preparations delivering textural and aromatic dimension. Artisanal confectionery producers value these for visual differentiation and clean-label positioning.
The dominant share belongs to Concentrates, while Essences is closing the gap fastest.
Application:
Volume throughput varies sharply by processing temperature tolerance and pH stability requirements across food matrices.
- Beverages:Carbonated soft drinks, functional waters, and alcoholic mixers demanding rapid flavor release and photostability. Cold-pressed oil suppliers in Spain and Italy anchor supply for premium sparkling water brands seeking EU F-Gas Regulation compliance.
- Baked Goods:Heat-stable formulations resisting thermal degradation through oven cycles. Powder and granular forms penetrate here for moisture-controlled distribution through industrial bakeries.
- Confectionery:Hard candies, gummies, and chocolate coatings requiring precise oil-in-water or fat-compatible delivery systems. Spray-dried citrus powders expand fastest for shelf stability in tropical retail environments.
- Dairy Products:Yogurts, ice creams, and flavored milks demanding lipophilic compatibility and fermentation tolerance. Clean-label mandates from German retail chains cascade through formulation specifications here.
Beverages commands the largest volume position, though Confectionery is expanding most quickly on powder form adoption.
Form:
Customer infrastructure determines form selection—liquid dominates continuous processing lines while dry forms unlock geographic distribution advantages.
- Liquid:Industrial batching standard enabling precise metering through automated dosing systems. Beverage producers favor this for throughput efficiency in high-speed filling operations.
- Powder:Spray-dried or encapsulated formulations eliminating moisture migration risks. Confectionery and savory seasoning manufacturers adopt these for extended shelf stability in humidity-variable climates.
- Granular:Free-flowing particles for dry blending applications requiring rapid dispersion. Seasoning blend houses value these for uniform distribution without clumping.
- Paste:High-viscosity preparations for artisanal and small-batch applications. Premium bakery producers source these for controlled flavor release in laminated doughs.
Liquid maintains volume leadership, yet Powder is gaining share fastest on confectionery demand.
End User:
Procurement authority concentrates among large-scale manufacturers with certified supplier rosters and multi-year contract structures.
- Food Manufacturers:Industrial bakeries, sauce producers, and prepared meal facilities requiring standardized batch consistency. These buyers consolidate toward FSSC 22000-certified extractors with documented chain-of-custody.
- Beverage Producers:Multinational soft drink and bottled water companies driving clean-label portfolio expansion. EU Green Deal compliance mandates pull their sourcing toward cold-pressed oil specialists.
- Snack Companies:Savory snack and cereal manufacturers applying citrus for flavor novelty and sodium reduction masking. Powder form penetration is highest here for coating uniformity.
- Retailers:Private-label brand owners specifying ingredient decks for contract manufacturers. German retail chains enforce additive transparency thresholds that cascade through supplier tiers.
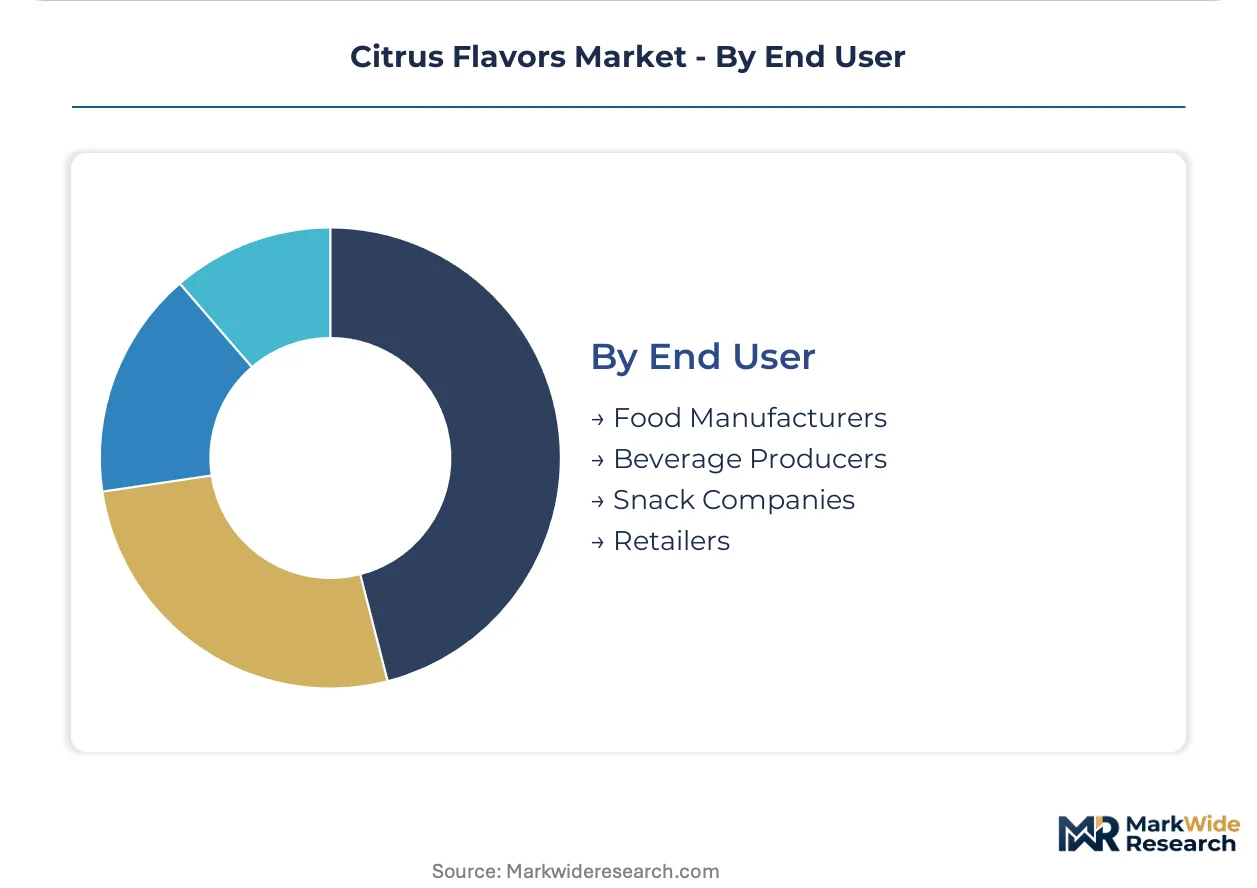
Food Manufacturers hold the dominant procurement position, while Beverage Producers are climbing the fastest on carbon-neutral sourcing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are redirecting extraction investment toward jurisdictions with established cold-pressed oil infrastructure and documented chain-of-custody capabilities. Germany, Spain, Italy, the United States, and India concentrate the highest procurement authority for certified natural citrus formulations.
Germany
Beverage manufacturers in Hamburg and Bavaria drive carbon-neutral sourcing mandates that cascade through Central European supply chains. EFSA enforces purity specifications under EU flavoring regulation 1334/2008, compressing certification timelines for new market entrants. Natural extraction clusters around Hamburg serve industrial food manufacturers with reduced logistics friction and FSSC 22000-certified supply bases.
Spain
Cold-pressed oil producers in Valencia and Andalusia anchor Mediterranean citrus supply for premium beverage applications. The EU F-Gas Regulation tightens solvent recovery requirements, forcing retrofit investments in closed-loop extraction systems. Industrial-scale pressing facilities in Murcia concentrate output for German and French buyers seeking EU Green Deal compliance documentation.
Italy
Artisanal and industrial extractors in Sicily and Calabria supply high-fold concentrates for confectionery and savory seasoning manufacturers. EFSA natural-status definitions under regulation 1334/2008 elevate compliance costs for synthetic-adjacent formulations. Processing clusters around Reggio Calabria maintain captive botanical sourcing relationships that sustain margin control through volatile harvest cycles.
United States
Beverage producers in California and Florida expand clean-label portfolios, eliminating synthetic terpenes from ingredient decks. The FDA governs GRAS self-affirmation pathways for citrus-derived flavorants, creating faster market access than EU certification routes. Extraction specialists in the San Joaquin Valley serve West Coast food manufacturers with cold-pressed oil standardized for fold concentration metrics.
India
Nagpur and Andhra Pradesh processing hubs supply spray-dried citrus powders for tropical confectionery markets requiring moisture-controlled shelf stability. FSSAI mandates additive labeling thresholds for natural additives, creating first-mover advantage for extraction specialists establishing local production. Domestic beverage manufacturers in Maharashtra accelerate procurement of certified natural concentrates to meet retail chain transparency requirements.
Citrus Flavors Market Vendor Landscape
Player mix skews toward integrated flavor houses with captive botanical sourcing and biotechnology-driven extraction capabilities. The supplier base concentrates among FSSC 22000-certified extractors with documented chain-of-custody systems, compressing margins for uncertified processors. Three archetypes dominate: Mediterranean cold-pressed oil specialists with backward integration into citrus groves, biotechnology-driven terpene recovery innovators, and diversified ingredient houses leveraging multi-category procurement scale. Competitive dynamics center on certification acquisition speed and multi-year contract consolidation with large beverage manufacturers.
Within the integrated flavor house tier, Givaudan SA, Kerry Group plc, and Symrise AG exemplify divergent strategic positions. Givaudan SA represents Mediterranean sourcing concentration with captive control over botanical supply chains. Kerry Group plc anchors its position through deep backward integration into cold-pressed oil extraction infrastructure. Symrise AG occupies the biotechnology-driven vector, with enzymatic terpene recovery systems that reduce raw material waste while capturing high-value aroma compounds for premium applications.
| Leading Market Players |
|---|
| Symrise AG |
| Kerry Group plc |
| Givaudan SA |
| Döhler GmbH |
| Sensient Technologies Corporation |
| International Flavors & Fragrances Inc. |
| Takasago International Corporation |
| MANE & CIE |
| Firmenich SA |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for cold-pressed citrus oils concentrate pricing power among FSSC 22000-certified extractors in Spain and Italy, while uncertified processors absorb margin compression from EU F-Gas Regulation compliance costs. This lead-time band locks buyer procurement to Mediterranean supply clusters, elevating certification premiums as the primary price stratification mechanism across beverage manufacturer contracts.
Pricing Analysis
Certification level under FSSC 22000 and EFSA regulation 1334/2008 creates the primary spread between premium cold-pressed oil suppliers and standard-grade solvent extractors. Three-tier pricing structure separates FSSC-certified natural-status suppliers from conventional extractors and uncertified commodity processors. Pricing pressure stems from EU Green Deal carbon-neutral mandates compressing margins for non-compliant facilities. Beverage producers show least price sensitivity due to clean-label portfolio premiums, while snack companies and retail private-label buyers drive hardest volume negotiations.
Supply Chain Analysis
Container availability on Valencia-Hamburg and Genoa-Rotterdam trade lanes governs inbound logistics costs for Central European food manufacturers sourcing Mediterranean citrus oils. Supply concentrates in Spain, Italy, and Greece for cold-pressed oil extraction, with India emerging for spray-dried powder production. The chain draws from citrus peel waste streams, specialized pressing equipment, and enzymatic recovery systems as critical inputs. Single-source vulnerability runs through Andalusian and Sicilian processing clusters exposed to climate-driven harvest volatility. Distribution runs through certified extractor direct contracts to large beverage manufacturers, bypassing traditional flavor distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Citrus flavors sit in early-cycle expansion as biotechnology-driven terpene recovery displaces conventional solvent extraction, with enzymatic methods capturing premium beverage demand faster than forecasted penetration curves suggested.
For Market Incumbents: Shield margin pools by accelerating FSSC 22000 certification across captive Mediterranean groves before regulatory tightening closes compliance windows. Consolidate procurement authority through multi-year contracts with German beverage manufacturers facing EU Green Deal deadlines. Biotechnology patent positions in enzymatic extraction represent the critical defensive lever against terpene recovery specialists eroding traditional cold-pressed oil premiums. For New Entrants and Emerging Players: Lead with powder form spray-drying capabilities targeting Indian confectionery markets where FSSAI labeling thresholds create first-mover certification advantages. White-space concentrates in moisture-controlled shelf stability formulations for tropical retail environments, with enzymatic terpene recovery from citrus peel waste offering the most penetrable technology angle against incumbent solvent infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because natural-status definitions under EFSA and FDA jurisdictions will continue tightening, concentrating value in certified extraction assets with documented chain-of-custody. Acquisition targets should cluster around FSSC 22000-certified mid-cap processors with captive botanical relationships in Spain or Italy. The signal to watch is EU F-Gas Regulation enforcement acceleration forcing smaller processors into distressed sale positions.| Strategic Initiative | Industry Significance |
|---|---|
| FSSC 22000 Certification Acceleration | Locks market access for extractors serving German beverage manufacturers under EU Green Deal mandates. |
| Enzymatic Terpene Recovery Deployment | Captures high-value aroma compounds from peel waste while reducing raw material intensity for premium applications. |
| Backward Integration into Citrus Groves | Sustains margin control through volatile harvest cycles by securing captive botanical supply in Mediterranean belts. |
| Spray-Dried Powder Capacity Expansion | Unlocks confectionery and savory seasoning demand in humidity-variable climates requiring moisture-controlled shelf stability. |
| India Local Production Establishment | Creates first-mover advantage under FSSAI labeling thresholds for natural additives in domestic beverage markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA regulatory filings, EU trade customs data, and FSSC 22000 certification registries. Interviews with extraction facility managers, beverage procurement leads at German manufacturers, and flavor house R&D directors informed supply-side and demand-side validation. Secondary sources included EFSA flavoring regulation 1334/2008 implementation reports, EU F-Gas Regulation compliance disclosures, and botanical sourcing documentation from Mediterranean processing clusters. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and form dimensions.
Segmentation dimensions modeled include product type hierarchy (concentrates, essences, extracts, zest), application matrix (beverages, baked goods, confectionery, dairy), form factor (liquid, powder, granular, paste), and end-user procurement structure. CAGRs derived from regression analysis of historical extraction capacity expansion, regulatory compliance cost trajectories, and clean-label adoption curves across beverage portfolios. Industry-specific forecast inputs incorporated citrus crop yield volatility indices and EU Green Deal carbon-neutral extraction investment schedules.
The analysis sits within stated boundaries; outcomes outside EFSA regulatory stability, Mediterranean climate patterns, or biotechnology cost reduction curves would require recalibration. Forecasts reflect documented assumptions on certification adoption rates and cold-pressed oil capacity expansion timelines. Harvest volatility, regulatory enforcement acceleration, or substitute flavor technology breakthroughs could materially revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Natural and Organic Flavors Market