
 Broth Market | 2026-2036
Broth Market Size, Share, and Industry Trends Forecast 2026-2036
Broth Market Analysis
Premium organic certification is redrawing competitive boundaries in the broth category. Campbell Soup Company leverages its refrigerated supply chain to sustain distribution advantages in fresh broth segments. Pacific Foods of Oregon anchors the West Coast natural-foods channel with clean-label positioning. Knorr competes on concentrated and dehydrated formats that dominate food-service procurement across Europe and North America.
Broth is a liquid food preparation produced by simmering animal bones, meat, vegetables, or seafood in water, typically containing 1-3% protein by weight and achieving clarity through controlled extraction temperatures below 100°C; it serves as a foundational ingredient for soups, sauces, gravies, and braising liquids in both household and commercial kitchens. Chicken broth occupies the largest volume share due to its neutral flavor profile and cross-cultural recipe compatibility, while vegetable broth represents the fastest-expanding segment as plant-based dietary patterns gain permanence. Pouch packaging is displacing rigid formats in online retail channels where shipping-weight reduction directly improves margin economics.
USDA organic standards and FDA food-labeling rules govern ingredient declarations and nutrient-content claims in the American market, while the EU Green Deal's packaging-waste directives are accelerating carton-format investments across European manufacturing footprints. Stakeholders must monitor evolving front-of-pack labeling requirements in multiple jurisdictions, as regulatory divergence between FDA and EFSA approaches to sodium-content warnings threatens to fragment formulation strategies and complicate pan-regional product portfolios.
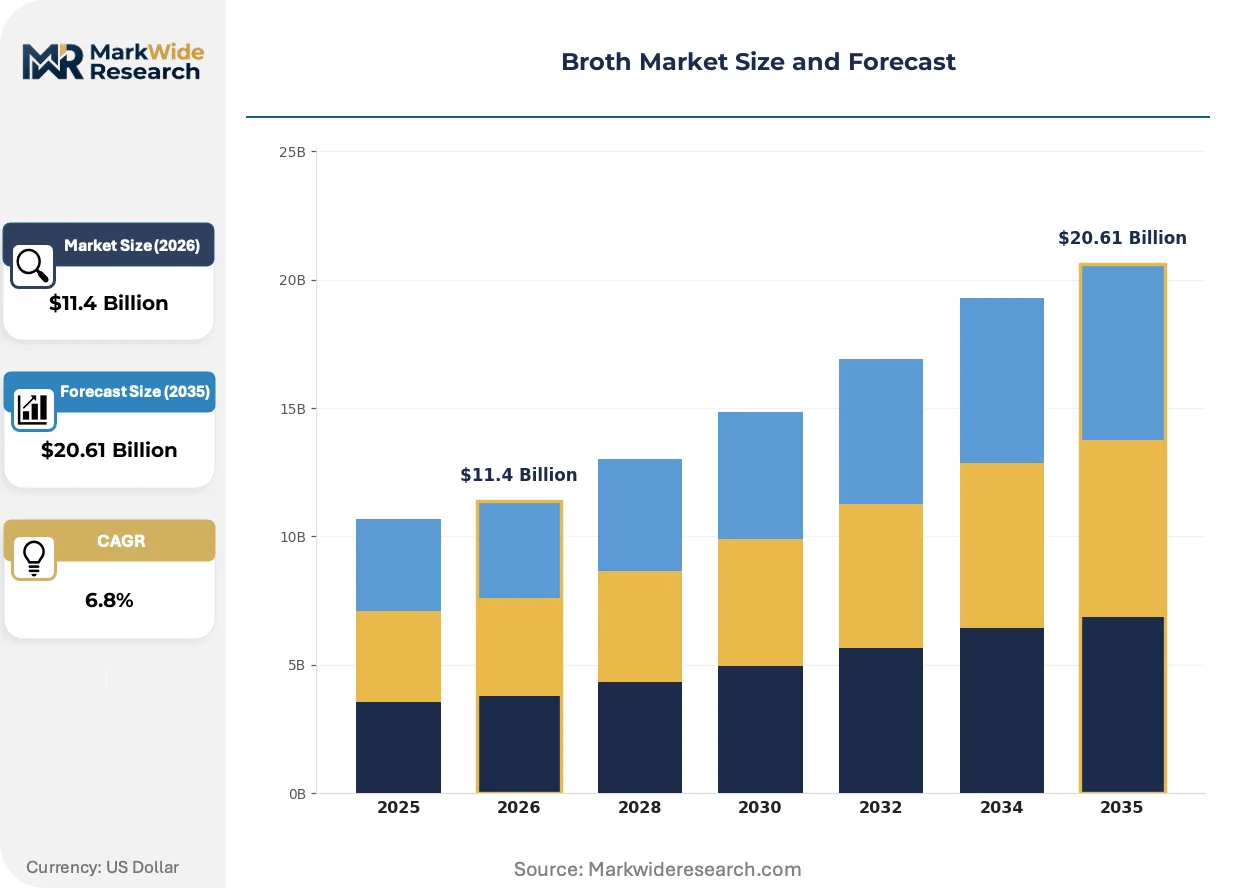
Market Dynamics
Clean-label certification requirements and EU Green Deal packaging mandates are compressing margins for conventional producers while rewarding early movers in organic and sustainable formats. The structural pivot toward refrigerated fresh segments is redrawing capital allocation across manufacturing footprints.
Growth Catalysts
- EU Green Deal packaging directives:Recyclable carton mandates are accelerating format innovation among European processors. Manufacturers investing in aseptic carton lines capture preferential retail placement.
- Functional food positioning:Collagen-rich bone broth variants command shelf-space premiums in US natural-foods channels. Health-conscious households are substituting broth for traditional meal bases.
- Plant-based dietary permanence:Vegetable broth formulations are capturing flexitarian households across Germany and the United Kingdom. Clean-label vegetable stocks now anchor premium private-label ranges.
Market Restraints
- Bone supply concentration:Rendering facility consolidation in the US Midwest creates input volatility for bone broth specialists. Single-source dependencies expose margin compression during cattle cycle downturns.
- Organic certification cost structure:USDA organic compliance requires three-year transition timelines for conventional livestock operations. Small-scale processors face working capital constraints during certification gaps.
- Refrigerated logistics limitations:Cold-chain infrastructure gaps in secondary US markets restrict fresh broth distribution. Shelf-stable formats retain advantage in food-service procurement.
Strategic Opportunities
- Direct-to-consumer subscription channels:Bone broth delivery services are capturing repeat-purchase households in California and New York. Recurring revenue models reduce slotting-fee dependence.
- Convergence of collagen extraction and broth production:Integrated processing lines yield co-products for nutraceutical markets. Dual-output facilities improve asset utilization rates.
- Sodium-content front-of-pack labeling:FDA guidance on voluntary sodium warnings creates formulation differentiation for reduced-sodium variants. Early adopters secure preferential placement in wellness-oriented retail banners.
Industry Challenges
- Clean-label formulation expertise:Natural preservation without artificial additives demands specialized food-science capabilities. Talent scarcity in natural-foods R&D constrains product pipeline velocity.
- Legacy equipment retooling:Aseptic carton lines require eight-figure capital commitments. Mid-tier processors face financing gaps for format transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broth Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken Broth, Beef Broth, Vegetable Broth, Fish Broth Packaging Type: Carton, Jar, Canned, Pouch Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Food Service End User: Households, Restaurants, Hospitals, Catering Services |
| Companies Covered | Pacific Foods of Oregon, Del Monte, Campbell Soup Company, Progresso, Swanson, Knorr, Manischewitz, Better Than Bouillon, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broth Market Emerging Trajectories
Pouch packaging formats and precision extraction technologies are compressing traditional manufacturing economics. Sustainability certifications and direct-channel proliferation are rewriting competitive rules.
Aseptic pouch packaging is supplanting rigid glass and metal formats in e-commerce channels. Direct-to-consumer brands in the United States and Germany are adopting flat-bottom pouches for shipping-weight reduction. This format shift is enabling margin recovery in subscription-based business models previously constrained by dimensional-weight pricing.
The EU Green Deal's packaging-waste directives are mandating recyclable mono-material structures by 2030. European manufacturers are accelerating carton-format investments and phasing out multi-layer laminates. Fresh broth segments in France and the Netherlands face compressed timelines for line conversions.
Health-conscious households are rotating toward collagen-forward functional positioning. Premium bone broth is displacing conventional soup bases in wellness-oriented retail banners across California and Texas. This consumption-pattern shift concentrates volume in natural-foods channels with higher margin structures.
Broth Market Segmentation
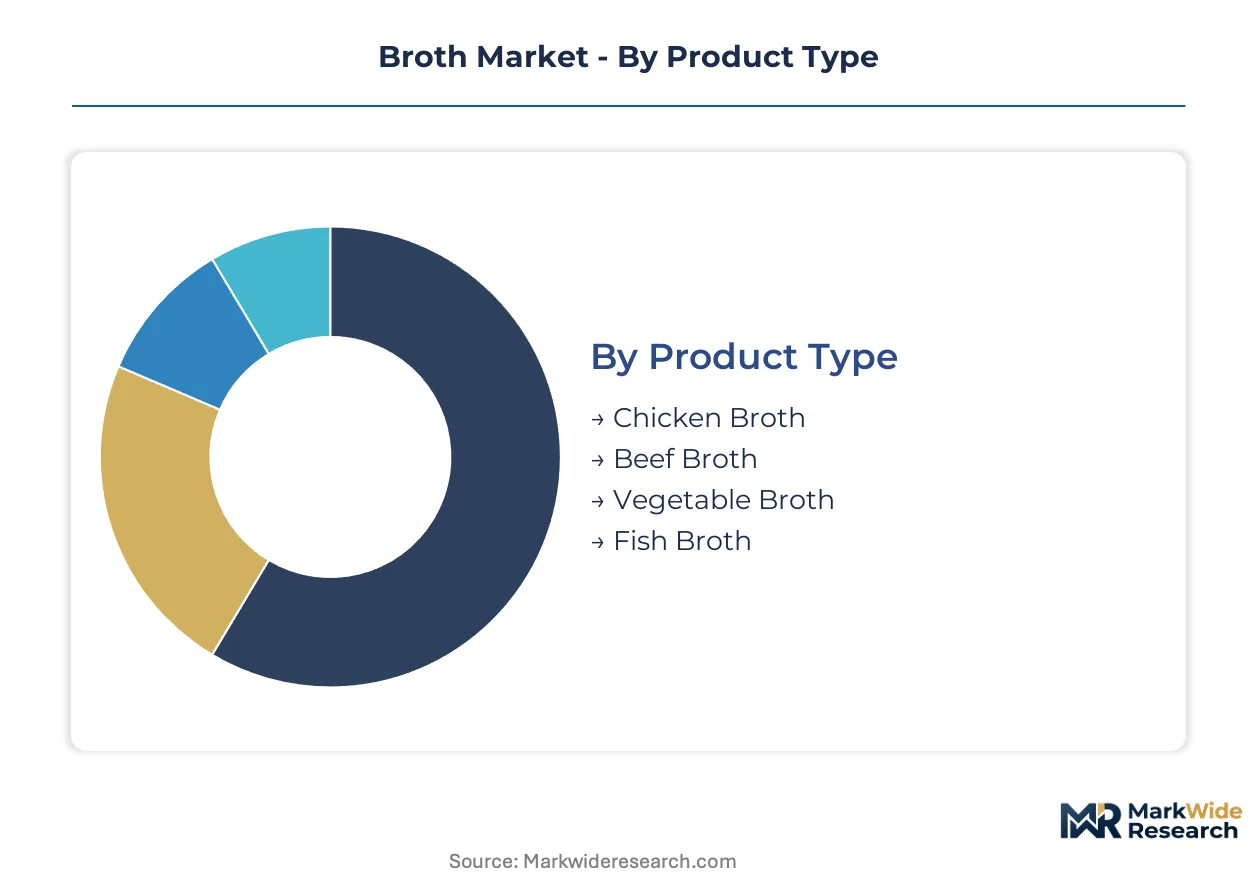
Broth segmentation reflects divergent regulatory pressures across product formats and distribution channels. USDA organic standards and EU Green Deal packaging mandates create distinct compliance burdens that reshape competitive positioning within each category.
Product Type:
FDA and USDA labeling requirements impose stricter nutrient-content thresholds on animal-derived broths than vegetable formulations, creating formulation complexity for multi-product portfolios.
- Chicken Broth:Neutral flavor profile with 1-3% protein content enables cross-cultural recipe compatibility. Demand concentrates in United States households where collagen-forward functional positioning commands shelf-space premiums in natural-foods channels.
- Vegetable Broth:Plant-based formulation achieves clarity through controlled extraction below 100°C without animal inputs. Flexitarian households across Germany and United Kingdom are adopting these variants fastest as clean-label stocks anchor premium private-label ranges.
- Beef Broth:Richer mouthfeel from higher gelatin content serves braising and sauce applications in commercial kitchens.
- Fish Broth:Coastal Mediterranean and Japanese culinary traditions sustain niche procurement volumes through specialty retail channels.
Established volume favors chicken broth; emerging adoption favors vegetable broth.
Packaging Type:
Cost tier differentiation separates premium aseptic formats from economy metal cans, with mid-tier cartons capturing mainstream retail placement.
- Carton:Aseptic carton lines require eight-figure capital commitments but deliver shipping-weight advantages and EU Green Deal compliance. European manufacturers investing in recyclable mono-material structures capture preferential retail placement ahead of 2030 mandates.
- Pouch:Flat-bottom flexible formats reduce dimensional-weight pricing penalties in direct-to-consumer channels. United States and German subscription brands recover margins previously eroded by e-commerce shipping economics.
- Canned:Metal formats retain dominance in food-service procurement where shelf stability outweighs sustainability premiums.
- Jar:Glass containers sustain premium positioning in specialty retail but face displacement from lighter alternatives.
Legacy volume concentrates in canned formats; steepest expansion trajectory belongs to pouch configurations.
Distribution Channel:
Customer type fragmentation splits procurement between price-sensitive institutional buyers and wellness-oriented household purchasers.
- Supermarkets:Refrigerated fresh segments command slotting fees but deliver higher turns in natural-foods banners. Cold-chain infrastructure gaps in secondary United States markets constrain penetration depth.
- Online Retailers:Subscription models reduce slotting-fee dependence while capturing repeat-purchase households in California and New York. Shipping-weight reduction through pouch formats directly improves margin economics.
- Specialty Stores:Premium bone broth variants achieve placement premiums in wellness-oriented retail banners across Texas.
- Food Service:Concentrated and dehydrated formats dominate procurement where shelf-stable logistics outweigh freshness positioning.
Volume gravity centers on supermarkets; fastest share gains occur in online retailers.
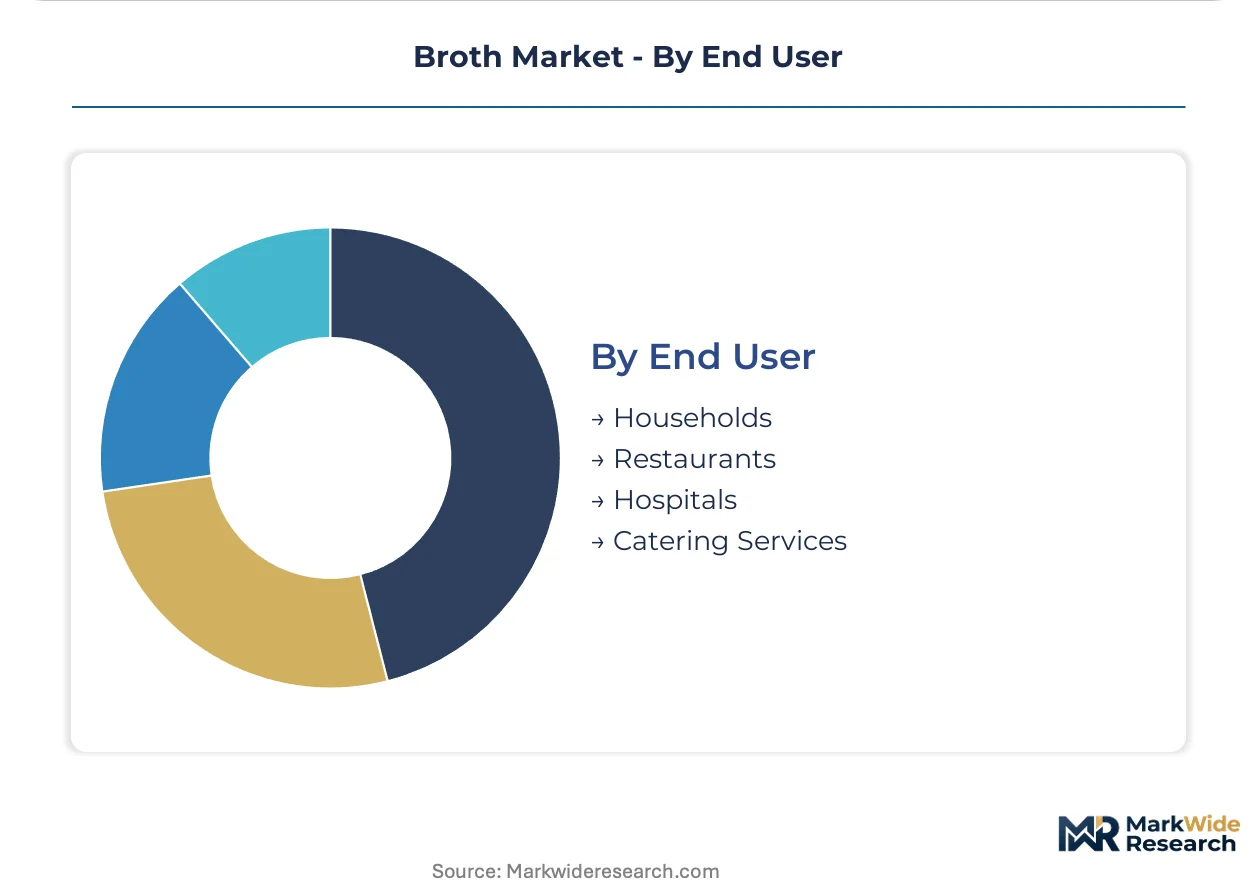
End User:
Application requirements dictate formulation specifications ranging from clean-label household consumption to sodium-controlled institutional nutrition.
- Households:Health-conscious consumers substitute collagen-rich bone broth for traditional meal bases. FDA guidance on voluntary sodium warnings creates formulation differentiation opportunities for reduced-sodium variants in wellness-oriented retail.
- Restaurants:Cross-utilization demands drive procurement of neutral-flavor chicken broth as foundational ingredient for soups, sauces, and braising liquids.
- Hospitals:Therapeutic nutrition protocols require precise sodium and protein content documentation under FDA food-labeling rules.
- Catering Services:Volume-scale operations prioritize shelf-stable formats where refrigerated logistics constraints limit fresh broth distribution.
Procurement scale favors restaurants; regulatory complexity concentrates in hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics vary sharply across major broth-consuming markets, with net importers in Northern Europe sourcing from concentrated production clusters in the United States and Brazil while Asian markets develop self-sufficient regional supply bases.
United States
Premium bone broth demand from health-conscious households in California and Texas drives category expansion. FDA food-labeling rules and USDA organic standards govern ingredient declarations and nutrient-content claims. The refrigerated supply chain infrastructure concentrated in the Midwest and Northeast supports fresh broth distribution to natural-foods banners.
Germany
Flexitarian households across Bavaria and North Rhine-Westphalia are adopting vegetable broth variants as clean-label stocks anchor premium private-label ranges. The EU Green Deal's packaging-waste directives mandate recyclable mono-material structures by 2030. Manufacturing investments in aseptic carton lines cluster around Hamburg and the Ruhr industrial region.
United Kingdom
Wellness-oriented retail banners in London and the Southeast concentrate demand for collagen-forward functional positioning. EFSA approaches to sodium-content warnings diverge from FDA guidance, complicating pan-regional formulation strategies. Direct-to-consumer subscription brands in Greater Manchester exploit pouch packaging for shipping-weight reduction.
France
Traditional culinary applications sustain demand for fish broth in coastal Mediterranean regions while Parisian households shift toward organic chicken variants. ANSM labeling requirements intersect with EU Green Deal mandates on sustainable packaging. Fresh broth segments in Île-de-France face compressed timelines for aseptic carton line conversions.
Japan
Dashi-derived broth traditions in Kanto and Kansai regions create distinct formulation specifications separate from Western animal-based stocks. METI standards on food processing and JIS packaging regulations shape manufacturing compliance. Precision extraction technology adoption concentrates in Nagoya-area processing facilities serving both domestic and export markets.
Broth Market Vendor Landscape
Listed leaders compete with private specialists across format innovation and channel access, creating a tiered structure where scale advantages in shelf-stable segments contrast with agility in fresh and direct-to-consumer channels. Three archetypes dominate: diversified food conglomerates with refrigerated supply chain assets, natural-foods specialists with clean-label certification expertise, and dehydrated format specialists serving food-service procurement. Competitive moves center on aseptic packaging line investments and direct-channel subscription model development.
Within the diversified conglomerate tier, Campbell Soup Company and General Mills occupy positions anchored by legacy retail distribution infrastructure, while Pacific Foods of Oregon exemplifies the natural-foods specialist archetype with West Coast channel concentration. Knorr represents the format-specialist position in concentrated and dehydrated segments.
| Leading Market Players |
|---|
| Pacific Foods of Oregon |
| Del Monte |
| Campbell Soup Company |
| Progresso |
| Swanson |
| Knorr |
| Manischewitz |
| Better Than Bouillon |
| General Mills |
| Others |
Supply Flow & Price Mechanics
USDA organic certification gates both supply qualification and price differentiation simultaneously, forcing three-year transition timelines that compress working capital for conventional livestock operations while rewarding certified producers with shelf-space premiums in natural-foods channels.
Pricing Analysis
Food-service procurement anchors a three-tier pricing structure across premium, standard, and economy levels in the broth market. Price differentiation hinges on certification grade and volume scale, with organic-certified variants commanding placement premiums while dehydrated formats compete on per-unit economy. Cost compression in shelf-stable tiers is intensifying because rendering facility consolidation in the US Midwest exposes single-source dependencies. Quick-service restaurants exhibit highest price sensitivity, whereas wellness-oriented retail banners absorb premiums for collagen-forward functional positioning.
Supply Chain Analysis
Strategic stockpiling of frozen bone inputs predominates over just-in-time freshness models due to cattle cycle volatility and rendering facility scheduling constraints. Supply concentrates in the United States, Brazil, and Germany, with raw material dependencies on cattle byproducts, vegetable crop rotations, and aseptic packaging substrates. Tariff exposure on aluminum can imports from China creates margin pressure for metal-format producers. Distribution runs through refrigerated trucking networks for fresh segments and ambient warehousing for shelf-stable formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates constitute a technological-regulatory inflection that will bifurcate the broth market between compliant carton producers and stranded legacy assets.
For Market Incumbents: Compound refrigerated supply chain advantages by extending distribution depth into secondary US markets where cold-chain infrastructure gaps currently constrain fresh broth penetration. Prioritize aseptic carton line investments ahead of 2030 EU mandates to capture preferential retail placement and defend against private-label displacement in European natural-foods channels. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels where recurring revenue models reduce slotting-fee dependence and shipping-weight reduction through pouch formats recovers margin economics previously eroded by dimensional-weight pricing. Target flexitarian households in Germany and the United Kingdom with clean-label vegetable broth variants that anchor premium private-label ranges. For Investors and Strategic Acquirers: EU Green Deal packaging mandates reshape the acquisition landscape by penalizing multi-layer laminate capabilities while rewarding mono-material carton expertise. Long-term viability favors targets with integrated collagen extraction and broth production lines that yield nutraceutical co-products. Monitor FDA guidance progression on voluntary sodium warnings as the inflection indicator for reduced-sodium variant valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Carton Line Investment | EU Green Deal compliance secures preferential retail placement ahead of 2030 mandates. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models reduce slotting-fee dependence in California and New York. |
| Collagen Extraction Integration | Dual-output facilities improve asset utilization rates for nutraceutical co-products. |
| Reduced-Sodium Formulation Development | FDA guidance on voluntary sodium warnings creates differentiation in wellness retail. |
| Vegetable Broth Premium Tier Introduction | Clean-label stocks anchor private-label ranges for flexitarian households in Germany. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at retailers, channel sales heads, and supply planners anchored the qualitative base. Primary fieldwork combined with secondary validation from Nielsen retail audit data, customs records, SEC 10-K filings, and USDA organic certification databases. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Sensitivity analysis tested forecast robustness across the projection horizon. The analytical framework modeled segmentation dimensions including product type, packaging format, distribution channel, and end-user application. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessments. Industry-specific inputs incorporated cattle cycle patterns and EU packaging-waste directive compliance timelines.
Material uncertainties — regulatory divergence between FDA and EFSA sodium-warning approaches, rendering facility consolidation disruptions, and cold-chain infrastructure expansion rates — sit outside the modeled envelope. Forecasts reflect documented assumptions on consumer substitution patterns and certification adoption curves. Revision becomes warranted when EU Green Deal implementation timelines or organic livestock transition rates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Egg White Cubes Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Processed Vegetable Market
Processed Foods
Porridge Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Processed Potatoes Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
United States Ice Cream Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Pates Market
Processed Foods
Tomato Puree Market
Processed Foods
Processed Meat Market